
 China Sports Optic Market | 2026-2036
China Sports Optic Market Size, Share, and Industry Trends Forecast 2026-2036
China Sports Optic Market Insights
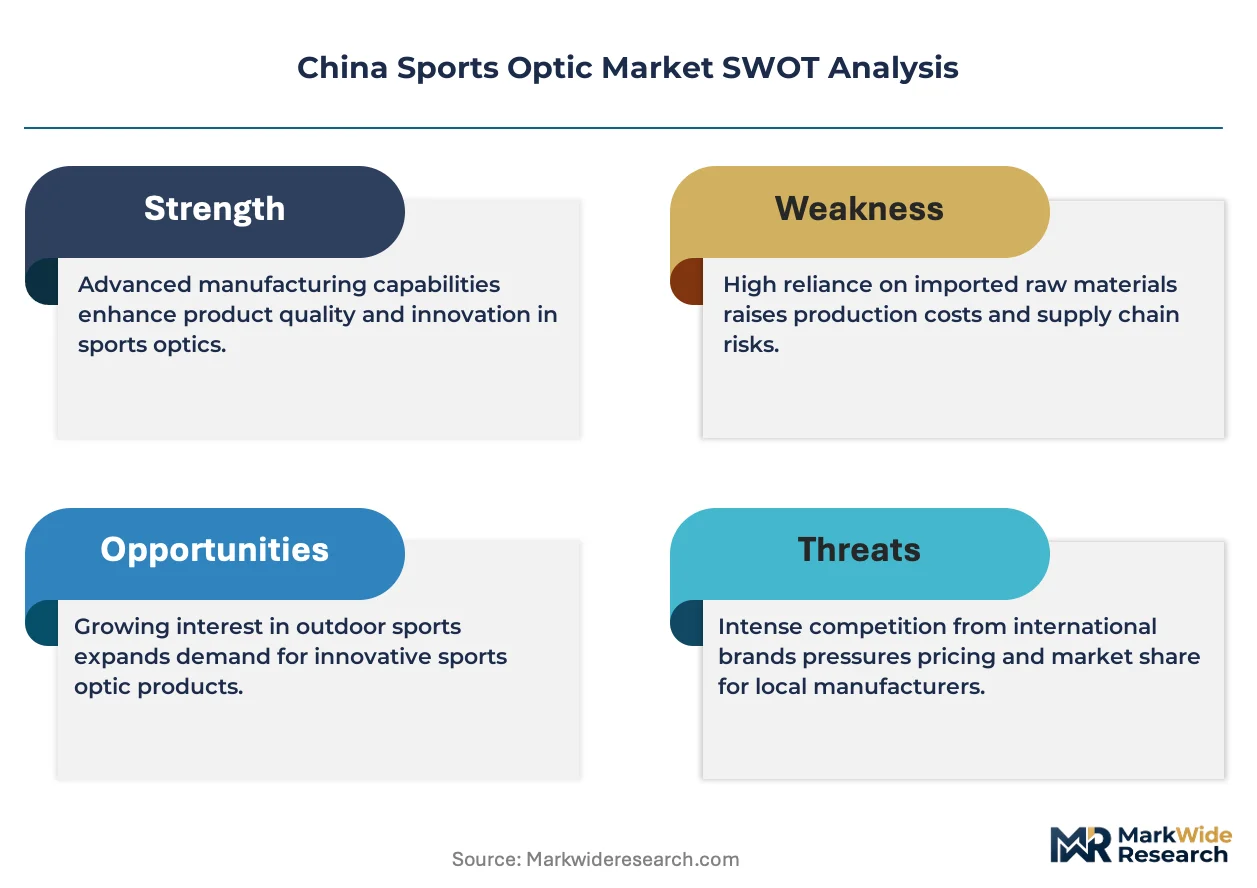
Digital imaging integration with traditional glass optics is narrowing the performance gap between consumer and professional-grade sports optics. Nikon Corporation leverages its precision glass heritage to sustain premium positioning in rangefinder segments. Guide Infrared Co., Ltd. anchors domestic supply chains through captive manufacturing of thermal imaging cores. Vector Optics competes aggressively on price-performance ratios in the spotting scope category.
Sports optics encompass precision-engineered visual instruments combining coated lens assemblies, prism systems, and electronic sensors to magnify distant targets for recreational and competitive activities. Manufacturing relies on ED (extra-low dispersion) glass grinding, nitrogen purging for waterproofing, and multi-layer dielectric coatings achieving light transmission rates above 90%. Binoculars occupy the largest volume position due to universal accessibility across customer tiers. Night vision technology captures the fastest expansion trajectory as thermal sensor costs decline and hunting regulations liberalize in select provinces. Digital imaging functionality concentrates margin pools among professional athletes requiring real-time capture and telemetry integration.
GB standards administered by SAMR establish optical performance benchmarks and environmental durability requirements for domestic sales. The MIIT's dual carbon goals are forcing energy-efficient retooling across lens polishing facilities. NMPA oversight extends to medical-adjacent applications where sports optics interface with diagnostic devices. Stakeholders must monitor regulatory alignment between provincial hunting permit systems and optic certification requirements as enforcement harmonization proceeds.
Market Dynamics
Domestic optical component standardization under MIIT is compressing import dependency while forcing coastal manufacturers to retool for GB compliance. This regulatory momentum is redistributing capability across the Yangtze River Delta and Pearl River Delta clusters.
Growth Catalysts
- Wildlife observation demand:Provincial nature reserve expansions in Sichuan and Yunnan are driving spotting scope adoption among domestic outdoor enthusiasts. Ranger station procurement cycles are shortening.
- GB standards harmonization:SAMR-administered optical performance benchmarks are creating certification clarity that accelerates retail channel stocking decisions. Standardized testing protocols reduce buyer uncertainty.
- Thermal sensor cost curves:Declining uncooled microbolometer prices are democratizing night vision capability for hunting permit holders in select provinces. Sensor integration is shifting from military to consumer supply chains.
Market Restraints
- ED glass import concentration:High-dispersion optical glass remains concentrated among Japanese and German suppliers, exposing margins to yen-euro volatility and ocean freight scheduling.
- Dual carbon retooling costs:MIIT energy-efficiency mandates for lens polishing facilities require capital-intensive vacuum coating upgrades that strain mid-tier manufacturers.
- Provincial hunting permit fragmentation:Non-harmonized wildlife management regulations across provinces create certification complexity that slows thermal optic distribution scaling.
Strategic Opportunities
- Telemetry-integrated digital capture:Professional athletes and competitive shooters are demanding real-time ballistics calculation overlays. This convergence of glass optics with edge computing creates premium tier expansion.
- Central and Western China penetration:Underdeveloped retail infrastructure in Hubei, Hunan, and Shaanxi presents first-mover advantage for direct-to-consumer thermal optic brands.
- NMPA medical-adjacent crossover:Sports optics interfacing with diagnostic devices face lighter regulatory pathways than pure medical devices, opening rehabilitation and sports medicine channels.
Industry Challenges
- Precision grinding talent scarcity:Master optician apprenticeship pipelines have collapsed in Guangdong and Jiangsu, forcing manufacturers to automate slower than planned.
- Multi-layer dielectric coating IP:Foreign-held patent thickets around 90%+ light transmission coatings are forcing domestic firms into costly licensing or inferior performance positioning.
- Nitrogen purging integration:Waterproofing assembly lines require cleanroom investments that conflict with existing factory footprints in legacy precision instrument zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sports Optic Market |
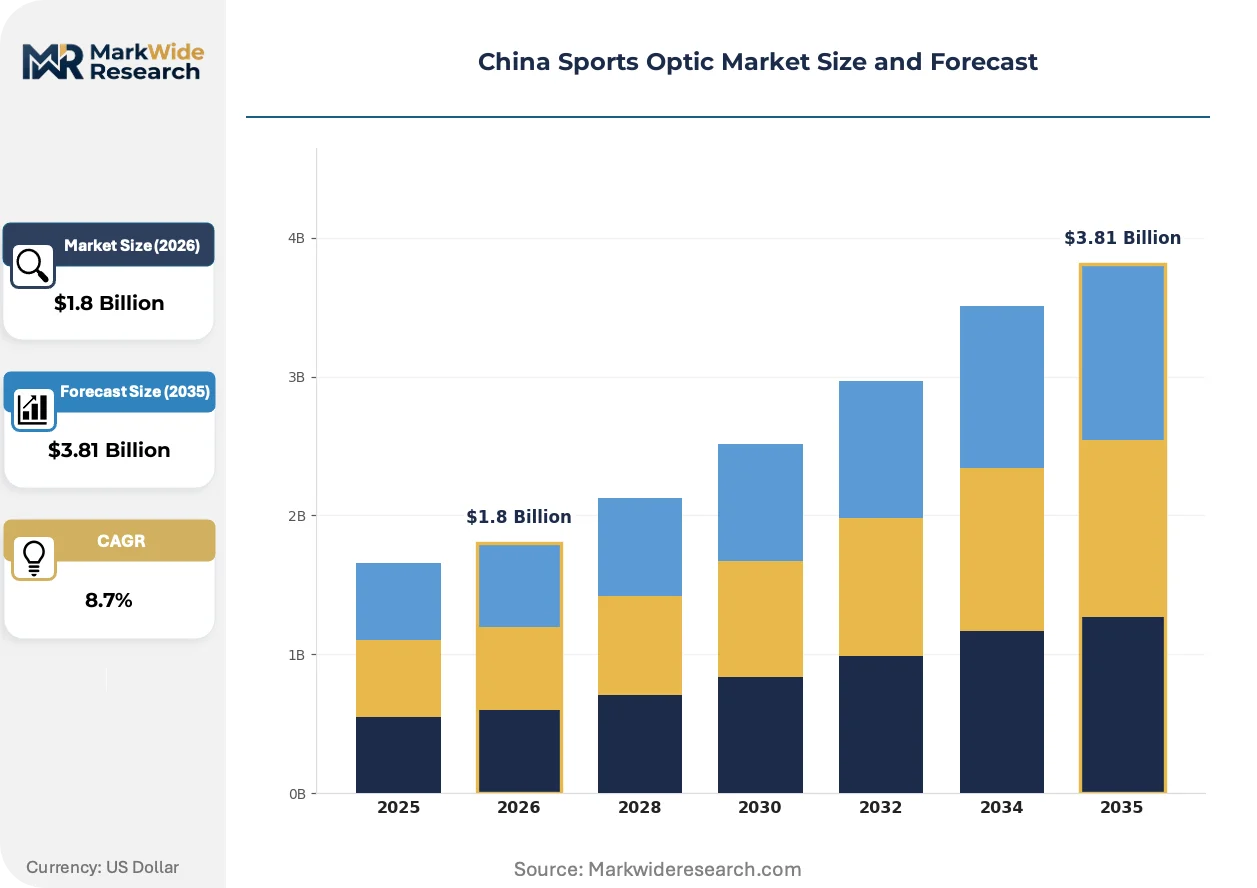
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binoculars, Spotting Scopes, Rangefinders, Goggles Use Case: Hunting, Wildlife Observation, Sports Events, Marine Activities Customer Type: Outdoor Enthusiasts, Professional Athletes, Hobbyists, Tourists Technology: Optical Zoom, Waterproofing, Night Vision, Digital Imaging |
| Companies Covered | Nikon Corporation, Carl Zeiss, Trijicon Inc., Teledyne FLIR LLC, Vortex Optics, Leica Camera AG, Guide Infrared Co., Ltd., Vector Optics, VISIONKING, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sports Optic Market Trends and Innovations
Computational imaging is dissolving the boundary between optical hardware and software-defined enhancement. This convergence is compressing product development cycles while elevating firmware capability as a competitive differentiator.
Silicon-carbide mirror substrates are rendering obsolete traditional glass primary optics in high-vibration hunting environments. Competitive shooters in Guangdong province are adopting these lightweight alternatives for rapid target acquisition. The structural consequence is collapsing the weight-performance tradeoff that previously segmented professional and consumer tiers.
MIIT's dual carbon goals are forcing energy audit compliance across lens polishing facilities in Jiangsu and Zhejiang. Manufacturers exceeding 50 kWh per kilogram of finished optic face production quota restrictions. Coastal exporters are responding by relocating energy-intensive grinding stages to western provinces with surplus hydroelectric capacity.
Specialized outdoor retailers are losing ground to manufacturer-direct livestream commerce on Douyin and Xiaohongshu. Young hunters in tier-two cities are bypassing traditional optics dealers for video-validated unboxing experiences. This channel rotation is most pronounced in Sichuan and Chongqing where provincial hunting association membership is rising fastest.
China Sports Optic Market Segmentation
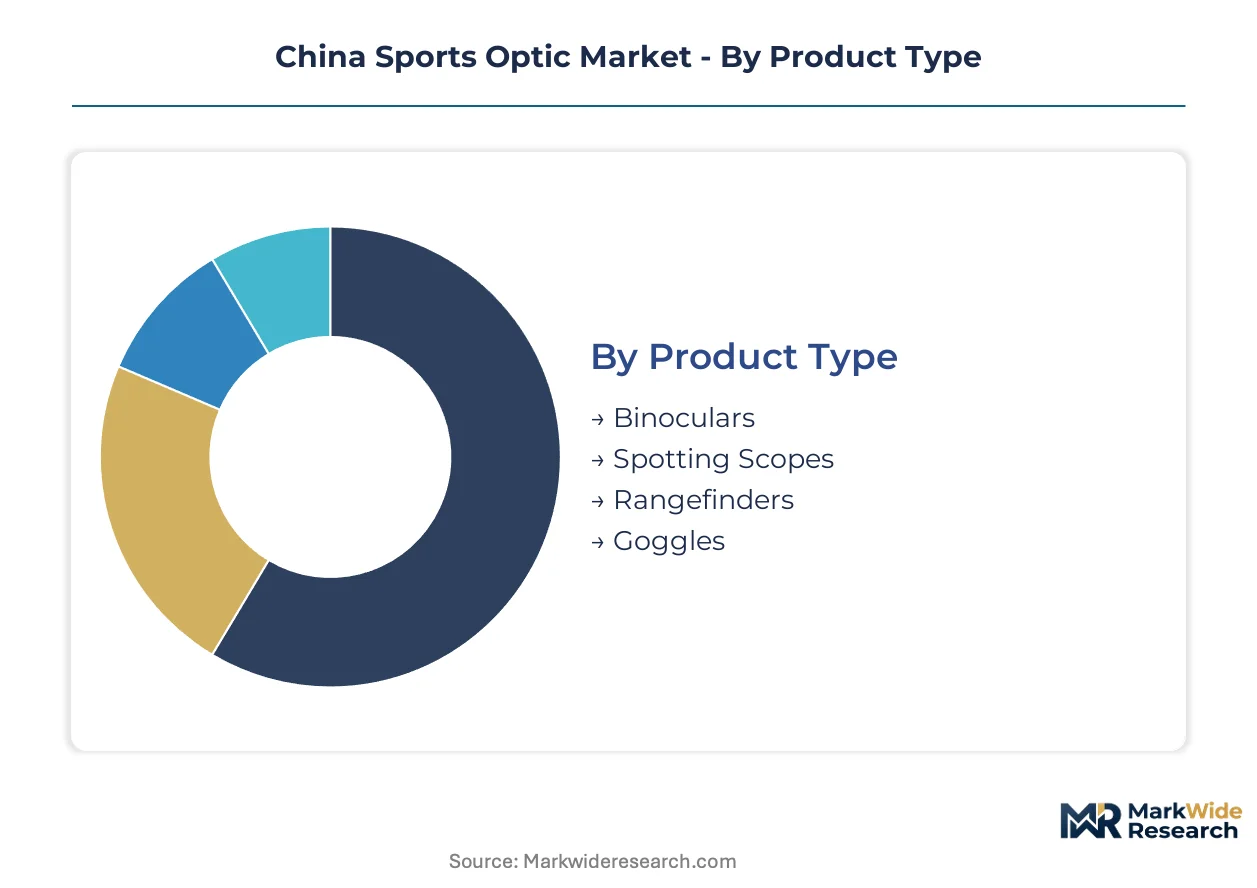
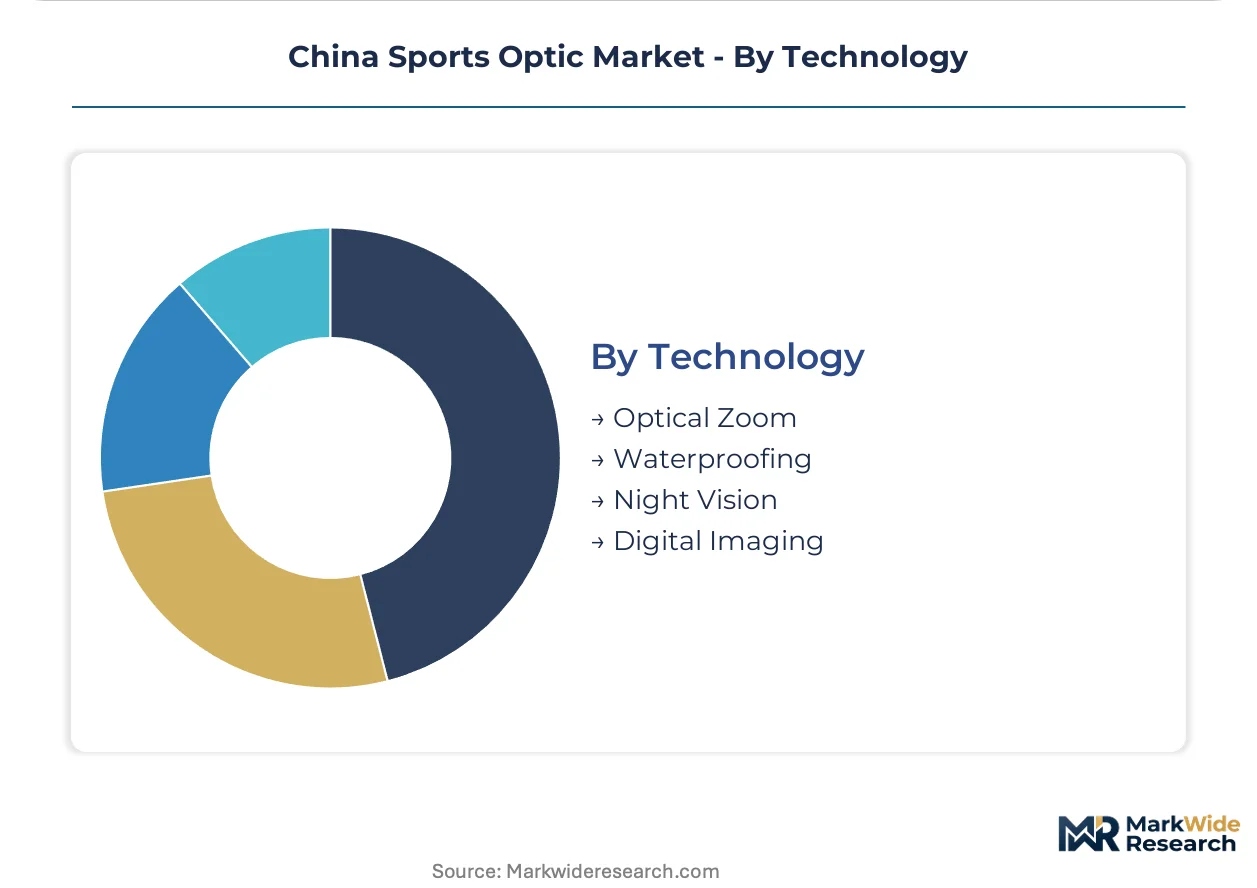
Segmentation in China's sports optic market reveals divergent replacement cycles and margin structures. Product type and technology dimensions show the widest gaps between commodity turnover and premium durability. Understanding these velocity differences sharpens inventory and channel strategy for manufacturers serving coastal clusters versus inland expansion zones.
Product Type:
Replacement cycles stretch from annual refresh rates for entry-level units to decade-long lifespans for professional-grade instruments. Coastal precision clusters in Jiangsu and Zhejiang dominate volume assembly, while thermal-integrated products concentrate margin pools.
- Binoculars:These dual-barrel refracting instruments employ roof or Porro prism configurations with multi-layer dielectric coatings achieving 90%+ light transmission. Demand concentrates among tourists and casual outdoor enthusiasts in Yunnan and Sichuan nature reserves, where ranger station procurement cycles are compressing. Entry-tier SKUs turn over fastest, flooding Douyin livestream channels.
- Spotting Scopes:High-magnification single-tube optics with ED glass elements and nitrogen-purged waterproofing serve wildlife observation at 60x+ zoom ratios. Professional photographers in Qinghai and Tibet wildlife corridors drive specification escalation toward fluorite crystal objectives. The MIIT's domestic optical component standards are accelerating local assembly of precision focus mechanisms.
- Rangefinders:Laser-emitting distance calculators with integrated ballistic computers for competitive shooting applications.
- Goggles:Head-mounted thermal and night vision systems with uncooled microbolometer sensors for hunting permit holders in select provinces.
Binoculars dominate installed base across all customer tiers. Spotting scopes represent where expansion concentrates as wildlife tourism infrastructure matures.
Use Case:
Application-driven demand splits between regulated activities requiring permit alignment and unrestricted recreational usage. Margin profiles invert between volume-heavy observation and premium-priced hunting segments.
- Hunting:Thermal optic and rangefinder combinations for permitted game management in provinces with liberalized regulations. Guangdong and Chongqing associations report fastest membership growth, concentrating demand for ballistic calculation overlays. Provincial permit fragmentation creates certification complexity that slows distribution scaling.
- Wildlife Observation:Spotting scope and binocular configurations for nature reserve visitors and ranger documentation. Sichuan panda corridor infrastructure expansion is driving 80mm+ objective lens adoption among domestic enthusiasts. State-funded biodiversity monitoring programs are shortening institutional procurement cycles.
- Sports Events:Compact zoom optics for stadium spectators and competitive shooting judges requiring rapid target acquisition.
- Marine Activities:Waterproof 7x50 standard binoculars with individual focus and compass reticles for coastal navigation.
Wildlife observation commands the broadest customer base. Hunting delivers the steepest expansion trajectory as thermal sensor costs decline and permit systems harmonize.
Customer Type:
Purchasing sophistication ranges from price-sensitive casual users to specification-driven professionals demanding telemetry integration. Channel preferences diverge sharply across these tiers.
- Outdoor Enthusiasts:Weekend hikers and campers seeking mid-tier waterproof binoculars with 8x-10x magnification. Tier-two city consumers in Hubei and Hunan are bypassing traditional retail for Xiaohongshu-validated purchases. Douyin unboxing videos are displacing specialized dealer relationships fastest in this segment.
- Professional Athletes:Competitive shooters and guides requiring real-time ballistics calculation and edge-computing integration. Guangdong province competitive leagues are adopting silicon-carbide mirror substrates for vibration resistance. Firmware capability is emerging as the primary differentiation lever.
- Hobbyists:Amateur astronomers and birdwatchers with intermittent usage patterns and storage-sensitive durability requirements.
- Tourists:Disposable-income visitors purchasing entry-tier optics at nature reserve gate retail.
Outdoor enthusiasts represent the volume anchor. Professional athletes concentrate premium tier innovation and margin expansion.
Technology:
Capability stacking determines price positioning, with basic waterproofing now table stakes and computational imaging creating new premium tiers. Technology integration intensity varies dramatically by end-use.
- Optical Zoom:Mechanical magnification systems employing ED glass and aspherical elements to minimize chromatic aberration. Japanese and German glass concentration exposes margins to yen-euro volatility. Domestic GB standard compliance is accelerating local grinding capability in Yangtze River Delta clusters.
- Waterproofing:Nitrogen purging and O-ring sealing achieving IPX7 ratings for marine and all-weather usage. Cleanroom assembly requirements conflict with legacy factory footprints in Guangdong precision instrument zones. Dual carbon retooling mandates are forcing vacuum coating upgrades.
- Night Vision:Image intensifier tubes and uncooled thermal microbolometers for low-light target acquisition. Sensor costs are democratizing capability for hunting permit holders as military supply chains pivot civilian. Western province retail infrastructure gaps present first-mover openings.
- Digital Imaging:CMOS sensor integration with wireless telemetry for real-time capture and ballistics calculation. Professional competitive shooters in Guangdong are demanding edge-computing overlays. This convergence is compressing product development cycles while elevating firmware differentiation.
Optical zoom dominates installed base across all price tiers. Digital imaging is where capability expansion and margin concentration intersect most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German ED glass shipments flow into Yangtze River Delta polishing facilities before finished optics reach Sichuan and Guangdong retail channels. Coastal manufacturing clusters dominate precision assembly while inland provinces drive consumption growth.
Yangtze River Delta
Jiangsu and Zhejiang host nitrogen-purging cleanrooms and vacuum coating facilities serving domestic GB compliance. MIIT dual carbon audits force energy-intensive grinding stages toward western hydroelectric zones. Suzhou precision instrument zones retool for 50 kWh per kilogram efficiency thresholds.
Pearl River Delta
Guangdong competitive shooting leagues demand silicon-carbide mirror substrates and real-time ballistics firmware. SAMR optical certification accelerates retail stocking decisions in Shenzhen and Dongguan. Master optician scarcity forces automation investments slower than planned across legacy factory footprints.
Sichuan-Chongqing
Panda corridor infrastructure expansion drives 80mm+ spotting scope adoption among domestic wildlife enthusiasts. Provincial nature reserve procurement cycles compress ranger station equipment refresh timelines. Chengdu and Chongqing urban consumers bypass traditional dealers for Douyin-validated thermal optic purchases.
Shandong Peninsula
Qingdao marine navigation demand concentrates waterproof 7x50 binocular specifications with compass reticles. Coastal shipping channels distribute finished products to Northeast Asian export markets. Local assembly plants integrate Japanese optical glass under yen-volatility hedging arrangements.
Western China
Hubei and Hunan retail infrastructure gaps present first-mover openings for direct-to-consumer thermal brands targeting tier-two city hunters. Underpenetrated Xiaohongshu commerce channels displace specialized outdoor retailers fastest in this zone. Surplus hydroelectric capacity attracts relocated energy-intensive grinding investments from coastal clusters.
China Sports Optic Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Japanese and German heritage brands occupy premium positioning through precision glass legacy. Domestic manufacturers anchor mid-tier volume through GB standard compliance and coastal cluster proximity. Competitive moves concentrate on firmware differentiation and thermal sensor integration rather than capacity expansion.
Within the heritage optics tier, Nikon Corporation and Carl Zeiss exemplify premium positioning sustained through multi-layer dielectric coating IP. Guide Infrared Co., Ltd. and Vector Optics occupy domestic manufacturing archetypes, with the former representing captive thermal core production and the latter exemplifying aggressive price-performance competition. These four anchors illustrate the market's bifurcation between import-dependent premium tiers and locally certified volume segments.
| Leading Market Players |
|---|
| Nikon Corporation |
| Carl Zeiss |
| Trijicon Inc. |
| Teledyne FLIR LLC |
| Vortex Optics |
| Leica Camera AG |
| Guide Infrared Co., Ltd. |
| Vector Optics |
| VISIONKING |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta nitrogen-purging cleanrooms is compressing mid-tier manufacturer margins while forcing premium brands to defend positioning through firmware differentiation. Coastal utilization rates below 70% are triggering price competition in entry-level binocular segments even as ED glass import costs sustain premium tier elevation.
Pricing Analysis
Prior-generation thermal microbolometer optics trade at 40% discounts to current-generation uncooled sensor units, while next-generation silicon-carbide mirror substrates command 3x premiums in Guangdong competitive shooting circles. Three-tier pricing structure across premium, standard, and economy levels separates professional athletes demanding real-time ballistics firmware from casual wildlife observers in Sichuan nature reserves. Cost compression in entry-tier SKUs is intensifying because Douyin livestream channels eliminate dealer markups. Outdoor enthusiasts in tier-two cities exhibit highest price sensitivity, while competitive shooters show near-zero elasticity for telemetry-integrated systems.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta precision instrument zones and Pearl River Delta legacy optics assembly plants, with limited third-party capacity in western hydroelectric regions. Japanese and German suppliers anchor ED glass feedstock, Chinese firms dominate thermal sensor packaging, and South Korean foundries supply CMOS imaging cores. Single-source vulnerability runs through Hoya and Schott optical glass concentrations exposed to yen-euro volatility. Distribution runs through Douyin and Xiaohongshu direct-to-consumer channels displacing specialized outdoor retailers fastest in Sichuan-Chongqing and Western China zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by MIIT dual carbon retooling completion and thermal sensor cost curve normalization. The recovery trajectory hinges on provincial hunting permit harmonization accelerating distribution scaling.
For Market Incumbents: Insulate premium positioning by in-housing thermal core production and securing captive ED glass offtake agreements with Japanese suppliers. Firmware differentiation represents the critical lever against price-erosion from Vector Optics and domestic GB-compliant entrants. Priority rests on defending Guangdong competitive shooter relationships through silicon-carbide substrate exclusivity. For New Entrants and Emerging Players: Pursue white-space penetration in Hubei and Hunan tier-two cities where Xiaohongshu commerce channels remain underdeveloped relative to coastal saturation. Central and Western China thermal optic distribution presents the most penetrable geography given ranger station procurement cycle compression in Sichuan. Go-to-market execution should anchor on video-validated unboxing content calibrated to provincial hunting association membership growth zones. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because master optician talent scarcity and multi-layer dielectric coating IP thickets are structurally advantaging scaled manufacturers with automation capital. Acquisition targets should screen for captive thermal core capability and MIIT GB certification compliance. The signal to watch is provincial hunting permit harmonization progress as inflection indicator for thermal optic distribution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Sensor Integration | Uncooled microbolometer cost declines are democratizing night vision for hunting permit holders in liberalized provinces. |
| Silicon-Carbide Substrate Adoption | Guangdong competitive shooters are rendering obsolete traditional glass optics in high-vibration hunting environments. |
| Direct-to-Consumer Channel Expansion | Douyin and Xiaohongshu livestream commerce is displacing specialized outdoor retailers in Sichuan and Chongqing. |
| GB Standards Compliance Investment | SAMR-administered optical performance benchmarks are accelerating retail channel stocking decisions for certified manufacturers. |
| Western China Manufacturing Relocation | Surplus hydroelectric capacity in Hubei and Hunan is attracting energy-intensive grinding investments from coastal clusters. |
Research Methodology
A spread of perspectives from precision instrument plant managers, MIIT regulatory affairs specialists, provincial hunting association procurement leads, and Douyin channel sales heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SAMR certification databases, MIIT energy audit disclosures, and provincial nature reserve procurement records. Bottom-up demand modeling across customer tiers triangulated with top-down supply capacity assessments from Yangtze River Delta and Pearl River Delta clusters.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, use case, customer sophistication tier, and technology integration intensity. CAGRs were derived from installed base turnover rates and replacement cycle compression observed in ranger station and competitive league procurement patterns. Forecast inputs incorporated thermal sensor cost curve trajectories and provincial hunting regulation harmonization timelines.
Sensitivities concentrate around yen-euro volatility in ED glass imports, MIIT dual carbon enforcement intensity, and provincial wildlife management regulatory divergence. Forecasts reflect assumptions on thermal sensor democratization velocity and firmware capability diffusion among domestic manufacturers. Quarterly review of SAMR certification issuance rates and provincial hunting permit system harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Juggling Clubs Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Padel Balls Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Bike Saddles Market