
 Global Sex Toys Market | 2026-2036
Global Sex Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sex Toys Market Foresight
Medical-grade silicone is expanding its share of premium product lines as manufacturers abandon phthalate-laden PVC formulations to meet stricter biocompatibility standards and reduce liability exposure. LELO leverages vertical integration across design and distribution to command premium positioning in European and Asian markets. Doc Johnson Enterprises anchors North American manufacturing scale through its Los Angeles facility, while TENGA Co., Ltd. competes through distinctive product architecture and discrete packaging norms suited to Japanese retail conventions.
Sex toys comprise electromechanical and non-powered devices engineered for genital or erogenous-zone stimulation, typically incorporating vibration motors rated between 3,000 and 10,000 RPM, rechargeable lithium-ion power cells, and IPX7 water-resistant sealing for hygienic cleaning. Their commercial purpose spans personal pleasure, couples' intimacy enhancement, and prescribed sexual wellness therapy for conditions including anorgasmia and erectile dysfunction. Silicone formulations dominate premium tier margins due to hypoallergenic properties and thermal stability, while ABS Plastic occupies mass-market price points through injection-molded efficiency. Online Retailers capture the fastest-growing distribution trajectory as direct-to-consumer platforms bypass geographic stigma barriers and enable subscription-based replenishment models.
FDA oversight of devices marketed with therapeutic claims in the United States, combined with EU REACH substance restrictions and CE marking requirements under the MDR framework, elevates compliance costs but simultaneously filters low-quality competitors from Western markets. Japan's PMDA and METI coordinate on electrical safety standards for motorized intimate devices, creating a dual-track approval environment distinct from Western pharmaceutical-device classifications. Stakeholders must monitor evolving definitions of wellness versus medical claims across jurisdictions, as regulatory reclassification would fundamentally alter distribution channels and marketing permissible under each framework.
Market Dynamics
REACH substance restrictions and MDR biocompatibility mandates are forcing manufacturers to abandon phthalate-laden PVC formulations and retool production lines around medical-grade silicone, compressing margins for mid-tier producers while elevating compliance costs across European and North American supply chains.
Growth Catalysts
- REACH and RoHS frameworks:European chemical safety mandates accelerate the phase-out of hazardous plasticizers, creating premium positioning for silicone-based product lines that command higher retail price points and reduced liability exposure.
- Millennial and Gen Z buyer expansion:Direct-to-consumer platforms dismantle geographic stigma barriers through discrete packaging and subscription replenishment models, capturing cohorts previously excluded from brick-and-mortar retail channels.
- Medical-grade silicone thermal stability:Hypoallergenic material properties enable therapeutic device classification pathways, opening reimbursement discussions with healthcare systems in Germany, Japan, and the United States.
Market Restraints
- Medical-grade silicone feedstock concentration:Specialty polymer supply concentrates among a limited set of European and North American chemical processors, exposing manufacturers to input cost volatility and allocation constraints during demand surges.
- FDA therapeutic claim oversight:Devices marketed for sexual wellness therapy face extended 510(k) review timelines and clinical substantiation requirements, delaying market entry and elevating regulatory capital reserves.
- IPX7 sealing technical limitation:Water-resistant motor housing designs constrain vibration motor thermal dissipation, capping maximum RPM ratings and limiting power output relative to corded alternatives.
Strategic Opportunities
- Japanese retail convention adaptation:Discrete packaging norms and compact form factors suited to urban density create export templates for South Korean, Singaporean, and Taiwanese metropolitan markets with comparable spatial constraints.
- Subscription-based replenishment channels:Direct-to-consumer platforms enable recurring revenue models through consumable accessory bundling, reducing customer acquisition costs and improving lifetime value metrics.
- EU MDR classification alignment:CE marking under medical device regulations permits therapeutic positioning and healthcare procurement channel access, differentiating compliant manufacturers from general wellness competitors.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols for skin contact devices extend product development cycles by 8-14 months, compressing first-mover advantage windows and elevating working capital requirements.
- Electrical safety standard fragmentation:Divergent PMDA-METI coordination in Japan versus FDA-FCC alignment in the United States forces dual-track engineering validation, duplicating compliance expenditure for multi-regional launches.
- Supply chain reconfiguration friction:PVC-to-silicone material transitions require injection mold retooling, curing oven installation, and workforce retraining, straining mid-capitalization producers with limited technical transfer capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sex Toys Market |
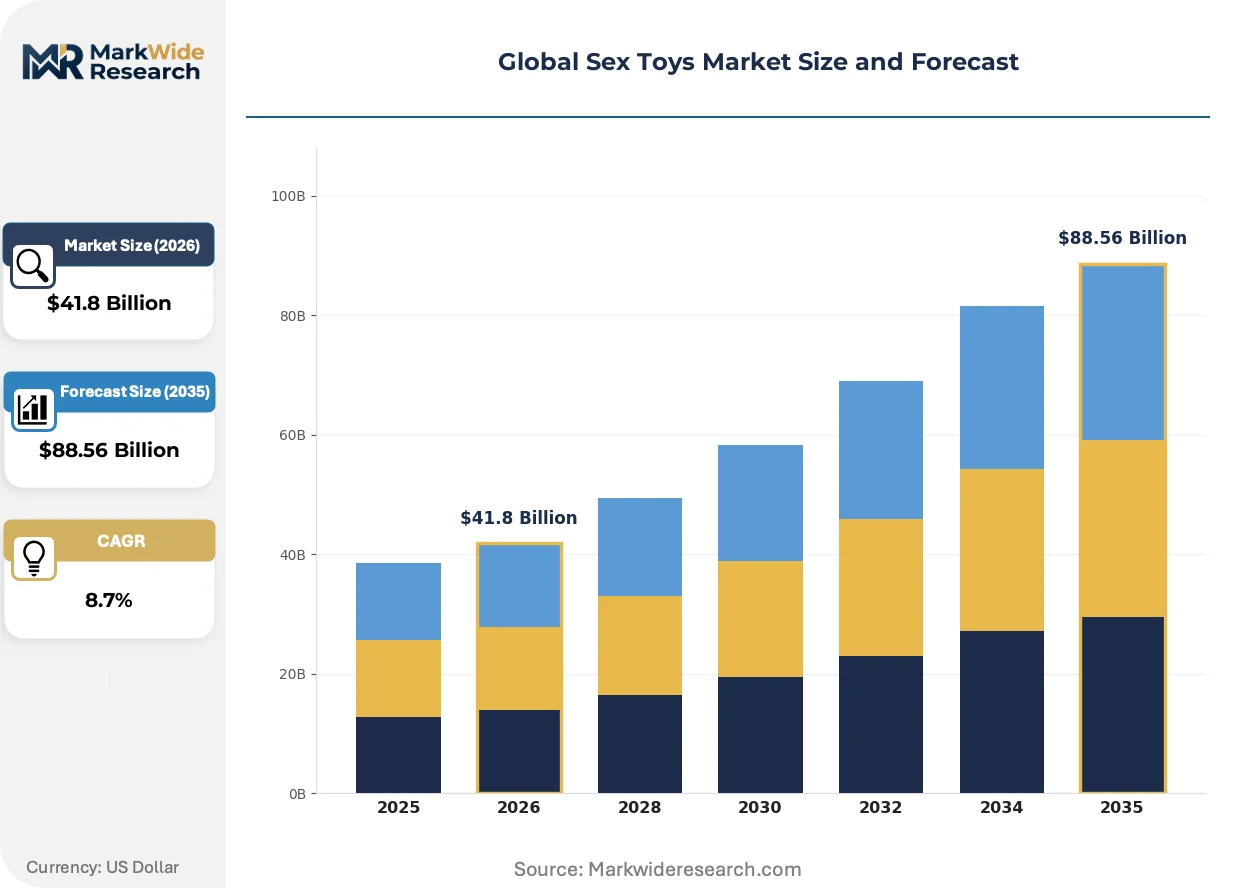
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $88.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibrators, Dildos, Anal Toys, Masturbators, Couples' Toys, Lubricants Material: Silicone, ABS Plastic, TPE, Glass, Metal, Wood Application: Personal Pleasure, Couples' Enhancement, Sexual Wellness, Medical Therapy, Sensory Stimulation, Relationship Building Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Supermarkets, Direct Sales, Boutique Shops |
| Companies Covered | LELO, Doc Johnson Enterprises, We-Vibe, Lovehoney Group Ltd, FUN FACTORY GmbH, BMS Factory, TENGA Co., Ltd., Church & Dwight Co., Inc., Adam & Eve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sex Toys Market Shifts & Advancements
App-connected firmware and biometric feedback systems are compressing product differentiation cycles, forcing manufacturers to embed software engineering capabilities alongside traditional electromechanical design competencies.
Bluetooth Low Energy connectivity is integrating haptic feedback customization and partner-remote control functionality into rechargeable device architectures. Wellness-focused buyer segments in Germany and California adopt these features at replacement-cycle intervals of 18-24 months. The technology is integrating hardware-software bundling that locks users into proprietary app ecosystems and subscription accessory models.
EU MDR substance restrictions and biocompatibility documentation requirements tighten material traceability obligations across the supply chain. Manufacturers must now maintain batch-level silicone polymer certificates and third-party lab testing records for CE marking audits. Premium product lines in France, Italy, and the Netherlands absorb these compliance costs most directly, while mass-market competitors face margin compression or market exit.
Subscription-based replenishment models displace traditional retail purchasing patterns among urban millennial demographics. Direct-to-consumer platforms capture recurring revenue through lubricant, cleaner, and accessory bundling, while specialty boutiques lose foot traffic in Berlin, Tokyo, and New York. This channel rotation is most visible in metropolitan markets with dense same-day delivery logistics infrastructure and established discrete packaging norms.
Global Sex Toys Market Segmentation
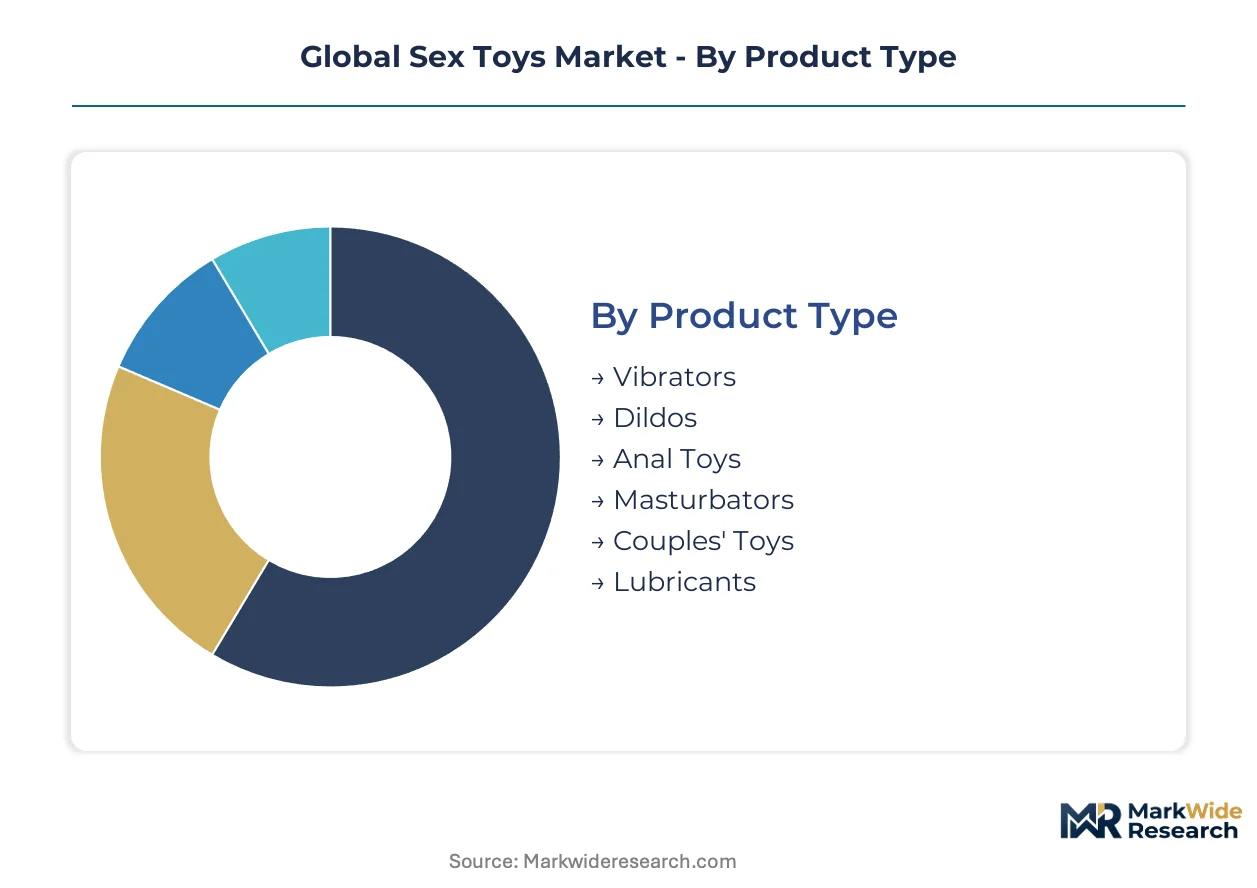
Material composition and distribution channel access determine buyer willingness-to-pay and regulatory compliance burden across the Global Sex Toys Market. Product architecture choices cascade through manufacturing cost structures, biocompatibility certification requirements, and retail placement possibilities.
Product Type:
Buyers prioritize functional versatility and discretion in form factor when selecting stimulation devices for solo or partnered use.
- Vibrators:Electromechanical devices incorporating vibration motors rated between 3,000 and 10,000 RPM with rechargeable lithium-ion power cells and IPX7 water-resistant sealing. Demand concentrates in Germany and California where wellness-focused buyer segments adopt app-connected firmware and biometric feedback systems at replacement-cycle intervals of 18-24 months.
- Dildos:Non-powered penetration devices manufactured through injection molding or hand-pouring processes, available in anatomical and abstract form factors. Sales velocity runs highest in United States urban markets where direct-to-consumer platforms dismantle geographic stigma barriers through discrete packaging norms.
- Anal Toys:Specialized devices with flared base safety architecture and graduated sizing systems for progressive comfort adaptation.
- Masturbators:Male-focused stimulation sleeves and automated devices, with compact form factors suited to Japanese retail conventions and urban density constraints.
- Couples' Toys:Wearable or remote-controllable devices designed for partnered intimacy enhancement, featuring Bluetooth Low Energy connectivity for haptic customization.
- Lubricants:Water-based, silicone-based, and hybrid formulations sold as consumable accessories bundled into subscription replenishment models.
Vibrators lead on scale; couples' toys lead on momentum.
Material:
Regulatory pressure on chemical safety is restructuring procurement patterns across European and North American supply chains.
- Silicone:Medical-grade formulations meeting ISO 10993 biocompatibility standards for skin contact devices, with thermal stability enabling sterilization protocols. Manufacturers in France, Italy, and the Netherlands absorb batch-level polymer certificate and third-party lab testing costs most directly to maintain CE marking under MDR framework.
- ABS Plastic:Injection-molded thermoplastic polymer occupying mass-market price points through manufacturing efficiency, though facing phase-out pressure from REACH substance restrictions on hazardous plasticizers.
- TPE:Thermoplastic elastomer blends offering softness gradients at lower cost tiers, common in disposable or short-lifecycle products.
- Glass:Borosilicate formulations valued for thermal conductivity and aesthetic properties, niche-positioned in artisanal and premium boutique channels.
- Metal:Surgical-grade stainless steel and aluminum alloys targeting durability-focused buyers and temperature-play applications.
- Wood:Sealed hardwood products from sustainable forestry sources, occupying craft-market positioning with limited scale.
Silicone commands the steepest expansion trajectory as PVC-to-silicone transitions accelerate; ABS plastic retains volume leadership in price-sensitive segments.
Application:
End-use purpose determines marketing permissible, distribution channel access, and reimbursement discussion potential with healthcare systems.
- Personal Pleasure:Solo-use devices marketed through direct-to-consumer platforms with subscription-based replenishment models capturing recurring revenue through lubricant and accessory bundling.
- Couples' Enhancement:Partnered intimacy products with remote-control functionality, expanding most quickly in metropolitan markets with dense same-day delivery logistics infrastructure.
- Sexual Wellness:Positioning that navigates wellness-versus-medical claim definitions across FDA, EMA, and PMDA jurisdictions, requiring careful regulatory monitoring.
- Medical Therapy:Devices prescribed for anorgasmia, erectile dysfunction, and pelvic floor rehabilitation, facing extended 510(k) review timelines and clinical substantiation requirements in United States markets.
- Sensory Stimulation:Products targeting neurodivergent users or those seeking alternative sensory experiences through texture, temperature, or vibration variation.
- Relationship Building:Communication-focused kits and guided experience products sold through specialty boutiques losing foot traffic to online channels in Berlin, Tokyo, and New York.
Personal pleasure leads on scale; medical therapy leads on margin expansion potential.
Distribution Channel:
Channel selection shapes customer acquisition economics, brand positioning latitude, and geographic reach constraints.
- Online Retailers:Direct-to-consumer platforms bypassing geographic stigma barriers, capturing fastest-growing distribution trajectory through discrete packaging and subscription replenishment models among millennial and Gen Z demographics.
- Specialty Stores:Brick-and-mortar boutiques with educated staff and product demonstration capabilities, experiencing foot traffic erosion in dense urban markets.
- Pharmacies:Retail health channels permitting therapeutic positioning and healthcare procurement access for MDR-compliant manufacturers.
- Supermarkets:Mass-market placement for lubricants and entry-level devices, constrained by shelf-space competition and conservative corporate purchasing policies.
- Direct Sales:Party-plan and consultant-based models with high-touch customer education, declining share in digital-native buyer cohorts.
- Boutique Shops:Curated independent retailers emphasizing artisanal and luxury positioning, concentrated in Paris, London, and Los Angeles.
Online retailers lead on momentum; specialty stores lead on customer lifetime value for premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors manufacturing scale for North American supply chains, while regulatory divergence across FDA, ECHA, and PMDA jurisdictions fragments compliance pathways for multi-regional operators.
United States
Direct-to-consumer platforms dismantle geographic stigma barriers through discrete packaging and subscription replenishment models. FDA oversight of therapeutic claims forces extended 510(k) review timelines and clinical substantiation requirements. California's wellness-focused buyer segments in San Francisco and Los Angeles adopt app-connected firmware at compressed replacement cycles.
Germany
REACH substance restrictions and MDR biocompatibility mandates accelerate PVC-to-silicone transitions among manufacturers. ECHA enforcement elevates batch-level polymer certificate and third-party lab testing obligations. Berlin specialty boutiques experience foot traffic erosion as online channels capture recurring revenue through lubricant and accessory bundling.
Japan
PMDA and METI coordinate on electrical safety standards for motorized intimate devices, creating dual-track approval environments distinct from Western pharmaceutical-device classifications. Compact form factors suited to urban density drive export templates for metropolitan Asian markets. Tokyo's retail conventions emphasize discrete packaging norms that constrain marketing latitude.
United Kingdom
Post-Brexit regulatory divergence from EU MDR frameworks creates parallel compliance obligations for CE-marked and UKCA-marked product lines. London's curated independent retailers emphasize artisanal and luxury positioning. Manchester and Birmingham distribution hubs consolidate direct-to-consumer fulfillment infrastructure for European cross-border sales.
France
ANSM oversight intersects with EU chemical safety mandates to tighten material traceability across silicone supply chains. Paris boutique shops absorb premium-tier compliance costs most directly. Lyon and Marseille metropolitan markets demonstrate dense same-day delivery logistics infrastructure supporting subscription replenishment adoption.
Global Sex Toys Market Competitive Landscape
Global majors compete with regional champions across material certification and distribution channel access. Market structure tierizes across premium silicone specialists, mass-market ABS plastic fabricators, and vertically integrated design houses. Three archetypes dominate: medical-grade formulation leaders, direct-to-consumer platform operators, and discrete packaging innovators. Competitive moves concentrate on M&A for compliance capabilities and capacity expansion for silicone polymer processing.
Within the premium-tier vector, LELO exemplifies vertically integrated design-to-distribution positioning across European and Asian markets. Doc Johnson Enterprises anchors North American manufacturing scale through its Los Angeles-based production footprint. TENGA Co., Ltd. occupies a distinctive position through compact form factors and packaging norms calibrated to Japanese retail conventions.
| Leading Market Players |
|---|
| LELO |
| Doc Johnson Enterprises |
| We-Vibe |
| Lovehoney Group Ltd |
| FUN FACTORY GmbH |
| BMS Factory |
| TENGA Co., Ltd. |
| Church & Dwight Co., Inc. |
| Adam & Eve |
| Others |
Supply & Pricing Matrix
EU REACH substance restrictions gate both qualified silicone feedstock access and premium-tier pricing power, as manufacturers absorbing batch-level polymer certification costs pass through elevated input expenses to wellness-focused buyer segments in Germany and California while mid-tier ABS plastic competitors face margin compression or market exit.
Pricing Analysis
Medical-grade silicone feedstock costs pass through to end-buyers via three-tier pricing structure across premium, standard, and economy levels, with ISO 10993 biocompatibility certification and brand heritage driving differentiation between LELO-positioned luxury tiers and mass-market alternatives. Pricing pressure stems from specialty polymer supply concentration among limited European and North American chemical processors, exposing manufacturers to allocation constraints. Gen Z direct-to-consumer subscribers show lowest price sensitivity due to subscription bundling, while supermarket mass-market buyers remain most elastic.
Supply Chain Analysis
Returns processing and refurbishment flows for motorized devices with lithium-ion cells complicate reverse logistics, as IPX7-sealed housings must be disassembled for battery recovery under EU WEEE directives. Manufacturing concentrates in China, Germany, and Japan, with medical-grade silicone polymer sourcing from specialty chemical processors in the Netherlands and Pennsylvania. Tariff exposure on Chinese-assembled electronics creates vulnerability for cost-optimized product lines. Distribution runs through direct-to-consumer platforms and specialty boutiques, with pharmacy channels expanding for MDR-compliant therapeutic positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate among manufacturers completing PVC-to-silicone material transitions, as compliance-driven supply consolidation eliminates low-quality competitors and leaves premium positioning to scaled specialists with captive polymer relationships.
For Market Incumbents: Anchor North American manufacturing scale through Los Angeles facility consolidation while deepening backward integration into medical-grade silicone compounding to offset feedstock volatility. Defend against direct-to-consumer platform disintermediation by capturing subscription replenishment revenue through lubricant and accessory bundling. Prioritize FDA 510(k) pathway investment for therapeutic claim differentiation. For New Entrants and Emerging Players: EU MDR classification alignment in Germany opens a window for premium positioning through CE-marked medical device procurement channels, bypassing crowded general wellness segments. Target compact form factor design for Japanese and South Korean metropolitan density constraints. Launch through discrete packaging direct-to-consumer platforms to circumvent specialty boutique gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap silicone specialists with incomplete certification pipelines but established manufacturing infrastructure. Long-term viability favors vertically integrated design houses with proprietary app ecosystems and recurring revenue attachment. Monitor FDA therapeutic claim reclassification discussions as inflection signal for reimbursement channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Silicone Transition | REACH compliance eliminates phthalate-laden PVC competitors from European markets. |
| Direct-to-Consumer Platform Launch | Subscription bundling captures recurring revenue from millennial urban demographics. |
| FDA 510(k) Therapeutic Pathway | Clinical substantiation opens healthcare procurement and reimbursement discussions. |
| App-Connected Firmware Development | Bluetooth Low Energy integration locks users into proprietary accessory ecosystems. |
| Japanese Retail Convention Adaptation | Discrete packaging norms create export templates for dense Asian metropolitan markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with product development executives at silicone formulation specialists, regulatory affairs leads navigating FDA and ECHA frameworks, direct-to-consumer platform operators, and hospital procurement managers evaluating therapeutic device categories. Secondary validation drew from FDA 510(k) filings, ECHA REACH substance restriction updates, EU MDR guidance documents, and customs trade data on polymer feedstock flows. Bottom-up manufacturer capacity assessments and top-down demographic demand modeling were triangulated against channel shipment data.
Comparable historical periods anchored projections across the analysis window, with segmentation modeling by material grade tier, distribution channel type, application purpose, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, subscription attachment rate trajectories, and certification-driven supply consolidation patterns. Forecast inputs incorporated biocompatibility testing timeline extensions and direct-to-consumer logistics infrastructure penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA therapeutic reclassification scenarios or ECHA polymer supply allocation shocks. Practitioners should monitor regulatory definition shifts between wellness and medical claims, specialty silicone processor capacity announcements, and direct-to-consumer platform customer acquisition cost trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Compostable Toothbrush Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Electric Shavers Market
Personal Grooming Products
Global Away-From-Home Tissue and Hygiene Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Sneaker Deodorant Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Organic and Natural Tampons Market