
 Compostable Toothbrush Market | 2026-2036
Compostable Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Toothbrush Market Analysis
Hotel procurement teams is rotating toward compostable amenities as sustainability mandates harden across the hospitality sector. Brush with Bamboo leverages its Pacific Northwest manufacturing base to control bamboo fiber sourcing. Humble Group anchors European distribution through pharmacy and eco-retail channels. Colgate-Palmolive Company competes via brand recognition and existing retail shelf dominance in conventional oral care.
A compostable toothbrush is a manually operated oral hygiene device whose handle and bristles degrade into non-toxic organic matter under industrial or home composting conditions, typically incorporating bamboo cellulose, polylactic acid, or castor-oil-derived nylon-11 in bristle construction. Its primary commercial purpose is to replace petroleum-based plastic toothbrushes that persist in landfills and marine environments for centuries. Bamboo handles currently lead product type volumes due to established agricultural supply chains and consumer familiarity, while cornstarch variants represent the fastest-growing material category as injection-molding compatibility improves. Subscription services within distribution channels capture disproportionate margin pools through recurring revenue and direct customer relationships that bypass wholesale markups.
The EU Green Deal and REACH regulations restrict conventional plastic content in consumer goods sold across member states, compelling formulation shifts toward certified compostable inputs. The FDA maintains safety standards for oral care devices in the United States, while BIS certification requirements in India create compliance thresholds for imported compostable products. Stakeholders must monitor compostability certification fragmentation between industrial and home standards, as divergent labeling rules across jurisdictions threaten consumer trust and market access clarity.
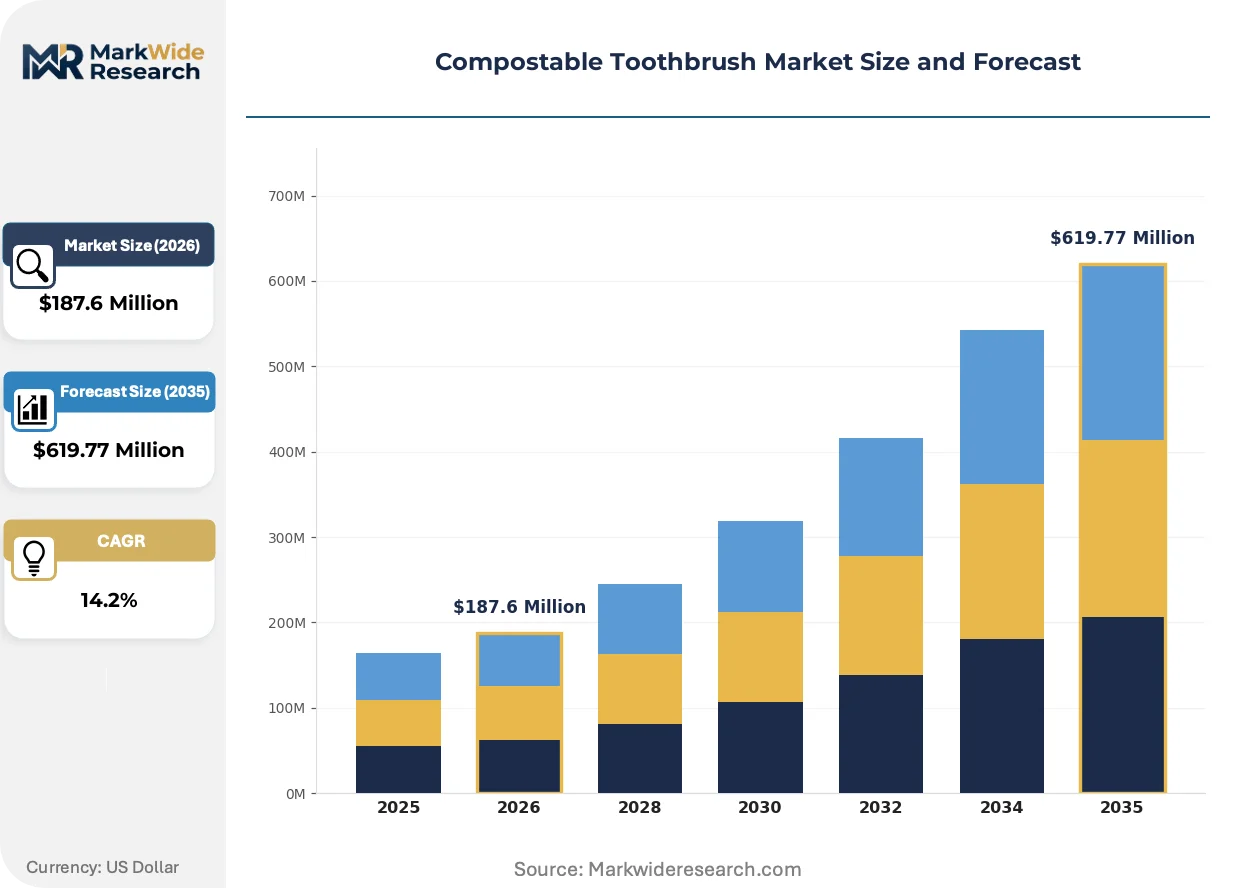
Market Dynamics
The compostable toothbrush market is experiencing structural pressure from municipal composting infrastructure gaps that fragment end-of-life processing capabilities across jurisdictions. Manufacturers must navigate certification heterogeneity while scaling bamboo fiber supply chains to meet hospitality and retail procurement mandates.
Growth Catalysts
- EU Green Deal plastic restrictions:REACH frameworks ban petroleum-based polymers in consumer goods, forcing formulation shifts toward certified compostable inputs across member states.
- Castor-oil-derived nylon-11 bristles:This bio-based polymer achieves performance parity with conventional nylon while enabling home compostability, accelerating material substitution in premium product tiers.
- German municipal composting networks:Industrial composting facility density supports verified end-of-life processing, creating demand concentration for certified compostable oral care products.
Market Restraints
- Bamboo fiber supply concentration:Pacific Northwest and Zhejiang Province agricultural bases control raw material flows, exposing manufacturers to climate-driven harvest volatility and freight cost spikes.
- Industrial versus home composting certification divergence:BPI and OK Compost HOME standards create labeling fragmentation that confuses consumer purchase decisions and complicates cross-border retail distribution.
- Petroleum-based plastic price anchoring:Conventional polypropylene handles maintain 60-80% cost advantages at manufacturing scale, compressing margin structures for compostable alternatives in price-sensitive retail channels.
Strategic Opportunities
- Indian BIS certification pathway:Import compliance thresholds for compostable consumer goods create first-mover advantages for certified manufacturers targeting pharmacy and modern trade expansion.
- Subscription direct-to-consumer channels:Recurring revenue models bypass wholesale markups while capturing customer relationship data that informs product iteration cycles.
- Cornstarch injection-molding compatibility:Material science advances enable conventional manufacturing equipment utilization, reducing capital barriers for plastic toothbrush converters entering compostable segments.
Industry Challenges
- Compostability testing protocol complexity:ISO 17088 and ASTM D6400 certification timelines extend 12-18 months, delaying product launches and freezing working capital in inventory.
- Multi-material assembly integration:Bamboo handles require moisture-resistant adhesives and bristle anchoring systems that complicate automated production lines designed for homogeneous plastic construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Toothbrush Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $619.77 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo, Biodegradable Plastic, Cornstarch, Wood End User: Households, Dental Clinics, Eco-Store Retailers, Hospitality Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Subscription Services Packaging Type: Recyclable Paper, Biodegradable Film, Minimalist Carton, Plant-Based Bags |
| Companies Covered | Colgate-Palmolive Company, Brush with Bamboo, Humble Group, Bam&Boo, Georganics Company, WooBamboo, Mabboo Company, Bambrush, Environmental Toothbrush, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Toothbrush Market Emerging Trajectories
Material science convergence with regulatory mandates is compressing development cycles for bio-based oral care products. Three distinct vectors are reshaping competitive positioning: polymer chemistry evolution, compliance framework tightening, and procurement model transformation.
Castor-oil-derived nylon-11 is displacing petroleum-based nylon-6 in bristle construction across European pharmacy channels. Hotel procurement teams specify this material for amenity programs seeking EU Green Deal alignment. The displacement is compressing conventional polymer demand while creating captive supply relationships between brush manufacturers and Indian castor bean processors.
REACH authorization requirements for microplastic additives now extend to oral care products sold in EU member states. Formulators must submit safety dossiers for residual polymer content in bristle coatings. German eco-retailers and Scandinavian pharmacy chains are responding by delisting products lacking OK Compost HOME certification, accelerating third-party verification adoption.
Buyer concentration in hospitality procurement is consolidating vendor relationships around single-source compostable amenity contracts. Independent hotels and boutique chains are displacing fragmented spot purchasing with multi-year supply agreements that bundle toothbrushes with other biodegradable room amenities. This pattern is most visible in Nordic markets where municipal sustainability mandates cascade through franchise operator requirements.
Compostable Toothbrush Market Segmentation
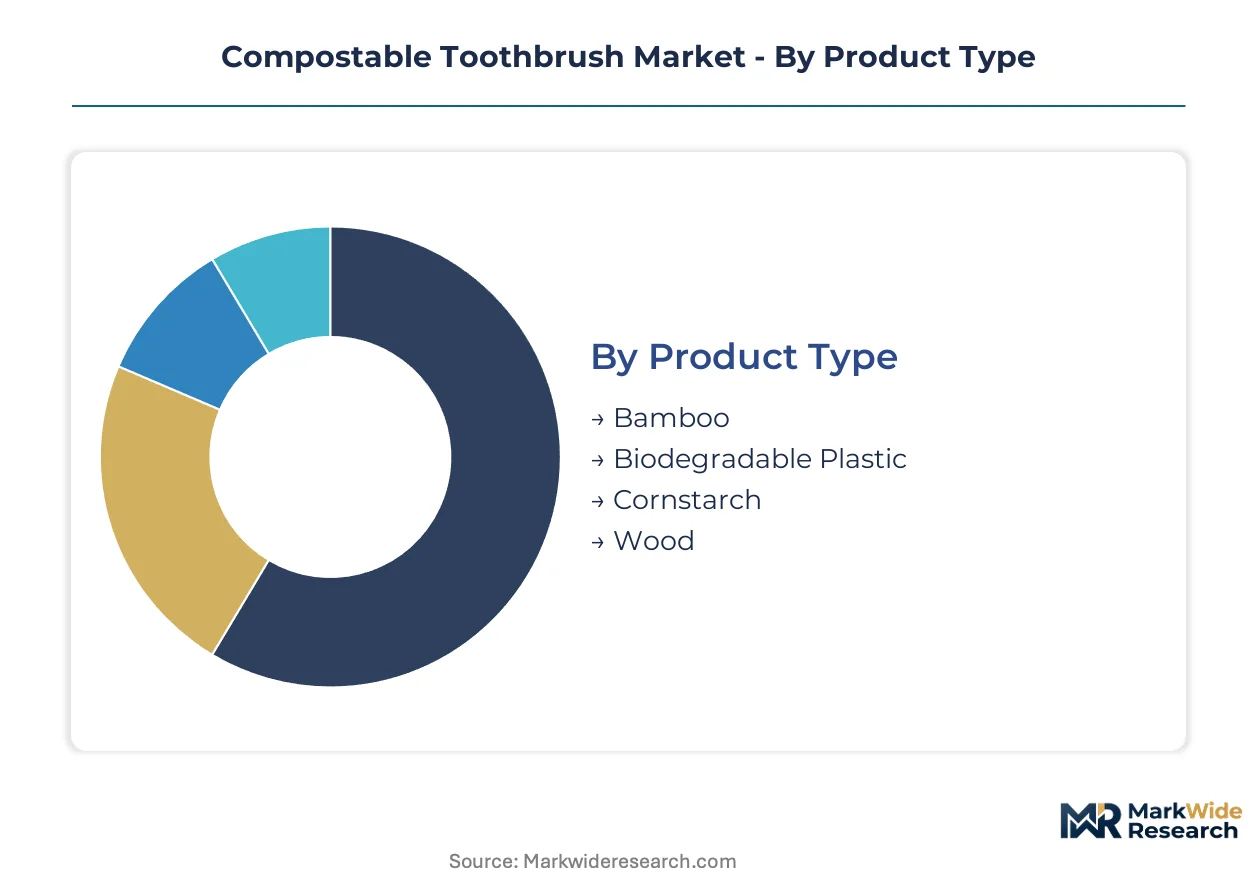
Segmentation in the compostable toothbrush market reveals where petroleum-based substitutes retain cost advantages and where bio-based alternatives command procurement premiums. Material composition and distribution channel choices determine margin structures and end-of-life processing requirements.
Product Type:
Bamboo handles face substitution pressure from cornstarch injection-molded variants that leverage existing plastic toothbrush manufacturing equipment, while biodegradable plastic competes directly with conventional polypropylene on price.
- Bamboo:Cellulose fiber handles sourced from Pacific Northwest and Zhejiang Province agricultural bases dominate current production volumes. German municipal composting networks and Nordic hotel procurement programs specify bamboo for verified end-of-life processing under industrial composting standards.
- Cornstarch:Polylactic acid blends achieve injection-molding compatibility with conventional equipment, reducing capital barriers for plastic toothbrush converters. This segment captures pharmacy and modern trade expansion in India where BIS certification pathways reward first-mover manufacturers.
- Biodegradable Plastic:Petroleum-alternative polymers from castor-oil and sugarcane feedstocks serve premium product tiers seeking performance parity with conventional nylon bristles.
- Wood:Beech and maple handles from European forestry operations target eco-retail channels emphasizing regional supply chain transparency and FSC certification alignment.
Bamboo retains volume leadership; cornstarch holds the steepest expansion curve.
End User:
Cost tier stratification separates premium hospitality procurement from price-sensitive household purchasing, with dental clinics occupying a mid-tier position driven by professional recommendation authority.
- Households:Individual consumers purchasing through pharmacy, supermarket, and online channels represent the largest addressable population. REACH-compliant product specifications and OK Compost HOME certification influence purchase decisions in EU member states.
- Hospitality:Hotel procurement teams rotate toward single-source compostable amenity contracts bundling toothbrushes with biodegradable room supplies. Nordic franchise operators cascade municipal sustainability mandates through vendor consolidation.
- Dental Clinics:Professional recommendation channels in Germany and Scandinavian markets drive patient trial and repeat purchase conversion for certified compostable alternatives.
- Eco-Store Retailers:Specialty channels including zero-waste shops and organic product chains curate SKU assortments around third-party compostability verification and transparent supply chain documentation.
Households retain volume leadership; hospitality holds the steepest expansion curve.
Distribution Channel:
Margin capture potential varies dramatically across channels, with direct-to-consumer subscription models bypassing wholesale markups while brick-and-mortar retains tactile evaluation advantages for first-time compostable product trial.
- Subscription Services:Recurring revenue models capture customer relationship data informing product iteration cycles. Brush replacement scheduling aligns with dentist-recommended three-month replacement intervals.
- Online Retail:E-commerce platforms enable cross-border access to certified products where local retail distribution remains underdeveloped, particularly for Indian and Southeast Asian consumers seeking BIS-compliant imports.
- Brick-and-Mortar:Pharmacy and supermarket shelf placement depends on certification clarity and labeling standardization across BPI and OK Compost HOME frameworks.
- Wholesale:Bulk procurement for hospitality and corporate wellness programs leverages volume pricing and consolidated logistics to offset per-unit compostability certification costs.
Brick-and-mortar retains volume leadership; subscription services hold the steepest expansion curve.
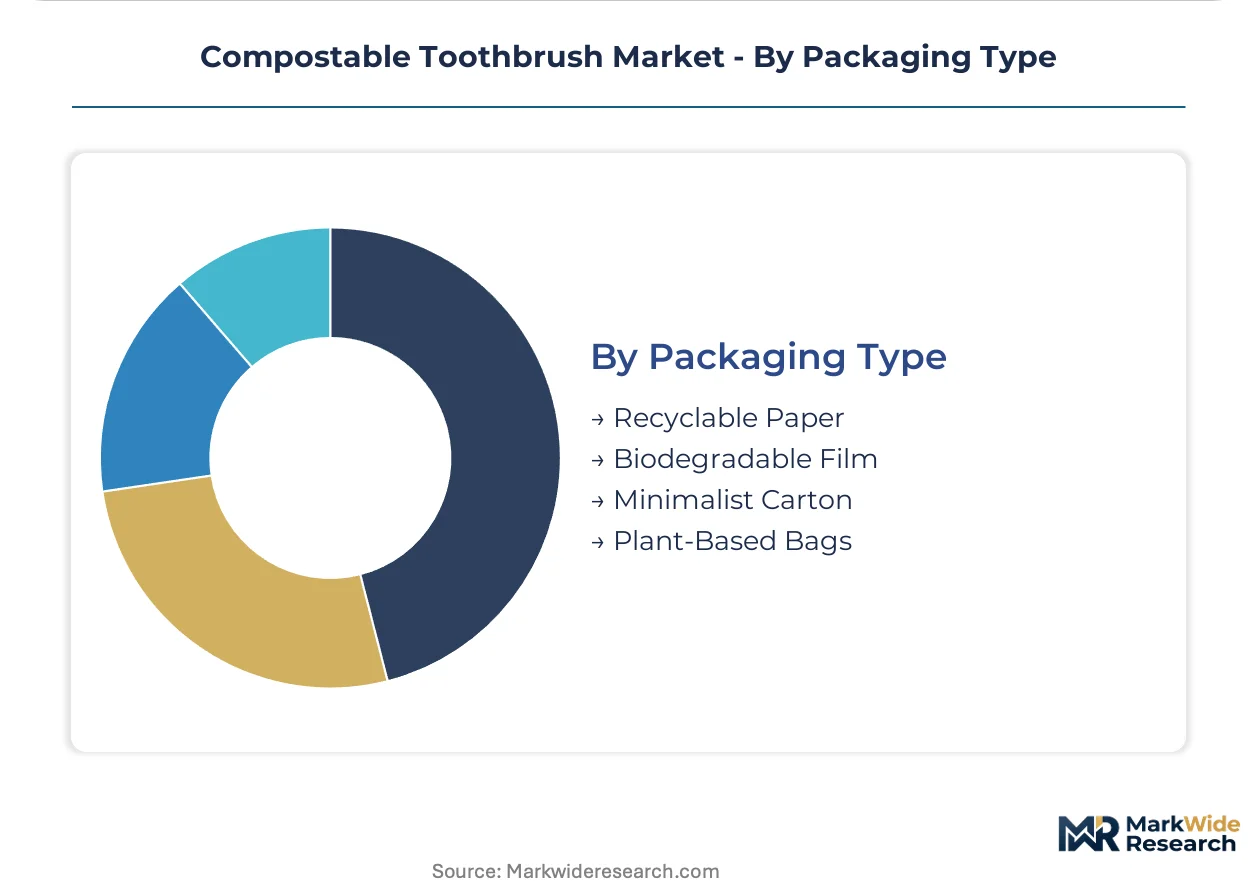
Packaging Type:
Supply concentration in paper and film converting operations shapes regional packaging availability, with minimalist carton designs gaining traction where retail shelf space commands premium positioning fees.
- Minimalist Carton:Unbleached kraft paperboard with soy-based inks eliminates plastic window films and satisfies zero-waste retailer requirements. German eco-retailers and Scandinavian pharmacy chains specify this format for shelf placement.
- Recyclable Paper:Post-consumer recycled content cartons align with EU Green Deal circular economy objectives and support corporate sustainability reporting for hospitality procurement teams.
- Biodegradable Film:Cellulose and PLA-based transparent windows maintain product visibility while achieving home compostability certification.
- Plant-Based Bags:Seaweed and cornstarch-derived flexible packaging serves bulk and travel-size product formats in online retail and subscription channels.
Recyclable paper retains volume leadership; minimalist carton holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for compostable oral care, handling containerized bamboo fiber shipments from Zhejiang Province while connecting to Rhine-Ruhr industrial composting networks. This maritime-logistics nexus underwrites Germany's concentration of certified compostable toothbrush demand.
Germany
Municipal composting infrastructure density in North Rhine-Westphalia and Bavaria drives verified end-of-life processing demand. The EU Green Deal's REACH framework bans petroleum-based polymers in consumer goods sold across member states. Cologne and Munich anchor pharmacy and eco-retail distribution channels for OK Compost HOME certified products.
United States
FDA safety standards for oral care devices shape formulation compliance thresholds while Pacific Northwest bamboo cultivation supports domestic fiber sourcing. The EPA's emerging sustainable materials management priorities influence municipal procurement guidelines. Seattle and Portland manufacturing clusters supply hospitality amenity programs seeking plastic-free certifications.
India
BIS certification requirements for imported compostable consumer goods create compliance barriers that reward first-mover domestic manufacturers. The country's PLI scheme for advanced materials indirectly supports bio-polymer research. Maharashtra and Gujarat pharmaceutical hubs drive pharmacy channel expansion for certified oral care products.
United Kingdom
Post-Brexit regulatory divergence from EU REACH standards creates dual certification requirements for cross-channel trade. The Environment Agency's waste hierarchy enforcement pressures hospitality procurement toward verified compostable amenities. London and Southeast England concentrate eco-retail and subscription service headquarters.
Sweden
Municipal sustainability mandates cascade through franchise hotel operator requirements, consolidating vendor relationships around single-source compostable amenity contracts. The Swedish Chemicals Agency's microplastic restrictions exceed EU baseline standards. Stockholm anchors Nordic pharmacy chain procurement for home-compostable oral care.
Compostable Toothbrush Market Vendor Landscape
Listed leaders compete with private specialists across certification credibility and supply chain transparency dimensions. The market structure splits between mass-market incumbents with conventional oral care shelf dominance and venture-backed specialists with direct-to-consumer subscription models. Three archetypes dominate: bamboo-focused agricultural integrators, bio-polymer technology licensors, and hospitality procurement consolidators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing captive fiber supply and certification body co-development agreements.
Within the bamboo-integrated tier, Brush with Bamboo and Humble Group exemplify divergent geographic strategies. Brush with Bamboo anchors Pacific Northwest manufacturing with controlled agricultural sourcing. Humble Group occupies a position emphasizing European pharmacy and eco-retail channel density. Colgate-Palmolive represents the incumbent archetype, leveraging existing retail shelf relationships to introduce certified compostable line extensions alongside conventional portfolios.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Brush with Bamboo |
| Humble Group |
| Bam&Boo |
| Georganics Company |
| WooBamboo |
| Mabboo Company |
| Bambrush |
| Environmental Toothbrush |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Pacific Northwest bamboo fiber mills and Zhejiang Province processing facilities shapes both supply concentration and price floors for compostable toothbrush manufacturers. High-volume production runs at these agricultural bases enable per-unit cost advantages that smaller cornstarch converters cannot match, while underutilized capacity in emerging biopolymer facilities keeps premium-tier pricing elevated.
Pricing Analysis
Volume-discount tiering structures separate hospitality procurement contracts from household retail channels, with three-tier pricing stratification across premium castor-oil bristle variants, standard bamboo handles, and economy cornstarch alternatives. Certification grade—specifically BPI versus OK Compost HOME verification—drives price differentiation alongside brand premium recognition. Cost compression in the economy tier intensifies as petroleum-based plastic converters enter with modified injection-molding equipment. Dental clinic procurement shows least price sensitivity due to professional recommendation authority, while eco-store retail channels face acute margin pressure from minimalist packaging requirements.
Supply Chain Analysis
Inventory lead times extending 12-18 months for ISO 17088 and ASTM D6400 certification create working capital traps that favor established manufacturers with balance sheet depth. Raw material flows draw from Pacific Northwest bamboo cultivation, Zhejiang Province cellulose processing, and Indian castor bean plantations for nylon-11 feedstock. Single-source vulnerability concentrates in Zhejiang agricultural bases exposed to climate-driven harvest volatility. Distribution runs through Port of Hamburg container terminals connecting to Rhine-Ruhr industrial composting networks, with Seattle and Portland anchoring North American hospitality amenity logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostable toothbrush demand tracks cyclical recovery patterns tied to EU Green Deal enforcement waves, with each regulatory tightening cycle triggering procurement mandate cascades through hospitality and retail channels.
For Market Incumbents: Secure captive bamboo fiber supply through long-term agricultural offtake agreements with Pacific Northwest and Zhejiang Province growers to defend against emerging cornstarch converters exploiting injection-molding compatibility. Accelerate OK Compost HOME certification co-development with European verification bodies before REACH authorization timelines compress competitor entry windows. For New Entrants and Emerging Players: BIS certification fast-track pathways in India create first-mover positioning in pharmacy and modern trade channels where import compliance thresholds filter established competitors. Target underdeveloped Southeast Asian eco-retail networks with minimalist carton packaging formats that bypass German shelf-space concentration. Launch direct-to-consumer subscription models capturing recurring revenue and customer relationship data. For Investors and Strategic Acquirers: Bio-polymer technology licensors with castor-oil-derived nylon-11 patents and Indian agricultural integration offer acquisition profiles aligned with hospitality procurement consolidation toward single-source amenity contracts. Monitor Nordic municipal sustainability mandate adoption rates as inflection indicators for vendor relationship consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Fiber | Pacific Northwest and Zhejiang agricultural offtake agreements secure raw material cost stability against climate volatility. |
| OK Compost HOME Certification Investment | German eco-retailers and Scandinavian pharmacy chains delist non-certified products, creating shelf-access moats. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass wholesale markups while capturing brush replacement interval data. |
| Cornstarch Injection-Molding Conversion | Conventional plastic toothbrush equipment retrofit reduces capital barriers for economy-tier volume production. |
| Hospitality Amenity Contract Consolidation | Nordic franchise operators cascade municipal mandates through multi-year bundled supply agreements. |
Methodological Framework
A spread of perspectives from hotel procurement directors, pharmacy category managers, bamboo fiber agricultural cooperatives, and composting facility operators converged on the working assumptions shaping this analysis. Primary interviews with sustainability certification body technical directors and oral care device regulatory consultants combined with secondary validation from EU Green Deal implementation reports, BPI and OK Compost certification registries, and REACH authorization databases. Customs records from Port of Hamburg and Pacific Northwest export terminals anchored trade flow analysis. Bottom-up production capacity tallies and top-down demand modeling from hospitality procurement surveys triangulated volume estimates.
Segmentation dimensions modeled include material composition tier, end-user procurement archetype, distribution channel structure, and packaging format across the projection horizon. CAGRs derived from fitted growth curves incorporating regulatory enforcement timelines, municipal composting infrastructure buildout rates, and material substitution elasticity parameters. Forecast inputs weighted Indian BIS certification pathway velocity, German industrial composting network density, and castor-oil nylon-11 production capacity expansion.
Underlying assumptions cover REACH authorization adherence, Pacific Northwest agricultural yield stability, and hospitality procurement mandate adoption, with deviation risk concentrated in certification standard fragmentation between industrial and home composting protocols. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Hand Massager Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Pre-Shave Products Market