
 Global Mosquito Repellent Products Market | 2026-2036
Global Mosquito Repellent Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mosquito Repellent Products Market Outlook
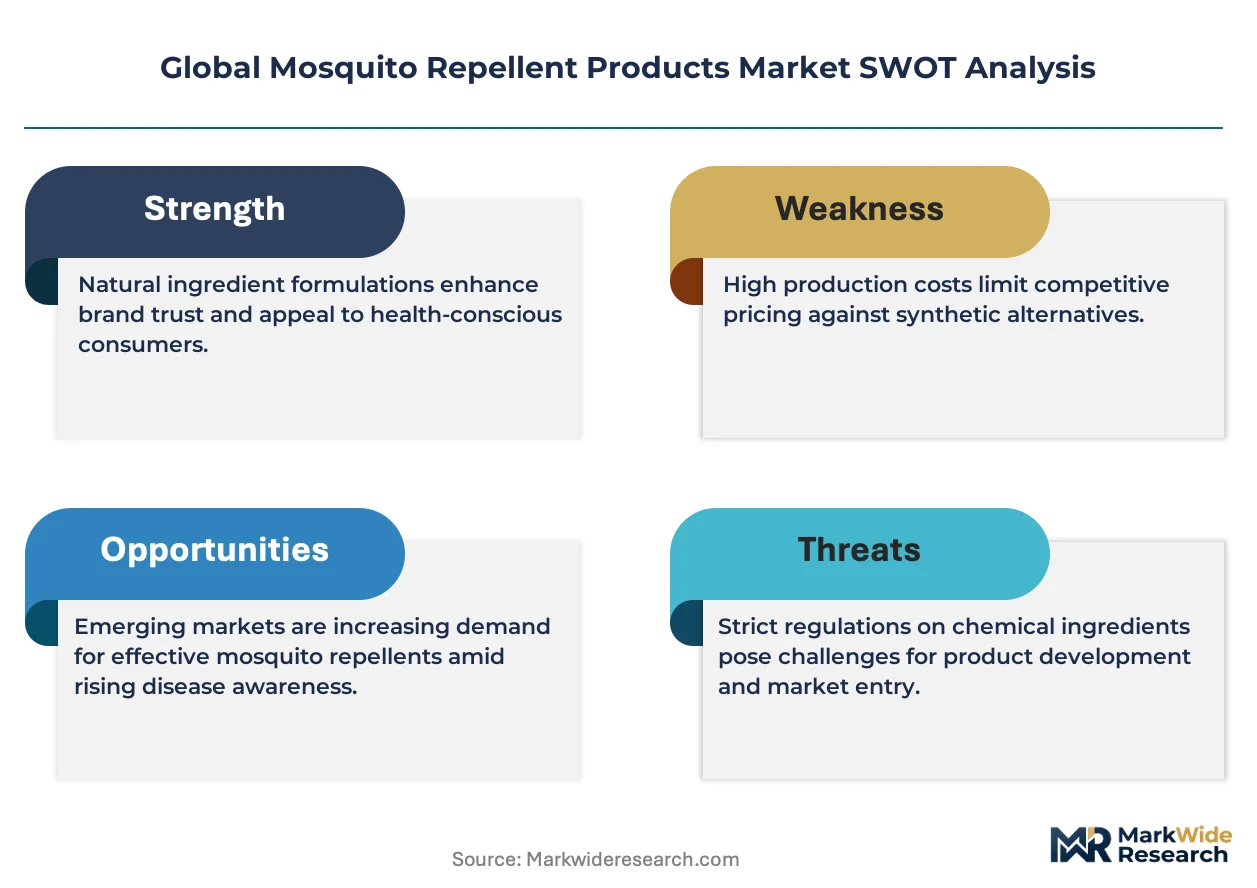
Asset-light contract manufacturing and third-party formulation licensing is fragmenting competitive barriers in mosquito repellent production. S.C. Johnson & Son, Inc. anchors North American retail shelf presence through proprietary polymer-based slow-release technology. Reckitt Benckiser Group plc leverages dual-brand architecture across premium and mass channels in emerging markets. Godrej Consumer Products Ltd. dominates South Asian distribution through deep rural penetration and sachet-format affordability.
Mosquito repellent products encompass topical, spatial, and fabric-applied formulations engineered with active concentrations typically ranging from 10% to 30% DEET or synthetic pyrethroid analogs, designed to interfere with arthropod olfactory receptors and reduce human-vector contact. The category serves residential, commercial hospitality, military, and outdoor recreation sectors where vector-borne disease transmission risk or nuisance biting degrades human activity. Spray formats lead volume globally due to immediate efficacy perception and established application habits among households. Oil of Lemon Eucalyptus and IR3535 segments are capturing fastest growth as EPA-registered botanical alternatives attract ingredient-conscious consumers in the United States and European Union markets. Mosquito mats sustained by electric vaporizer penetration in East Asian and Southeast Asian households represent a mature margin pool with limited innovation velocity.
EPA registration requirements under FIFRA govern active ingredient efficacy claims and label instructions in the United States, while the EU Biocidal Products Regulation mandates comprehensive substance dossiers and product authorization across member states. India's Central Insecticides Board enforces registration protocols under the Insecticides Act that govern import, manufacture, and sale of repellent formulations containing synthetic actives. Stakeholders must monitor evolving residue limit standards and botanical claim substantiation requirements as regulatory divergence between major markets intensifies compliance complexity.
Market Dynamics
Regulatory divergence between the EPA's FIFRA registration timelines and the EU Biocidal Products Regulation is fragmenting formulation standards and forcing manufacturers to maintain parallel R&D streams for identical active ingredients.
Growth Catalysts
- Vector-borne disease resurgence:Dengue and malaria outbreaks in Brazil's Amazon-adjacent municipalities and India's monsoon-prone states sustain year-round household purchasing and institutional procurement cycles.
- Electric vaporizer penetration:Mosquito mats sustained by established appliance ownership in East Asian and Southeast Asian households generate recurring refill demand with minimal customer acquisition cost.
- Botanical ingredient registration:Oil of Lemon Eucalyptus and IR3535 gaining EPA registration as biopesticide alternatives attracts ingredient-conscious consumers seeking DEET alternatives in United States and European Union markets.
Market Restraints
- Synthetic pyrethroid input volatility:Active ingredient costs fluctuate with petrochemical feedstock prices and Chinese manufacturing capacity constraints, compressing margin predictability for spray-format producers.
- Registration timeline friction:EU Biocidal Products Regulation substance dossier requirements extend product authorization cycles to 18-24 months, delaying market entry for reformulated actives.
- Residual efficacy limitations:Botanical alternatives demonstrate shorter protection duration versus synthetic pyrethroids, creating performance perception gaps in high-transmission settings.
Strategic Opportunities
- Rural sachet penetration:India's tier-3 and tier-4 towns remain underpenetrated by organized retail, offering volume expansion through kirana store networks and micro-distribution partnerships.
- Outdoor hospitality procurement:Campsite operators and event venues represent emerging bulk purchasers of spatial repellent systems ahead of seasonal demand peaks.
- Polymer-based slow-release convergence:Combination of microencapsulation technology with wearable formats enables premium positioning in military and expedition segments.
Industry Challenges
- Reformulation talent scarcity:Toxicologists and entomologists with dual expertise in botanical chemistry and regulatory submission protocols command premium compensation, constraining mid-tier manufacturer capabilities.
- Cross-border label harmonization:Divergent residue limit standards between EPA, ECHA, and India's Central Insecticides Board force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mosquito Repellent Products Market |
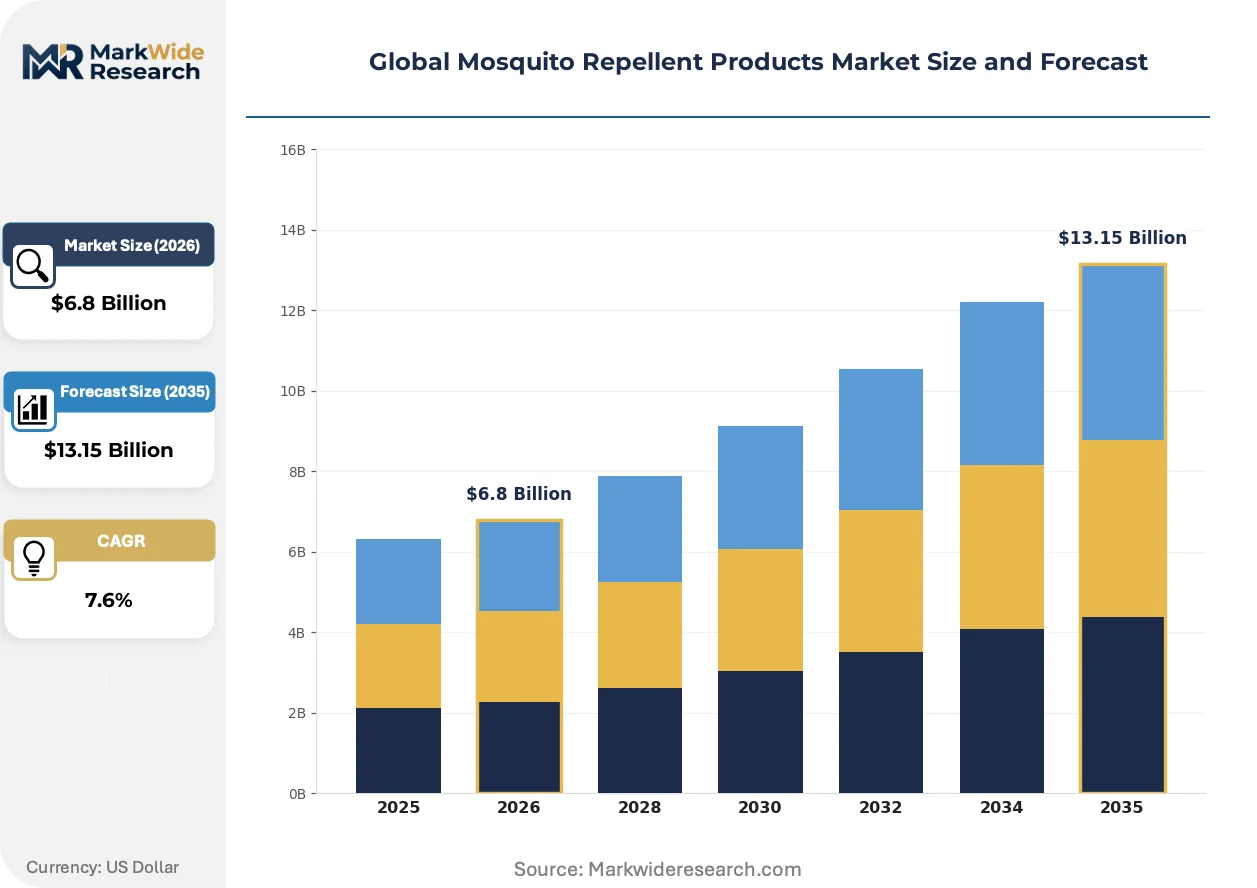
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Lotion, Insecticide Coatings, Mosquito Mats Active Ingredient: DEET, Picaridin, Oil of Lemon Eucalyptus, IR3535 End User: Households, Commercial, Outdoor Events, Campsites Packaging Type: Aerosol Cans, Bottles, Wipes, Sachets |
| Companies Covered | S.C. Johnson & Son, Inc., Reckitt Benckiser Group plc, Spectrum Brands Holdings Inc., Godrej Consumer Products Ltd., Dabur India Ltd., 3M Company, Henkel AG & Co. KGaA, Bayer AG, Thermacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mosquito Repellent Products Market Strategic Shifts
Formulation science is pivoting toward controlled-release architectures and botanical efficacy validation, while distribution models adapt to direct procurement by institutional buyers.
Microencapsulation technology is virtualizing traditional topical application by embedding actives in polymer matrices that extend protection duration from hours to days. Military and expedition gear manufacturers are adopting licensed formulations at accelerated pace. This virtualization compresses reapplication frequency expectations and shifts consumer value perception toward convenience metrics over immediate efficacy signaling.
ECHA's updated guidance on biocidal product family definitions is narrowing equivalence claims for spatial repellent devices. Manufacturers must now submit separate dossiers for plug-in versus battery-operated vaporizer formats. The electric mat segment in Germany and France faces accelerated compliance costs as legacy registrations expire under tightened substance evaluation protocols.
Institutional procurement by outdoor event operators and hospitality chains is consolidating volume previously fragmented through retail channels. Bulk purchasing agreements now specify efficacy duration guarantees and residue-free operation requirements. This concentration is most visible in Australia's Gold Coast tourism corridor and Brazil's Pantanal eco-lodge clusters.
Global Mosquito Repellent Products Market Segmentation
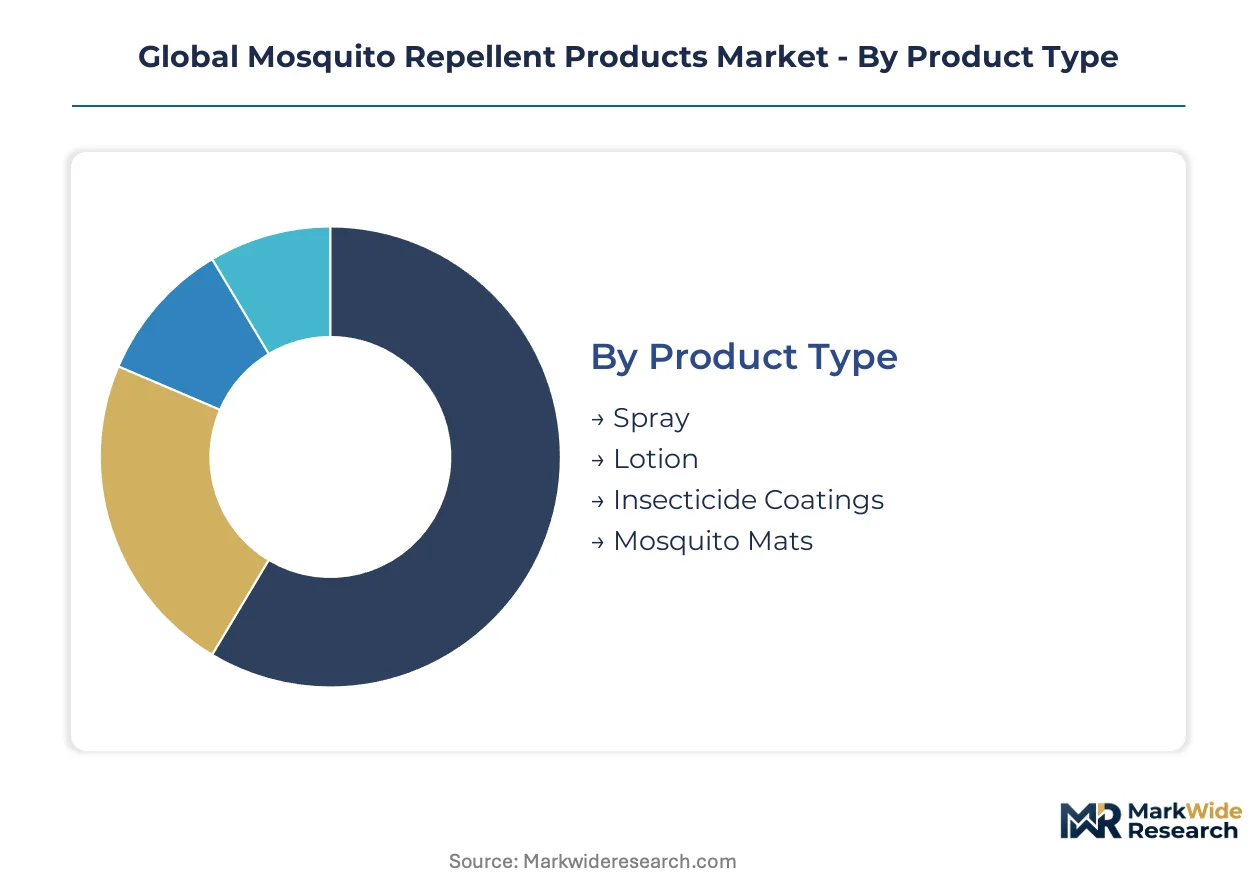
Mosquito repellent manufacturers configure product portfolios across four intersecting dimensions. Each dimension carries distinct margin profiles, regulatory pathways, and distribution requirements that determine competitive positioning.
Product Type:
Application format determines efficacy perception, reapplication frequency, and channel economics across residential and institutional buyers.
- Spray:Aqueous or alcohol-based formulations deliver immediate coverage with 10-30% active concentration. Volume concentrates in Brazil's Amazon-adjacent municipalities and India's monsoon-prone states where vector-borne disease incidence sustains year-round household purchasing cycles.
- Lotion:Emulsion-based systems with polymer binders extend skin adherence duration. Demand clusters in military and expedition segments where reapplication access is limited and protection continuity carries operational weight.
- Insecticide Coatings:Permethrin-impregnated fabrics for apparel and gear. Outdoor hospitality procurement is expanding ahead of seasonal peaks.
- Mosquito Mats:Electric vaporizer refills with synthetic pyrethroid actives. East Asian and Southeast Asian households sustain recurring demand through established appliance ownership.
Spray holds installed capacity. Lotion is rotating up the share rankings.
Active Ingredient:
Regulatory registration status and consumer ingredient consciousness are fragmenting formulation strategies across geographies.
- DEET:N,N-diethyl-meta-toluamide at 10-30% concentration remains the reference standard for duration and spectrum. EPA registration under FIFRA governs label claims in the United States, while India's Central Insecticides Board enforces parallel protocols.
- Picaridin:Synthetic piperidine derivative with comparable efficacy and improved cosmetic feel. European Union markets under ECHA's Biocidal Products Regulation show faster authorization velocity versus botanical alternatives.
- Oil of Lemon Eucalyptus:Botanical extract with EPA biopesticide registration. Ingredient-conscious consumers in the United States and European Union markets are expanding the addressable base for DEET alternatives.
- IR3535:Ethyl butylacetylaminopropionate with established EU BPR authorization. Reformulation cycles are accelerating as manufacturers seek botanical positioning without residual efficacy penalties.
DEET maintains formulation heritage. Oil of Lemon Eucalyptus is climbing the fastest.
End User:
Customer type dictates volume scale, pricing tolerance, and procurement modality across retail and direct channels.
- Households:Individual consumers purchasing through retail and e-commerce. Sachet-format affordability dominates rural India through kirana store networks.
- Commercial:Hospitality and healthcare facilities with standardized procurement protocols. Australia's Gold Coast tourism corridor shows concentrated institutional demand.
- Outdoor Events:Temporary venue operators requiring spatial coverage systems. Bulk purchasing agreements now specify efficacy duration guarantees.
- Campsites:Permanent and seasonal recreation facilities. Brazil's Pantanal eco-lodge clusters represent emerging volume concentration.
Households anchor volume throughput. Outdoor Events is gaining share fastest.
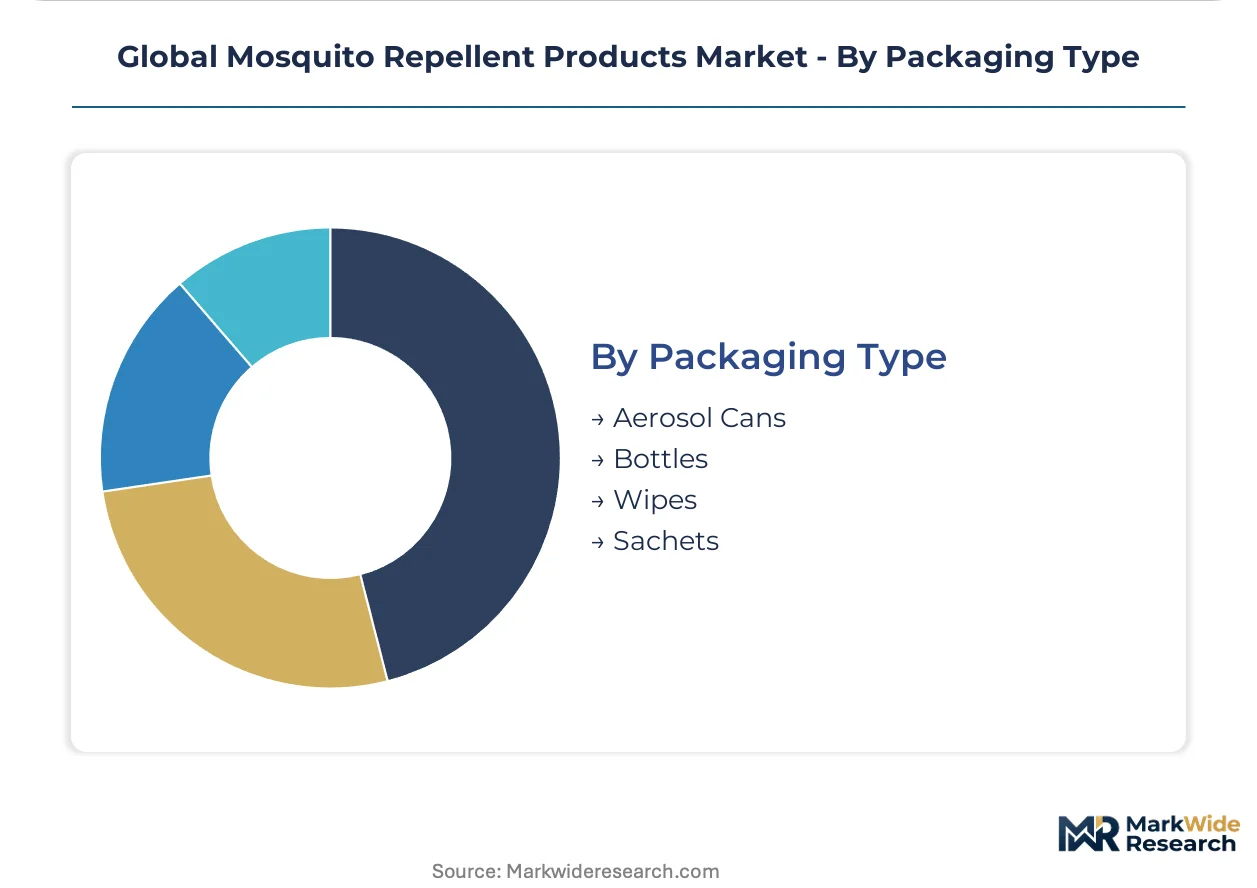
Packaging Type:
Container format determines distribution economics, usage occasion, and geographic penetration feasibility.
- Aerosol Cans:Pressurized delivery systems with immediate dispersion. Manufacturing concentrates where metal packaging supply chains and propellant regulations align.
- Bottles:Pump and trigger formats for lotion and spray formulations. Standard packaging across mass retail channels globally.
- Wipes:Nonwoven substrates pre-saturated with active solution. Military and travel segments favor portability and controlled dosing.
- Sachets:Single-use flexible pouches at price points accessible to tier-3 and tier-4 towns. Godrej Consumer Products Ltd. leverages deep rural penetration through micro-distribution partnerships.
Bottles hold format dominance. Sachets is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in mosquito repellent actives tilt toward Asian manufacturing hubs supplying formulation facilities in the Americas and Europe. Brazil and India run structural deficits in synthetic pyrethroid inputs, sourcing concentrated actives from Chinese chemical processors. Finished goods trade routes reflect divergent regulatory approval timelines, with EU-authorized formulations re-exported to African and Middle Eastern markets lacking domestic registration capacity.
United States
EPA registration under FIFRA governs label claims for DEET and botanical alternatives, with Oil of Lemon Eucalyptus gaining biopesticide status. The agency's updated ingredient review timelines are compressing reformulation cycles for domestic manufacturers. Procurement concentrates in Florida and Texas coastal counties where vector surveillance programs trigger seasonal household purchasing surges.
Brazil
Amazon-adjacent municipalities sustain year-round demand through dengue outbreak patterns and municipal vector control contracting. ANVISA enforces parallel registration protocols for imported actives, creating friction for Asian suppliers. São Paulo state's industrial corridor hosts blending facilities serving Latin American re-export markets.
Germany
ECHA's Biocidal Products Regulation mandates substance dossiers extending authorization cycles to 18-24 months for spatial repellent devices. The electric mat segment faces accelerated compliance costs as legacy registrations expire. Industrial formulation activity clusters in North Rhine-Westphalia's chemical processing belt.
India
Monsoon-prone states drive household purchasing through kirana store networks and sachet-format affordability. The Central Insecticides Board enforces registration under the Insecticides Act governing synthetic active imports. Godrej Consumer Products Ltd. anchors rural distribution through micro-distribution partnerships in Maharashtra and Gujarat.
China
Domestic manufacturers supply concentrated pyrethroid actives to Brazilian and Indian formulation facilities. NMPA and MEE oversight of chemical processing capacity constrains export volumes during environmental compliance inspections. Yangtze River Delta chemical parks concentrate active ingredient synthesis for global repellent supply chains.
Global Mosquito Repellent Products Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: multinational consumer goods conglomerates with polymer-based slow-release technology, regional specialists exploiting kirana store penetration and sachet economics, and contract manufacturers serving institutional procurement channels. Strategic archetypes include proprietary technology licensors, rural distribution aggregators, and military-specification suppliers. Dominant competitive moves encompass portfolio diversification into botanical alternatives and geographic expansion through third-party formulation licensing.
Among North American technology anchors, S.C. Johnson & Son, Inc. exemplifies the proprietary formulation tier, while Reckitt Benckiser Group plc occupies a position bridging premium and mass channels. Godrej Consumer Products Ltd. represents the rural penetration archetype within South Asian markets. These three entities collectively illustrate the competitive divergence between technology-driven positioning and distribution-depth strategies.
| Leading Market Players |
|---|
| S.C. Johnson & Son, Inc. |
| Reckitt Benckiser Group plc |
| Spectrum Brands Holdings Inc. |
| Godrej Consumer Products Ltd. |
| Dabur India Ltd. |
| 3M Company |
| Henkel AG & Co. KGaA |
| Bayer AG |
| Thermacell |
| Others |
Value Chain & Pricing Dynamics
Chinese pyrethroid concentrate manufacturers anchor upstream supply, concentrating margin capture in formulation and branded distribution tiers downstream. Synthetic active ingredient costs fluctuate with petrochemical feedstock volatility, compressing margin predictability for spray-format producers while electric vaporizer refill systems sustain recurring revenue pools.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across military and expedition gear procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates polymer-based slow-release formulations from conventional sprays and sachet-format mass-market products. Cost compression in standard-tier sprays is intensifying because of synthetic pyrethroid input volatility from Chinese manufacturing capacity constraints. Rural households in India's tier-3 and tier-4 towns exhibit highest price sensitivity, while military-specification suppliers demonstrate lowest sensitivity due to operational continuity requirements.
Supply Chain Analysis
Extended payment terms from Brazilian and Indian formulation facilities to Chinese active ingredient suppliers have become standard operating practice, stretching working capital cycles. Geographic supply concentration centers on China for pyrethroid synthesis, India for formulation and packaging, and Brazil for Latin American re-export blending. Raw material dependencies rest on petrochemical-derived synthetic actives, polymer microencapsulation materials, and aluminum aerosol can stock. Single-source vulnerability from Yangtze River Delta chemical park environmental compliance inspections creates periodic export volume constraints. Distribution runs through kirana store networks in rural South Asia, mass retail in North America, and direct institutional procurement for outdoor hospitality in Australia and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toxicologists and entomologists with dual expertise in botanical chemistry and regulatory submission protocols command premium compensation, constraining mid-tier manufacturer capabilities and fragmenting competitive barriers. This capability scarcity rewards early investment in cross-functional R&D teams and parallel registration track management.
For Market Incumbents: Build regulatory dossier depth as a moat against reformulation cycle acceleration. Secure backward integration into polymer microencapsulation technology to defend margin position against input cost volatility. Expand capacity addition in Maharashtra and Gujarat to deepen rural distribution control before emerging regional specialists consolidate kirana store networks. For New Entrants and Emerging Players: Establish a beachhead in Australia's Gold Coast tourism corridor where institutional procurement concentrates and brand heritage carries less weight. Target outdoor event operators and eco-lodge clusters in Brazil's Pantanal region with spatial repellent system bundles. Pursue direct-to-venue sales models bypassing retail margin extraction entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers serving institutional procurement channels with limited brand equity but established EPA and EU BPR registration portfolios. Five-to-ten year viability hinges on successful botanical alternative transition without residual efficacy penalties. Watch for ANVISA registration acceleration in Brazil as inflection indicator for Latin American market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Ingredient Registration | EPA biopesticide pathways for Oil of Lemon Eucalyptus unlock DEET-alternative positioning in ingredient-conscious segments. |
| Polymer Microencapsulation Licensing | Proprietary slow-release technology enables premium military and expedition segment penetration with extended protection claims. |
| Rural Sachet Distribution Expansion | Kirana store network penetration in India's tier-3 and tier-4 towns captures volume inaccessible to organized retail. |
| Institutional Procurement Direct Sales | Bulk agreements with outdoor hospitality operators consolidate previously fragmented retail channel volume. |
| Parallel Regulatory Track Management | Simultaneous EPA FIFRA and EU BPR dossier preparation compresses time-to-market for reformulated actives. |
Study Parameters
The analysis maps topical, spatial, and fabric-applied formulation sub-sectors, each validated through entomologists, regulatory affairs specialists at formulation facilities, procurement managers at outdoor hospitality chains, and kirana store distributors. Primary interviews combined with secondary validation from EPA registration databases, ECHA biocidal product dossiers, Indian Central Insecticides Board filings, and customs trade flow records. Bottom-up and top-down triangulation cross-checked volume estimates against active ingredient import data and finished goods retail audit patterns.
Assumptions held fixed include regulatory divergence intensity between EPA and EU authorization timelines, while petrochemical feedstock price trajectories and vector-borne disease outbreak patterns were varied across sensitivity scenarios. Segmentation dimensions modeled span application format, active ingredient type, end-user category, and packaging configuration. CAGRs were derived from installed base growth in electric vaporizer households, rural penetration velocity, and institutional procurement scaling. Industry-specific forecast inputs incorporated electric vaporizer appliance ownership rates and municipal vector control contracting cycles.
Stress conditions across synthetic pyrethroid input cost spikes, extended EU BPR authorization delays, and accelerated botanical efficacy validation requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction in emerging market purchasing power, harmonization of residue limit standards across EPA-ECHA-India regulators, or breakthrough in non-pyrethroid synthetic actives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Foot Care Products Market