
 Sneaker Deodorant Market | 2026-2036
Sneaker Deodorant Market Size, Share, and Industry Trends Forecast 2026-2036
Sneaker Deodorant Market Analytics
ISO 9235 certification for natural fragrance raw materials is redrawing competitive boundaries in sneaker deodorant formulation. S. C. Johnson & Son Inc. leverages its aerosol manufacturing infrastructure to sustain shelf presence across mass retail channels. Reckitt Benckiser Group PLC anchors its position through antimicrobial technology leadership in household hygiene extensions. Church & Dwight Co., Inc. differentiates via baking soda-based formulations that occupy the natural-ingredient positioning tier.
Sneaker deodorant encompasses topical or spray-applied formulations engineered to neutralize odor-causing bacteria, absorb moisture, or mask residual smells from athletic and casual footwear, typically incorporating active ingredients such as zinc ricinoleate, cyclodextrin complexes, or essential oil blends at concentrations between 0.5% and 5% by weight. The product category serves both hygienic maintenance and sensory enhancement functions for consumers seeking to extend footwear lifespan and wearing comfort. Aerosol spray formats dominate volume throughput due to convenience and perceived efficacy, though powder segments command margin premiums through natural-positioned ingredient stories. Antimicrobial ingredient types are gaining fastest as consumers prioritize bacterial elimination over fragrance masking, while online retail channels are capturing share from supermarkets through subscription and direct-to-athlete models.
The EPA regulates volatile organic compound content in aerosol formulations under 40 CFR Part 59, constraining propellant choices and spray delivery architectures for US-market products. REACH compliance in Europe governs fragrance allergen disclosure thresholds and restricts certain synthetic biocides, compelling reformulation cycles for exporters serving multiple jurisdictions. Stakeholders must monitor evolving biocidal product regulations under the EU BPR and state-level green chemistry initiatives in California and New York, as these frameworks will determine which active ingredient platforms retain market access across the largest addressable economies.
Market Dynamics
Antimicrobial ingredient preference is compressing fragrance-masking formulations as athletes and hygiene-conscious consumers prioritize bacterial elimination over scent coverage, forcing reformulation investments across aerosol and powder architectures.
Growth Catalysts
- Athletic Footwear Maintenance Prioritization:Organized sports participants in Germany, the United States, and Japan now treat sneaker deodorants as essential equipment care, expanding per-capita consumption beyond occasional-use patterns.
- EPA Safer Choice Program:The tightening formulation standards for household chemical products in the United States are accelerating ingredient transparency investments and creating competitive separation for early certifiers.
- Zinc Ricinoleate Complexes:Advanced odor-neutralizing chemistry at 0.5-5% weight concentration is displacing older masking agents in premium formulations targeting sneaker collectors and resale market participants.
Market Restraints
- Propellant Cost Volatility:Hydrocarbon and compressed gas propellant prices fluctuate with petrochemical feedstock markets, squeezing margin structures for aerosol-dominant product lines.
- REACH Compliance Burden:The European regulation's fragrance allergen disclosure thresholds and biocide restrictions force parallel formulation tracks for exporters serving EU versus US markets.
- Solid Bar Substitutes:Cedar blocks, activated charcoal pouches, and UV sanitizing devices compete for shelf space and consumer attention in specialty athletic retail.
Strategic Opportunities
- Subscription Direct-to-Athlete Models:Online retail channels are capturing share from supermarkets through recurring delivery programs targeting organized sports teams and individual training regimens.
- EU Biocidal Products Regulation Tailwind:Approved active substance lists under BPR Article 95 create first-mover advantages for compliant zinc-based and essential oil formulations entering European markets.
- India Organized Sports Expansion:Cricket academies, marathon training collectives, and football leagues represent underpenetrated demand for specialized footwear hygiene protocols.
Industry Challenges
- ISO 9235 Certification Timeline:Natural fragrance raw material verification requires 12-18 month documentation cycles, delaying product launches for brands pivoting to plant-based positioning.
- Cross-Jurisdiction Formulation Management:Simultaneous compliance with 40 CFR Part 59 VOC limits, REACH Annex XVII restrictions, and state-level green chemistry initiatives in California and New York fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sneaker Deodorant Market |
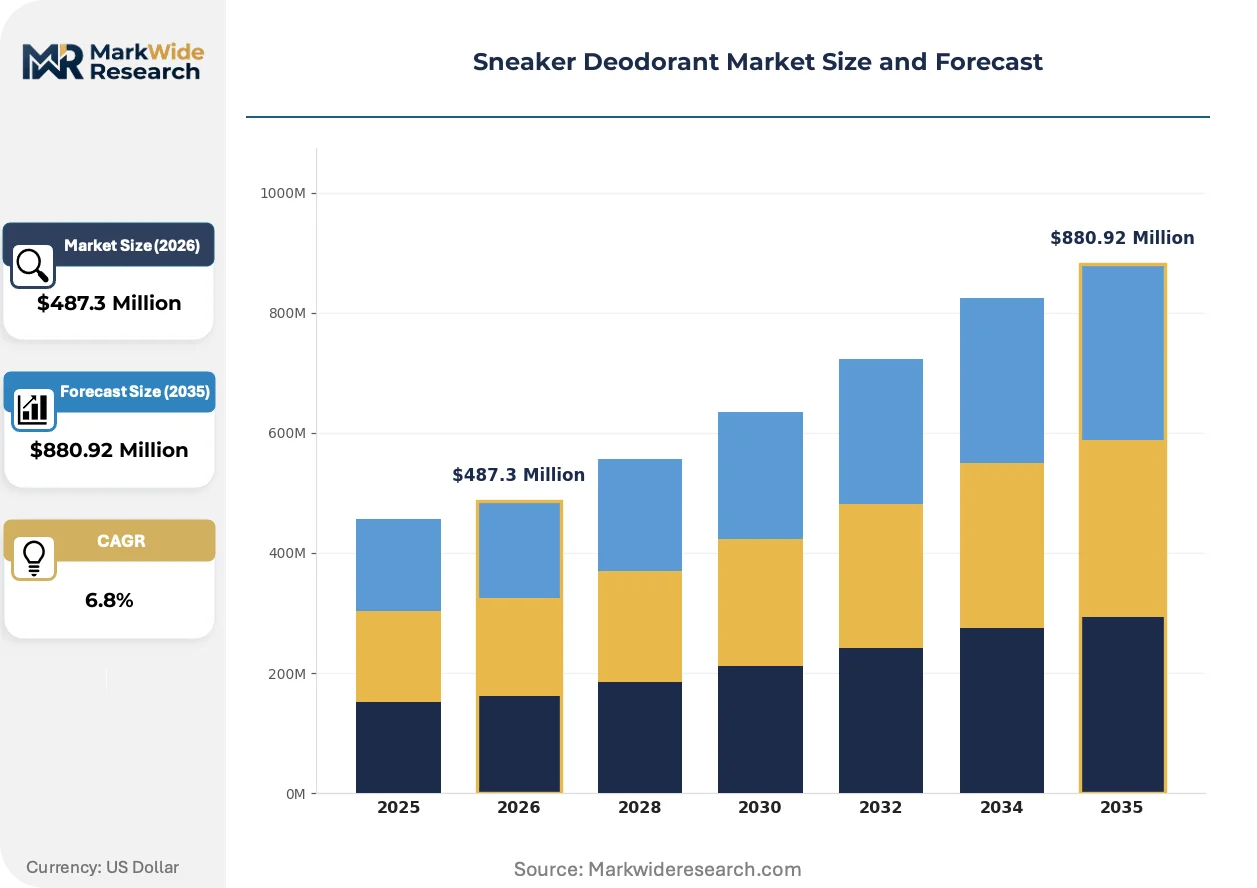
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Spray, Powder, Cream, Wipes Ingredient Type: Natural, Synthetic, Antimicrobial, Fragrance Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Athletes, Casual Users, Children, Outdoor Enthusiasts |
| Companies Covered | S. C. Johnson & Son Inc., Reckitt Benckiser Group PLC, Church & Dwight Co., Inc., Blistex Inc., Scholl’s Wellness Company, Puma SE, Procter & Gamble, Chattem Chemicals Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sneaker Deodorant Market Evolving Landscape
Formulation science and distribution architecture are diverging simultaneously as antimicrobial efficacy claims replace fragrance storytelling and direct channels bypass traditional retail gatekeepers.
Cyclodextrin inclusion complexes are fragmenting traditional encapsulation approaches in sneaker deodorant formulation. These molecular cages trap odor molecules through host-guest chemistry rather than masking with perfume overload. Athletes in competitive running and basketball programs are adopting cyclodextrin-based sprays at faster replacement cycles than general consumers. The technology is fragmenting market share concentration among legacy aerosol brands that built positioning on fragrance intensity rather than neutralization chemistry.
REACH Annex XVII amendments governing synthetic biocide restrictions are compelling reformulation investments across European-exporting manufacturers. The regulation's substance evaluation process creates approval bottlenecks for novel antimicrobial actives while grandfathering certain zinc salts. Powder-format natural-positioned products face the steepest compliance costs as they rely heavily on botanical extracts now under enhanced scrutiny. German formulators are responding fastest through early engagement with ECHA substance identification protocols.
Team and league procurement contracts are consolidating individual purchasing decisions into bulk supply agreements with specified performance metrics. Specialty running stores and soccer club equipment managers now negotiate annual deodorant supply as part of broader footwear care packages. This concentration is most visible in organized youth sports leagues across the United States and Germany where parental purchasing authority shifts to volunteer coordinators and club administrators.
Sneaker Deodorant Market Segmentation
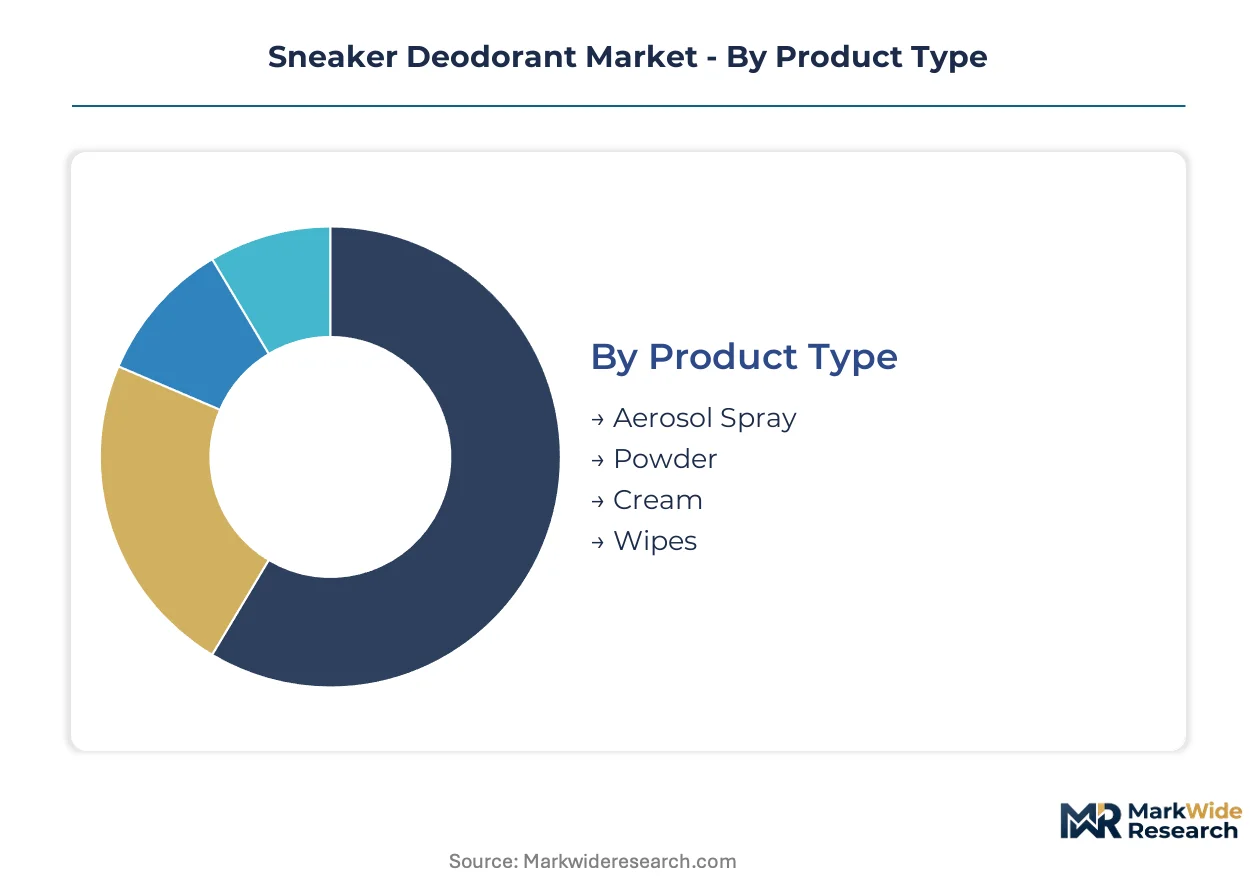
Sneaker deodorant market segmentation reveals divergent margin structures across delivery formats, ingredient platforms, and channel economics. Product type and ingredient composition determine formulation complexity and regulatory compliance costs, while distribution channel selection shapes customer acquisition economics and repeat purchase frequency.
Product Type:
Margin pools concentrate in powder formats where natural-positioned ingredient stories command price premiums, while aerosol architectures dominate absolute volume throughput.
- Aerosol Spray:Pressurized delivery systems using hydrocarbon or compressed gas propellants achieve 0.5-5% active ingredient concentration with uniform coverage. Demand concentrates among organized sports participants in Germany and the United States who prioritize convenience and perceived efficacy in high-frequency training regimens. Hydrocarbon propellant cost volatility compresses margin structures for manufacturers dependent on petrochemical feedstocks.
- Powder:Talc or starch-based carriers incorporating zinc ricinoleate or baking soda at higher loadings enable natural-ingredient positioning tiers. Sneaker collectors and resale market participants in Japan and Germany drive replacement cycles above general consumer averages. REACH Annex XVII compliance costs for botanical extracts create entry barriers for new entrants.
- Cream:Thickened emulsions targeting targeted application to insoles and interior surfaces with extended contact time.
- Wipes:Pre-moistened substrates offering portability for travel and gym bag storage, competing with liquid formats on convenience.
The dominant share belongs to Aerosol Spray, while Powder is closing the gap fastest.
Ingredient Type:
Application requirements split the category between bacterial elimination protocols favored by athletes and scent-oriented solutions targeting casual maintenance.
- Antimicrobial:Zinc salt and essential oil actives eliminate odor-causing bacteria rather than masking with fragrance overload. Competitive running and basketball programs adopt these formulations at faster replacement cycles than general consumers. EPA Safer Choice certification and EU BPR Article 95 compliance create competitive separation for early certifiers.
- Natural:Plant-derived actives and ISO 9235-certified fragrance materials serve sustainability-preferring segments in Germany and premium athletic footwear cultures. Documentation cycles spanning 12-18 months delay product launches for brands pivoting to plant-based positioning. Cyclodextrin inclusion complexes fragment traditional encapsulation approaches through host-guest chemistry.
- Synthetic:Petrochemical-derived masking agents and older encapsulation technologies facing displacement by neutralization chemistry.
- Fragrance:Perfume-forward formulations emphasizing sensory enhancement over hygienic maintenance, losing share to efficacy-focused alternatives.
Antimicrobial formulations now lead volume growth, with Natural ingredients expanding most quickly on premium positioning.
Distribution Channel:
Customer acquisition economics favor direct channels where subscription models capture recurring revenue, while mass retail maintains reach for impulse purchases.
- Online Retail:Direct-to-athlete subscription programs and marketplace presence enable recurring delivery targeting organized sports teams. Parental purchasing authority in United States and German youth sports leagues shifts to volunteer coordinators negotiating annual supply contracts. 40 CFR Part 59 VOC documentation requirements add friction for cross-border aerosol shipments.
- Specialty Stores:Running shops and soccer club equipment managers bundle deodorant supply into broader footwear care packages with specified performance metrics. Team and league procurement contracts consolidate individual purchasing decisions into bulk agreements.
- Supermarkets:Mass retail channels losing share to online alternatives, retaining occasional-use casual consumers.
- Pharmacies:Healthcare-adjacent positioning for sensitive-skin and pediatric formulations, constrained by shelf space competition.
Online Retail commands the steepest expansion trajectory, though Specialty Stores retain margin advantages through bundled service models.
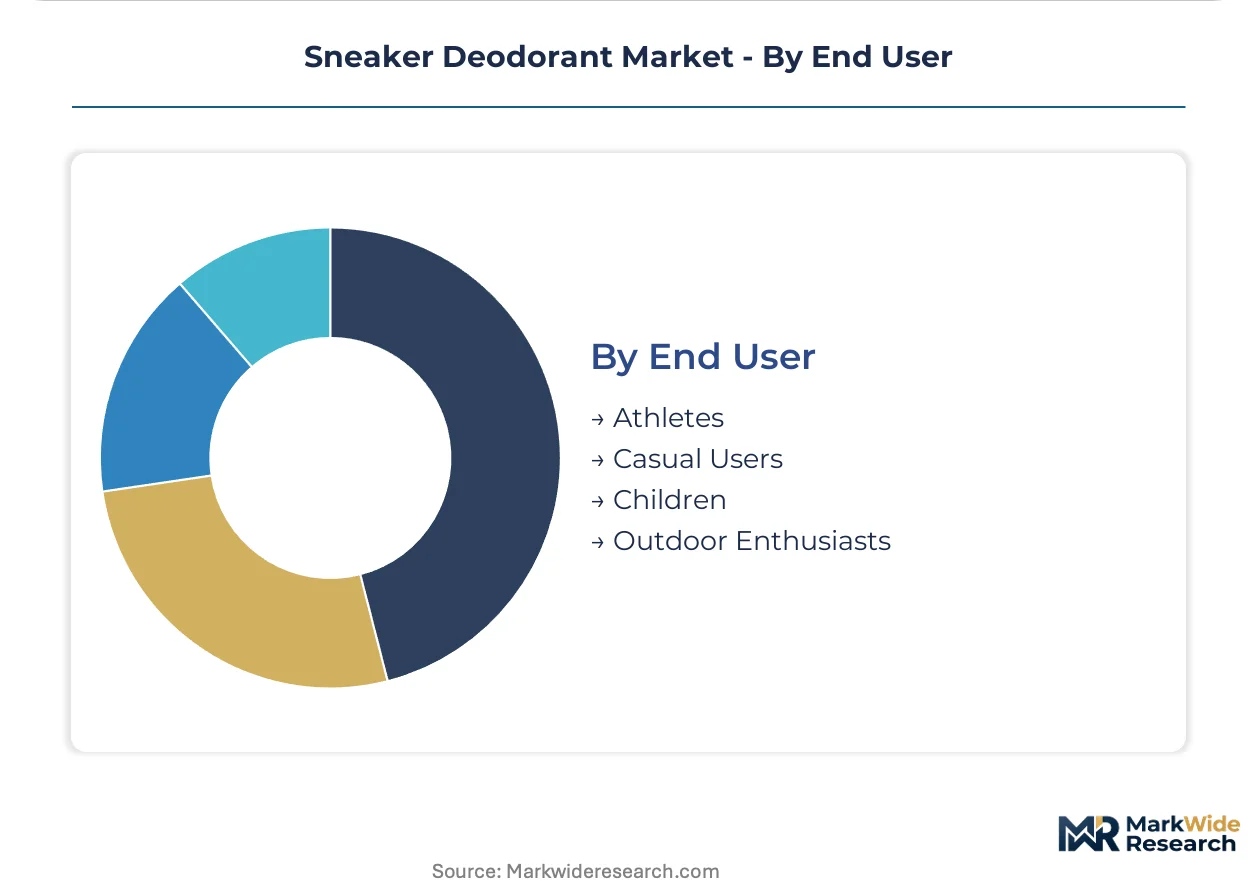
End User:
Training intensity and footwear investment levels determine per-capita consumption rates and product specification requirements.
- Athletes:Organized sports participants in cricket academies, marathon training collectives, and football leagues treat specialized footwear hygiene as essential equipment care. Per-capita consumption in Germany, the United States, and Japan exceeds occasional-use patterns through daily training regimens. Zinc ricinoleate complexes at 0.5-5% concentration displace older masking agents in premium formulations.
- Casual Users:Infrequent application patterns and price sensitivity dominate, with cedar blocks and activated charcoal pouches competing for attention.
- Children:Pediatric formulations with milder actives, parental purchasing authority concentrated in youth league procurement structures.
- Outdoor Enthusiasts:Hiking and trail running participants requiring moisture absorption in extended-wear conditions.
Athletes generate the highest per-user revenue, while Outdoor Enthusiasts represent the most underpenetrated addressable expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safer Choice certification requirements in the United States are accelerating formulation transparency investments across North America and Europe. Germany's premium athletic footwear culture and REACH compliance frameworks position it as the highest per-capita consumption market for specialized care products. India's organized sports expansion through cricket academies and marathon collectives represents the most significant underpenetrated demand vector.
United States
Organized youth sports leagues and marathon training collectives treat sneaker deodorants as essential equipment care. EPA 40 CFR Part 59 constrains volatile organic compound content in aerosol formulations, forcing propellant architecture redesigns. Greater Boston and Pacific Northwest running communities drive replacement cycles above national averages through daily training regimens.
Germany
Premium athletic footwear culture and sustainability preferences concentrate demand for ISO 9235-certified natural formulations. REACH Annex XVII fragrance allergen disclosure thresholds and biocide restrictions compel parallel formulation tracks for exporters. Bavaria's sneaker collector communities and resale market participants in Munich drive premium positioning for zinc ricinoleate complexes.
Japan
Sneaker collectors and resale market participants sustain replacement cycles above general consumer averages through footwear investment protection. METI chemical substance regulations govern antimicrobial active approvals, creating documentation bottlenecks for novel formulations. Tokyo's specialty running stores and basketball club equipment managers consolidate procurement into annual supply contracts.
India
Cricket academies, marathon training collectives, and football leagues generate underpenetrated demand for specialized footwear hygiene protocols. BIS standards for household chemical products are tightening, though enforcement lags European frameworks. Maharashtra's organized youth sports infrastructure in Mumbai and Pune represents the most concentrated addressable expansion.
United Kingdom
Marathon running clubs and football league equipment managers are adopting team procurement contracts for bulk deodorant supply. EU BPR Article 95 compliance requirements for biocidal products create competitive separation for early certifiers post-Brexit transition. London's specialty athletic retail clusters and Southeast running communities drive premium product adoption.
Sneaker Deodorant Market Competitive Landscape
Player mix skews toward diversified household hygiene conglomerates with aerosol manufacturing infrastructure and natural-positioned specialists with baking soda or essential oil platforms. Market structure concentrates around three strategic archetypes: mass-market aerosol brands leveraging retail shelf presence, premium natural-formulation specialists commanding margin premiums, and athletic-lifestyle brand extensions capturing team procurement channels. Dominant competitive moves include EPA Safer Choice certification racing and direct-to-athlete subscription model deployment.
Among diversified household hygiene conglomerates, S. C. Johnson & Son Inc., Reckitt Benckiser Group PLC, and Church & Dwight Co., Inc. represent the core competitive anchors. S. C. Johnson & Son Inc. exemplifies mass-market aerosol infrastructure deployment. Reckitt Benckiser Group PLC occupies a position within antimicrobial technology leadership. Church & Dwight Co., Inc. anchors the natural-ingredient positioning tier through baking soda-based formulation heritage. These three entities collectively demonstrate how divergent ingredient platforms and channel strategies fragment competitive positioning across convenience-oriented, efficacy-focused, and sustainability-preferring consumer segments.
| Leading Market Players |
|---|
| S. C. Johnson & Son Inc. |
| Reckitt Benckiser Group PLC |
| Church & Dwight Co., Inc. |
| Blistex Inc. |
| Scholl's Wellness Company |
| Puma SE |
| Procter & Gamble |
| Chattem Chemicals Inc. |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for hydrocarbon propellants and zinc ricinoleate feedstock lock in both supply access and price visibility for aerosol-dominant manufacturers serving EPA-regulated US markets and REACH-governed European jurisdictions. These arrangements insulate margin structures from petrochemical volatility while constraining formulation flexibility for brands pivoting to natural-positioned powder architectures.
Pricing Analysis
Certification level creates the primary spread between ISO 9235-certified natural formulations and standard aerosol tiers. Three-tier pricing structure across premium, standard, and economy levels segments by ingredient transparency and regulatory compliance depth. Pricing pressure stems from REACH Annex XVII documentation costs compressing margins on botanical extract-dependent powders. Casual users exhibit highest price sensitivity, while sneaker collectors in Germany and Japan absorb premium positioning for zinc ricinoleate complexes.
Supply Chain Analysis
Germany and the United States anchor active ingredient formulation and aerosol manufacturing infrastructure for branded household hygiene conglomerates. Propellant systems draw from petrochemical feedstock networks, while zinc salt and essential oil actives source from specialized chemical producers. Single-source vulnerability concentrates in hydrocarbon propellant supply exposed to energy market volatility. Distribution runs through mass retail chains for impulse purchases and direct-to-athlete subscription platforms for recurring revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment—EPA Safer Choice certification and EU BPR Article 95 compliance—creates asymmetric barriers against unqualified entrants. Switching costs for organized sports procurement contracts further harden incumbent positions.
For Market Incumbents: Consolidate aerosol manufacturing scale in Germany and the United States while accelerating ISO 9235 certification pipelines to defend against natural-positioned disruptors. Secure backward integration into zinc ricinoleate supply to offset propellant cost volatility. Lock in multi-year team procurement contracts with cricket academies and marathon collectives to raise replacement switching costs. For New Entrants and Emerging Players: Anchor in India's underpenetrated organized sports infrastructure, specifically Maharashtra's youth cricket leagues and Pune marathon training hubs where specialized footwear hygiene protocols remain nascent. Bypass saturated US and German mass retail through direct-to-athlete subscription models targeting parental purchasing authority in volunteer-coordinated supply structures. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier natural-formulation specialists with pending ISO 9235 documentation and established EU BPR compliance pathways. These assets offer 5-10 year viability through regulatory tailwinds displacing synthetic biocide-dependent competitors. Monitor EPA Safer Choice certification velocity as the inflection signal for margin expansion in US market access.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9235 Certification Investment | Natural fragrance verification unlocks premium positioning in Germany's sustainability-preferring segments. |
| Direct-to-Athlete Subscription Launch | Recurring delivery models capture parental procurement authority in US and German youth sports leagues. |
| EU BPR Article 95 Compliance Pathway | Early zinc-based active substance approval creates first-mover access against delayed botanical extract competitors. |
| Backward Integration into Zinc Ricinoleate Supply | In-house active ingredient production insulates margin compression from petrochemical feedstock volatility. |
| Team Procurement Contract Consolidation | Bulk supply agreements with cricket academies and marathon collectives lock in replacement cycle predictability. |
Research Methodology
Desk research of customs trade records, EPA 40 CFR Part 59 regulatory filings, and ECHA substance identification protocols preceded structured interviews with aerosol manufacturing plant managers, formulation R&D directors at household hygiene conglomerates, procurement leads at specialty running retailers, and volunteer coordinators in US youth sports leagues. Bottom-up demand modeling triangulated against top-down market sizing from trade association data and company SEC disclosures.
Variance decomposition across product type, ingredient platform, distribution channel, and end-user training intensity shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level replacement cycle analysis, regulatory compliance cost trajectories, and procurement contract consolidation patterns. Cyclodextrin inclusion complex adoption curves and zinc ricinoleate displacement rates informed technology transition assumptions.
Decision-makers should treat outputs as directional under sustained EPA Safer Choice enforcement and REACH Annex XVII amendment continuity; material deviation in biocidal product approval timelines or propellant cost volatility would warrant model refresh. Recalibration cycles align with material shifts in EU BPR substance evaluation outcomes and organized sports participation rates in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Electrical Neck Warmer Market