
 Europe Electric Toothbrush Market | 2026-2036
Europe Electric Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Toothbrush Market Intelligence
Young professionals and tech-engaged adults are redrawing demand patterns across Europe, displacing traditional family-centric purchasing as the dominant buyer archetype. Koninklijke Philips N.V. leverages its connected oral health ecosystem to sustain premium positioning in German and British retail channels. Procter & Gamble Company competes through mass-market scale and pharmacy shelf dominance across Southern Europe. Colgate-Palmolive Company anchors its position via dentist endorsement programs that build professional trust in France and Italy.
Europe electric toothbrush denotes a motorized dental hygiene device employing oscillating-rotating or sonic vibration mechanisms, typically operating at frequencies between 20,000 and 62,000 brush movements per minute, designed to reduce plaque and gingivitis more effectively than manual brushing. Sonic and ultrasonic product types command the widest margin pools as consumers trade up for pressure sensors and Bluetooth connectivity features. The adult end user segment remains structurally mature while caregiver-directed purchases for seniors represent the fastest-growing demand pocket. Online distribution channels are displacing supermarkets as the primary volume pathway, though pharmacies retain outsized influence in Mediterranean markets where clinician recommendations drive trial.
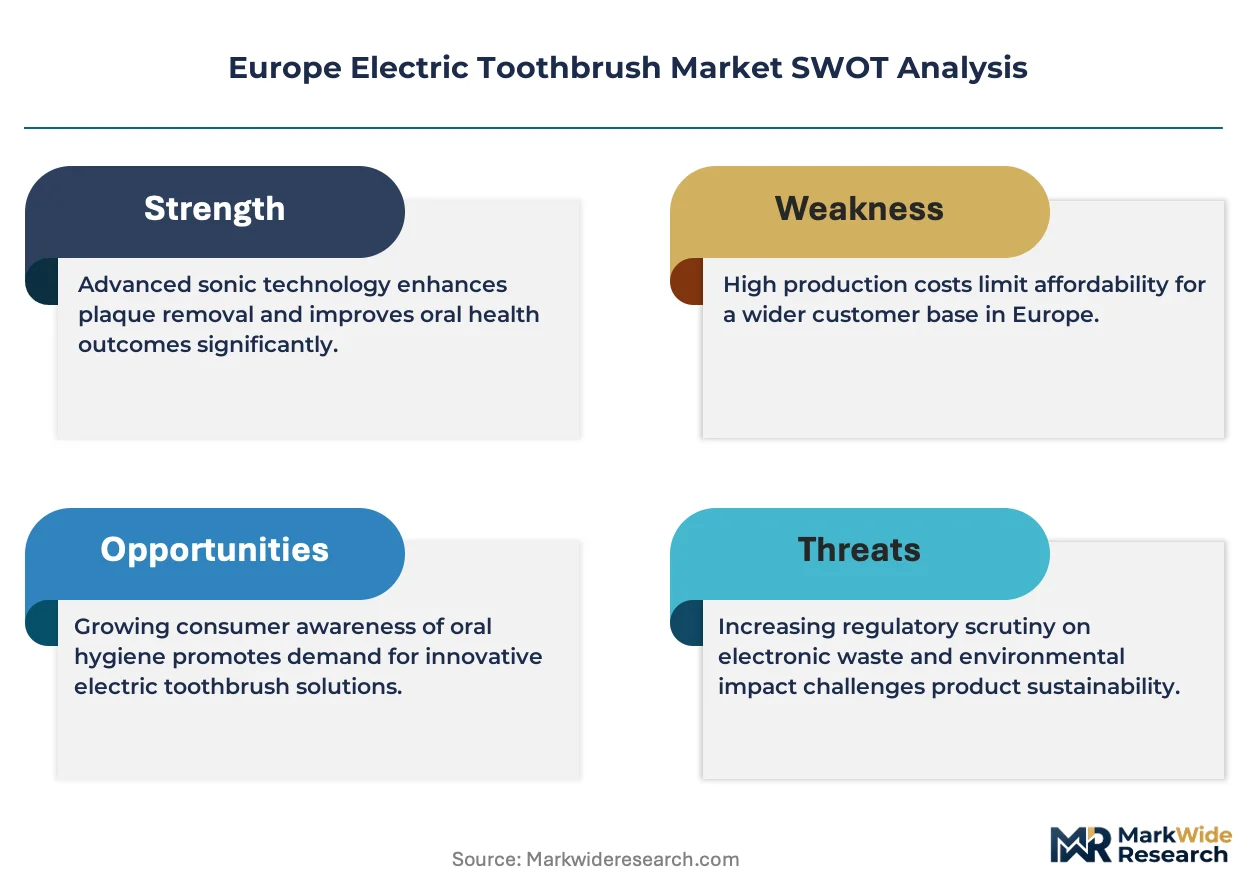
CE marking requirements under the EU Medical Devices Regulation govern product safety claims and electrical standards for rechargeable units sold across member states. France's ANSM and Germany's BfArM maintain national vigilance systems that track adverse events and shape post-market surveillance obligations for manufacturers. REACH compliance and the EU Green Deal's packaging directives are elevating material transparency requirements and recyclability mandates. Stakeholders must monitor how evolving EPR schemes and national eco-modulation fees reshape cost structures and competitive positioning in the years ahead.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing manufacturers to redesign brush head architectures and supply chains around recyclability mandates, compressing margin structures while elevating compliance costs as a competitive differentiator.
Growth Catalysts
- EU Medical Devices Regulation (MDR):CE marking requirements under the MDR elevate safety standards for rechargeable units, filtering out low-quality imports and consolidating shelf space for compliant manufacturers in German and French retail channels.
- Bluetooth connectivity modules:Integration of pressure sensors and real-time brushing feedback is pulling tech-engaged millennials toward premium sonic devices with subscription brush head replenishment models.
- France and Italy:Dentist endorsement programs carry disproportionate consumer trust weight, creating professional channel pull-through that accelerates trial among oral health-conscious households.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on East Asian cell manufacturers creates input cost volatility and geopolitical exposure for European assembly operations.
- REACH compliance costs:Material transparency requirements for plastics and electronic components elevate R&D expenditure and extend product development timelines.
- Manual brush substitution persistence:Price-sensitive consumer segments in Southern and Eastern Europe continue to resist motorized solutions despite proven efficacy differentials.
Strategic Opportunities
- Caregiver-directed senior purchases:Aging demographics in Germany and the United Kingdom create demand pockets for ergonomically designed devices with grip assistance and simplified interfaces.
- Extended Producer Responsibility (EPR) schemes:Evolving national eco-modulation fees reward early movers in recyclable brush head design with reduced compliance levies.
- Online pharmacy integration:Digital health platforms in the Netherlands and Scandinavia enable subscription-based oral health monitoring tied to insurance incentive programs.
Industry Challenges
- Post-market surveillance obligations:France's ANSM and Germany's BfArM vigilance systems require rapid adverse event reporting, straining quality assurance bandwidth for multi-country operators.
- Cross-border regulatory fragmentation:Divergent national interpretations of MDR implementation create certification complexity despite harmonized EU frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Toothbrush Market |
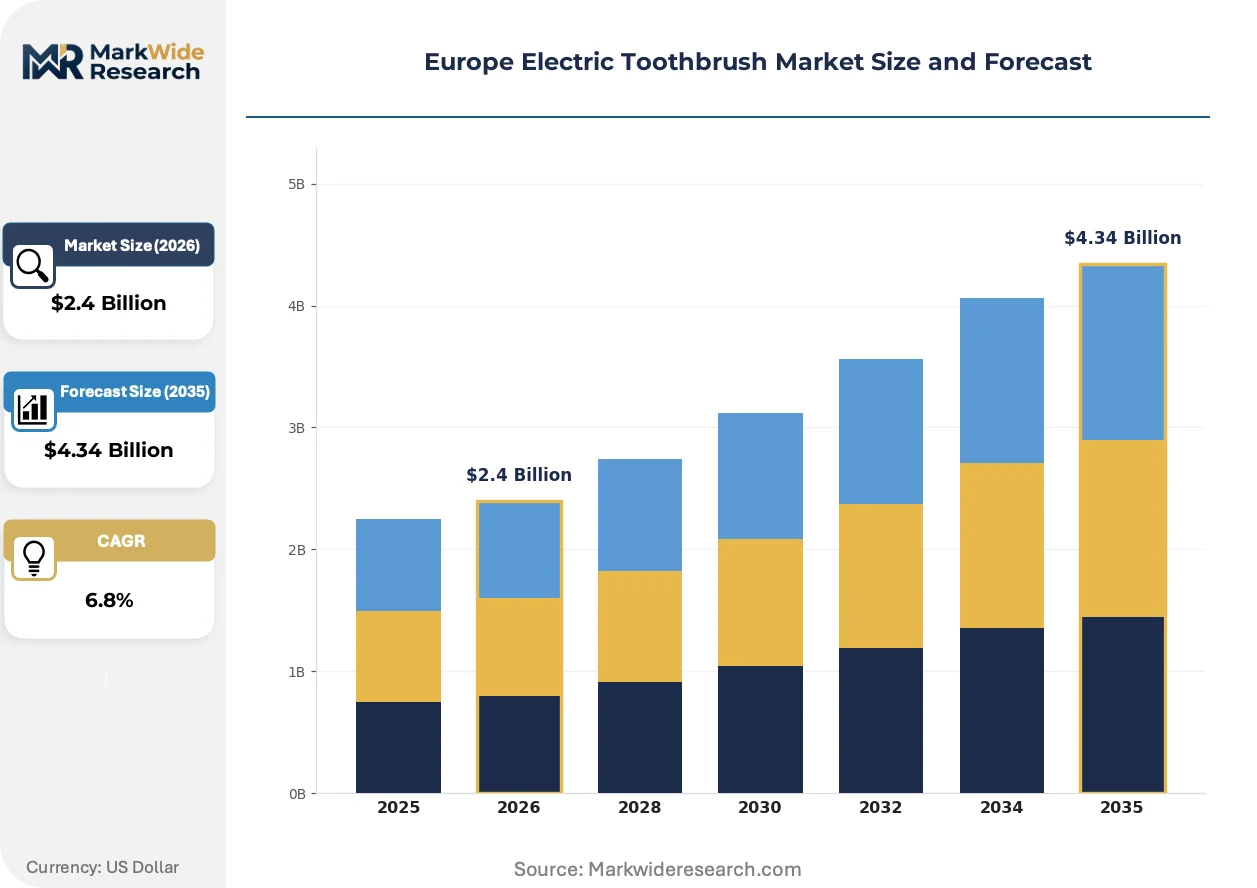
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotating, Sonic, Ultrasonic, Interdental End User: Adults, Children, Seniors, Caregivers Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | FOREO, Church & Dwight Co., Inc., Koninklijke Philips N.V., Ordo, Waterpik, Procter & Gamble Company, Panasonic, Seago, Colgate-Palmolive Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Toothbrush Market Strategic Shifts & Innovations
Connected oral health ecosystems and sustainable material science are redrawing competitive boundaries, with differentiation increasingly anchored in data services rather than hardware performance metrics alone.
Sonic vibration technology is fragmenting across multiple frequency architectures and brush head geometries. Young professionals in urban centers are adopting pressure-sensing models at accelerated replacement cycles. This fragmentation is compressing R&D economies of scale while enabling niche positioning around specific gingival sensitivity profiles.
The EU Green Deal's packaging directives are mandating minimum recycled content thresholds and extended producer responsibility frameworks. Manufacturers are redesigning supply chains to incorporate bio-based plastics and modular brush head systems. Premium product lines in Germany and France are responding fastest, leveraging compliance as a brand positioning element.
Subscription-based brush head replenishment is displacing traditional retail repurchase patterns. Online direct-to-consumer channels are capturing caregiver-directed segments previously served by pharmacy counters. This shift is most visible in the United Kingdom and Nordic markets, where dental insurance integration accelerates automated delivery adoption.
Europe Electric Toothbrush Market Segmentation
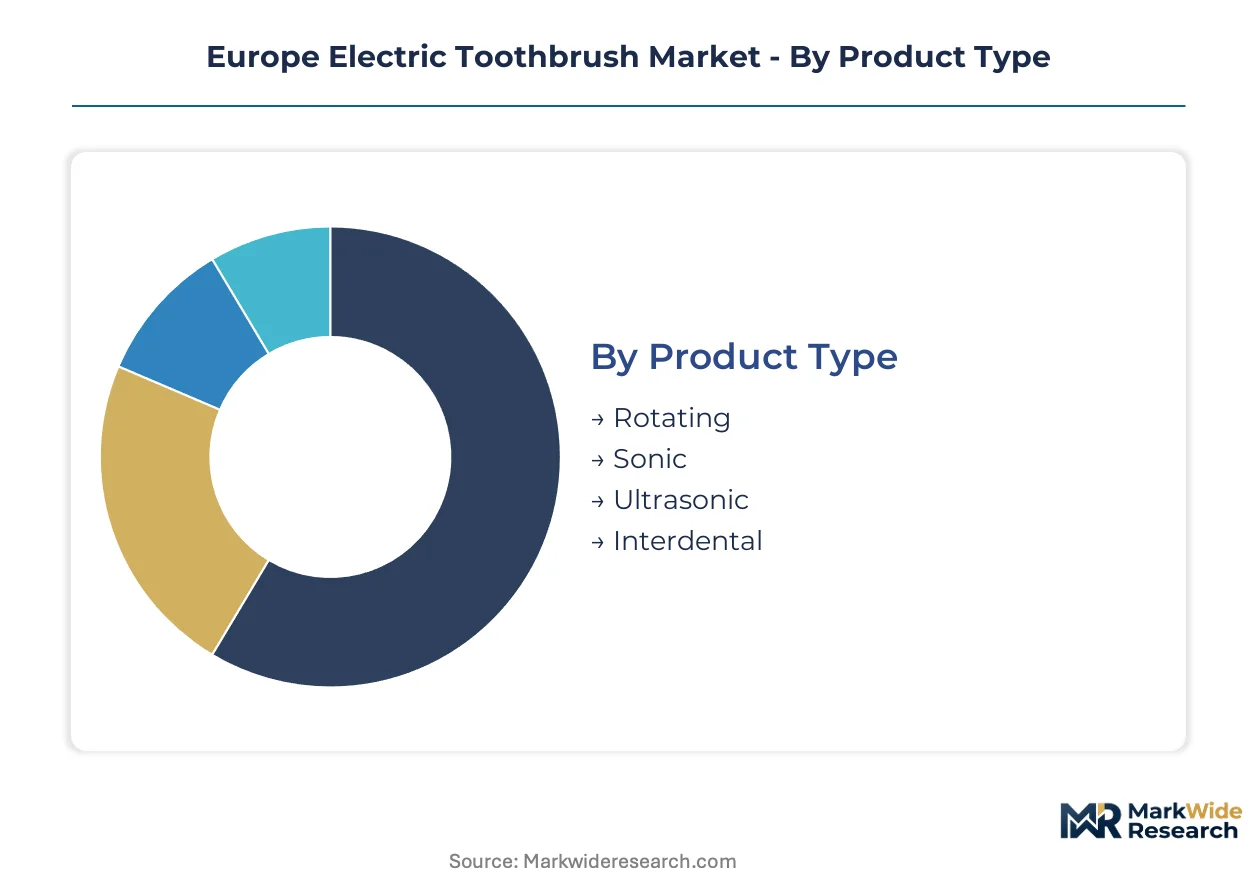
Segmentation in the Europe electric toothbrush market reveals how purchasing power, channel preferences, and demographic aging reshape competitive strategy across national borders. Manufacturers must calibrate feature sets and pricing architectures to distinct buyer archetypes rather than treating the region as a uniform addressable base.
Product Type:
Sonic devices dominate German and British retail channels where consumers trade up for pressure sensors and Bluetooth connectivity, while rotating models retain volume leadership in Southern European pharmacies through dentist endorsement programs.
- Sonic:Operating at 31,000 to 62,000 brush movements per minute, these devices integrate pressure sensors and real-time feedback modules. Demand concentrates in urban Germany and the United Kingdom where dental insurance integration accelerates subscription replenishment adoption.
- Rotating:Oscillating-rotating mechanisms at 7,500 to 9,900 movements per minute deliver proven plaque reduction at accessible price points. French and Italian pharmacy channels favor these units where clinician recommendations carry disproportionate trial conversion weight.
- Ultrasonic:Frequencies exceeding 20,000 Hz disrupt bacterial chains without mechanical abrasion. Niche positioning targets consumers with gingival sensitivity in Scandinavian markets.
- Interdental:Specialized brush head geometries access proximal tooth surfaces. Caregiver-directed purchases for seniors in the United Kingdom drive modest volume.
Sonic holds the largest share; momentum sits with ultrasonic as sensitivity-conscious consumers seek non-abrasive alternatives.
End User:
Adult self-purchasers generate the revenue base across Northern Europe, while caregiver-directed segments expand fastest as aging demographics in Germany and the United Kingdom reshape household oral health spending.
- Adults:Self-directed purchasers aged 25-45 dominate replacement cycles and premium tier migration. Tech-engaged professionals in German metropolitan areas drive connected device adoption with automated brush head replenishment.
- Caregivers:Purchasers acting on behalf of dependents or elderly family members prioritize ergonomic grips and simplified interfaces. British and German aging demographics expand this segment most quickly.
- Seniors:Direct purchasers over 65 favor larger handles and reduced vibration intensity. French pharmacy consultations guide product selection for this cohort.
- Children:Parent-directed purchases emphasize gamification features and smaller brush head geometries. Italian family structures sustain above-average penetration in this category.
Adult self-purchasers anchor revenue; caregivers represent the steepest expansion trajectory as demographic aging accelerates.
Distribution Channel:
Online channels capture volume leadership in Nordic markets and the United Kingdom through subscription integration, while Mediterranean pharmacies retain outsized influence where clinician trust shapes trial decisions.
- Online:Direct-to-consumer platforms and marketplace aggregators displace traditional retail in the Netherlands, Sweden, and the United Kingdom. Dental insurance incentive programs in these markets accelerate automated replenishment adoption.
- Pharmacies:Consultative counter service and professional endorsement sustain relevance in France, Italy, and Spain. ANSM vigilance requirements elevate consumer confidence in pharmacy-sourced devices.
- Supermarkets:Mass-market shelf space competes on promotional pricing and impulse placement. Southern and Eastern European price sensitivity sustains this channel's volume contribution.
- Specialty Stores:Curated retail environments emphasize premium positioning and hands-on demonstration. Limited to flagship urban locations in Paris, Munich, and London.
Online channels are gaining share fastest; pharmacies defend their position through professional trust arbitrage in Mediterranean markets.
Price Tier:
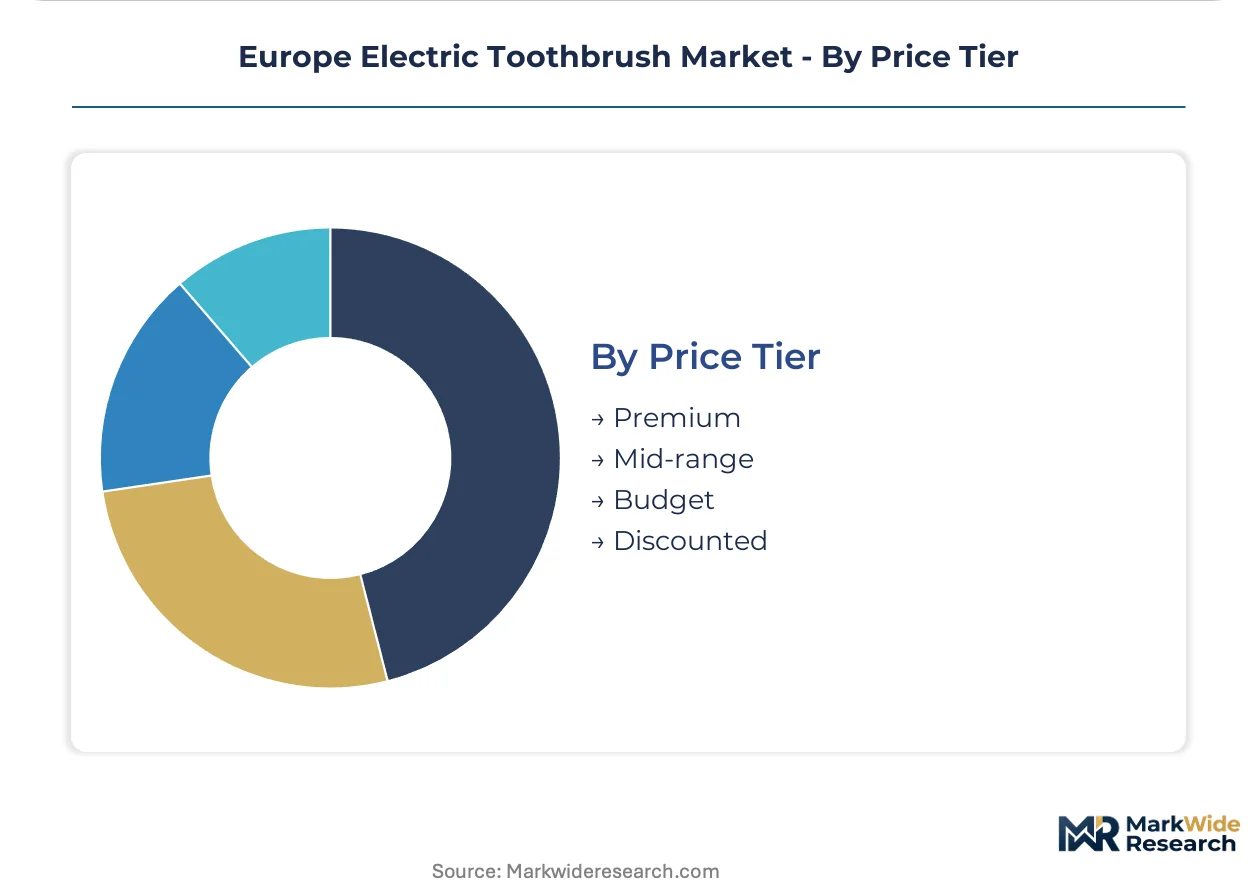
Premium positioning concentrates in German and French markets where EU MDR compliance and sustainability credentials justify margin structures, while budget tiers serve price-elastic segments in Southern and Eastern Europe.
- Premium:Devices exceeding €150 integrate AI-powered brushing analysis, premium materials, and extended warranties. REACH compliance and recyclable brush head architectures differentiate offerings in German and French retail.
- Mid-range:€50-€150 price bands balance essential connected features with mass-market accessibility. British and Dutch consumers migrate here from budget tiers as replacement cycles mature.
- Budget:Entry-level rechargeable units under €50 compete on basic motorized functionality. Polish and Romanian markets sustain volume through price-sensitive household penetration.
- Discounted:Promotional and grey-market units challenge branded positioning. Cross-border e-commerce fragmentation complicates manufacturer price discipline.
Premium tiers command the margin pool; mid-range segments climb fastest as upgrade cycles mature across Northern European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tech-engaged millennials and caregiver-directed senior purchases concentrate demand across Northern Europe, while Mediterranean markets sustain pharmacy-centric trial patterns rooted in professional endorsement culture.
Germany
Dental insurance integration and sustainability credentials pull urban professionals toward premium connected devices. BfArM vigilance requirements filter non-compliant imports from pharmacy shelves. Berlin and Munich retail clusters anchor subscription-based brush head replenishment adoption.
United Kingdom
Online direct-to-consumer channels capture caregiver-directed segments for aging demographics. NHS dental cost pressures push self-pay households toward preventive oral health investments. London and Southeast England concentrate insurtech-linked automated delivery programs.
France
ANSM regulatory oversight elevates consumer confidence in pharmacy-sourced devices. Dentist endorsement programs carry disproportionate trial conversion weight in family purchasing decisions. Paris and Lyon retail environments emphasize CE marking compliance as a quality signal.
Italy
Clinician recommendation culture sustains rotating-model volume through pharmacy counters. Multi-generational household structures extend product lifecycles across family units. Milan and Rome urban centers show early sonic upgrade momentum among younger professionals.
Netherlands
Digital health platform integration enables insurance-linked subscription models. REACH compliance transparency requirements reward early movers in recyclable brush head design. Amsterdam and Rotterdam direct-to-consumer channels displace traditional retail fastest.
Europe Electric Toothbrush Market Key Industry Players
Player mix skews toward diversified consumer health conglomerates with oral care heritage, creating tiered competition between premium ecosystem builders and mass-market pharmacy anchors. Consolidation pressure favors scale operators with CE marking expertise and multi-channel logistics. Three archetypes dominate: connected-device ecosystem specialists, pharmacy-endorsed heritage brands, and direct-to-consumer subscription innovators. Geographic expansion into Eastern Europe and vertical integration into sustainable materials represent the dominant competitive vectors.
Within the diversified health conglomerate tier, Koninklijke Philips N.V. and Procter & Gamble Company exemplify scale-driven positioning across Northern European retail channels. Colgate-Palmolive Company occupies a pharmacy-centric archetype leveraging professional endorsement networks in Mediterranean markets. FOREO represents the design-forward direct-to-consumer vector targeting urban millennials through subscription and sustainability positioning.
| Leading Market Players |
|---|
| FOREO |
| Church & Dwight Co., Inc. |
| Koninklijke Philips N.V. |
| Ordo |
| Waterpik |
| Procter & Gamble Company |
| Panasonic |
| Seago |
| Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with East Asian lithium-ion cell manufacturers lock in both supply access and cost visibility for European assembly operations, insulating premium tier producers from spot market volatility while compressing margin flexibility for mid-range competitors facing REACH compliance escalators.
Pricing Analysis
Cost-plus contracts with lithium-ion battery indexation dominate procurement structures for rechargeable units, anchoring pricing to raw material benchmarks rather than finished goods competition. Price differentiation separates CE-marked premium tiers with recyclable brush head architectures from budget tiers competing on basic motorized functionality. Cost compression in mid-range segments intensifies as EU Green Deal packaging mandates elevate material transparency expenditures. Caregiver-directed senior purchasers exhibit lowest price sensitivity, while Southern and Eastern European households remain most elastic.
Supply Chain Analysis
Inventory buffers for brush head components stretch to 8-12 weeks as manufacturers navigate post-pandemic logistics recalibration. Cell manufacturing concentrates in China, South Korea, and Japan, while final assembly clusters in Poland, Hungary, and Germany to satisfy CE marking proximity requirements. Supply chain risk centers on single-source dependency for rare earth magnets in sonic motor assemblies. Distribution runs through online direct-to-consumer platforms displacing traditional pharmacy wholesale in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment moat where CE marking expertise and BfArM/ANSM vigilance compliance create asymmetric barriers against unqualified entrants, locking in shelf space advantages for incumbent certification holders.
For Market Incumbents: Compound defensive positioning by deepening backward integration into sustainable brush head materials and expanding capacity reservation agreements with cell manufacturers. Subscription-based replenishment models represent the priority lever against direct-to-consumer challengers eroding pharmacy channel control. For New Entrants and Emerging Players: Anchor in caregiver-directed senior segments where ergonomic design differentiation and simplified interfaces bypass entrenched brand loyalty in self-purchaser markets. Scandinavian digital health platform partnerships offer the most penetrable go-to-market angle through insurance-linked subscription integration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with dormant CE marking pathways and underutilized pharmacy distribution networks in Mediterranean markets. Watch for BfArM adverse event disclosure spikes as inflection indicators of quality assurance failures that trigger consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Brush Head Architecture Redesign | EU Green Deal compliance transforms from cost burden to premium positioning element in German retail. |
| Subscription-Based Replenishment Launch | Direct-to-consumer capture of caregiver segments displaces pharmacy counter dependence in British markets. |
| Bluetooth Ecosystem Integration | Real-time brushing feedback modules pull tech-engaged millennials toward premium sonic tier migration. |
| Pharmacy Channel Expansion | ANSM-regulated counter presence builds professional trust arbitrage against online price competition in France. |
| Senior-Focused Ergonomic Product Line | Grip assistance features address fastest-growing demand pocket as German and British demographics age. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with product development executives at oral care manufacturers, regulatory affairs specialists, pharmacy category buyers, and dental insurance program managers; and secondary validation against CE marking databases, ANSM vigilance reports, BfArM adverse event filings, and EU trade customs records. Bottom-up unit economics triangulated against top-down category spend estimates to anchor volume and value outputs.
Across the projection horizon, the analytical framework modeled demand by product type, end user archetype, distribution channel, and national regulatory cluster. CAGRs were derived from replacement cycle maturation curves and premium tier migration elasticities observed in insurance-integrated markets. Forecast inputs incorporated REACH compliance cost trajectories and lithium-ion cell price index movements.
Decision-makers should treat outputs as directional under assumptions of sustained EU MDR enforcement intensity and stable East Asian cell supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Organic Tampons Market