
 US Sex Toys Market | 2026-2036
US Sex Toys Market Size, Share, and Industry Trends Forecast 2026-2036
US Sex Toys Market Insights
Online retail is tilting toward subscription and direct-to-consumer models as legacy adult shops cede ground to privacy-first digital channels. Church & Dwight Co., Inc. leverages its mass-market distribution infrastructure to sustain shelf presence across mainstream pharmacy chains. Dame Products, Inc. differentiates through design-forward positioning and FDA-registered device claims. LELO anchors the premium segment with extended warranty programs and European manufacturing heritage translated into US pricing power.
US sex toys encompass motorized and non-motorized intimate devices engineered from medical-grade silicone, thermoplastic elastomers, or borosilicate glass, typically operating at frequencies between 60-120 Hz with rechargeable lithium-ion power systems designed for external or internal stimulation. Vibrators command the largest revenue pool due to repeat purchase frequency and technology upgrade cycles, while silicone materials capture margin concentration as consumers prioritize hypoallergenic and non-porous compositions. The couples segment demonstrates the fastest trajectory as relationship wellness frameworks normalize joint purchasing behavior.
FDA Center for Devices and Radiological Health governs medical device classifications for therapeutic vibrators, while Consumer Product Safety Commission monitors phthalate restrictions in plastic formulations; state-level obscenity statutes in Alabama, Mississippi, and Texas create patchwork retail barriers that online channels systematically circumvent. Stakeholders must monitor evolving FDA guidance on software-enabled teledildonics and biometric feedback integration as the next frontier of product differentiation and compliance burden.
Market Dynamics
Direct-to-consumer platforms are compressing traditional retail margins while FDA medical-device registrations create bifurcated quality tiers that reshape competitive positioning across California, New York, and Texas distribution clusters.
Growth Catalysts
- Wellness Framework Normalization:Relationship wellness discourse reframes intimate devices as self-care staples, expanding addressable demand among partnered millennials and Gen Z cohorts in urban coastal metros.
- Body-Safe Material Standards:Medical-grade silicone formulations displace porous TPE alternatives as consumer education around phthalate risks intensifies through OB-GYN and pelvic health professional channels.
- Teledildonics Integration:Bluetooth-enabled biometric feedback systems enable long-distance intimacy applications, opening software-enabled recurring revenue streams distinct from hardware refresh cycles.
Market Restraints
- State-Level Obscenity Statutes:Alabama, Mississippi, and Texas maintain patchwork retail prohibitions that force brick-and-mortar operators into compliance-heavy zoning negotiations, elevating physical distribution costs relative to online channels.
- Lithium-Ion Supply Concentration:Rechargeable power system dependence on East Asian battery cell suppliers exposes margin compression from shipping volatility and raw material price swings in cobalt and lithium carbonate markets.
- Silicone Feedstock Oligopoly:Medical-grade silicone precursor supply concentrates among three specialty chemical producers, constraining formulation flexibility and elevating minimum order quantities for emerging product lines.
Strategic Opportunities
- FDA Software-as-Medical-Device Pathway:Draft guidance on algorithm-driven stimulation patterns offers first-mover advantage for firms submitting 510(k) premarket notifications for app-controlled intimate wellness platforms.
- Subscription Replenishment Models:Consumable accessories and hygiene companion products enable recurring revenue architecture comparable to razor-razorblade economics, reducing customer acquisition cost dependence.
- Pelvic Floor Therapy Crossover:Physical therapist and urogynecologist referral channels for therapeutic vibrator indications open institutional procurement pathways distinct from consumer discretionary spending patterns.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization study queues at certified laboratories extend product development timelines, compressing competitive response windows for feature-matching.
- Payment Processor Risk Classification:Adult industry merchant category codes trigger elevated reserve requirements and account termination risk at mainstream financial institutions, necessitating specialized banking relationships with higher transaction fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sex Toys Market |
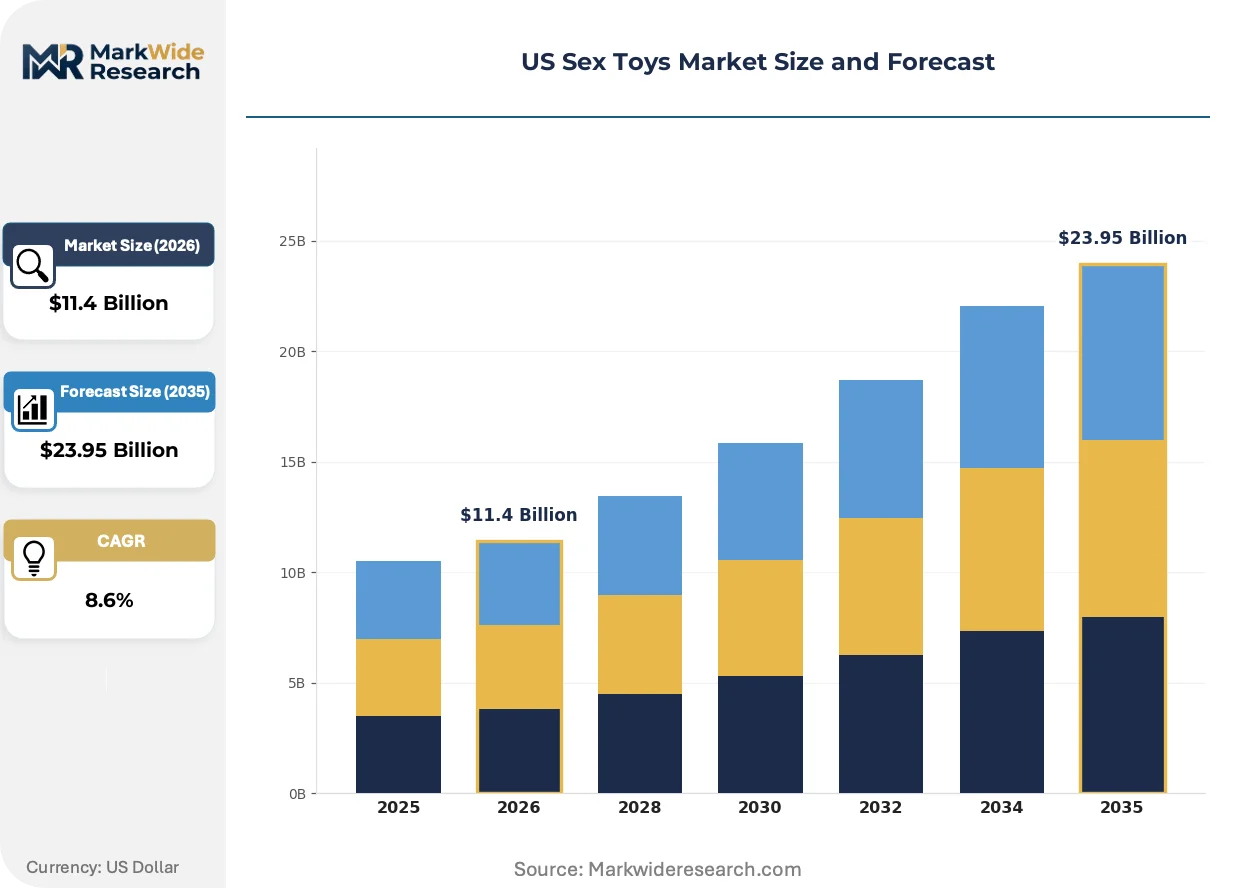
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibrators, Dildos, Anal Toys, Masturbators Material: Silicone, Glass, Plastic, Metal Gender: Female, Male, Couples, Non-binary Distribution Channel: Online Retail, Specialty Stores, Department Stores, Adult Shops |
| Companies Covered | Church & Dwight Co., Inc., Lovehoney Group Ltd., LELO, Doc Johnson Enterprises, Reckitt Benckiser Group plc, PHE, Inc. (Adam & Eve), California Exotic Novelties, Dame Products, Inc., BMS Factory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sex Toys Market Trends and Innovations
App-enabled intimacy hardware is compressing the boundary between consumer electronics and medical devices, forcing recalibration of quality assurance protocols and go-to-market strategies simultaneously.
App-controlled stimulation systems are hybridizing hardware-software architectures previously siloed in separate regulatory frameworks. Millennial and Gen Z purchasers in California and New York metros adopt these platforms at rates outpacing traditional analog alternatives. The convergence is compressing product refresh cycles while elevating cybersecurity and data privacy compliance burdens beyond conventional consumer electronics standards.
FDA Center for Devices and Radiological Health draft guidance on software-enabled teledildonics is reshaping premarket submission requirements for biometric feedback integration. Manufacturers must now document algorithm validation and electromagnetic compatibility testing previously exempt from intimate device classifications. The couples segment faces the steepest compliance adaptation curve as joint-use applications trigger heightened therapeutic claims scrutiny.
Privacy-first purchasing behavior is displacing legacy adult retail footprints across Texas and Florida suburban corridors. Amazon and specialized direct-to-consumer platforms capture volume previously routed through physical storefronts subject to local zoning restrictions. Urban millennials demonstrate the strongest channel preference divergence, with subscription and discreet packaging options commanding premium price acceptance relative to conventional retail anonymity.
US Sex Toys Market Segmentation
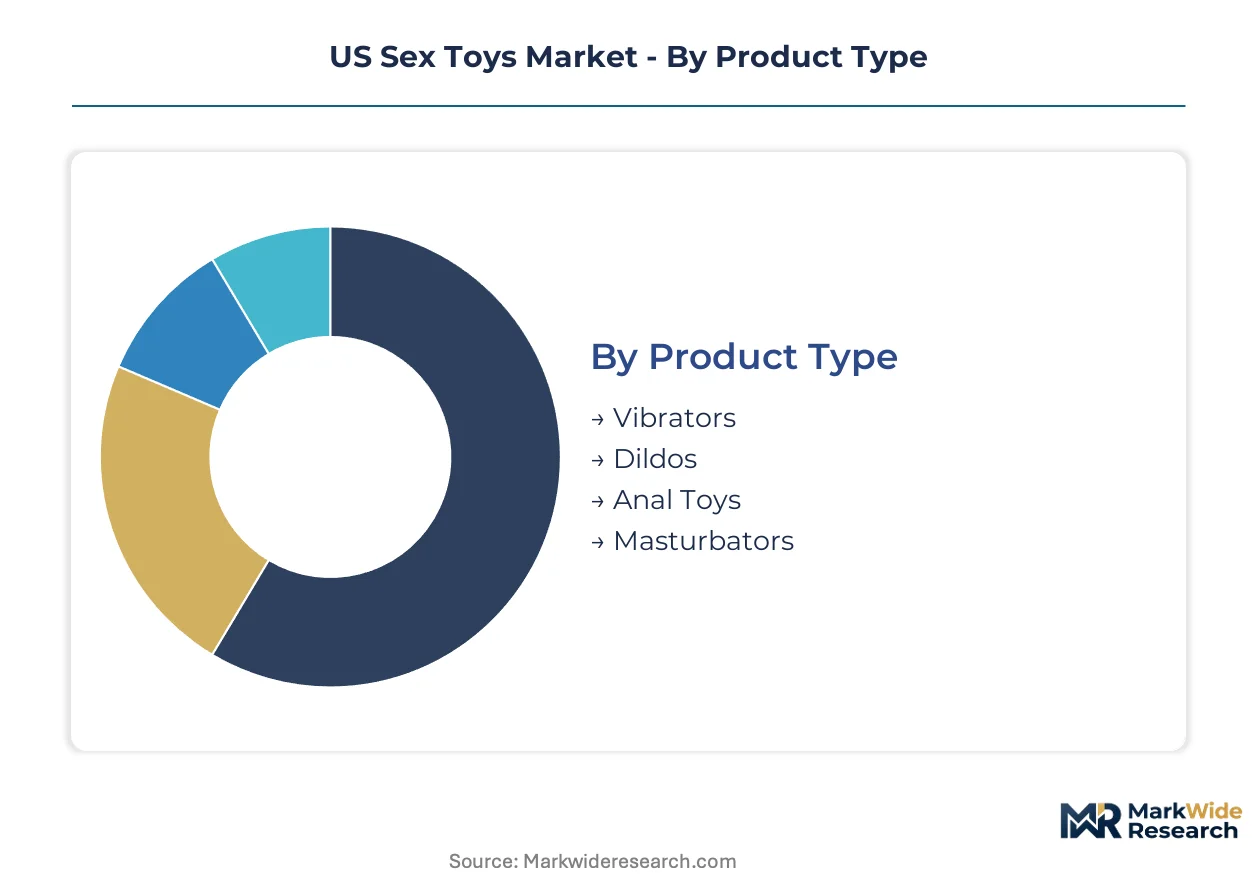
Segmentation in the US sex toys market reveals how FDA medical-device classifications, material biocompatibility standards, and privacy-prioritized purchasing reshape competitive entry points. Manufacturers must navigate distinct technical specifications, distribution compliance burdens, and end-user wellness frameworks simultaneously.
Product Type:
The use-case spectrum spans external stimulation, internal penetration, anal-specific anatomy, and solo simulation with divergent motor requirements and frequency specifications.
- Vibrators:Motorized devices operating at 60-120 Hz with rechargeable lithium-ion systems command the largest revenue pool due to repeat purchase frequency and technology upgrade cycles. Demand concentrates heavily in California and New York metros where wellness-oriented millennials prioritize app-enabled biometric feedback integration.
- Dildos:Non-motorized penetrative devices crafted from medical-grade silicone, borosilicate glass, or thermoplastic elastomers offer the lowest price entry point but face margin pressure from body-safe material certification requirements. Texas and Florida suburban corridors show strongest adoption through privacy-first direct-to-consumer channels circumventing local zoning restrictions.
- Anal Toys:Specialized designs incorporating flared-base safety engineering and graduated sizing target distinct anatomical requirements with heightened flammability and biocompatibility testing protocols.
- Masturbators:Male-focused sleeves and automated systems integrate textured interiors with heating elements, facing concentrated competition from Japanese and European import manufacturers.
Established volume favors vibrators; emerging adoption favors masturbators.
Material:
Cost tier stratification separates medical-grade formulations from commodity alternatives, with FDA oversight and OB-GYN channel education elevating premium positioning.
- Silicone:Medical-grade platinum-cured formulations capture margin concentration as hypoallergenic and non-porous compositions displace porous alternatives. FDA Center for Devices and Radiological Health registration requirements and ISO 10993 cytotoxicity testing create barrier to entry for non-specialty manufacturers.
- Glass:Borosilicate formulations offer thermal conductivity for temperature play applications with non-porous surfaces eliminating bacterial harboring risks. Artisan production in California and Oregon clusters serves boutique direct-to-consumer brands seeking design differentiation.
- Plastic:Thermoplastic elastomers and ABS formulations face Consumer Product Safety Commission phthalate restriction monitoring, compressing addressable market to price-sensitive entry-level segments.
- Metal:Surgical stainless steel and aluminum alloys target temperature-responsive and weight-specific preferences with limited domestic manufacturing infrastructure.
Silicone dominates premium positioning; glass gains share fastest among design-forward independents.
Gender:
Customer type segmentation reflects evolving relationship wellness discourse normalizing joint purchasing and non-binary product architecture.
- Female:External clitoral stimulators and dual-action devices represent the historical market foundation with established pelvic health professional referral channels for therapeutic indications.
- Male:Prostate massagers and automated masturbation systems face slower wellness framework integration but show accelerating adoption through subscription replenishment models.
- Couples:Bluetooth-enabled teledildonics and wearable remote-control devices demonstrate the steepest expansion trajectory as partnered millennials and Gen Z cohorts normalize joint purchasing behavior in urban coastal metros.
- Non-binary:Gender-neutral form factors and customizable stimulation patterns emerge from design-forward independents targeting identity-affirming product positioning.
Female segments anchor established revenue; couples applications climb the fastest amid relationship wellness normalization.
Distribution Channel:
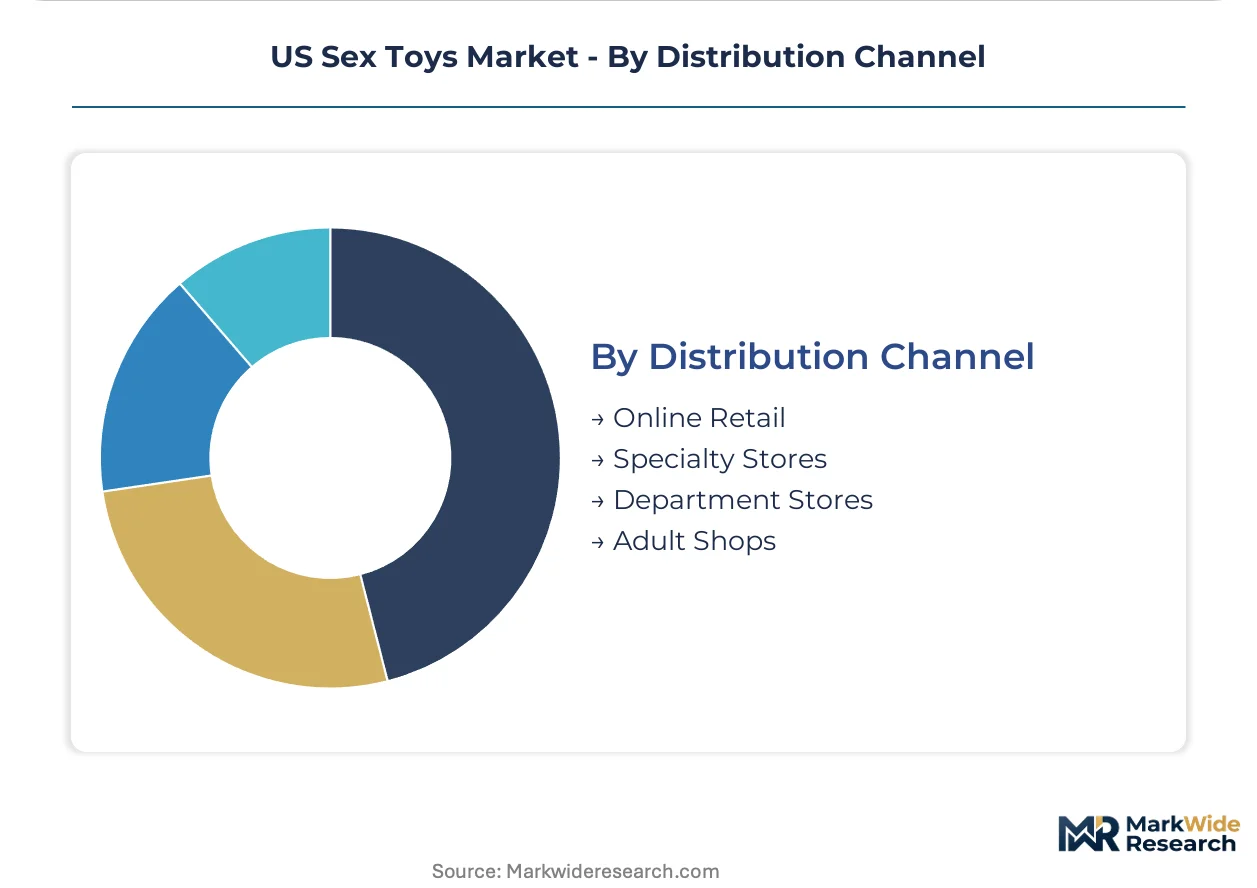
Geography of retail access determines compliance burden intensity, with state-level obscenity statutes fragmenting physical presence while digital channels consolidate.
- Online Retail:Amazon and specialized direct-to-consumer platforms capture volume previously routed through physical storefronts, with subscription and discreet packaging options commanding premium price acceptance. Payment processor risk classification triggers elevated reserve requirements necessitating specialized banking relationships.
- Specialty Stores:Curated boutiques in Los Angeles, New York City, and Austin clusters serve design-conscious consumers seeking educational staff consultation and hands-on material assessment.
- Department Stores:Mainstream pharmacy and big-box retail presence remains limited to mass-market brands with established mass-market distribution infrastructure, facing shelf space competition from broader wellness categories.
- Adult Shops:Legacy brick-and-mortar operators in Alabama, Mississippi, and Texas confront compliance-heavy zoning negotiations elevating physical distribution costs relative to online alternatives.
Online retail concentrates transaction volume; specialty stores retain premium positioning through experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Devices and Radiological Health oversight shapes the dominant US market, with state-level obscenity statutes creating patchwork distribution barriers that online channels systematically circumvent across sub-regional clusters.
California
Wellness-oriented millennials in Los Angeles and San Francisco metros drive demand for app-enabled biometric feedback devices. State consumer protection laws exceed federal baselines on phthalate disclosure requirements. Silicon Valley engineering talent pools enable teledildonics startups clustered in San Francisco and Oakland.
New York
Urban coastal professionals normalize joint purchasing behavior through relationship wellness frameworks. New York State Department of Health maintains alignment with FDA medical-device registration pathways without additional state-level barriers. Manhattan and Brooklyn specialty boutiques serve design-conscious consumers seeking educational staff consultation.
Texas
Suburban corridors in Dallas-Fort Worth and Houston show strongest privacy-first direct-to-consumer adoption. State obscenity statutes force brick-and-mortar operators into compliance-heavy zoning negotiations. Austin clusters emerge as exception with curated retail presence serving progressive urban demographics.
Florida
Miami and Tampa metros demonstrate accelerating subscription replenishment model penetration among male-focused product categories. State regulations mirror federal Consumer Product Safety Commission phthalate restrictions without supplementary local barriers. Discreet packaging options command premium price acceptance relative to conventional retail anonymity.
Illinois
Chicago anchors Midwest distribution infrastructure for mass-market brands with established pharmacy chain presence. Illinois Commerce Commission oversight of e-commerce logistics centers supports fulfillment network density. Pelvic health professional referral channels for therapeutic indications open institutional procurement pathways distinct from coastal consumer discretionary patterns.
US Sex Toys Market Competitive Landscape
Mass-market conglomerates and design-forward independents split the market into bifurcated quality tiers. FDA medical-device registrations create barrier-to-entry moats that favor established players with compliance infrastructure. Three archetypes dominate: pharmaceutical-backed mass-market distributors, European heritage premium manufacturers, and venture-funded wellness startups. Competitive moves concentrate on direct-to-consumer platform expansion and subscription replenishment model deployment.
Within the pharmaceutical-backed tier, Church & Dwight Co., Inc. and Reckitt Benckiser Group plc occupy positions leveraging mass-market distribution infrastructure across mainstream retail channels. Among design-forward independents, Dame Products, Inc. exemplifies FDA-registered device positioning, while LELO anchors premium-tier pricing through European manufacturing heritage translated into US market presence. California Exotic Novelties and Doc Johnson Enterprises represent established domestic fabricators with decades-long category participation. Lovehoney Group Ltd. and PHE, Inc. (Adam & Eve) sit within specialized direct-to-consumer and catalog heritage archetypes respectively, each navigating payment processor risk classification through specialized banking relationships.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Lovehoney Group Ltd. |
| LELO |
| Doc Johnson Enterprises |
| Reckitt Benckiser Group plc |
| PHE, Inc. (Adam & Eve) |
| California Exotic Novelties |
| Dame Products, Inc. |
| BMS Factory |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian lithium-ion cell manufacturing compresses supplier margins while elevating buyer leverage across US distribution tiers, forcing manufacturers to absorb cost volatility or sacrifice volume commitments. This utilization dynamic cascades into silicone precursor markets, where medical-grade formulation minimums create pricing rigidity for emerging brands.
Pricing Analysis
California-to-Texas price spreads of 15-25% reflect differential compliance burdens and last-mile logistics costs rather than product differentiation. Three-tier pricing structure across premium, standard, and economy levels segments by FDA registration status and warranty depth, with LELO and Dame Products commanding brand premiums. Pricing pressure stems from direct-to-consumer platform commission structures and payment processor reserve requirements. Mass-market pharmacy channels show highest price sensitivity; specialty boutiques and subscription models demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates lithium-ion battery sourcing decisions, with South Korean and Japanese cell suppliers gaining share as alternative feedstock. Medical-grade silicone precursors draw from Germany, Japan, and domestic California specialty chemical producers. Single-source vulnerability concentrates in cobalt cathode materials and platinum-cure catalysts. Distribution runs through Amazon fulfillment centers and specialized direct-to-consumer platforms, with discreet packaging logistics constituting a dedicated warehouse tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sex toys market exhibits cyclical recovery characteristics driven by wellness category normalization following pandemic-era demand spikes, with relationship wellness discourse sustaining elevated baseline consumption.
For Market Incumbents: Build FDA 510(k) submission infrastructure as a compliance moat against venture-funded wellness startups lacking regulatory affairs capacity. Deepen backward integration into medical-grade silicone compounding through captive supply agreements with California and German specialty chemical producers. Defend channel position by securing exclusive pharmacy chain shelf space before mass-market conglomerates expand intimate wellness assortments. For New Entrants and Emerging Players: Texas suburban corridors and Florida retirement communities represent geographic underpenetration relative to coastal metro saturation, offering privacy-first direct-to-consumer acquisition efficiency. Target male-focused subscription replenishment models where wellness framework integration lags female and couples segments. Pursue physical therapist and urogynecologist referral channel development as institutional credibility accelerators distinct from discretionary retail competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among teledildonics platforms with app-enabled companion subscriptions and consumable accessory replenishment. Long-term viability favors firms with FDA software-as-medical-device pathway submissions and biometric feedback algorithm validation. Acquisition target archetype: venture-backed wellness startups with established direct-to-consumer unit economics and pending 510(k) portfolios. Monitor FDA draft guidance finalization as inflection indicator for compliance cost repricing across competitive tiers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | 510(k) premarket notification for app-controlled stimulation algorithms creates first-mover regulatory moat. |
| Subscription Replenishment Model Launch | Consumable accessories and hygiene companions enable razor-razorblade recurring revenue architecture. |
| Pelvic Health Professional Channel Development | Physical therapist and urogynecologist referrals open institutional procurement distinct from retail. |
| Direct-to-Consumer Platform Expansion | Privacy-first digital channels circumvent state-level obscenity statute barriers in Texas and Alabama. |
| Medical-Grade Silicone Backward Integration | Captive supply agreements with California and German specialty chemical producers secure formulation flexibility. |
Research Methodology
The analysis maps vibrators, dildos, anal toys, and masturbators, each validated through product development executives at established manufacturers and regulatory affairs specialists at FDA-registered firms. Primary interviews with OB-GYNs, pelvic floor physical therapists, and pharmacy category buyers combined with secondary triangulation against FDA 510(k) filings, CPSC phthalate restriction databases, and state-level obscenity statute compilations. Bottom-up demand modeling and top-down category sizing cross-validated segment-level projections.
Assumptions held fixed include FDA Center for Devices and Radiological Health oversight continuity and lithium-ion battery chemistry cost curves; variables tested encompass state-level regulatory liberalization scenarios and teledildonics adoption elasticity. Segmentation dimensions span product type, material grade, gender application, and distribution channel, with couples and non-binary categories receiving distinct modeling treatment. CAGR derivation anchored historical correlation between wellness discourse intensity and category penetration rates, with biometric feedback integration and subscription attach rates as industry-specific forecast inputs across the projection horizon.
Practitioners should monitor FDA software-as-medical-device guidance finalization and lithium carbonate price volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Dartboard Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Bubble Blower Market
Toys and Games
Table Top Games Market
Toys and Games
Arcade Games Machine Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Inflatable Toys Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Air Hockey Table Market
Toys and Games
Action Figures Market
Toys and Games
Plush Toy Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Kid's Microphone Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Male Sex Toys Market