
 Global Roofing Software Market | 2026-2036
Global Roofing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Roofing Software Market Outlook
The EU Green Deal is recalibrating how European roofing contractors select software platforms, with energy performance documentation and carbon reporting modules becoming baseline requirements. AccuLynx leverages its contractor-centric workflow design to sustain strong positions in North American residential markets. STACK Construction Technologies anchors its growth through specialized takeoff and estimating tools that dominate commercial bidding workflows. JobNimbus competes aggressively on field-service mobility, extending its footprint among mid-sized roofing operations.
Roofing software encompasses digital platforms that automate measurement, estimation, project scheduling, material ordering, and crew dispatch for roofing contractors and related construction professionals. Core technical specifications include aerial imagery integration with sub-inch measurement accuracy, API connectivity to supplier pricing databases, and mobile-native field data capture supporting offline synchronization. Cloud-Based deployment leads structural segment dynamics as contractors prioritize remote access and automatic updates without IT infrastructure burdens. Subscription offerings capture expanding recurring revenue pools while legacy license models stagnate among established players. Project Management and Estimating features concentrate margin attraction, with contractors paying premium tiers for integrated CRM and supplier procurement links.
The EPA's ENERGY STAR certification requirements and the EU Green Deal's building performance standards shape product roadmap priorities across platform developers. OSHA fall-protection documentation mandates in the United States and REACH material compliance in Europe further embed regulatory logic into software feature sets. Stakeholders must monitor how emerging building codes in Germany, California, and Japan integrate digital compliance verification into permitting workflows.
Market Dynamics
Cloud migration pressure from commercial roofing contractors is compressing deployment cycles and forcing platform consolidation around integrated estimation-to-payment workflows.
Growth Catalysts
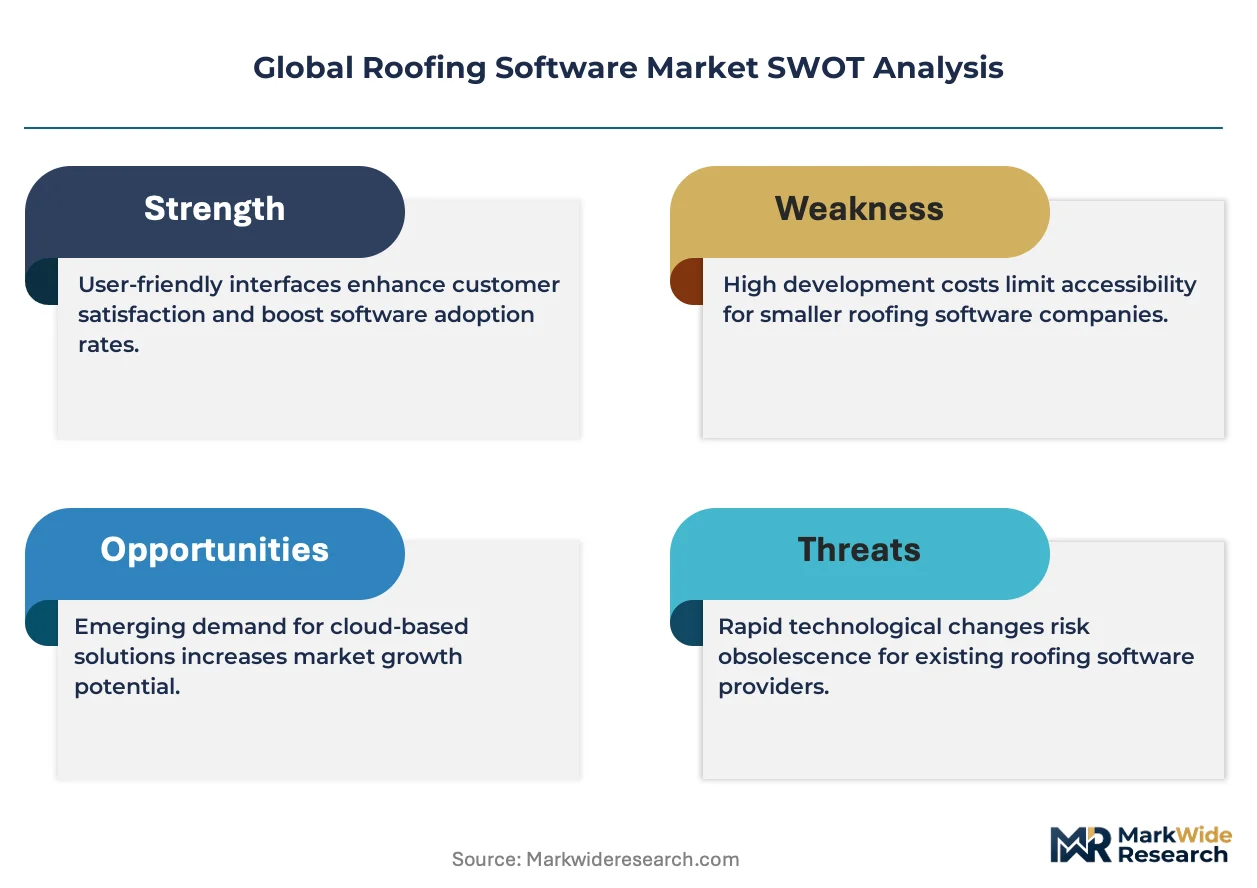
- EU Green Deal building renovation mandates:European contractors must document energy performance and carbon metrics, pulling compliance-tracking modules into standard software procurement decisions.
- Solar roofing integration:Photovoltaic installation workflows require specialized measurement and electrical coordination tools, expanding addressable platform spend per contractor.
- Storm restoration cycles:United States weather volatility accelerates replacement demand, pushing contractors toward rapid-estimation platforms that compress bidding-to-award timelines.
Market Restraints
- High switching costs:Embedded historical project data and crew training investments lock contractors into incumbent platforms, slowing competitive displacement.
- Supplier pricing API fragmentation:Regional building material distributors maintain incompatible data formats, limiting real-time cost accuracy outside major metropolitan markets.
- Connectivity infrastructure gaps:Rural job sites in the United States, Canada, and Australia lack reliable broadband, degrading cloud synchronization performance for field crews.
Strategic Opportunities
- Japan's building energy efficiency standards:METI's tightening envelope performance codes create demand for thermal modeling modules absent from most Western platforms.
- AI-powered aerial damage assessment:Computer vision integration with drone imagery is automating hail and wind damage documentation for insurance carriers.
- Embedded finance penetration:Contractor financing and homeowner payment plans integrated at the point of estimate represent untapped recurring revenue streams.
Industry Challenges
- Skilled estimator scarcity:Retiring trade professionals leave knowledge gaps that software onboarding cannot fully bridge, extending implementation timelines.
- Multi-platform integration complexity:Roofing contractors operate accounting, CRM, and supplier systems that resist API-based data synchronization, creating manual reconciliation burdens.
- OSHA documentation audit trails:Fall-protection compliance logging requirements demand specialized mobile workflows that generic construction platforms fail to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Roofing Software Market |
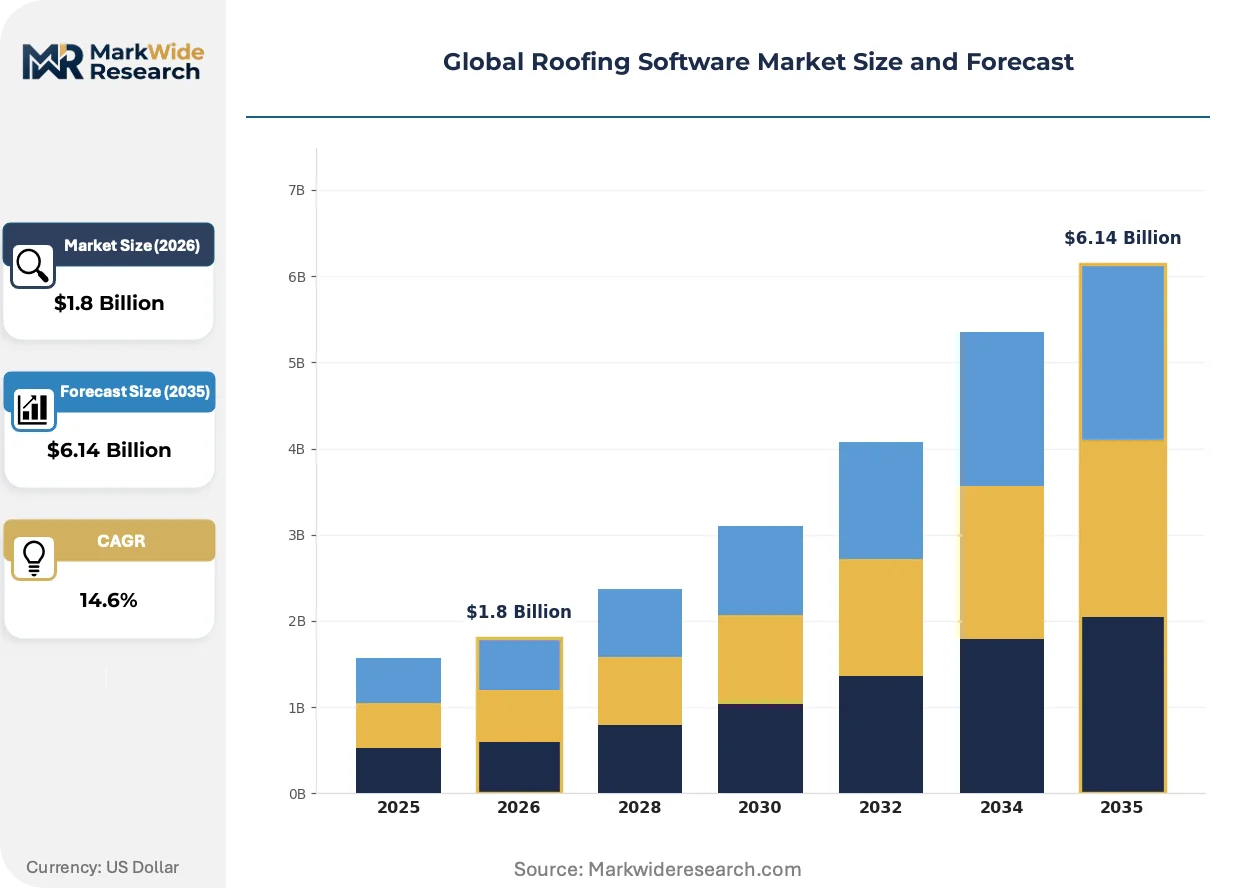
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based End User: Contractors, Architects, Builders, Manufacturers Offering: License, Subscription, Freemium, One-Time Purchase Feature: Project Management, Estimating, Reporting, Collaboration |
| Companies Covered | RoofSnap, Buildxact, JobNimbus, FieldPulse, EagleView Technologies, STACK Construction Technologies, AccuLynx, Project Manager by Knowify, Hover, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Roofing Software Market Strategic Shifts
Machine learning and satellite imagery convergence is collapsing measurement timelines from days to hours, while regulatory documentation requirements embed compliance logic directly into core platform architectures.
Computer vision paired with sub-inch aerial imagery is automating roof plane detection, ridge line extraction, and material quantity calculations. Mid-sized commercial contractors in storm-prone United States counties are adopting these tools fastest, replacing manual tape-measure workflows. The technology is automating estimator labor allocation, allowing firms to bid three times more projects with equivalent headcount.
REACH material compliance in Europe and EPA ENERGY STAR certification in the United States are mandating chemical disclosure and thermal performance documentation. Platform developers must now embed regulatory logic into supplier procurement modules and project closeout reporting. German contractors face the tightest integration deadlines as the federal building code transitions to digital permitting workflows.
Subscription pricing is displacing perpetual licenses as contractors prioritize cash flow flexibility over ownership. Mid-market roofing operations in Texas, Florida, and California lead this shift, demanding month-to-month terms that align with seasonal revenue volatility. The model concentrates vendor risk around retention metrics rather than upfront license recognition.
Global Roofing Software Market Segmentation
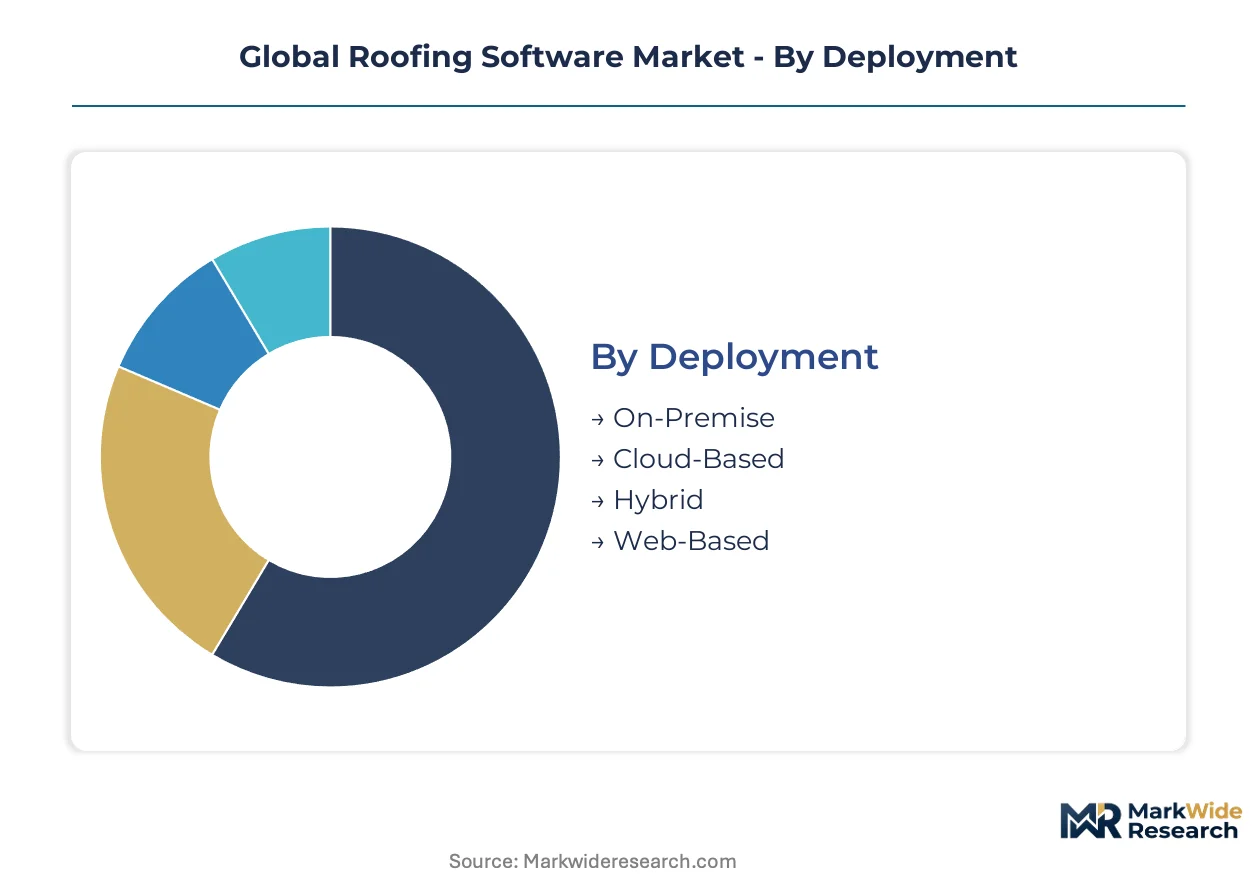
Roofing software procurement patterns diverge sharply across deployment models, end-user workflows, and commercial terms. Platform vendors must align feature packaging with distinct upgrade cycles that vary from annual contractor renewals to multi-year manufacturer contracts.
Deployment:
Upgrade cycles for roofing contractors accelerate as legacy server infrastructure reaches end-of-life, pushing decisions toward remote-access architectures.
- Cloud-Based:Vendors host applications on distributed server infrastructure with automatic security patching and feature rollouts. Storm restoration contractors in Florida and Texas prioritize this model for field crew synchronization across dispersed job sites. The EPA's ENERGY STAR documentation requirements favor centralized data repositories that cloud architectures enable.
- On-Premise:Software runs on contractor-owned servers with localized data control and custom integration capabilities. Large commercial roofing operations in Germany and Japan maintain these deployments for compliance with strict data residency rules under national building codes.
- Hybrid:Combines local processing for sensitive estimation data with cloud synchronization for mobile field access. Mid-sized United States contractors adopt this during phased migrations from legacy systems.
- Web-Based:Browser-delivered functionality eliminates installation requirements for temporary project staff. Australian roofing subcontractors use this for short-duration storm response contracts.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Hybrid configurations bridging legacy and modern workflows.
End User:
Customer type determines pricing tolerance and feature depth, with specialized workflows commanding premium tiers.
- Contractors:Field operations demand mobile-native interfaces for crew dispatch, material ordering, and progress documentation. Residential roofing contractors in California and Arizona drive subscription growth through seasonal hiring patterns.
- Architects:Design-phase integration with BIM platforms and thermal modeling tools defines procurement criteria. German architectural firms under EU Green Deal mandates require embedded carbon calculation modules.
- Builders:Multi-trade coordination needs pull roofing software into broader construction management ecosystems. Japanese general contractors integrate these tools under METI building energy efficiency standards.
- Manufacturers:Material suppliers deploy white-label estimation platforms to lock in contractor specification behavior. United States shingle and metal roofing producers lead this channel strategy.
Revenue concentration sits with Contractors; Architects show the steepest expansion trajectory as regulatory documentation demands intensify.
Offering:
Commercial terms reshape vendor cash flow profiles and customer lifetime value calculations across the market.
- Subscription:Recurring monthly or annual payments align with contractor seasonal revenue volatility. United States mid-market roofing operations in storm-prone states favor this flexibility for scaling seat counts.
- License:Perpetual ownership with maintenance contracts persists among established Japanese contractors with conservative capital allocation practices.
- Freemium:Basic functionality at no cost converts to paid tiers for advanced estimating or supplier integrations. Solo contractors in rural Australia and Canada enter through this channel.
- One-Time Purchase:Single upfront payment for standalone estimation modules without ongoing support. Declining share reflects cloud migration pressure across all geographies.
Subscription terms capture the dominant revenue pool; Freemium conversion rates are climbing fastest among new market entrants.
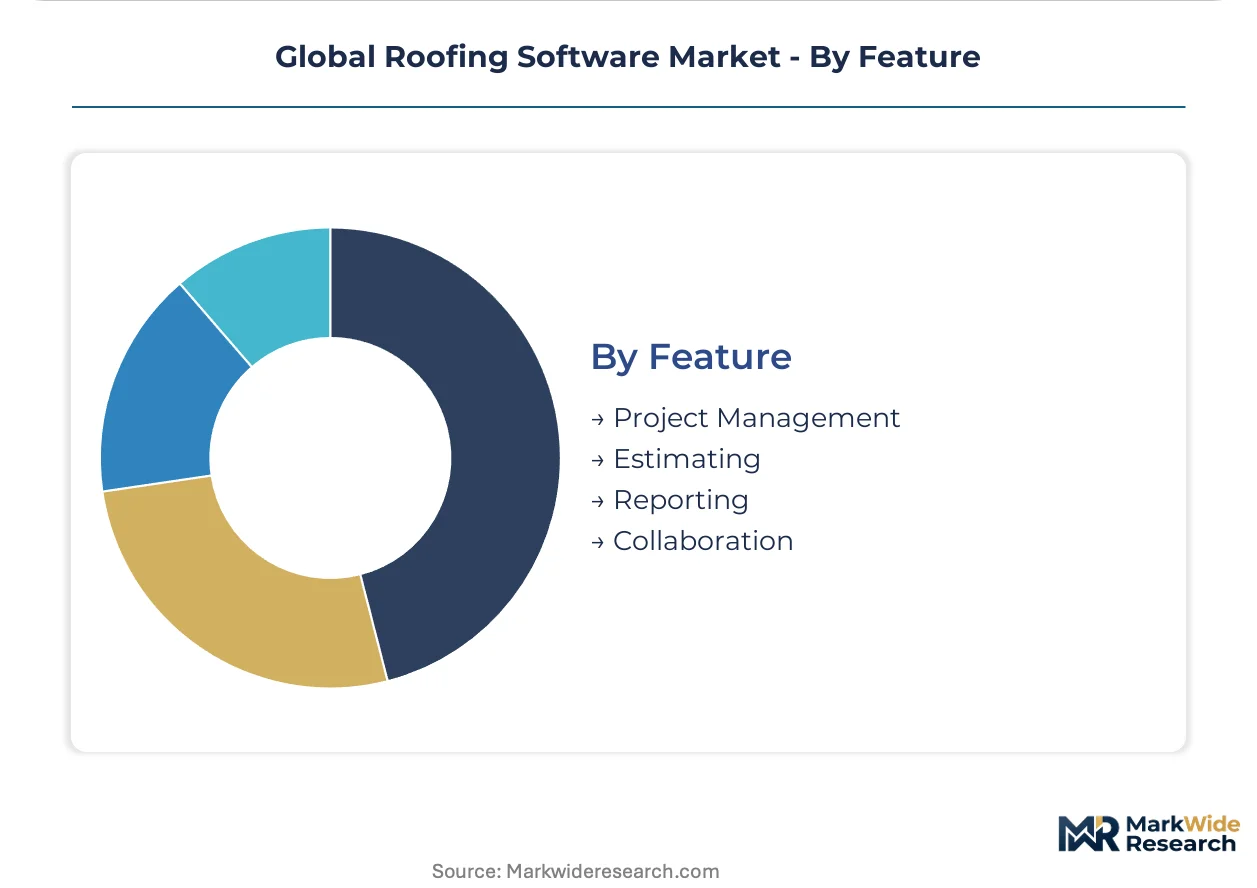
Feature:
Module bundling strategies separate premium platforms from point solutions in competitive positioning.
- Estimating:Aerial imagery integration with sub-inch measurement accuracy and real-time supplier pricing feeds. Commercial contractors in United States metropolitan markets pay premium tiers for multi-supplier API connectivity.
- Project Management:Scheduling, crew dispatch, and progress tracking with mobile offline synchronization. OSHA fall-protection documentation mandates in the United States embed specialized compliance workflows.
- Reporting:Automated closeout packages for warranty submission and regulatory filing. EU Green Deal carbon disclosure requirements expand this module's scope in Germany, France, and Netherlands.
- Collaboration:Multi-stakeholder communication portals connecting contractors, adjusters, and homeowners. Storm restoration specialists in Florida and Oklahoma deploy these for insurance carrier coordination.
Estimating modules generate the highest per-seat pricing; Collaboration features are gaining share fastest as insurance-integrated workflows proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American roofing software deployment, where storm restoration contractors compress bidding cycles through rapid-estimation platforms. The metro's concentration of hail-damage specialists drives cloud-native adoption rates above national averages.
United States
Storm restoration contractors in Florida, Texas, and Oklahoma deploy rapid-estimation platforms to compress bidding-to-award timelines during peak hail and hurricane seasons. OSHA fall-protection documentation mandates embed specialized mobile workflows into procurement decisions. The Dallas-Fort Worth corridor concentrates the highest density of insurance-integrated roofing operations.
Germany
Federal building code transitions to digital permitting workflows accelerate compliance-tracking software procurement among mid-sized commercial contractors. EU Green Deal carbon disclosure requirements expand reporting module scope beyond Western platform defaults. The Rhine-Ruhr industrial cluster leads adoption of thermal modeling integrations for envelope performance verification.
Japan
METI's tightening building energy efficiency standards create demand for thermal modeling modules absent from most imported platforms. General contractors in the Kanto region integrate roofing tools into broader construction management ecosystems under national performance codes. Tokyo-based architectural firms require embedded carbon calculation capabilities for design-phase compliance.
Australia
Rural connectivity gaps degrade cloud synchronization performance, pushing storm response subcontractors toward web-based browser solutions for short-duration contracts. Solo contractors in Queensland and New South Wales enter through freemium channels before converting to paid estimation tiers. Sydney and Melbourne metros concentrate premium-tier subscription growth among residential specialists.
United Kingdom
Post-Grenfell cladding safety regulations extend documentation requirements to roofing systems, pulling compliance modules into standard software specifications. London-based commercial contractors prioritize API connectivity to supplier pricing databases for real-time material cost accuracy. The Southeast England corridor drives collaboration feature adoption for multi-stakeholder warranty coordination.
Global Roofing Software Market Competitive Environment
The competitive structure tilts toward specialized workflow platforms rather than generic construction software suites. Mid-market roofing operations fragment procurement across estimation-centric, project-management-centric, and field-mobility-centric archetypes. Two dominant competitive moves shape positioning: technology licensing partnerships with aerial imagery providers, and vertical integration into embedded contractor financing at the point of estimate.
Within the estimation-specialist tier, EagleView Technologies and STACK Construction Technologies occupy positions defined by sub-inch measurement accuracy and commercial bidding workflow dominance. AccuLynx anchors the contractor-centric archetype with residential market penetration. These three exemplify how North American players concentrate feature development around insurance carrier coordination and storm restoration velocity.
| Leading Market Players |
|---|
| RoofSnap |
| Buildxact |
| JobNimbus |
| FieldPulse |
| EagleView Technologies |
| STACK Construction Technologies |
| AccuLynx |
| Project Manager by Knowify |
| Hover |
| Others |
Value Chain & Pricing Dynamics
Subscription-tier divergence between premium API-integrated suites and basic estimation modules manifests in both customer acquisition costs and cloud infrastructure sourcing strategies. Premium vendors draw from hyperscale server farms in the United States and Germany while economy-tier providers rely on regional hosting partners, creating divergent margin structures and data residency compliance paths.
Pricing Analysis
Value-based pricing anchors on estimator throughput and bid-to-award conversion rates rather than seat counts. Three-tier pricing structure across premium, standard, and economy levels separates full API-integrated platforms from standalone estimation tools and freemium entry points. Price differentiation rests on aerial imagery accuracy grade and OSHA compliance module depth. Pricing pressure stems from mid-market contractors demanding month-to-month terms that align with seasonal revenue volatility. Residential storm-restoration specialists in Florida and Texas show highest price sensitivity; commercial contractors in Germany and Japan accept premium tiers for thermal modeling and carbon reporting capabilities.
Supply Chain Analysis
Logistics costs for aerial imagery licensing and cloud server provisioning concentrate vendor margin pressure in distributed deployment models. Software development and satellite imagery processing concentrate in the United States, Germany, and Japan, with customer success operations distributed regionally. Raw material dependencies include sub-inch orthorectified imagery feeds, hyperscale compute capacity, and supplier pricing API connectivity. Single-source vulnerability runs through dominant aerial imagery providers that control measurement-grade satellite constellations. Distribution runs through direct sales teams for enterprise accounts and self-service portals for contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated workflow platforms as high switching costs and embedded historical data lock weaker point-solution vendors into irreversible decline.
For Market Incumbents: Anchor platform stickiness through backward integration into embedded contractor financing at the point of estimate, capturing recurring revenue streams beyond software subscriptions. Deepen API connectivity to regional supplier pricing databases to defend against emerging estimation specialists. Threat from AI-powered aerial damage assessment tools demands accelerated computer vision R&D investment. Certification investment in EPA ENERGY STAR and EU Green Deal compliance modules represents the critical defensive lever. For New Entrants and Emerging Players: Capture white-space in thermal modeling modules for Japanese METI building energy efficiency standards, where imported platforms lack native capability. Target Australia's rural storm-response subcontractor segment with web-based browser solutions that bypass connectivity infrastructure gaps. Freemium conversion pathways among solo contractors in Queensland and New South Wales offer the most penetrable entry point. Go-to-market angle should emphasize rapid deployment without legacy data migration burdens. For Investors and Strategic Acquirers: Re-rating potential sits with verticalized estimation platforms given solar roofing integration catalysts expanding addressable spend per contractor. Long-term viability favors vendors with embedded finance capabilities and insurance carrier coordination workflows. Acquisition target archetype: mid-sized commercial estimation specialists with sub-inch measurement accuracy and storm-prone United States county penetration. Signal to watch: contractor consolidation rates in Texas and Florida as leading indicator of platform upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies estimation-to-payment workflows for storm restoration contractors in hail-prone United States counties. |
| Strategic Partnership | Aerial imagery licensing agreements with satellite operators secure sub-inch measurement accuracy differentiation. |
| Acquisition of Specialist Firm | Embedded finance capabilities at point of estimate unlock recurring revenue beyond SaaS subscriptions. |
| Geographic Expansion | Thermal modeling module development for Japanese METI building energy efficiency standards addresses capability gaps. |
| Product Launch | AI-powered hail damage assessment tools automate insurance carrier documentation for Florida contractors. |
Study Parameters
Multi-period observation of contractor platform upgrade cycles and regulatory compliance module adoption anchored the trend analysis, supplemented by interviews with roofing software product managers, commercial contractor operations directors, aerial imagery platform engineers, and insurance carrier technology procurement leads. Secondary validation drew from SEC SaaS company filings, EPA ENERGY STAR certification databases, EU Green Deal implementation guidance documents, and METI building energy efficiency standard updates. Bottom-up contractor survey data triangulated against top-down vendor revenue segmentation.
Input-output matrices mapped deployment model transitions, feature module bundling strategies, and end-user pricing tolerance across the projection horizon. Segmentation dimensions modeled include cloud versus on-premise architecture, contractor versus architect versus builder versus manufacturer end-use, subscription versus license commercial terms, and estimating versus project management versus reporting versus collaboration feature depth. CAGRs derived from installer base growth rates, platform spend per contractor, and solar roofing integration penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rural broadband infrastructure buildout pace, supplier pricing API standardization progress, and OSHA documentation mandate enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
MRP Software Market
Software & Services
Global Cinema Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Embedded Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Human Resource Management Software Market
Software & Services
Lighting Control Software Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
K8s Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Workstation Software Market