
 Sodium Cumenesulfonate Market | 2026-2036
Sodium Cumenesulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Cumenesulfonate Market Analysis
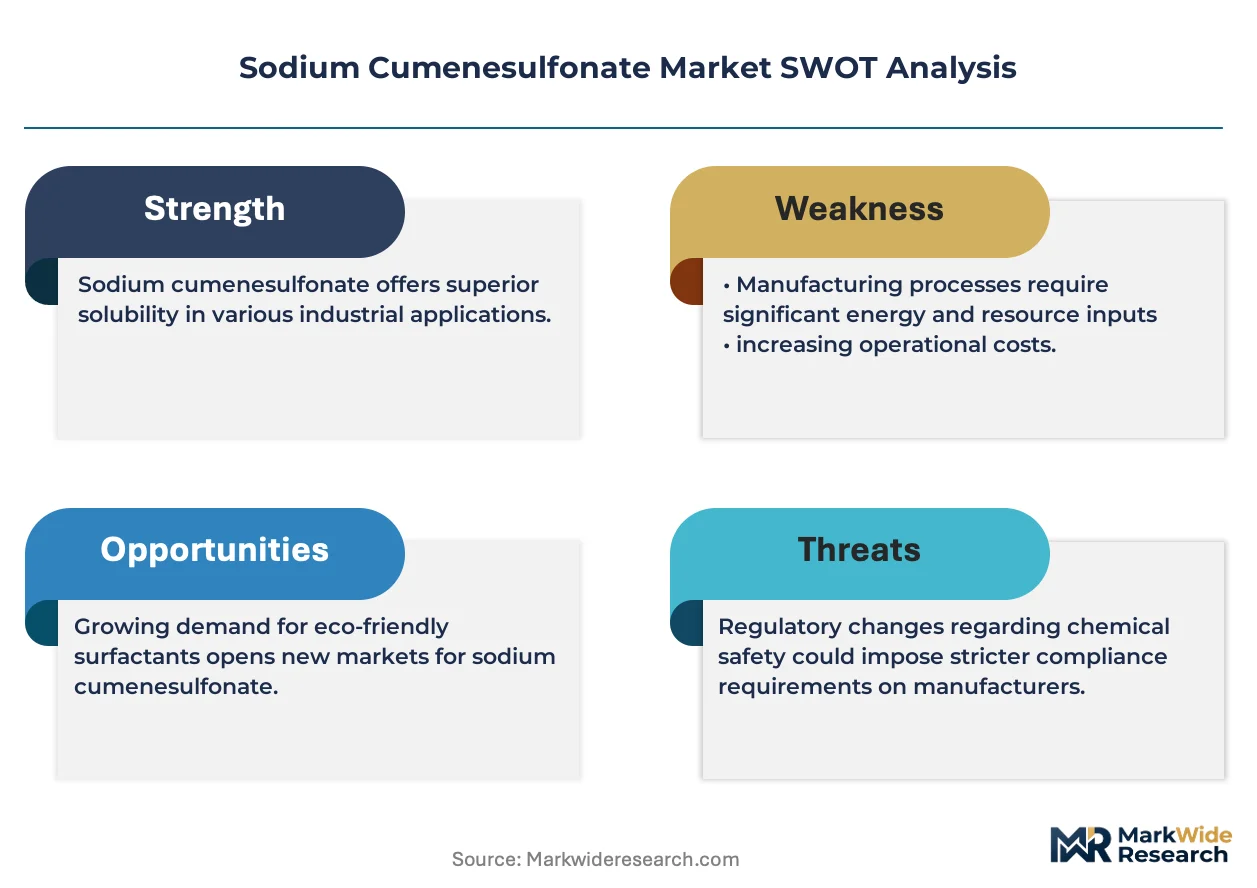
Specialized chemical engineering talent for sulfonation process optimization is reorganizing competitive dynamics among Western suppliers. Solvay S.A. leverages its integrated cumene-to-sulfonate chain to secure feedstock continuity. Stepan Company anchors North American hydrotrope supply through dedicated alkylbenzene sulfonate infrastructure. Kao Corporation differentiates via Japanese pharmaceutical-grade certification protocols that command premium positioning.
Sodium cumenesulfonate is an alkylbenzene sulfonate salt produced through sulfonation of cumene followed by neutralization, typically supplied as a clear aqueous solution with active content ranging from 30% to 60%. It functions primarily as a hydrotrope, solubilizing hydrophobic surfactants and improving formulation stability in concentrated liquid detergents and industrial cleaners. Liquid formulations dominate volume flows due to compatibility with automated dosing systems in textile processing and coatings manufacturing. Powder grades serve pharmaceutical tablet disintegrant applications where anhydrous handling properties reduce caking risk. Surfactant applications capture the broadest end-use footprint, though dispersant demand in pigment grinding operations is expanding fastest among coatings producers seeking VOC-compliant grinding aids.
EPA toxicity testing requirements under TSCA Section 5 govern new chemical introductions in the United States, while REACH registration dossiers in Europe mandate comprehensive ecotoxicological data for cumene derivatives above one-tonne thresholds. China's MEE enforces GB standards for anionic surfactant discharge into wastewater treatment networks, pressuring domestic producers toward closed-loop sulfonation systems. Stakeholders must monitor regulatory divergence between OECD-aligned hazard assessment protocols and emerging national chemical inventories that could fragment product registration requirements.
Market Dynamics
REACH registration dossiers and EPA toxicity testing under TSCA Section 5 are fragmenting product approval timelines, forcing hydrotrope suppliers to maintain parallel compliance infrastructures across Atlantic and Pacific regulatory zones.
Growth Catalysts
- Specialty surfactant demand:Personal care formulators in Asia-Pacific manufacturing clusters are reorganizing procurement patterns toward certified hydrotrope grades.
- REACH compliance tightening:ECHA purity specifications for cumene derivatives are accelerating replacement of legacy hydrotrope formulations in European liquid detergent production.
- Closed-loop sulfonation systems:China's MEE wastewater discharge standards are pressuring domestic producers toward process upgrades that yield higher-active-content aqueous solutions.
Market Restraints
- Cumene feedstock volatility:Benzene-propylene cracking economics concentrate input cost risk with integrated petrochemical majors.
- Supply concentration in Yangtze River Delta:Domestic Chinese cumene derivative capacity scaling creates single-geography dependency for volume procurement.
- Xylene sulfonate substitution:Alternative alkylbenzene sulfonate salts compete on cost in industrial cleaner formulations where pharmaceutical-grade certification is not required.
Strategic Opportunities
- Pharmaceutical-grade certification:Japanese PMDA-aligned protocols command premium positioning in tablet disintegrant applications.
- VOC-compliant grinding aids:Coatings producers seeking pigment dispersant alternatives are expanding fastest among hydrotrope applications.
- Automated dosing compatibility:Textile processing and coatings manufacturing are shifting volume flows toward liquid formulations with 40-60% active content.
Industry Challenges
- Sulfonation process optimization expertise:Specialized chemical engineering talent scarcity limits Western suppliers' ability to defend yield rates against Asian cost structures.
- Parallel registration timelines:Divergence between OECD-aligned hazard assessment protocols and emerging national chemical inventories fragments product introduction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Cumenesulfonate Market |
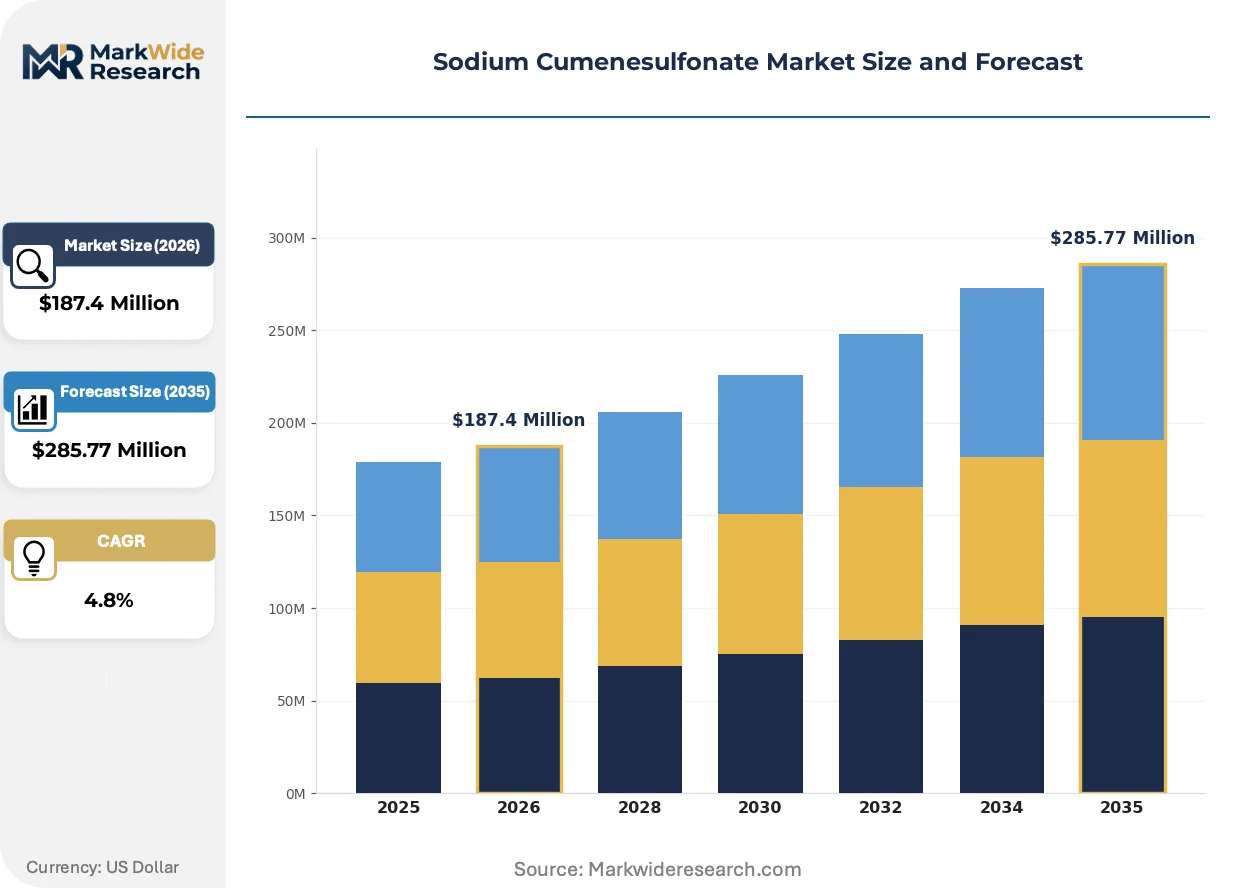
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Solid End Use Industry: Textiles, Pharmaceuticals, Coatings, Personal Care Application: Surfactant, Dispersant, Wetting Agent, Stabilizer Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Solvay S.A., Nease Corporation, BASF SE, Sasol, Enaspol A.S., Clariant AG, Kao Corporation, Innospec, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Cumenesulfonate Market Emerging Trajectories
Formulation chemistry and regulatory data requirements are compressing product development cycles while expanding the addressable application set for high-purity hydrotrope grades.
Continuous sulfonation reactor technology is miniaturizing. This equipment reduces neutralization stage residence time while improving active content consistency. Coatings manufacturers adopting mini-plant configurations are compressing batch qualification timelines from months to weeks.
EPA oversight under TSCA Section 5 is extending pre-manufacture notification review periods for new cumene derivative introductions. The industrial consequence is defensive patenting of existing sulfonation process conditions. Hydrotrope suppliers serving North American textile processing are responding by dual-registering formulations under both EPA and REACH dossier structures.
Buyer concentration among personal care multinationals is consolidating formulation specification authority. Direct supplier relationships are displacing distributor intermediaries in Asia-Pacific procurement. This pattern is most visible in China's Yangtze River Delta chemical corridor, where domestic producers now negotiate directly with brand-owner technical teams.
Sodium Cumenesulfonate Market Segmentation
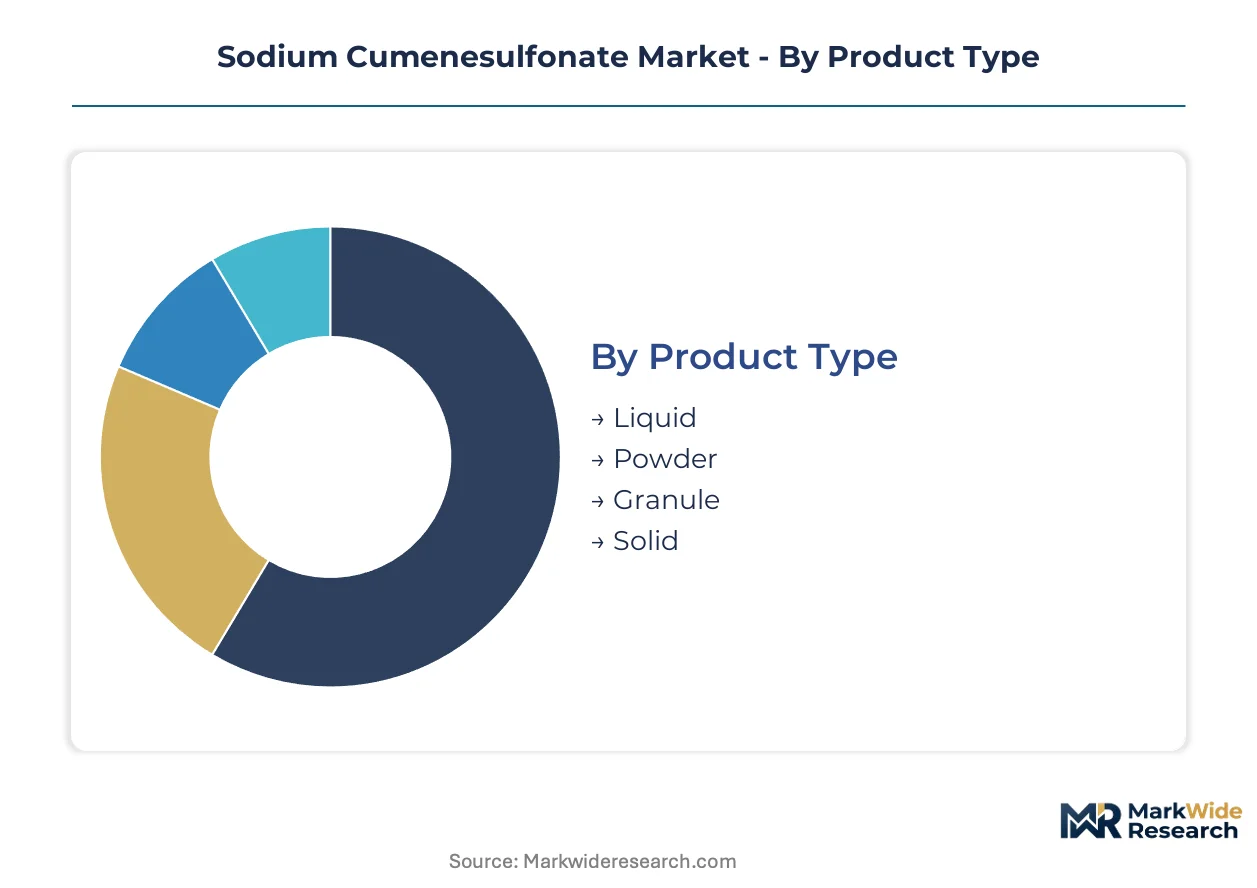
Sodium cumenesulfonate procurement patterns diverge sharply across physical forms and application contexts, with regulatory compliance tiers—REACH dossier depth, EPA TSCA registration status, and pharmaceutical-grade certification—creating distinct commercial boundaries between otherwise chemically identical products.
Product Type:
REACH registration dossiers and EPA toxicity testing under TSCA Section 5 impose divergent purity specifications across physical forms, fragmenting supplier qualification requirements.
- Liquid:Aqueous solutions with 30-60% active content serve automated dosing systems in textile processing and coatings manufacturing. China's Yangtze River Delta chemical corridor dominates volume production, with domestic cumene derivative capacity scaling pressuring Western suppliers on cost.
- Powder:Anhydrous grades eliminate caking risk in pharmaceutical tablet disintegrant applications. Japanese PMDA-aligned certification protocols command premium positioning where moisture sensitivity governs formulation stability.
- Granule:Intermediate handling properties suit industrial cleaner compounding where flowability requirements sit between liquid dosing convenience and powder storage density.
- Solid:Compressed or crystalline forms address specialized logistics constraints in remote manufacturing locations lacking aqueous handling infrastructure.
Established volume favors Liquid; emerging adoption favors Powder.
End Use Industry:
Customer concentration patterns reorganize procurement authority, with personal care multinationals consolidating direct supplier relationships and displacing distributor intermediaries.
- Personal Care:Specialty surfactant demand from formulators in Asia-Pacific manufacturing clusters is reorganizing procurement patterns toward certified hydrotrope grades. Direct technical negotiations between brand owners and producers now dominate China's Yangtze River Delta corridor.
- Coatings:VOC-compliant grinding aid applications are expanding fastest among pigment dispersant alternatives. Mini-plant sulfonation configurations compress batch qualification timelines from months to weeks for coatings manufacturers.
- Pharmaceuticals:Tablet disintegrant specifications require pharmaceutical-grade certification that fragments supplier pools. Japanese PMDA protocols and FDA oversight create dual-registration burdens for serving both Pacific and Atlantic markets.
- Textiles:Automated processing lines favor liquid formulations with precise active content consistency. Closed-loop sulfonation systems in China respond to MEE wastewater discharge standards while yielding higher-active-content solutions.
Personal Care commands margin premiums; Coatings delivers the steepest expansion trajectory.
Application:
Functional differentiation in formulation chemistry determines price realization, with hydrotrope solubilization commanding broader volume than specialized dispersant roles.
- Surfactant:Hydrotrope functionality solubilizes hydrophobic surfactants in concentrated liquid detergents and industrial cleaners. REACH compliance tightening in Europe accelerates replacement of legacy formulations with ECHA-purity-specified grades.
- Dispersant:Pigment grinding operations in coatings manufacturing seek VOC-compliant alternatives to traditional grinding aids. Continuous sulfonation reactor miniaturization enables rapid qualification of dispersant-grade specifications.
- Wetting Agent:Surface tension reduction properties serve niche industrial cleaner formulations where xylene sulfonate substitution threatens cost-competitive positioning.
- Stabilizer:Formulation integrity maintenance in multi-component liquid systems addresses stability challenges in automated dosing environments.
Surfactant anchors volume scale; Dispersant captures application expansion.
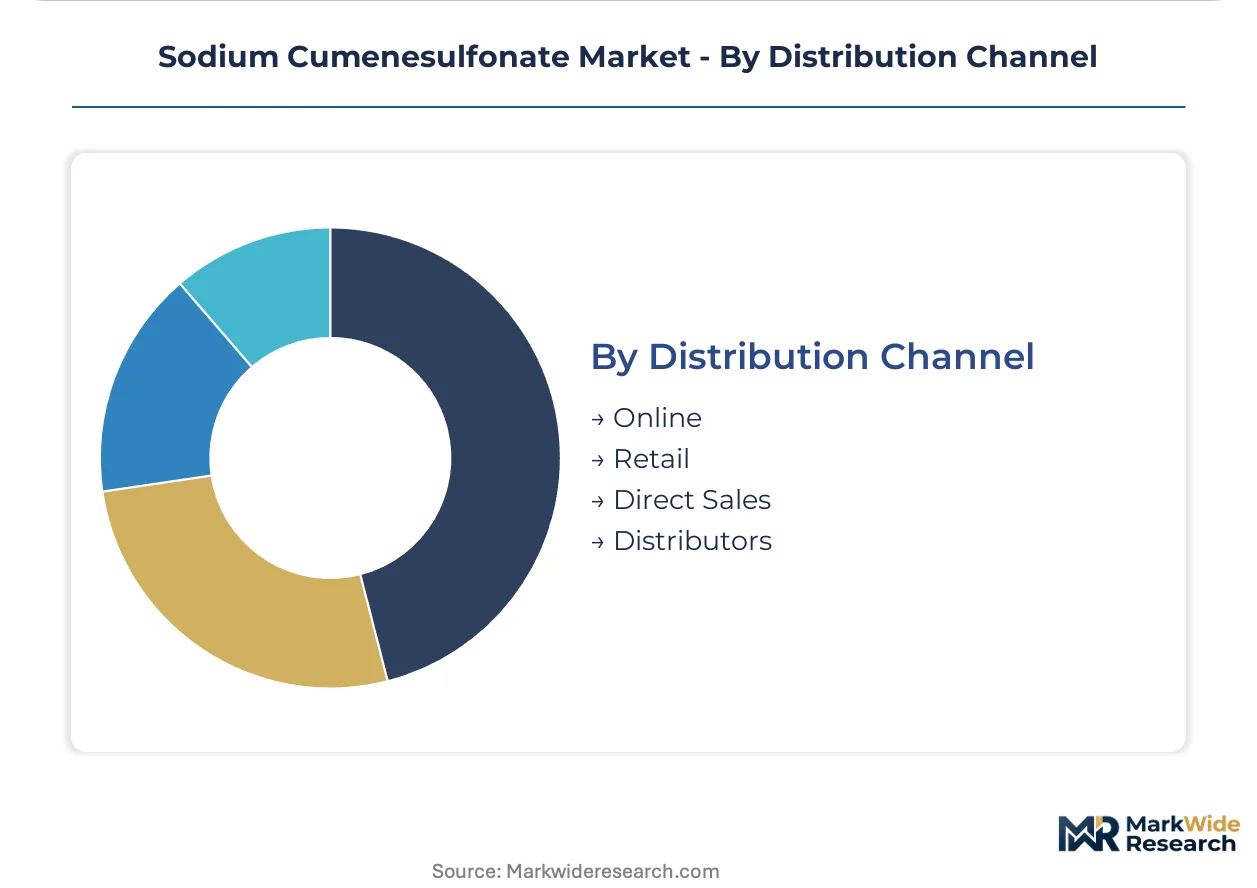
Distribution Channel:
Supply chain configuration determines market access economics, with technical specification authority shifting channel power toward direct relationships.
- Direct Sales:Technical teams at personal care multinationals negotiate directly with producers in China's Yangtze River Delta, eliminating distributor margins. Procurement pattern consolidation favors suppliers with integrated cumene-to-sulfonate chains.
- Distributors:Regional chemical distributors retain relevance in fragmented industrial cleaner markets where formulation volumes do not justify direct supplier development costs.
- Online:Digital procurement platforms serve small-volume pharmaceutical and specialty coatings formulators requiring rapid sample access and documentation retrieval.
- Retail:Limited relevance given industrial and institutional customer concentration; occasional presence in specialty chemical trade channels serving research laboratories.
Direct Sales concentrates value capture; Online channels address geographic fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE wastewater discharge standards in China are reorganizing production economics across the sodium cumenesulfonate supply base. REACH dossier requirements in Europe and EPA oversight in the United States fragment compliance architectures. Industrial clusters in Germany, Japan, and the Yangtze River Delta concentrate technical specification authority.
China
Specialty surfactant procurement from personal care multinationals is reorganizing direct technical negotiations in the Yangtze River Delta. MEE enforces GB standards for anionic surfactant discharge into wastewater treatment networks. Domestic cumene derivative capacity scaling in Jiangsu and Zhejiang provinces pressures Western suppliers on cost.
United States
Textile processing and coatings manufacturing drive automated dosing system demand for 40-60% active content liquid formulations. EPA toxicity testing under TSCA Section 5 governs new chemical introductions and extends pre-manufacture notification review periods. Gulf Coast petrochemical infrastructure anchors cumene feedstock supply for hydrotrope producers.
Germany
ECHA purity specifications for cumene derivatives accelerate replacement of legacy hydrotrope formulations in liquid detergent production. REACH registration dossiers mandate comprehensive ecotoxicological data above one-tonne thresholds. The Ruhr industrial region concentrates sulfonation process optimization expertise among Western suppliers.
Japan
Pharmaceutical-grade tablet disintegrant applications command premium positioning through PMDA-aligned certification protocols. METI industrial standards govern chemical manufacturing quality assurance. The Kansai chemical corridor, particularly Osaka and surrounding prefectures, anchors domestic hydrotrope production for Asian pharmaceutical markets.
Sodium Cumenesulfonate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the sodium cumenesulfonate market. Integrated petrochemical majors with captive cumene supply compete against specialized sulfonation houses with process optimization expertise. Two strategic archetypes dominate: backward-integrated feedstock controllers and certification-focused specialty formulators. Competitive moves concentrate on capacity expansion in China's Yangtze River Delta and dual-registration dossier filing under both EPA and REACH structures.
Among European-based integrated chemical producers, Solvay S.A. and BASF SE exemplify the feedstock-control archetype through their cumene derivative chains. Stepan Company represents the North American hydrotrope specialist model with dedicated alkylbenzene sulfonate infrastructure. Kao Corporation occupies a position within the premium-tier certification segment through Japanese pharmaceutical-grade protocols.
| Leading Market Players |
|---|
| Solvay S.A. |
| Nease Corporation |
| BASF SE |
| Sasol |
| Enaspol A.S. |
| Clariant AG |
| Kao Corporation |
| Innospec |
| Stepan Company |
| Others |
Supply Flow & Price Mechanics
REACH registration dossiers and EPA TSCA Section 5 compliance simultaneously gate supplier qualification and stratify price realization, with ECHA-purity-specified grades commanding substantial premiums over industrial-grade alternatives while legacy formulations face accelerated replacement economics.
Pricing Analysis
China's Yangtze River Delta producers undercut Western suppliers by double-digit percentage spreads on standard-grade liquid formulations. Three-tier pricing structure across pharmaceutical-grade, REACH-certified, and industrial-grade levels reflects certification investment recovery and feedstock integration advantages. Price differentiation hinges on active content consistency and dual-registration dossier completeness. Cost compression in standard-grade liquids is intensifying because domestic Chinese cumene derivative capacity scaling eliminates import dependency premiums. Industrial cleaner formulators exhibit highest price sensitivity; pharmaceutical tablet disintegrant buyers accept premium positioning for PMDA-aligned certification.
Supply Chain Analysis
Inventory cycles compress to six-to-eight weeks for coatings manufacturers adopting mini-plant sulfonation configurations. Production gravity centers on China, Germany, and Japan, with Jiangsu and Zhejiang provinces anchoring volume supply. Feedstock draws from benzene-propylene cracking economics tethered to Gulf Coast and Rotterdam petrochemical complexes. Single-geography dependency in the Yangtze River Delta creates concentrated disruption exposure from MEE enforcement actions. Distribution runs through direct technical relationships with personal care multinationals, displacing regional distributor intermediaries in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sulfonation process optimization expertise scarcity constrains Western suppliers' yield defense against Asian cost structures, creating asymmetric capability gaps that determine competitive viability across certification tiers.
For Market Incumbents: Secure captive cumene supply through backward integration or long-term offtake agreements with Rotterdam or Gulf Coast petrochemical complexes. Defend yield rates by investing in continuous reactor miniaturization technology that compresses neutralization residence time. Counter xylene sulfonate substitution threats in industrial cleaner segments through pharmaceutical-grade certification anchoring in tablet disintegrant applications. For New Entrants and Emerging Players: Lead with VOC-compliant grinding aid formulations targeting coatings manufacturers seeking pigment dispersant alternatives outside legacy hydrotrope supply relationships. Penetrate the dispersant application segment where continuous sulfonation reactor adoption enables rapid batch qualification against established surfactant-grade suppliers. Deploy mini-plant configurations to compress technical qualification timelines from months to weeks. For Investors and Strategic Acquirers: EPA TSCA Section 5 review period extensions reshape the acquisition landscape toward dual-registered asset targets with existing REACH dossier depth. Prioritize specialized sulfonation houses with process optimization expertise over commodity-scale producers lacking certification infrastructure. Watch ECHA purity specification tightening velocity as the signal indicating premium-grade margin expansion versus industrial-grade commoditization trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene Supply | Captive feedstock secures margin defense against benzene-propylene volatility at Rotterdam and Gulf Coast hubs. |
| Dual-Registration Dossier Filing | Parallel EPA and REACH compliance opens transatlantic procurement channels for personal care multinationals. |
| Continuous Reactor Miniaturization | Mini-plant configurations enable coatings producers to compress batch qualification timelines significantly. |
| Pharmaceutical-Grade Certification Investment | PMDA-aligned protocols command premium positioning in tablet disintegrant applications with moisture-sensitive formulations. |
| Closed-Loop Sulfonation System Deployment | MEE-compliant wastewater handling yields higher-active-content solutions while reducing discharge penalty exposure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and Cefic industry reports through structured interviews with plant managers, procurement leads at downstream detergent and coatings OEMs, distribution channel partners, and technical R&D directors specializing in sulfonation process optimization. Bottom-up volume modeling triangulates against top-down value chain analysis across the projection horizon.
Segmentation dimensions modeled span physical form tier, end-use industry concentration, functional application role, and regional regulatory compliance cluster throughout the forecast period. CAGRs derive from weighted average growth assumptions applied to volume trajectories in each segment, with specific inputs including MEE enforcement intensity in Jiangsu province, ECHA purity specification revision schedules, and coatings industry VOC regulation adoption curves.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and China's GB standards regimes; material policy shifts including cumene derivative hazard reclassification or anionic surfactant discharge prohibition would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Natural Surfactants Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Alkylamines Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Polymer Surfactants Market
Surfactants
Global Detergent Polymers Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Glycol Monostearate Market
Surfactants
Zeolite for Detergents Market
Surfactants
Dispersant Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Cetyl Chloride Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Cationic Surfactants Market