
 Air Conditioner Remote Control Market | 2026-2036
Air Conditioner Remote Control Market Size, Share, and Industry Trends Forecast 2026-2036
Air Conditioner Remote Control Market Analytics
Asset-light manufacturing partnerships and third-party ODM financing is reconfiguring competitive entry barriers for peripheral electronics, allowing new contenders to scale without captive fabrication. Daikin Industries leverages its captive component ecosystem to control quality across remote production lines. LG Electronics anchors its position through deep integration with its HVAC installed base. Honeywell International Inc. differentiates by specializing in enterprise-grade wireless protocols for commercial building management systems.
An air conditioner remote control is a handheld or wall-mounted transmitter that encodes user commands into infrared, radio frequency, or digital wireless signals to regulate temperature, fan speed, and operational modes across cooling systems; contemporary units incorporate MEMS sensors, low-power Bluetooth 5.0 modules, and voice-recognition chipsets to enable precise environmental management. Smart remotes and Wi-Fi-enabled units command premium positioning as consumers prioritize app-based scheduling and energy analytics, while infrared variants retain volume dominance in replacement channels across price-sensitive markets. The hospitality end-user segment is concentrating procurement around unified property management interfaces that consolidate climate control with lighting and access systems.
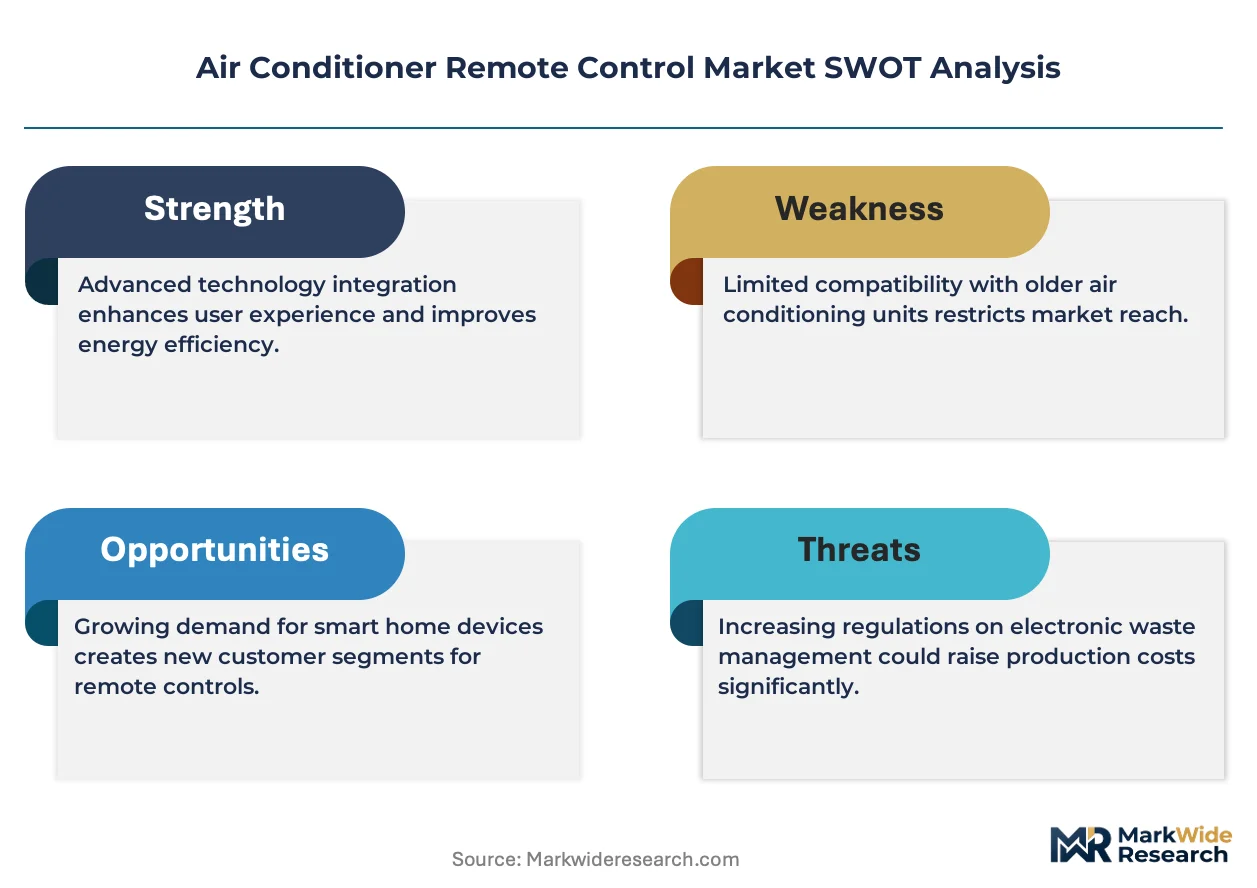
The US FCC governs RF emission thresholds for wireless remote controls, while China's MIIT certifies domestic Zigbee and Wi-Fi implementations under GB standards; India's WPC mandates frequency authorization for RF remotes operating in unlicensed bands. Compliance with these frameworks determines market access timelines and testing cost structures for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving interoperability mandates as building automation standards converge around Matter protocol specifications.
Market Dynamics
Asset-light manufacturing partnerships and third-party ODM financing are reconfiguring competitive entry barriers for peripheral electronics, allowing new contenders to scale without captive fabrication while established players defend through component ecosystems and HVAC integration depth.
Growth Catalysts
- Residential smart home adoption:India's urban residential sector is accelerating demand as rising temperatures and electrification expand air conditioner penetration. Wi-Fi-enabled remotes with app-based scheduling command premium positioning.
- GB standards for wireless interoperability:China's MIIT certification requirements under GB standards are tightening product compliance, filtering out subscale manufacturers and consolidating quality-tier supply.
- Hospitality procurement consolidation:Property management interfaces that consolidate climate control with lighting and access systems are concentrating volume around unified building automation vendors.
Market Restraints
- RF component cost volatility:Bluetooth 5.0 modules and MEMS sensors face input price pressure from semiconductor foundry capacity allocation, compressing margin on mid-tier units.
- Frequency authorization friction:India's WPC mandates for unlicensed band operation add testing timelines and certification costs that delay market entry for RF remote variants.
- Infrared substitution ceiling:Legacy infrared remotes retain volume dominance in replacement channels across price-sensitive markets, limiting premium smart remote penetration rates.
Strategic Opportunities
- Matter protocol convergence:Building automation standards converging around Matter specifications create interoperability white space for remotes bridging HVAC with broader smart home ecosystems.
- Enterprise-grade wireless specialization:Commercial building management systems present underserved demand for enterprise-grade protocols beyond residential-grade Bluetooth implementations.
- Energy analytics integration:Low-power chipsets enabling consumption tracking and predictive maintenance represent unexpressed value capture in utility-partnered distribution channels.
Industry Challenges
- Multi-jurisdiction certification complexity:Manufacturers targeting US FCC emission thresholds alongside China's MIIT GB standards and India's WPC authorization face fragmented testing cost structures and timeline coordination.
- Legacy HVAC integration friction:Smart remotes must maintain backward compatibility with installed base infrared receivers while enabling forward-compatible digital wireless, complicating firmware architecture and QA cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Conditioner Remote Control Market |
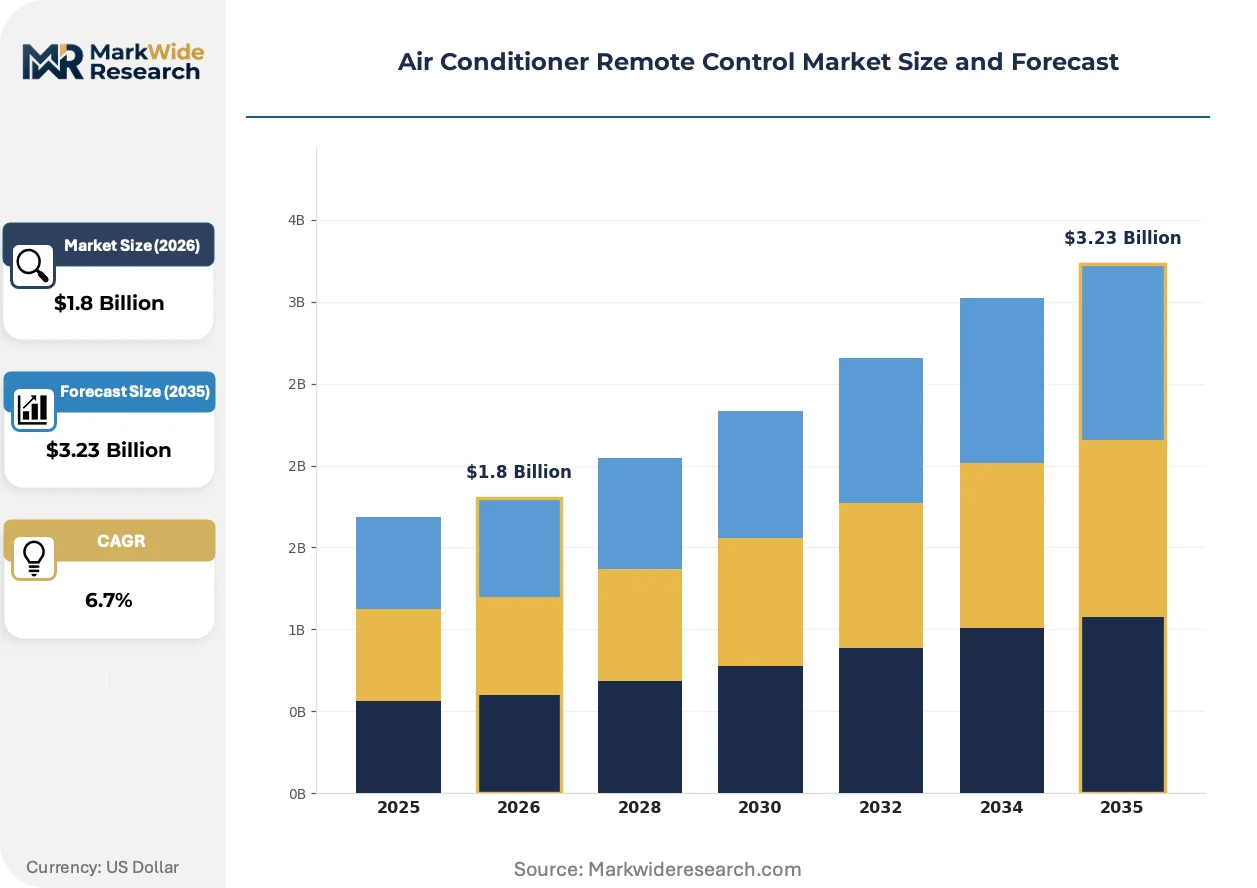
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Remote, Bluetooth Remote, Smart Remote, Universal Remote Technology: Wi-Fi, Zigbee, Infrared, RF End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Daikin Industries, Ltd., Johnson Controls, Carrier Global Corporation, Honeywell International Inc., Emerson Electric Co., Schneider Electric, Siemens AG, Mitsubishi Electric Corporation, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Conditioner Remote Control Market Evolving Landscape
Voice-recognition chipsets and low-power wireless modules are collapsing the functional boundary between standalone remotes and integrated smart home hubs, forcing a repositioning of the entire peripheral category.
MEMS sensors embedded in contemporary remotes are collapsing the distinction between environmental sensing and control command, enabling occupancy-based climate adjustment without separate thermostat hardware. Hospitality operators and premium residential developers are adopting these units fastest, compressing the addressable market for discrete temperature sensors while expanding remote control ASPs through bundled functionality.
The US FCC's RF emission thresholds are tightening testing documentation requirements for wireless remote controls, extending certification timelines by forcing additional spurious emission verification. Manufacturers are responding by front-loading compliance engineering into product development rather than treating certification as a final-stage gate, particularly for units targeting simultaneous FCC and China MIIT approval.
Buyer concentration around unified property management platforms is compressing procurement cycles for standalone remote vendors, as hospitality chains and multi-family developers consolidate climate control purchasing with lighting and access system vendors. This bundling is most visible in India's urban commercial construction and US Sun Belt hospitality development, where integrated building automation specifications are displacing discrete HVAC accessory procurement.
Air Conditioner Remote Control Market Segmentation
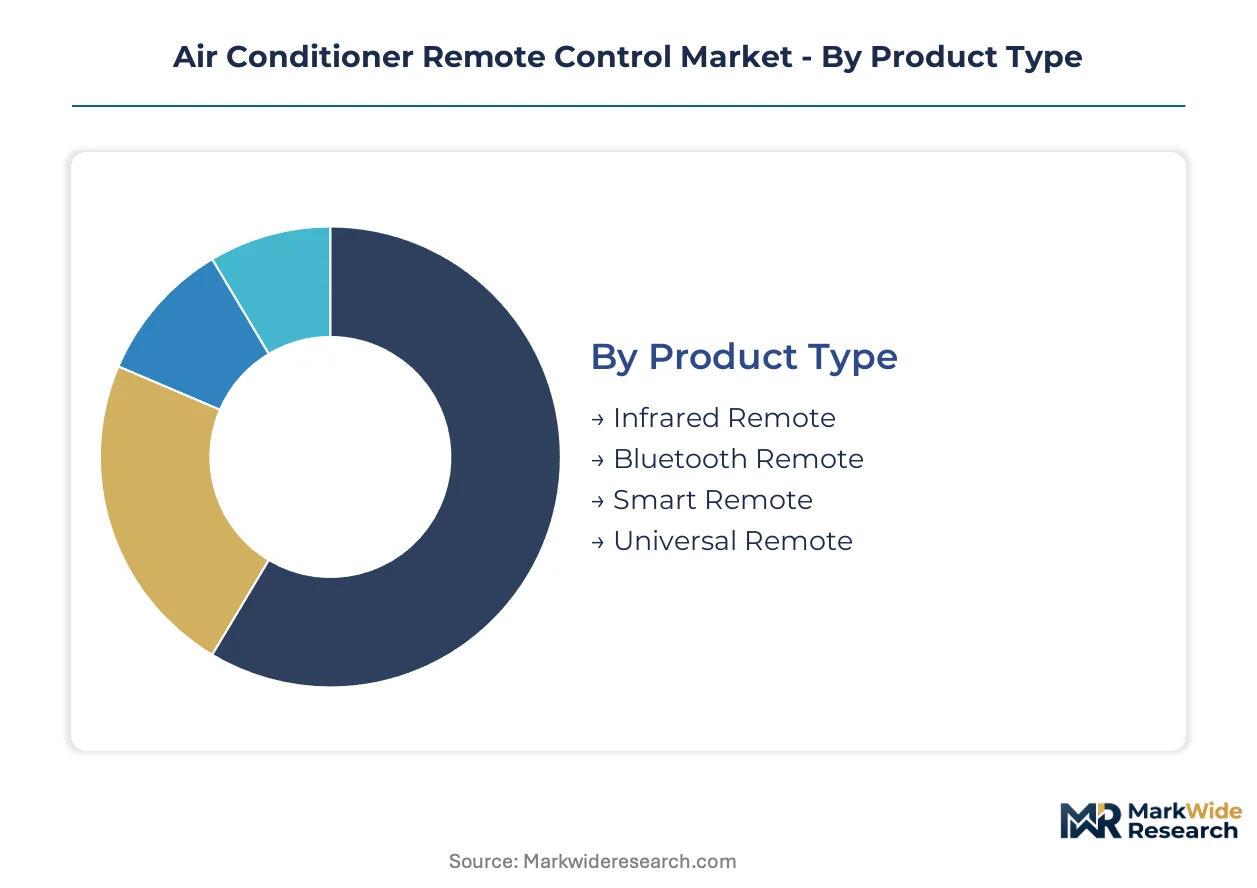
Remote control segmentation determines warranty exposure, replacement cycle forecasting, and inventory staging across aftermarket channels. Product type and technology choices directly correlate with service call frequency and customer support infrastructure requirements.
Product Type:
After-sales-service intensity varies dramatically by product type, with smart remotes requiring firmware update support and universal remotes driving highest compatibility-related return rates.
- Smart Remote:Embedded MEMS sensors, voice-recognition chipsets, and low-power Bluetooth 5.0 modules enable app-based scheduling and energy analytics. Demand concentrates in India's urban residential sector where electrification and rising temperatures expand air conditioner penetration; premium positioning commands higher ASPs but requires ongoing cloud service support.
- Infrared Remote:Legacy encoding architecture using near-infrared LEDs at 940nm wavelength dominates replacement channels. Volume concentrates in price-sensitive emerging markets where installed base infrared receivers remain prevalent; margin compression limits manufacturer investment in durability improvements.
- Bluetooth Remote:Point-to-point wireless connectivity eliminating line-of-sight constraints, typically integrating with smartphone companion apps for expanded functionality.
- Universal Remote:Multi-device code databases supporting cross-brand HVAC operation, experiencing elevated return rates due to incomplete compatibility matrices.
Infrared remotes hold the largest share; momentum sits with smart remotes.
Technology:
Certification cost tiering separates these technologies, with Wi-Fi and Zigbee requiring MIIT GB standards compliance in China and FCC emission testing in the US.
- Wi-Fi:Full TCP/IP stack implementation enabling cloud connectivity and over-the-air firmware updates. Residential smart home adoption in India's urban markets accelerates penetration; China's tightening GB standards for wireless device interoperability filter subscale manufacturers and consolidate quality-tier supply.
- Infrared:Unidirectional optical transmission at 38kHz carrier frequency requiring direct line-of-sight. Replacement channel dominance across price-sensitive markets constrains premium migration; no RF certification requirements reduce regulatory friction for multi-jurisdiction distribution.
- Zigbee:Mesh networking protocol operating in 2.4GHz unlicensed band, favored for building automation integration.
- RF:Proprietary radio frequency implementations in sub-GHz bands, common in commercial multi-zone systems.
Infrared technology holds the largest share; Wi-Fi is climbing the fastest.
End User:
Customer type determines procurement cycle length and specification complexity, with hospitality and commercial buyers consolidating volume around unified building automation vendors.
- Hospitality:Property management interfaces consolidating climate control with lighting and access systems drive procurement concentration. India's urban commercial construction and US Sun Belt hospitality development displace discrete HVAC accessory purchasing; bundled specifications favor vendors with enterprise-grade wireless protocol expertise.
- Residential:Individual consumer purchases through retail and online channels, segmented by smart home adoption intensity.
- Commercial:Multi-tenant buildings and office complexes requiring centralized control integration.
- Industrial:Heavy-duty specifications for manufacturing environments with extended operating temperature ranges.
Residential holds the largest share; hospitality is gaining share fastest.
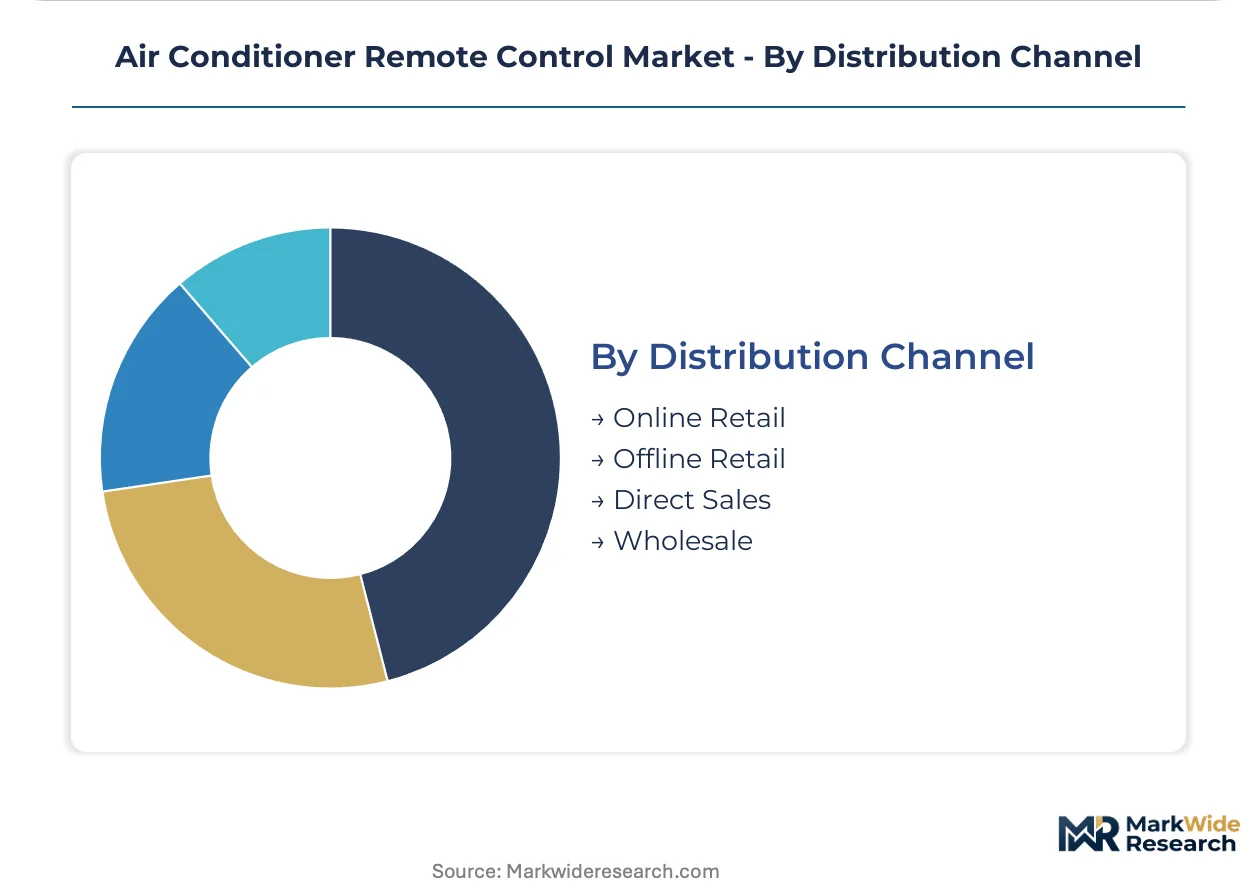
Distribution Channel:
Volume concentration patterns favor wholesale for OEM bundling and online retail for replacement and upgrade purchases.
- Online Retail:E-commerce platforms capturing smart remote and universal remote demand from tech-forward consumers. India's electrification expansion drives first-time buyer traffic; app-enabled product demonstrations and comparison tools reduce friction for Wi-Fi-enabled unit selection.
- Wholesale:Bulk procurement by HVAC installers and property developers for new construction and system replacement. China's manufacturing base supplies cost-optimized infrared units for price-sensitive markets; inventory pooling reduces working capital requirements for regional distributors.
- Offline Retail:Electronics specialty stores and home improvement chains serving immediate replacement needs.
- Direct Sales:Manufacturer-owned channels for enterprise and hospitality accounts requiring customized integration support.
Wholesale holds the largest share; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in air conditioner remote controls track the geographic dispersion of HVAC manufacturing and smart home adoption intensity. China maintains a substantial export surplus in infrared and basic RF units, while the United States and Germany import premium Wi-Fi-enabled variants for residential and commercial retrofit markets.
China
Domestic electrification campaigns and GB standards tightening under MIIT certification are filtering subscale manufacturers from the supply base. Shenzhen and Dongguan manufacturing clusters concentrate ODM production for global brands, with component ecosystems supporting rapid prototyping of Bluetooth 5.0 and Zigbee modules.
United States
Sun Belt residential construction and hospitality development in Florida, Texas, and Arizona are accelerating procurement of unified building automation interfaces. FCC emission threshold documentation requirements are extending certification timelines, particularly for dual-protocol units targeting simultaneous domestic and export markets.
India
Urban residential electrification in Maharashtra, Karnataka, and Tamil Nadu is expanding first-time air conditioner penetration and replacement remote demand. WPC frequency authorization mandates for unlicensed band RF operation are adding testing costs that disadvantage smaller importers against established domestic distributors.
Germany
Commercial building retrofit programs and Energieeffizienz standards are concentrating procurement around enterprise-grade wireless protocols for multi-zone climate management. Bavaria and North Rhine-Westphalia industrial clusters host system integrators bundling HVAC controls with broader building automation specifications.
Japan
Residential smart home adoption in Greater Tokyo and Osaka-Kobe corridors sustains demand for voice-recognition and MEMS-enabled remotes with predictive maintenance functionality. METI efficiency regulations and JIS interoperability standards are compressing replacement cycles as consumers upgrade to ecosystem-integrated units.
Air Conditioner Remote Control Market Competitive Landscape
On the supply side, the industry is bifurcated between captive producers serving integrated HVAC manufacturers and independent ODMs supplying aftermarket channels. Tier-one electronics conglomerates leverage component ecosystems and brand recognition, while mid-scale specialists compete on certification agility and customization velocity. Strategic archetypes include vertically integrated HVAC OEMs, third-party ODM platforms, and building automation system integrators. Dominant competitive moves encompass geographic certification pre-positioning and protocol convergence around Matter specifications.
Within the integrated HVAC tier, Daikin Industries, Ltd. and LG Electronics Inc. exemplify archetypes leveraging captive component ecosystems to control quality across distributed production. Honeywell International Inc. occupies a position representing enterprise-grade wireless specialization for commercial building management systems, anchoring the protocol-agnostic integration segment.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Johnson Controls |
| Carrier Global Corporation |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Schneider Electric |
| Siemens AG |
| Mitsubishi Electric Corporation |
| LG Electronics Inc. |
| Others |
Value Network & Pricing Analysis
Shenzhen and Dongguan manufacturing clusters concentrate Bluetooth 5.0 module and MEMS sensor production, anchoring margin pools in Wi-Fi-enabled smart remotes while infrared assembly migrates to lower-cost inland provinces. Component ecosystem density in China's Pearl River Delta directly shapes where manufacturers can extract premium pricing versus commodity positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with Wi-Fi-enabled units commanding spreads over infrared equivalents based on certification grade and after-sales cloud service bundling. Price differentiation separates FCC/MIIT dual-certified variants from single-jurisdiction units, while RF component cost volatility from semiconductor foundry allocation is compressing margins on mid-tier Bluetooth remotes. Hospitality procurement consolidation around unified building automation vendors exhibits lowest price sensitivity; replacement channel distributors in India's price-sensitive urban markets face highest pressure.
Supply Chain Analysis
Foxconn, BYD Electronics, and Tonly Electronics hold dominant contract manufacturing capacity for remote control assembly, with backend testing and firmware loading concentrated in their Vietnam and Mexico facilities to hedge tariff exposure. Raw material dependencies draw from Taiwan for Bluetooth chipsets, Japan for precision MEMS sensors, and South Korea for display modules. Single-source vulnerability in 2.4GHz RF front-end components presents structural risk given India's WPC authorization bottlenecks. Distribution runs through HVAC installer wholesale networks for new construction volume, while online retail captures replacement and upgrade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone app-based climate control and voice-activated home hubs threaten standalone remote obsolescence, forcing incumbents to defend substitution through embedded functionality expansion.
For Market Incumbents: Harden ecosystem lock-in by deepening captive component ecosystems around voice-recognition chipsets and MEMS sensors that smartphone apps cannot replicate. Prioritize Matter protocol certification investment to anchor interoperability positioning as building automation standards converge, defending against white-label entrants exploiting ODM financing accessibility.
For New Entrants and Emerging Players: Build out certification agility as a competitive wedge, targeting India's WPC-authorized RF remote segment where established distributors face testing timeline disadvantages. Focus on hospitality procurement concentration in US Sun Belt development corridors, offering unified property management interface integration that incumbent HVAC OEMs bundle less flexibly.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light ODM platforms as third-party financing reconfigures fabrication requirements. Long-term viability favors acquisition targets with pre-positioned dual FCC/MIIT certification and established relationships with Shenzhen component ecosystems. Monitor WPC authorization backlog clearance rates as inflection indicator for India market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Interoperability positioning with Apple, Google, and Amazon smart home ecosystems secures premium channel placement. |
| Dual-Jurisdiction Certification Pre-Positioning | Simultaneous FCC and MIIT GB standards compliance compresses market entry timelines for multi-region HVAC OEMs. |
| Energy Analytics Integration | Utility-partnered distribution channels unlock unexpressed value capture through consumption tracking firmware. |
| Hospitality Bundle Specification | Unified property management interface consolidation in India's urban commercial construction displaces discrete procurement. |
| MEMS Sensor Embedding | Occupancy-based climate adjustment functionality compresses discrete thermostat hardware addressable market. |
Research Methodology
A standing panel of HVAC procurement managers, ODM platform engineers, MIIT certification consultants, and hospitality technology directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, MIIT GB standards filings, WPC frequency allocation registers, and customs export-import records for infrared and RF transmitter components. Bottom-up unit shipment modeling triangulated against top-down HVAC installed base estimates across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, technology protocol, end-user segment, and distribution channel dimensions throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to electrification expansion rates in India's urban corridors and smart home adoption intensity in Japanese residential markets. Semiconductor foundry capacity allocation patterns and Matter protocol certification timelines served as industry-specific forecast inputs.
Stress conditions across RF component cost volatility, WPC authorization delays, and GB standards compliance stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospitality procurement consolidation velocity and residential smart home ecosystem adoption. Quarterly review of MIIT certification queue lengths and India electrification subsidy disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Audio Jack Market