
 Mobile Phone Power Accessories Market | 2026-2036
Mobile Phone Power Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Phone Power Accessories Market Analytics
Online retail is narrowing the gap with offline distribution for mobile phone power accessories across Asia-Pacific and North America. Anker Innovations Technology Co. Ltd. leverages direct-to-consumer engineering to sustain premium positioning in fast charging. Xiaomi Corporation anchors volume production through captive supply of GaN components. Baseus competes aggressively on price while extending its SKU breadth across cables and adapters.
Mobile phone power accessories comprise electromechanical devices that convert, store, and transmit electrical energy to handheld communication equipment, typically operating between five and 240 watts with lithium-ion or lithium-polymer cell chemistries and gallium nitride or silicon power management semiconductors. Their commercial purpose centers on extending device uptime, reducing recharge duration, and enabling interoperability across heterogeneous connector standards. Fast charging technology captures the highest margin pool as OEMs bundle proprietary protocols with hardware, while wireless charging posts the fastest structural expansion amid furniture and automotive integration. Power banks remain the most mature segment with compressed margins and commodity-grade competition.
FCC certification governs electromagnetic emissions for accessories sold in the United States, while CE marking and RoHS compliance mandate substance restrictions and safety verification across European Economic Area markets. India's BIS compulsory registration order now blocks uncertified chargers and adapters at customs, tightening market access for unbranded imports. Stakeholders must monitor regulatory divergence around universal charging mandates versus proprietary protocol ecosystems.
Market Dynamics
GaN semiconductor migration is compressing charger form factors while IEC 62684 USB-C harmonization eliminates proprietary cable fragmentation, forcing OEMs to consolidate protocol stacks and redesign thermal architectures around unified power delivery standards.
Growth Catalysts
- Remote workforce expansion:Digital nomad clusters in Portugal, Mexico, and Thailand generate concentrated demand for multi-device charging hubs and high-capacity power banks with universal voltage compatibility.
- IEC 62684 standardization:The international USB-C mandate under EU common charger directive eliminates fragmentation costs, enabling accessory makers to scale single-SKU designs across previously incompatible regional markets.
- Automotive integration:In-cabin wireless charging pads and rear-seat USB-C ports in electric vehicles from Tesla, BYD, and Volkswagen create incremental socket demand requiring vehicle-specific form factors and thermal management.
Market Restraints
- Lithium-polymer cell cost volatility:Cobalt and lithium carbonate price swings tied to DRC mining output and Chilean brine processing constrain power bank margin stability for contract manufacturers.
- Shenzhen supply concentration:Seventy percent of GaN driver IC and transformer winding capacity sits within fifty kilometers of the Pearl River Delta, exposing procurement to single-region weather, power, or labor disruptions.
- Thermal dissipation ceiling:Silicon carbide and GaN devices above 100W require active cooling or gallium nitride-on-silicon substrates that remain cost-prohibitive for economy-tier charger SKUs.
Strategic Opportunities
- India BIS compliance gap:The 2023 compulsory registration order for adapters and power banks blocks uncertified imports, creating first-mover advantage for domestic assembly operations and joint ventures with Dongguan ODMs.
- Furniture-embedded wireless:IKEA, Herman Miller, and Steelcase are integrating Qi2 charging surfaces into desks and hospitality fixtures, opening B2B specification channels beyond traditional consumer electronics retail.
- GaN-SiC hybrid architectures:Converging gallium nitride front-end rectification with silicon carbide output stages enables 240W laptop-class charging in palm-sized housings previously limited to 65W silicon designs.
Industry Challenges
- FCC Part 15 certification backlog:Electromagnetic interference testing queue times at accredited labs now exceed fourteen weeks, delaying North American market entry for seasonal product cycles.
- Protocol licensing complexity:Qualcomm Quick Charge, USB Power Delivery, and proprietary vendor standards require separate royalty structures and firmware certification, fragmenting engineering resources across incompatible validation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Phone Power Accessories Market |
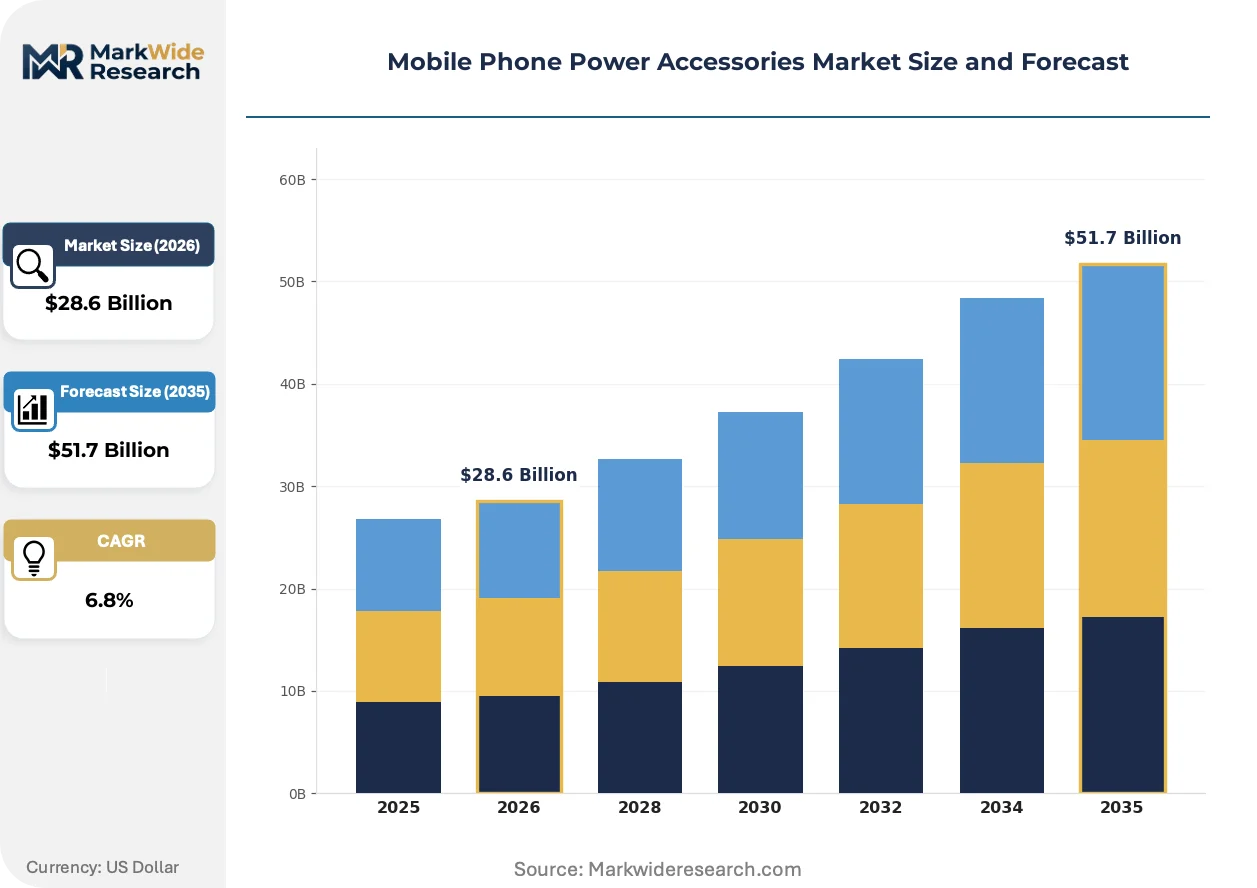
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chargers, Power Banks, Cables, Adapters End User: Retail Consumers, Corporate Users, Educational Institutions, E-Commerce Platforms Technology: Fast Charging, Wireless Charging, Solar Charging, Standard Charging Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Baseus, Panasonic Corporation, Anker Innovations Technology Co. Ltd., ZAGG Inc, Energizer Holdings Inc., Belkin International Inc., Spigen Inc, AUKEY Official, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Phone Power Accessories Market Evolving Landscape
Active thermal management and magnetic alignment standards are redefining physical interfaces, while regulatory pressure on interoperability accelerates consolidation around unified power delivery architectures.
GaN-on-silicon power ICs is hybridizing charger topologies by replacing silicon MOSFETs in active clamp flyback designs, enabling 100W+ output from 30% smaller enclosures. Remote workers purchasing multi-port desktop hubs prioritize these compact thermal profiles for co-working portability. The technology is hybridizing previously distinct product categories—laptop adapters, phone chargers, and power banks—into converged 140W universal devices that compress SKU proliferation.
EU common charger mandates under the Radio Equipment Directive now require USB-C for all handheld devices by late 2024, eliminating Lightning and micro-USB variants from European shelves. Manufacturers must retool molding lines and cable inventories to single-connector specifications, raising compliance costs for multi-region portfolios. The directive most impacts Apple ecosystem accessory makers, who are accelerating MFi-licensed USB-C cable certification to maintain aftermarket positioning.
Direct-to-consumer engineering brands now bypass distributor markups through TikTok Shop and Amazon storefront analytics, capturing margin previously allocated to retail slotting fees. This channel compression reaches highest penetration among 25-34 year old buyers in the United States and United Kingdom, where unboxing content and charging speed benchmarks drive purchase decisions. The shift concentrates marketing spend on influencer partnerships and performance creative rather than trade promotion budgets.
Mobile Phone Power Accessories Market Segmentation
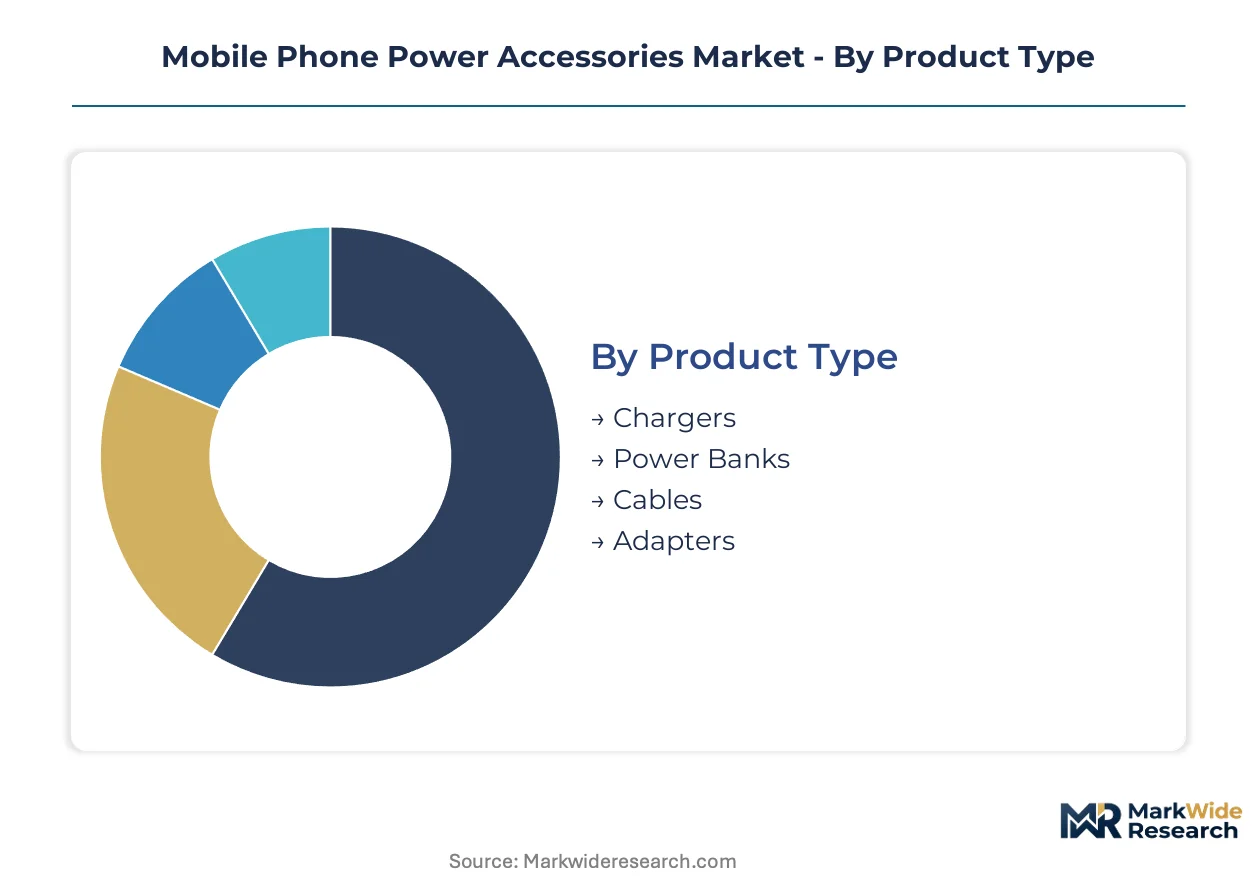
Segmentation in mobile phone power accessories reveals how protocol licensing, thermal architecture, and channel economics fragment commercial opportunity across incompatible customer workflows and procurement patterns.
Product Type:
Power conversion hardware spans pocket-sized single-device units to multi-port desktop hubs serving heterogeneous device fleets.
- Chargers:GaN-on-silicon designs now dominate 65W+ output categories, replacing silicon MOSFETs in active clamp flyback topologies. Demand concentrates among remote workers in Lisbon, Mexico City, and Bangkok purchasing multi-port desktop hubs for co-working portability, driven by IEC 62684 USB-C harmonization eliminating regional plug variants.
- Power Banks:Lithium-polymer and lithium-ion cell chemistries store 5,000mAh to 30,000mAh capacities with USB Power Delivery output negotiation. Procurement clusters around Shenzhen contract manufacturers supplying Amazon private-label sellers, constrained by cobalt price volatility from DRC mining output.
- Cables:Copper-core conductors with TPE or braided nylon jackets carry 3A to 5A current ratings across USB-C, Lightning, and legacy micro-USB terminations.
- Adapters:Plug converters and voltage transformers bridge regional socket standards for international travelers and import-dependent markets.
Established volume favors chargers; emerging adoption favors power banks with integrated wireless output coils.
End User:
Procurement authority and volume scale diverge sharply between individual purchasing decisions and institutional fleet deployment.
- Retail Consumers:Individual buyers prioritize unboxing aesthetics and charging speed benchmarks from TikTok Shop and Amazon storefront analytics.
- Corporate Users:IT procurement departments specify multi-device charging hubs with universal voltage compatibility for hybrid work arrangements. Deployment concentrates in technology sector headquarters across Austin, Berlin, and Singapore, driven by employee retention programs equipping home offices.
- Educational Institutions:K-12 and university technology departments purchase durable, tamper-resistant charging carts and wall-mounted stations for shared device programs.
- E-Commerce Platforms:Marketplace operators and fulfillment centers source white-label accessories through Dongguan ODM relationships for private-brand placement.
Margin concentration sits with corporate users; volume scale sits with retail consumers.
Technology:
Power delivery protocols and physical interfaces determine thermal design, certification complexity, and royalty cost structures.
- Fast Charging:Proprietary protocols from Qualcomm, MediaTek, and OEM-specific implementations negotiate voltage and current above 5V/2A baseline. Qualcomm Quick Charge and USB Power Delivery require separate firmware certification tracks, fragmenting engineering resources for accessory makers.
- Wireless Charging:Qi and Qi2 magnetic alignment standards enable furniture and automotive integration without physical connectors. IKEA, Herman Miller, and Steelcase specification channels drive B2B adoption beyond consumer electronics retail.
- Solar Charging:Photovoltaic panels with integrated lithium storage target outdoor recreation and emergency preparedness segments with extended off-grid autonomy.
- Standard Charging:Legacy 5V/1A to 5V/2.4A specifications serve price-sensitive replacement markets and regulatory minimums in developing economies.
Protocol licensing burdens fast charging; physical integration opportunities favor wireless charging.
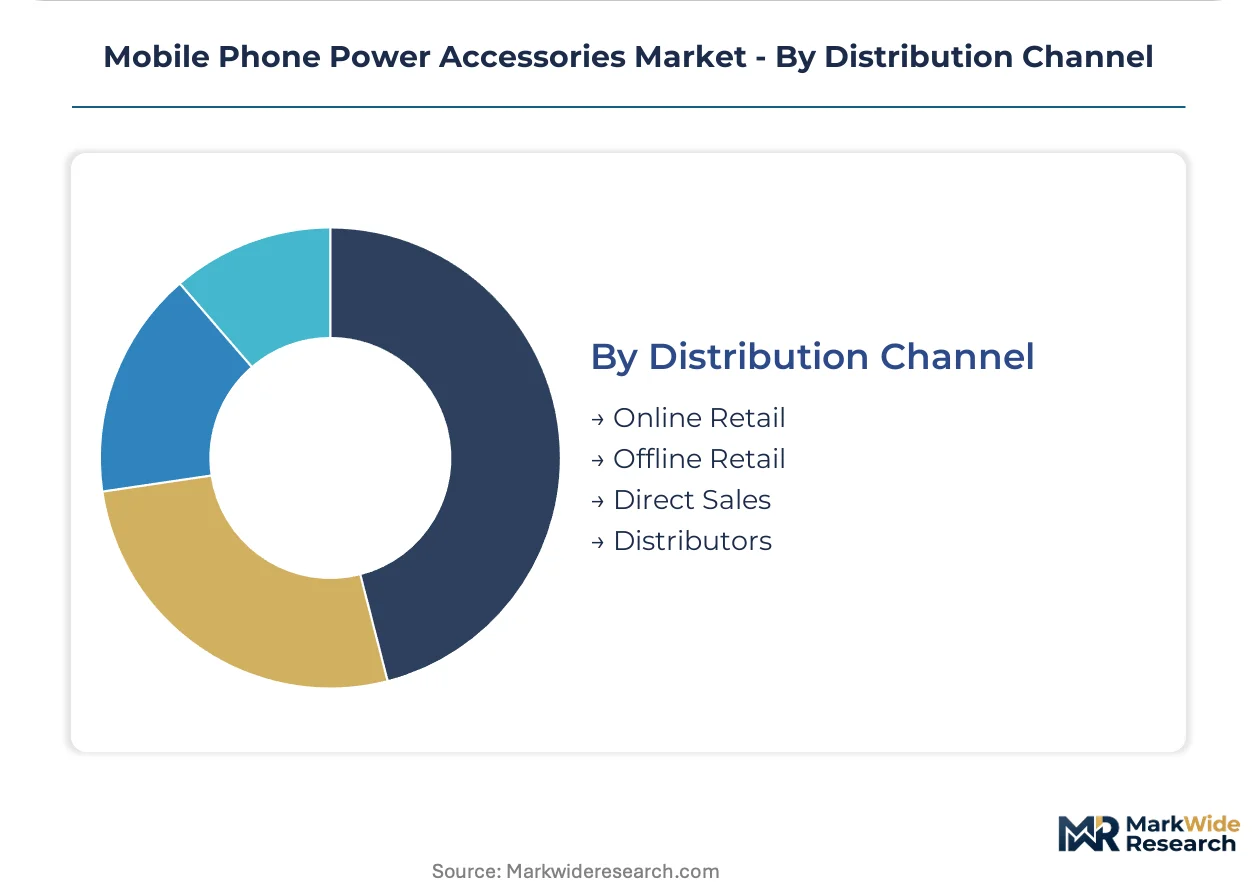
Distribution Channel:
Channel economics determine margin capture, return rates, and speed-to-market for seasonal product cycles.
- Online Retail:Amazon, TikTok Shop, and direct-to-consumer storefronts bypass distributor markups, capturing margin previously allocated to retail slotting fees. Concentration peaks among 25-34 year old buyers in the United States and United Kingdom where charging speed benchmarks drive purchase decisions.
- Offline Retail:Electronics specialty stores and mobile carrier shops provide tactile evaluation and immediate fulfillment for emergency replacement purchases.
- Direct Sales:Enterprise account teams and OEM bundling agreements supply corporate fleet deployments with customized branding and warranty terms.
- Distributors:Regional wholesalers manage inventory and credit risk for smaller retailers in markets with underdeveloped logistics infrastructure.
Marketing efficiency favors online retail; relationship dependency favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification governs electromagnetic emissions for accessories entering the United States, while China's MIIT and GB standards anchor production planning for the world's largest manufacturing base. Remote worker clusters in Lisbon, Mexico City, and Bangkok generate concentrated procurement of multi-device charging hubs.
United States
Digital nomad concentrations in Austin and Miami drive demand for high-wattage multi-port chargers with universal voltage compatibility. FCC Part 15 certification queues now exceed fourteen weeks at accredited laboratories, delaying seasonal product launches. Silicon Valley and Shenzhen maintain synchronized engineering cycles through direct airline links and shared ODM relationships.
China
Seventy percent of GaN driver IC and transformer winding capacity sits within fifty kilometers of Shenzhen and Dongguan, exposing procurement to single-region disruption risks. MIIT enforces GB 4943.1 safety standards for information technology equipment, harmonizing with IEC frameworks. The Pearl River Delta hosts vertically integrated charger assembly from semiconductor packaging through final molding.
Germany
Corporate IT procurement in Berlin and Munich specifies multi-device charging hubs for hybrid work arrangements under employee retention programs. CE marking and RoHS compliance verification operate through notified bodies in Frankfurt and Hamburg. Bavaria's automotive suppliers integrate USB-C power delivery into vehicle cabin architectures for Volkswagen and BMW electric platforms.
India
BIS compulsory registration orders now block uncertified chargers and adapters at Mumbai and Chennai customs entry points. Domestic assembly operations in Noida and Sri City attract joint venture capital from Dongguan ODMs seeking first-mover positioning. The PLI scheme for electronics manufacturing incentivizes local power bank cell packaging and final assembly.
Japan
METI promotes USB-C harmonization through alignment with IEC 62684 standards for consumer electronics interoperability. Tokyo and Osaka corporate technology departments procure compact GaN chargers for domestic and international business travel. Kyushu semiconductor foundries supply power management ICs to accessory designers in Kansai and Kanto regions.
Mobile Phone Power Accessories Market Competitive Landscape
Engineering-led specialists and volume-scaled manufacturers split the market into divergent margin structures. Consolidation pressures concentrate around protocol licensing costs and GaN semiconductor procurement scale. Three archetypes dominate: direct-to-consumer engineering brands, captive-component electronics conglomerates, and contract-manufacturing private-label suppliers. Competitive moves center on backward integration into GaN driver IC sourcing and TikTok Shop channel compression to bypass distributor markups.
Among direct-to-consumer engineering specialists, Anker Innovations Technology Co. Ltd. and Baseus exemplify the premium positioning archetype through compact thermal profile development. Xiaomi Corporation occupies a scale-driven position leveraging in-house component supply. Panasonic Corporation and Belkin International Inc. represent established electronics conglomerates with retail channel heritage.
| Leading Market Players |
|---|
| Baseus |
| Panasonic Corporation |
| Anker Innovations Technology Co. Ltd. |
| ZAGG Inc |
| Energizer Holdings Inc. |
| Belkin International Inc. |
| Spigen Inc |
| AUKEY Official |
| Xiaomi Corporation |
| Others |
Value Network & Pricing Analysis
Shenzhen and Dongguan manufacturing clusters concentrate seventy percent of GaN driver IC and transformer winding capacity within fifty kilometers, concentrating upstream pricing leverage among contract manufacturers while compressing margin pools for downstream brands lacking captive component supply.
Pricing Analysis
Geographic price spreads between North American direct-to-consumer channels and Southeast Asian e-commerce platforms exceed three-to-one for equivalent GaN charger specifications. Three-tier pricing structure across premium, standard, and economy levels separates Anker and Baseus engineering brands from Amazon private-label sellers and unbranded Shenzhen exports. Cost compression in economy-tier silicon-based chargers is intensifying because of GaN-on-silicon migration rendering legacy thermal architectures obsolete. Corporate IT procurement departments show lowest price sensitivity, prioritizing multi-device compatibility and warranty terms over unit cost.
Supply Chain Analysis
US export-control restrictions on advanced semiconductor manufacturing equipment constrain domestic GaN fabrication scale-up, forcing accessory brands to source power ICs from Taiwan Semiconductor Manufacturing Company and South Korean foundries. Lithium-polymer cells draw from DRC cobalt and Chilean brine processing, tethering power bank margins to mining output volatility. Single-region vulnerability concentrates in Pearl River Delta assembly operations exposed to typhoon-season logistics disruption. Distribution runs through Dongguan ODM relationships supplying Amazon FBA and TikTok Shop fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where extended warranty programs and firmware-update subscriptions expand faster than hardware unit economics, rewarding brands that embed recurring revenue into initial purchase transactions.
For Market Incumbents: Build certification moats around BIS India compliance and FCC Part 15 pre-clearance to block seasonal entrants during fourteen-week laboratory queue periods. Capture Dongguan ODM equity stakes to secure GaN driver IC allocation during foundry capacity constraints. Defend against Xiaomi's captive-component cost position by accelerating Qi2 wireless charging furniture partnerships with Herman Miller and Steelcase specification channels.
For New Entrants and Emerging Players: India's BIS registration gap offers first-mover positioning through Noida and Sri City joint ventures with established Dongguan contract manufacturers. Target corporate IT procurement departments in Austin and Berlin hybrid-work hubs with white-labeled multi-port desktop hubs carrying custom branding. Bypass Amazon saturation by leveraging TikTok Shop analytics for unboxing-content-driven customer acquisition among 25-34 year old buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-led specialists with backward integration into GaN semiconductor sourcing rather than pure-brand aggregators dependent on spot-market component procurement. Long-term viability over the coming decade hinges on protocol licensing consolidation as USB Power Delivery and Qi2 standards displace fragmented proprietary implementations. Monitor IEC harmonization progress across EU member states as inflection indicator for single-SKU design scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | In-house power IC sourcing insulates margin from Taiwan and South Korea foundry allocation constraints. |
| India BIS Certification Pre-Investment | Early compliance with compulsory registration orders blocks competitor entry at Mumbai and Chennai customs. |
| Qi2 Wireless Furniture Partnership | Specification relationships with IKEA and Steelcase open B2B channels beyond consumer electronics retail saturation. |
| TikTok Shop Channel Compression | Direct-to-consumer analytics bypass distributor markups previously allocated to retail slotting fees. |
| Multi-Protocol Firmware Consolidation | Unified USB Power Delivery and Qi2 certification reduces engineering fragmentation across incompatible validation tracks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, FCC equipment authorization databases, and BIS registration filings to anchor volume estimates in documented trade flows. Primary interviews with GaN semiconductor procurement managers at Dongguan ODMs, Amazon private-label category leads, and corporate IT fleet deployment officers in Austin and Berlin supplied forward-looking demand signals. Secondary validation drew from MIIT GB standard publications, EU Radio Equipment Directive implementation guidance, and Pearl River Delta industrial zone output statistics. Bottom-up SKU-level pricing data triangulated against top-down regional consumption patterns.
Forecast inputs span product-type segmentation across chargers, power banks, cables, and adapters; technology tiers separating GaN from silicon architectures; and distribution channel splits between online retail, offline electronics specialty, and direct enterprise sales. End-user segmentation incorporates remote worker cluster density in Lisbon, Mexico City, and Bangkok alongside corporate IT procurement scale in technology sector headquarters. CAGRs derive from installed-base replacement cycles, USB-C harmonization penetration curves, and automotive integration adoption across Tesla, BYD, and Volkswagen electric platforms.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated electronics conglomerates or unexpected BIS enforcement acceleration would shift outcomes. Material shifts in DRC cobalt export policy, Taiwan semiconductor foundry allocation, or EU universal charging mandate implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Wireless Keyboard Market