
 USB Power Strips Market | 2026-2036
USB Power Strips Market Size, Share, and Industry Trends Forecast 2026-2036
USB Power Strips Market Analytics
Multi-source component procurement is decoupling from the single-factory assembly model that historically dominated USB power strip production. Anker leverages its direct-to-consumer channel strength to control pricing across North American and European markets. Belkin sustains retail shelf presence through Best Buy and Amazon partnerships that competitors struggle to replicate. Xiaomi anchors volume in Asia through ecosystem bundling with smartphones and routers.
A USB power strip integrates AC outlets with USB-A and USB-C charging ports, typically housing gallium nitride or silicon-based power management chips within flame-retardant polycarbonate enclosures rated for 125V to 250V operation. Smart power strips with Wi-Fi connectivity and app-based scheduling command premium positioning as residential consumers automate home energy use. Surge protectors dominate commercial procurement for office setups where equipment protection justifies higher unit costs. Quick charge technology is displacing standard USB-A output in travel-oriented strips as consumers prioritize charging speed over port quantity.
The US Consumer Product Safety Commission and FCC enforce electrical safety and electromagnetic interference standards that determine market access for imported units. China's SAMR administers GB standards for plug configurations and fire resistance that shape manufacturing specifications for Asia-bound production. India's BIS certification requirement for electrical accessories is tightening import compliance and filtering out uncertified suppliers. Stakeholders must monitor whether regional charger standard fragmentation forces SKU proliferation or consolidation into universal USB-C PD architectures.
Market Dynamics
GaN semiconductor adoption is compressing power management chip footprints while China's tightening GB standards force enclosure material upgrades, creating simultaneous cost pressure and compliance complexity across manufacturing tiers.
Growth Catalysts
- Remote Work Normalization:Residential consumers now maintain 4-6 active devices per workstation, expanding port density requirements in home office setups.
- India's BIS Certification Mandate:The Bureau of Indian Standards tightened electrical accessory import rules, filtering uncertified suppliers and elevating demand for compliant smart power solutions among small businesses.
- USB-C PD Architecture Convergence:Universal Power Delivery standards are consolidating previously fragmented charger protocols, enabling single-SKU strategies for multi-market distribution.
Market Restraints
- Polycarbonate Resin Volatility:Flame-retardant enclosure materials face petrochemical feedstock price swings that compress assembly margins unpredictably.
- Single-Region Manufacturing Concentration:Component sourcing clusters heavily in Guangdong province, exposing supply continuity to localized logistics disruptions.
- Silicon-GaN Cost Gap:Legacy silicon-based power chips retain 30-40% cost advantage over gallium nitride alternatives, slowing premium tier penetration.
Strategic Opportunities
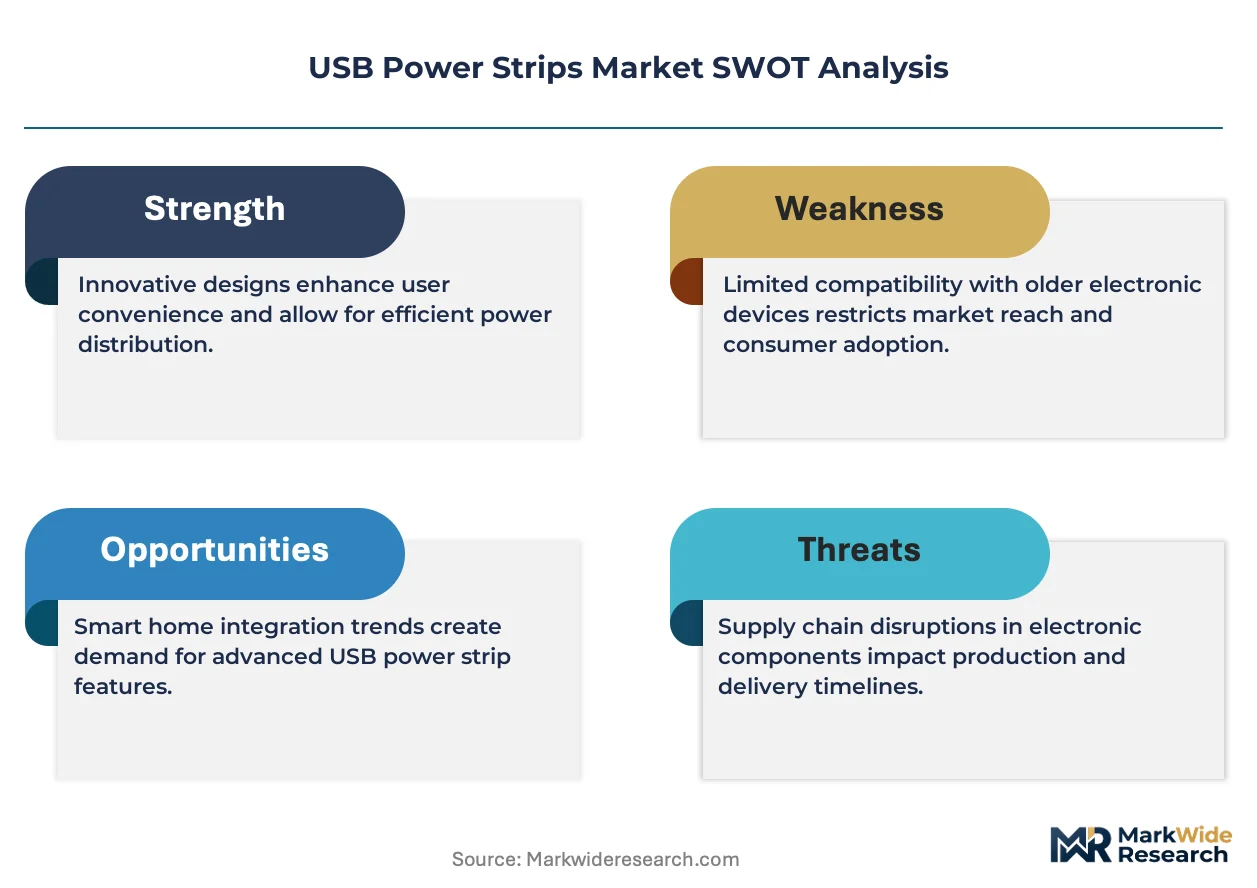
- Smart Home Ecosystem Integration:Wi-Fi-enabled strips with app-based scheduling command premium positioning as residential consumers automate energy use.
- India Small Business Infrastructure:Affordable smart power solutions face underpenetrated demand among offices upgrading from basic surge protectors.
- EU Energy Efficiency Directives:The EU Green Deal's standby power limits create regulatory tailwind for intelligent load-sensing product lines.
Industry Challenges
- EMC Certification Timeline Compression:FCC electromagnetic interference testing for North American market entry now averages 14-18 weeks, delaying revenue recognition.
- Firmware-Hardware Integration Complexity:Smart strip developers face skill scarcity in embedded systems engineering capable of bridging power management silicon with cloud connectivity stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Power Strips Market |
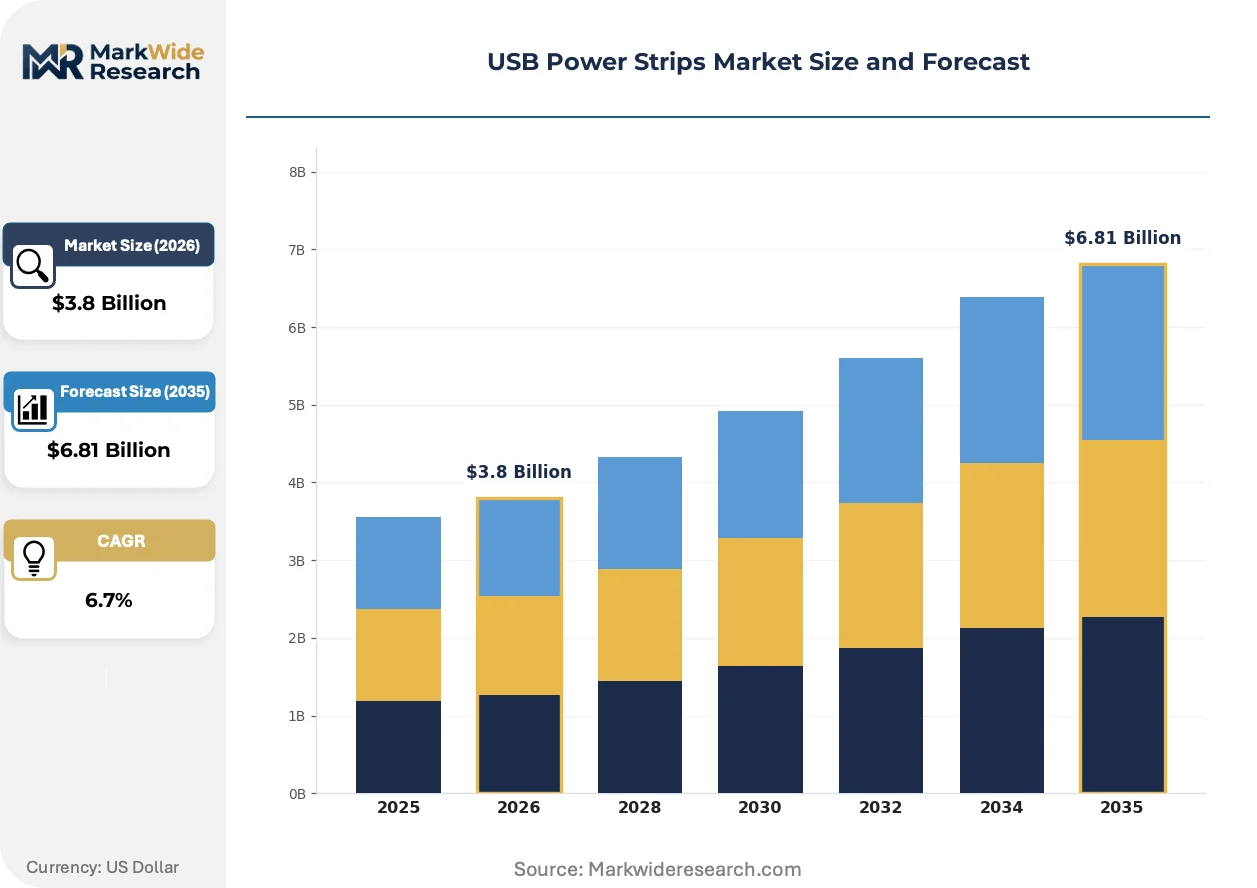
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Power Strips, Surge Protectors, Multi-Outlet Strips, Wall-Mounted Strips Application: Home Use, Office Setup, Industrial Usage, Travel Technology: Surge Protection, Smart Features, Quick Charge, Power Monitoring End User: Residential Consumers, Small Businesses, Large Enterprises, Educational Institutions |
| Companies Covered | Anker, Belkin, Xiaomi, UGREEN, Baseus, Huawei, Philips, Gongniu, Leviton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Power Strips Market Evolving Landscape
Power delivery architectures are fragmenting across regional certification requirements while consumer expectations compress around charging velocity and cross-device compatibility.
Gallium nitride power ICs are modularizing traditional AC-DC conversion blocks within strip enclosures. Residential buyers now prioritize 65W-100W single-port output over multi-port quantity. This density shift enables slimmer industrial designs that command shelf space premiums in retail channels.
China's SAMR administration is enforcing updated GB standards for plug configurations and fire resistance ratings that determine Asia-bound production specifications. Manufacturers must redesign enclosure molds and retest thermal runaway profiles. Smart power strip variants with integrated load monitoring face the steepest compliance recertification burdens.
Direct-to-consumer channel capture is displacing traditional electronics retail for premium USB power strip tiers. Anker's pricing control model demonstrates how owned digital storefronts bypass distributor margin stacking. This pattern concentrates in North American and European markets where Amazon marketplace fees still undercut brick-and-mortar slotting costs.
USB Power Strips Market Segmentation
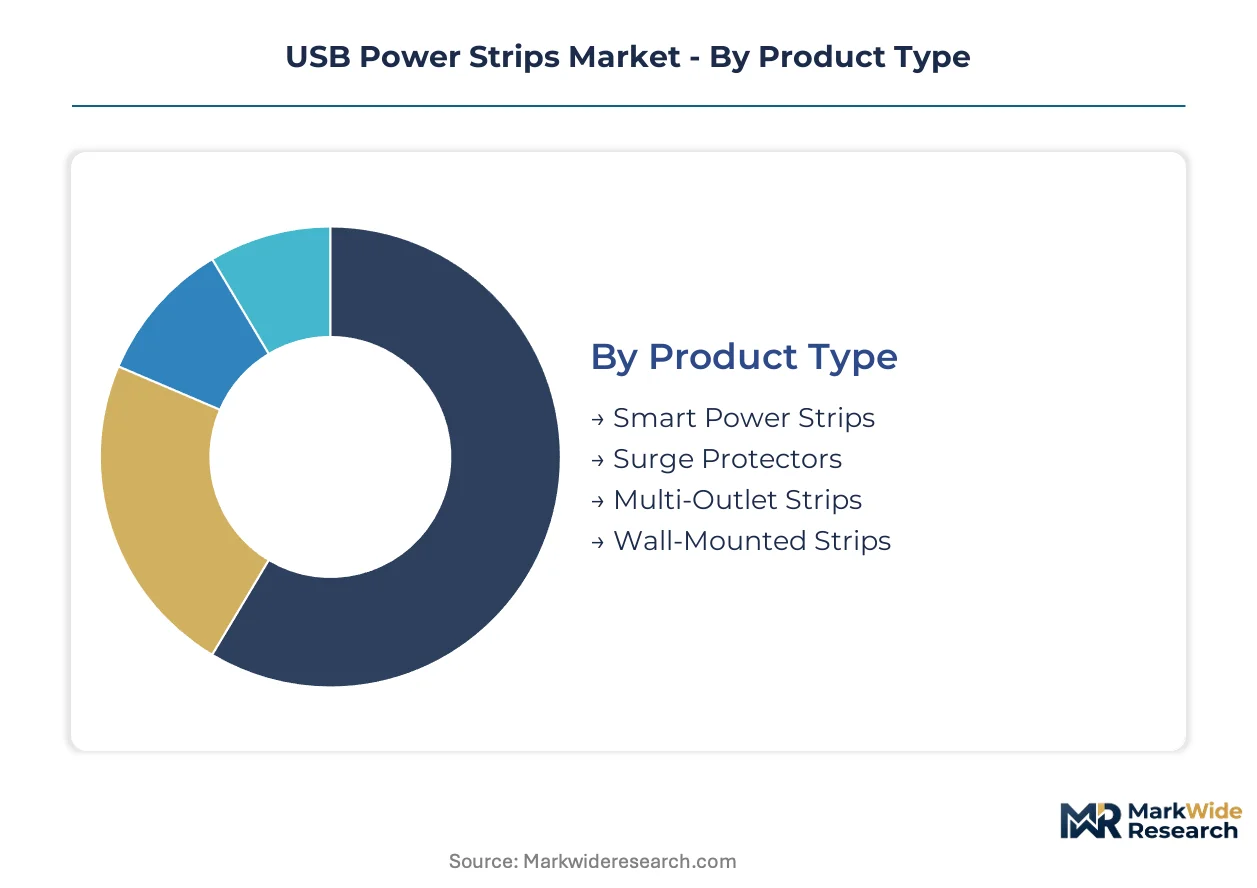
USB power strip segmentation reveals divergent capital requirements across product tiers, with smart connectivity and industrial-grade surge protection demanding substantially higher upfront R&D investment than basic multi-outlet configurations. Understanding these investment thresholds helps manufacturers align portfolio depth with technical capabilities and certification resources.
Product Type:
Capital intensity varies sharply across this category, with smart power strips requiring embedded systems engineering and cloud infrastructure investment that basic surge protectors avoid entirely.
- Smart Power Strips:Wi-Fi-enabled units integrate load-sensing silicon with app-based scheduling firmware housed in thermally optimized enclosures. Residential consumers in India and small business offices across Southeast Asia are consolidating procurement around these units as electricity monitoring becomes standard infrastructure. The steepest expansion trajectory sits here due to ecosystem bundling and home automation adoption.
- Surge Protectors:Metal oxide varistor arrays and gas discharge tubes clamp voltage spikes across industrial and commercial deployments where equipment protection justifies premium positioning. Large enterprises in Germany and Japan specify these for server rack installations under strict facility insurance requirements.
- Multi-Outlet Strips:Standard AC outlet expansion without USB integration serves price-sensitive residential segments and legacy office retrofits where device charging is handled separately.
- Wall-Mounted Strips:Permanent installation variants with hardwired connections target commercial construction and hospitality fit-outs requiring clean aesthetic integration and tamper resistance.
Surge protectors absorb the bulk of installed capacity in commercial infrastructure; smart power strips are expanding most quickly through consumer channel capture.
Application:
Volume concentration follows workstation density patterns, with office setups and home use commanding unit scale that industrial and travel segments cannot match.
- Home Use:Remote work normalization has elevated residential port density requirements to 4-6 active devices per workstation, with GaN-based fast charging now expected as standard. China's tightening GB standards for fire resistance are reshaping enclosure specifications for units bound to this segment.
- Office Setup:Small business infrastructure upgrades in India concentrate demand for affordable smart power solutions with load monitoring and scheduled shutoff capabilities. BIS certification requirements are filtering uncertified suppliers from this procurement channel.
- Industrial Usage:Heavy-duty housings with IP ratings and extended temperature tolerance serve manufacturing floors and warehouse environments where dust ingress and vibration resistance are mandatory.
- Travel:Compact foldable designs with universal voltage input and multi-country plug adapters prioritize 65W-100W single-port output over port quantity for mobile professionals.
Home use commands the largest revenue pool; office setup applications are climbing the fastest on small business digitization trends.
Technology:
Margin structure separates legacy silicon-based implementations from GaN-enabled architectures that command shelf space premiums despite higher bill-of-materials cost.
- Surge Protection:MOV and GDT component arrays with thermal fusing remain the baseline for commercial procurement where insurance compliance mandates documented protection levels. Installations in US office buildings and German industrial facilities specify these under NFPA and VDE guidelines respectively.
- Smart Features:Wi-Fi connectivity stacks with cloud-based energy dashboards and voice assistant integration require ongoing firmware maintenance and cybersecurity certification that silicon-only designs avoid. EU Energy Efficiency Directive standby power limits are accelerating regulatory tailwind for this tier.
- Quick Charge:USB-C PD protocol implementation with dynamic voltage negotiation enables 65W-100W output from compact enclosures, displacing standard USB-A in premium consumer tiers.
- Power Monitoring:Integrated current sensing with real-time display or app reporting serves energy-conscious residential buyers and facility managers tracking phantom load consumption.
Surge protection retains the widest installed base; smart features are gaining share fastest on home automation integration.
End User:
Procurement sophistication escalates from individual residential purchase decisions through institutional tender processes with extended certification and liability requirements.
- Residential Consumers:Individual buyers prioritize charging velocity, port count, and aesthetic integration for home office and entertainment center deployments. India's residential segment shows particular price elasticity sensitivity with strong preference for ecosystem-bundled solutions.
- Small Businesses:Office infrastructure procurement in India and Southeast Asia favors affordable smart power strips with basic scheduling and monitoring as upgrades from legacy surge protectors. BIS certification is tightening import compliance and elevating demand for verified suppliers.
- Large Enterprises:Facility-wide standardization with centralized procurement, extended warranty requirements, and integration with building management systems characterizes this tier. US and German corporate deployments specify UL and VDE certifications respectively.
- Educational Institutions:K-12 and university procurement emphasizes tamper resistance, surge protection for lab equipment, and bulk pricing with extended replacement cycles.
Residential consumers represent the largest addressable population; small businesses are expanding most quickly on infrastructure modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors global USB power strip manufacturing, with Shenzhen and Dongguan housing the densest concentration of gallium nitride semiconductor foundries and flame-retardant polycarbonate molding operations that feed assembly lines worldwide.
United States
Residential remote work setups drive 4-6 device charging density per workstation, expanding premium GaN-enabled strip demand. The FCC enforces electromagnetic interference standards averaging 14-18 weeks for certification, delaying market entry for new suppliers. Texas and California concentrate procurement from enterprise facility managers standardizing office infrastructure under NFPA electrical safety guidelines.
Germany
Industrial surge protector procurement dominates facility insurance compliance, with VDE certification mandatory for server rack installations. The EU Green Deal's standby power limits accelerate intelligent load-sensing product adoption. Bavaria's manufacturing clusters source thermally optimized enclosures for smart strip variants targeting building management system integration.
China
Domestic consumption absorbs volume from Xiaomi's ecosystem bundling with smartphones and routers, while export production faces SAMR-administered GB standard tightening for plug configurations and fire resistance. Yangtze River Delta mold retooling costs are elevating compliance burdens for smart variants with integrated load monitoring.
India
Small business office infrastructure upgrades concentrate demand for affordable smart power solutions with basic scheduling capabilities. BIS certification requirements tightened in 2024, filtering uncertified import suppliers from procurement channels. Maharashtra and Karnataka host distributor networks capturing underpenetrated demand from legacy surge protector replacements.
Japan
Corporate facility standardization emphasizes extended warranty requirements and integration with existing building automation. METI energy efficiency guidelines shape product specifications for standby power consumption. Kanto region electronics retailers maintain premium positioning for compact travel-oriented strips with 65W-100W single-port output.
USB Power Strips Market Competitive Landscape
Global majors compete with regional champions across certification resource depth and channel control, producing a tiered structure where direct-to-consumer pricing power separates premium positioning from commodity volume. Three archetypes dominate: ecosystem bundlers leveraging smartphone brand equity, direct-to-consumer specialists controlling digital shelf pricing, and component-integrated manufacturers capturing margin through captive GaN semiconductor supply. Consolidation pressure concentrates around M&A targeting embedded systems engineering talent and strategic partnerships securing FCC certification queue priority.
Among China-based fabricators, Xiaomi and UGREEN occupy positions reflecting divergent channel strategies, with the former anchoring ecosystem-tied volume and the latter exemplifying accessory-specialist agility. Anker represents the direct-to-consumer archetype through North American and European digital storefront control. These three entities collectively illustrate how pricing power and certification bandwidth determine tier placement without requiring identical technical specifications or geographic focus.
| Leading Market Players |
|---|
| Anker |
| Belkin |
| Xiaomi |
| UGREEN |
| Baseus |
| Huawei |
| Philips |
| Gongniu |
| Leviton |
| Others |
Value Network & Pricing Analysis
Embedded systems engineering talent clustering in Shenzhen and Dongguan feeds labor-cost differentials that widen pricing-tier spreads between basic multi-outlet strips and Wi-Fi-enabled smart variants with firmware maintenance obligations.
Pricing Analysis
Warranty bundling separates premium tiers from commodity positioning, with GaN-enabled units carrying extended replacement guarantees against basic surge protectors sold as-is. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service depth. Pricing pressure stems from polycarbonate resin feedstock volatility compressing assembly margins in flame-retardant enclosure production. Small business buyers in India exhibit highest price elasticity, while German industrial procurement prioritizes VDE-certified equipment protection over unit cost.
Supply Chain Analysis
GaN semiconductor supply rests on Taiwanese foundry capacity and Chinese packaging operations, with silicon-based alternatives drawing from legacy Korean and Japanese discrete component channels. Flame-retardant polycarbonate resins hinge on petrochemical feedstocks concentrated in Middle Eastern and US Gulf Coast production clusters. Single-region manufacturing concentration in Guangdong province exposes continuity to localized logistics disruptions. Distribution runs through direct-to-consumer digital storefronts for premium tiers and electronics retail partnerships for volume SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification bandwidth and embedded systems capability, with BIS mandate enforcement in India and FCC queue compression in the US forcing under-resourced competitors toward exit.
For Market Incumbents: Acquire FCC certification queue priority and embedded systems engineering teams to defend against direct-to-consumer specialists capturing pricing control. Deepen backward integration into GaN semiconductor sourcing to offset silicon-GaN cost gap pressure. Strengthen distributor exclusivity in Maharashtra and Karnataka before BIS-compliant supply consolidates. For New Entrants and Emerging Players: USB-C PD protocol implementation with 65W-100W single-port output offers technology-first entry against legacy multi-port incumbents. White-space concentration sits with affordable smart power strips for Indian small businesses upgrading from basic surge protectors. Go-to-market through Amazon marketplace storefronts bypasses brick-and-mortar slotting cost barriers that burden established retail partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with direct-to-consumer specialists with captive digital shelf pricing power given channel control premiumization trends. Long-term viability favors entities with vertical integration into GaN semiconductor supply and firmware maintenance infrastructure. Acquisition target archetype: mid-cap fabricators with BIS pre-certification and embedded systems talent depth. Signal to watch: FCC certification timeline compression accelerating revenue recognition delays for queue-positioned competitors.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive supply of power management chips defends margin position against silicon cost-gap pressure. |
| BIS Pre-Certification Investment | Early compliance with India's tightened electrical accessory rules filters uncertified import competition. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts bypass distributor margin stacking concentrated in North American markets. |
| Smart Home Ecosystem Partnership | Wi-Fi-enabled strip integration with voice assistant platforms commands premium residential positioning. |
| Embedded Systems Talent Acquisition | Firmware-hardware bridging capability scarcity limits smart variant development for mid-tier competitors. |
Research Methodology
Multi-period observation of GaN semiconductor adoption rates, BIS certification timelines, and FCC queue compression anchored the trend analysis, supplemented by interviews with power management IC procurement leads, electronics retail category buyers, smart home platform engineers, and flame-retardant materials sourcing managers. Secondary validation drew from customs trade data, SAMR GB standard filings, FCC equipment authorization databases, and EIA electricity consumption patterns. Bottom-up unit shipment modeling triangulated against top-down consumer electronics spend allocation across the analysis window.
Input-output matrices mapped gallium nitride penetration against silicon legacy share, certification resource requirements against manufacturer tier, and channel structure against pricing power realization. Segmentation dimensions spanned product type, application, technology implementation, and end-user procurement sophistication. CAGRs derived from installed base replacement cycles, remote work device density expansion, and regional infrastructure upgrade cadence. Industry-specific forecast inputs included polycarbonate resin price index trajectories and EMC certification duration trends.
Several conditions sit outside the modeled scope, including unforeseen GB standard enforcement acceleration, abrupt logistics disruption in Guangdong province, and rapid USB-C PD protocol obsolescence. Forecasts reflect documented assumptions about certification timeline stability and feedstock price volatility bands. A small set of named triggers warrants ongoing watch: FCC queue priority allocation shifts, BIS inspectorate capacity expansion, and GaN foundry capacity addition announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Electronic Equipment Repair Service Market