
 Audio Jack Market | 2026-2036
Audio Jack Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Jack Market Analysis
China's Guangdong province is rewriting the competitive map for audio jack manufacturing as domestic capacity for precision metal stamping and automated assembly expands across Shenzhen and Dongguan. Hirose Electric leverages vertical integration into contact plating and mold fabrication to sustain margin control in high-reliability segments. Amphenol anchors North American supply through its dominance in aerospace and military-qualified connector variants. TE Connectivity competes on global scale, operating multi-region factories that service both consumer electronics OEMs and industrial audio equipment builders.
An audio jack is a cylindrical electromechanical connector, typically incorporating nickel-plated brass housings and phosphor bronze contacts with gold or tin surface finishes, engineered to transmit analog or digital audio signals between source devices and output peripherals. The 3.5mm jack variant remains the dominant physical standard in consumer electronics and professional audio equipment due to universal backward compatibility and minimal insertion force requirements. USB-C jack adoption accelerates in communication devices as OEMs phase out dedicated analog ports, while wireless audio connector penetration expands fastest among electronic accessory retailers serving mobile-first users. Analog audio technology occupies the largest installed base, though digital audio interfaces command premium positioning in musical instruments and studio monitoring chains.
RoHS and REACH frameworks in Europe restrict hazardous substances in connector plating and substrate materials, compelling manufacturers to reformulate solder alloys and surface finishes. The FCC in the United States governs electromagnetic interference thresholds for audio connectors integrated into communication devices, shaping shielding design and certification costs. China's GB standards, administered by SAMR, mandate dimensional tolerances and environmental testing protocols for domestically sold jacks. Stakeholders must monitor regulatory divergence between analog preservation mandates and digital transition incentives as product compliance costs fragment across jurisdictions.
Market Dynamics
The audio jack market faces a structural compression as USB-C connectors is virtualizing the analog signal pathway in smartphones and laptops, forcing manufacturers to defend installed-base revenues while pivoting toward industrial and professional audio segments where legacy compatibility remains non-negotiable.
Growth Catalysts
- Professional Audio Equipment Demand:Studio monitoring chains and live sound systems in the United States and Germany sustain orders for 3.5mm and 6.35mm variants due to zero-latency requirements and universal backward compatibility with existing gear.
- REACH Substance Restrictions:European ECHA mandates on lead-free solder alloys and hexavalent chromium plating have accelerated reformulation investments, creating first-mover advantages for suppliers with certified green chemistries.
- Pearl River Delta Concentration:China's Guangdong province hosts vertically integrated stamping, plating, and automated assembly capacity that compresses lead times for global OEM procurement.
Market Restraints
- Nickel Price Volatility:Brass housing and contact substrate costs fluctuate with London Metal Exchange nickel futures, squeezing margin predictability for mid-tier stamping houses.
- USB-C Substitution Threat:Digital audio over USB-C connectors eliminates dedicated analog ports in Samsung, Apple, and Xiaomi flagship devices, shrinking addressable volume in consumer electronics.
- Single-Source Plating Chemistry:High-reliability gold and palladium-nickel surface finishes depend on Japanese and German specialty chemical suppliers, creating geographic concentration risk.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for mobile and audio device assembly in Tamil Nadu and Karnataka are generating localized demand for connector kits and sub-assemblies.
- Aviation Retrofit Cycles:FAA-mandated cockpit audio system upgrades in aging commercial fleets sustain demand for MIL-qualified 3.5mm variants with enhanced vibration resistance.
- Right-to-Repair Mandates:European Commission proposals for consumer electronics repairability are preserving modular analog audio ports as serviceable components against sealed-unit digital alternatives.
Industry Challenges
- Precision Stamping Talent Scarcity:Tool and die craftsmanship for micron-tolerance contact forming is aging out in Japan and Germany without sufficient apprenticeship pipeline replacement.
- Dual Certification Burden:Simultaneous FCC Part 15 EMI compliance and CE marking for shielded audio jacks extends validation timelines by four to six months for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Jack Market |
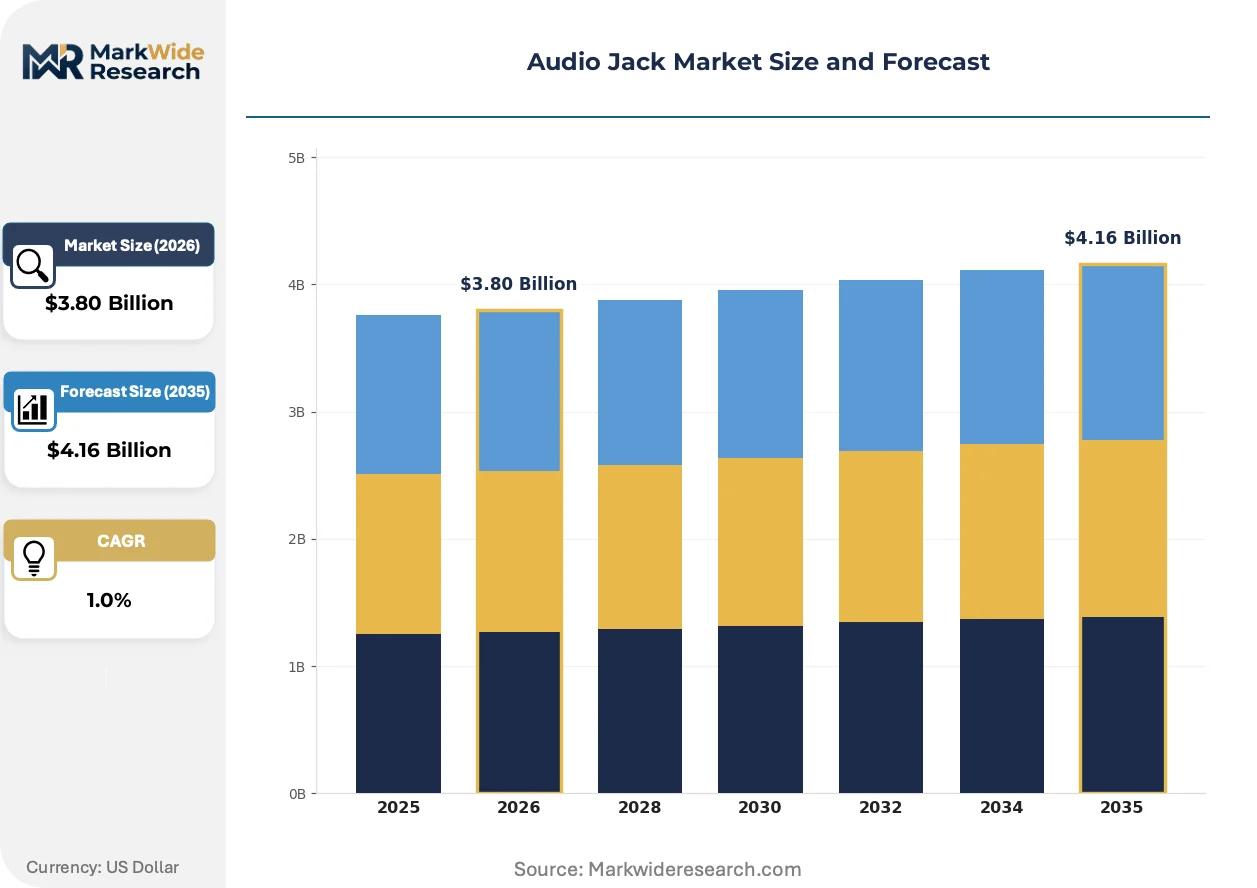
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3.5mm Jack, 6.35mm Jack, USB-C Jack, Lightning Jack, Wireless Audio Connector Technology: Analog Audio, Digital Audio, Balanced Audio, Unbalanced Audio, Optical Audio Interface Application: Consumer Electronics, Professional Audio Equipment, Communication Devices, Musical Instruments, Automotive Entertainment Systems Customer Type: OEMs, Aftermarket Suppliers, Audio Specialists, Electronic Accessory Retailers, Repair Service Providers |
| Companies Covered | Hirose Electric, LS Mtron, Amphenol, JST, ACON Laboratories, Molex, JAE, SMK Corporation, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Jack Market Emerging Trajectories
Signal transmission architectures are fragmenting across analog preservation and digital transition pathways, with connector manufacturers engineering hybrid solutions that bridge legacy compatibility with emerging interface standards.
Magnetic breakaway connectors is virtualizing the physical stress point in gaming headsets and professional in-ear monitors. These detachable cable systems from Chinese and Taiwanese suppliers allow users to replace worn cables without discarding the driver assembly. Gaming peripheral OEMs in Shenzhen are adopting this architecture fastest, compressing warranty claim rates while extending product lifecycles.
RoHS recast directives in Europe are tightening cadmium and lead thresholds in connector substrates and platings. Manufacturers serving EU-bound medical and industrial audio equipment must reformulate solder alloys and migrate to tin-bismuth or SAC305 compositions. German laboratory certification houses are experiencing backlog surges as suppliers race to validate new material stacks before enforcement deadlines.
Direct procurement from stamping houses is displacing tiered distribution for mid-volume professional audio brands. North American musical instrument manufacturers now source 3.5mm and 6.35mm jacks directly from Dongguan factories, bypassing traditional connector distributors. This channel compression is most visible among boutique guitar pedal builders in Texas and Tennessee seeking lot-size flexibility below distributor minimums.
Audio Jack Market Segmentation
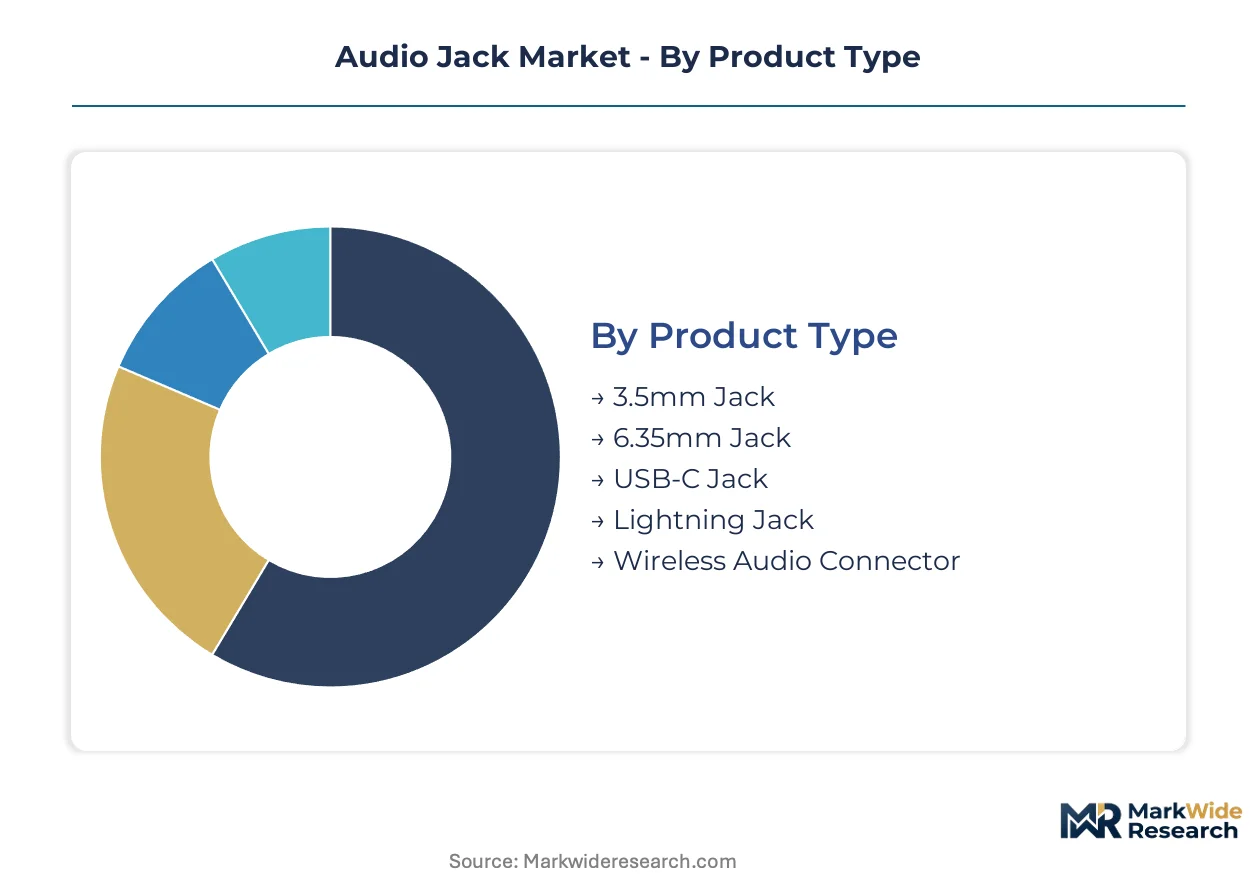
Audio jack manufacturers navigate divergent demand curves across connector form factors, signal architectures, and end-use verticals. Each segment imposes distinct tolerance specifications, certification requirements, and volume economics that reshape procurement patterns and margin structures.
Product Type:
Connector dimensions and interface protocols span legacy analog preservation to wireless signal transmission, with each variant commanding differentiated tooling investments and end-use loyalty.
- 3.5mm Jack:Cylindrical nickel-plated brass housings with phosphor bronze contacts remain the universal standard for headphones, smartphones, and laptops due to minimal insertion force and backward compatibility. Studio monitoring chains in Germany and the United States sustain premium orders for gold-plated variants with enhanced cycle life.
- USB-C Jack:Reversible 24-pin connectors integrate digital audio and power delivery, eliminating dedicated analog ports in Samsung, Apple, and Xiaomi flagship devices. Communication device OEMs in Shenzhen and Dongguan are accelerating procurement as they phase out 3.5mm jacks entirely.
- 6.35mm Jack:Quarter-inch variants dominate guitar amplifiers, mixing consoles, and live sound systems where mechanical robustness outweighs miniaturization.
- Lightning Jack:Apple's proprietary 8-pin connector persists in legacy iPhone and iPad installed bases, though new design wins have ceased.
- Wireless Audio Connector:Bluetooth and proprietary RF modules in charging cases and dongles serve mobile-first users abandoning physical jacks entirely.
The dominant share belongs to 3.5mm Jack, while USB-C Jack is closing the gap fastest.
Technology:
Signal processing architectures impose distinct electromagnetic constraints, with analog preservation competing against digital transition pathways across professional and consumer tiers.
- Analog Audio:Continuous voltage waveforms through conductive contacts deliver zero-latency transmission for real-time monitoring applications. Musical instrument manufacturers in Nashville and Hamburg specify unshielded or shielded variants based on cable run length and interference exposure.
- Digital Audio:Pulse-code modulation through USB-C or Lightning connectors enables software-defined signal processing and noise cancellation algorithms. Communication device OEMs prioritize digital interfaces for integration with voice assistant ecosystems.
- Balanced Audio:Three-conductor configurations with phase-inverted signal pairs cancel electromagnetic interference in studio environments and long cable runs.
- Unbalanced Audio:Two-conductor designs dominate consumer headphones and portable electronics where cost minimization supersedes noise rejection.
- Optical Audio Interface:Toslink connectors transmit S/PDIF signals via light pulses, persisting in home theater receivers and gaming consoles.
Analog Audio commands the largest installed base, though Digital Audio demonstrates the steepest expansion trajectory among new product introductions.
Application:
End-use verticals range from mass-market consumer electronics to precision-tolerant professional installations, each segment dictating distinct reliability grades and volume profiles.
- Consumer Electronics:Smartphones, tablets, laptops, and portable media players drive the highest unit volumes with tight tolerance for miniaturization. Chinese OEMs in the Pearl River Delta cluster source billions of units annually for domestic and export assembly.
- Professional Audio Equipment:Studio monitors, mixing consoles, and live sound systems demand MIL-qualified variants with enhanced vibration resistance and gold-plated contacts. FAA-mandated cockpit audio upgrades sustain orders for aviation-grade 3.5mm jacks.
- Communication Devices:Two-way radios, dispatch systems, and military headsets prioritize electromagnetic shielding and environmental sealing.
- Musical Instruments:Electric guitars, keyboards, and synthesizers specify 6.35mm jacks with reinforced strain relief for stage durability.
- Automotive Entertainment Systems:Head units and rear-seat entertainment modules integrate 3.5mm auxiliary inputs alongside Bluetooth modules for legacy device compatibility.
Consumer Electronics retains volume leadership, while Professional Audio Equipment generates the highest margin per unit.
Customer Type:
Procurement channels fragment across integrated OEM supply chains, independent distribution networks, and emerging direct-sourcing relationships.
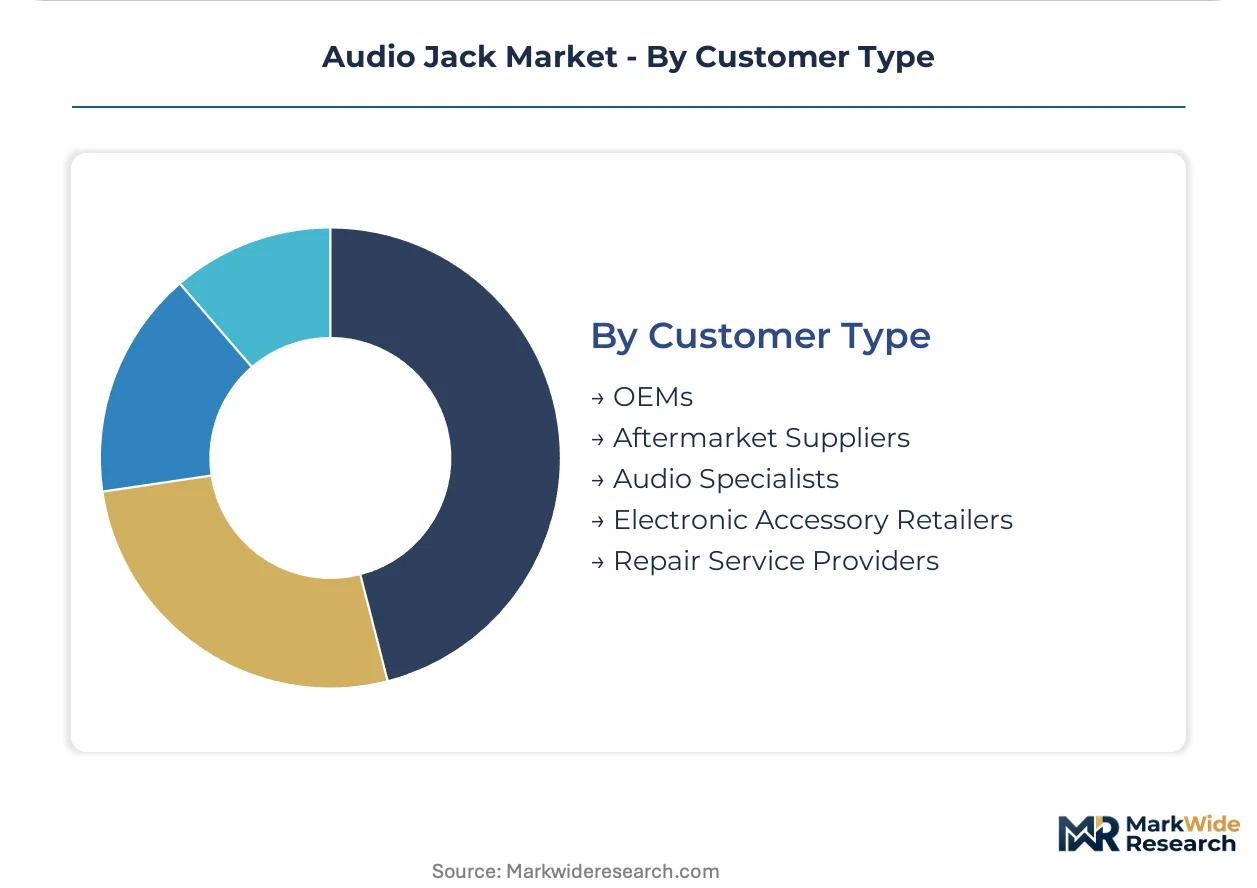
- OEMs:Original equipment manufacturers in consumer electronics and automotive specify custom tooled variants with proprietary housing geometries and logo embossing. Foxconn, BYD Electronics, and Pegatron negotiate annual blanket orders with Dongguan stamping houses.
- Aftermarket Suppliers:Independent brands source generic jacks for replacement cables, adapters, and repair kits distributed through Amazon and AliExpress storefronts.
- Audio Specialists:Boutique cable manufacturers and high-end headphone builders commission small-batch runs with exotic plating chemistries and cryogenic treatment.
- Electronic Accessory Retailers:Mobile phone shops and electronics chains stock adapter dongles and replacement jacks for immediate consumer purchase.
- Repair Service Providers:Independent technicians and authorized service centers procure replacement jacks for board-level soldering operations.
OEMs dominate procurement volume, though direct sourcing from stamping houses is compressing distributor margins fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional audio equipment manufacturers in Germany and the United States consume 3.5mm and 6.35mm jacks for zero-latency studio chains, while Chinese smartphone OEMs accelerate USB-C procurement as analog ports disappear from flagship devices.
United States
FAA-mandated cockpit audio retrofits sustain MIL-qualified 3.5mm orders for aviation-grade vibration resistance. FCC Part 15 governs electromagnetic interference thresholds for shielded jacks in communication devices. Texas and Tennessee host boutique guitar pedal builders sourcing directly from Dongguan stamping houses.
Germany
Studio monitoring chains in Hamburg demand gold-plated 3.5mm variants with enhanced cycle life for professional installations. ECHA REACH restrictions on hexavalent chromium plating compel solder alloy reformulation. German laboratory certification houses face backlog surges validating RoHS-recast material stacks.
China
Samsung, Apple, and Xiaomi suppliers in Shenzhen phase out dedicated analog ports entirely. SAMR-administered GB standards mandate dimensional tolerances and environmental testing protocols. Dongguan factories compress lead times through vertically integrated stamping, plating, and automated assembly capacity.
India
PLI scheme incentives for mobile and audio device assembly in Tamil Nadu and Karnataka generate localized connector kit demand. The country's national electronics regulator enforces BIS certification for domestically sold jacks. Bengaluru and Chennai clusters attract sub-assembly procurement from global OEMs.
Japan
Specialty chemical suppliers in Osaka and Tokyo control high-reliability gold and palladium-nickel plating chemistries. METI industrial standards shape precision stamping tolerances for automotive entertainment modules. Aging tool and die craftsmanship faces pipeline replacement challenges without sufficient apprenticeship programs.
Audio Jack Market Vendor Landscape
Capability concentration sits with Japanese and German specialty plating houses; scale advantage sits with Chinese stamping conglomerates. The vendor base stratifies across three tiers: precision specialists commanding premium positioning in aerospace and medical audio, mid-volume fabricators serving professional musical instruments, and commodity producers fulfilling consumer electronics procurement. Strategic moves center on backward integration into captive plating capacity and direct OEM relationships that bypass traditional distribution layers.
Within the precision-specialist tier, Hirose Electric and JAE exemplify Japanese manufacturers with upstream control over contact plating and mold fabrication. TE Connectivity occupies a position among multi-region operators servicing both consumer electronics OEMs and industrial audio equipment builders. Amphenol anchors North American supply through dominance in aerospace and military-qualified connector variants.
| Leading Market Players |
|---|
| Hirose Electric |
| LS Mtron |
| Amphenol |
| JST |
| ACON Laboratories |
| Molex |
| JAE |
| SMK Corporation |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Japan's Osaka-based specialty chemical suppliers command captive supply of high-reliability gold and palladium-nickel plating chemistries, anchoring margin pools in aerospace and medical audio jack tiers where MIL-spec certification creates pricing power unreachable by commodity stamping houses.
Pricing Analysis
Long-term offtake agreements dominate procurement between Dongguan stamping houses and Foxconn-class OEMs, insulating volume commitments from London Metal Exchange nickel volatility. Price differentiation stratifies across certification grade, volume scale, and customization level—aviation-qualified variants with enhanced vibration resistance command substantial premiums over consumer-grade 3.5mm jacks. Cost compression in the consumer tier intensifies because USB-C substitution eliminates dedicated analog port demand. Boutique guitar pedal builders in Texas exhibit highest price sensitivity; FAA-mandated cockpit retrofit programs show lowest sensitivity due to non-negotiable reliability requirements.
Supply Chain Analysis
Export-control regimes on precision stamping equipment from Germany and Japan constrain capacity expansion in emerging manufacturing clusters, fragmenting supply security across jurisdictions. Manufacturing concentrates in China, Japan, and Germany—Guangdong province hosts vertically integrated stamping-to-assembly capacity, Osaka suppliers control critical plating chemistries, and German toolmakers maintain micron-tolerance die craftsmanship. Raw material dependencies draw from London Metal Exchange nickel futures, phosphor bronze contact substrates, and RoHS-compliant solder alloys. Single-source vulnerability in Japanese specialty chemical supply creates structural risk. Distribution runs through direct OEM procurement compressing traditional distributor layers fastest among North American musical instrument manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as USB-C audio virtualization fragments the installed base between legacy analog preservation and digital transition pathways, with interoperability mandates in European right-to-repair proposals preserving modular jack architectures against sealed-unit alternatives.
For Market Incumbents: Build captive plating capacity moats to defend margin position against commodity erosion. Hirose Electric's upstream control over mold fabrication and contact plating demonstrates defensible positioning. Defend professional audio segment share through MIL-spec certification maintenance against USB-C substitution threat. Add precision stamping capacity in India's Tamil Nadu cluster to capture PLI-scheme procurement localization.
For New Entrants and Emerging Players: Pursue aviation retrofit aftermarket as FAA-mandated cockpit audio upgrades sustain demand for vibration-resistant 3.5mm variants with lower certification barriers than OEM qualification. Target India's Karnataka electronics assembly corridor where localized connector kit demand outstrips domestic stamping capacity. Deploy direct-to-OEM go-to-market positioning bypassing distributor markups for mid-volume professional audio brands.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Chinese stamping conglomerates seeking exit liquidity as consumer electronics volume plateaus. Five-to-ten-year viability favors precision specialists with aerospace-medical certification moats over commodity consumer-grade exposure. Monitor ECHA REACH enforcement timelines as signal for green chemistry reformulation investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Chemistry | Captive supply of REACH-compliant gold and palladium-nickel surface finishes insulates Hirose Electric from Japanese specialty chemical supplier concentration risk. |
| Aviation Certification Investment | FAA MIL-STD-810 qualification for enhanced vibration resistance opens cockpit retrofit procurement closed to consumer-grade competitors. |
| India Manufacturing Footprint Expansion | Tamil Nadu and Karnataka PLI incentives localize connector kit supply for Samsung and Xiaomi assembly operations. |
| Magnetic Breakaway Product Line Launch | Shenzhen gaming peripheral OEMs adopt detachable cable architectures to compress warranty claim rates and extend product lifecycles. |
| Direct OEM Procurement Channel Development | Texas and Tennessee boutique guitar pedal builders source Dongguan factories directly, bypassing distributor minimums for lot-size flexibility. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Stakeholder conversations spanned connector procurement managers at Foxconn-class OEMs, tool and die craftsmen at Japanese precision stamping houses, regulatory affairs leads at German laboratory certification bodies, and aftermarket sourcing directors at North American musical instrument manufacturers. Secondary sources included ECHA REACH substance restriction databases, FAA airworthiness directive filings, SAMR GB standards documentation, and SEC 10-K supply chain disclosures from listed connector manufacturers. Bottom-up volume builds from stamping house capacity data triangulate against top-down OEM procurement estimates.
Calibration against historical substitution patterns—USB-C displacement rates in Samsung and Apple flagships, aviation retrofit cycle timing, and PLI scheme uptake velocity—shapes the projection framework. Segmentation dimensions span connector form factor, signal architecture, certification grade, and end-use vertical. CAGRs derive from installed base erosion modeling in consumer electronics offset by industrial and professional audio preservation. Industry-specific inputs include London Metal Exchange nickel price trajectory assumptions and ECHA enforcement timeline scenarios.
Macroeconomic conditions sit as an overlay; deviation in Chinese electronics export demand, European regulatory enforcement intensity, or Indian assembly incentive continuity would shift the trajectory. Forecasts reflect documented assumptions about USB-C substitution velocity and aviation retrofit cycle persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
A/V Cassette Housings & Parts Market