
 Wireless Keyboard Market | 2026-2036
Wireless Keyboard Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Keyboard Market Analysis
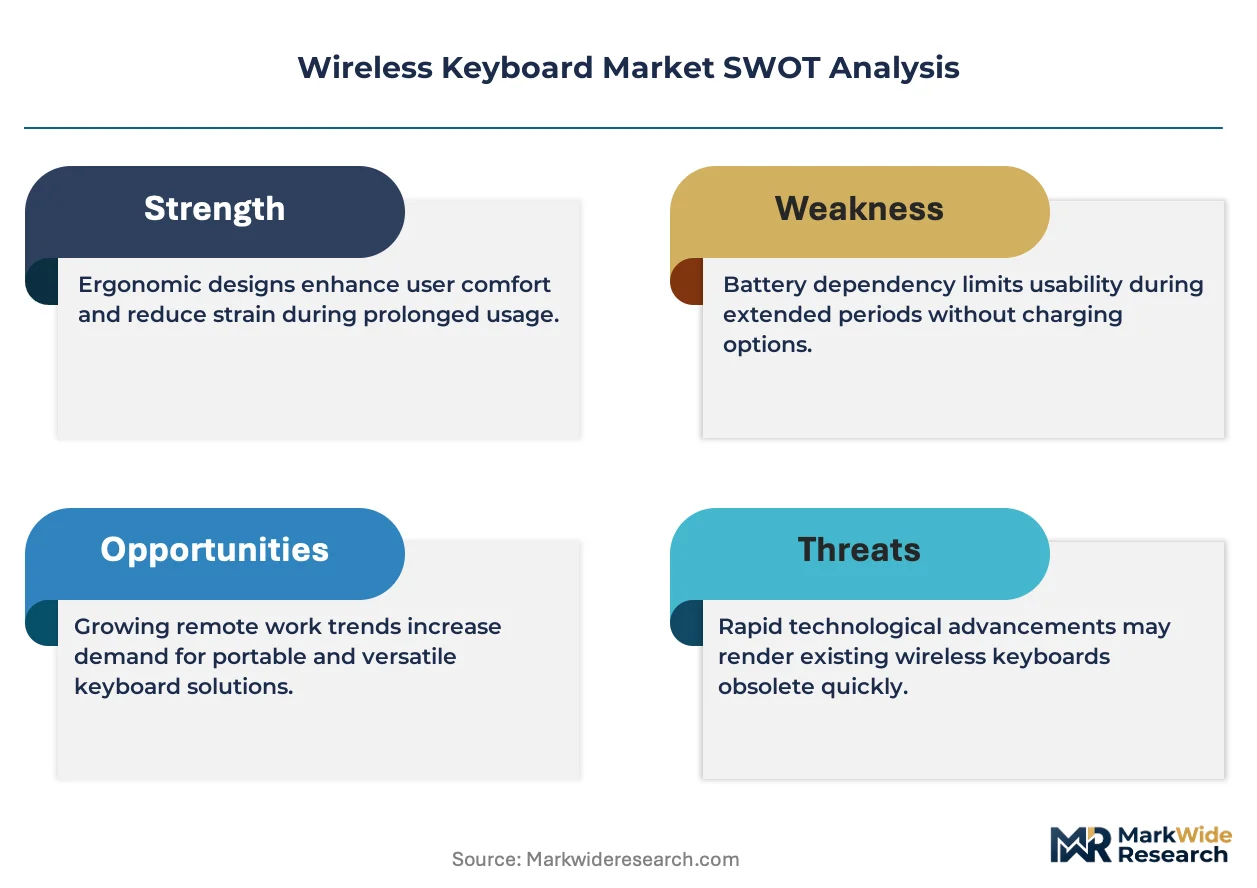
Asset-light manufacturing through original design manufacturer partnerships is rewriting competitive entry barriers in the wireless keyboard sector. Logitech leverages its captive supply chain and direct-to-enterprise sales infrastructure to sustain margin control across professional segments. Razer dominates gaming-oriented mechanical configurations with high-switch customization, while Keychron specializes in compact tenkeyless layouts that anchor enthusiast community loyalty. Apple competes through proprietary ecosystem lock-in rather than cross-platform compatibility.
A wireless keyboard is a human interface device employing radio frequency or optical transmission protocols to relay keystroke data to a host system without physical cabling, typically operating on Bluetooth or dedicated RF protocols. Primary commercial purpose centers on untethered workstation flexibility for mobile professionals and reduced desktop clutter in multi-device environments. Mechanical switch configurations command premium positioning among gamers and coders, while membrane assemblies retain cost-sensitive home user volume. Bluetooth connectivity leads consumer preference for multi-pairing versatility, though RF maintains latency advantages that gaming segments prioritize. Compact and tenkeyless form factors are gaining fastest among remote professionals seeking portable setups.
FCC Part 15 regulations govern intentional radiators in the United States, mandating emission limits that shape RF chipset selection and antenna design for manufacturers targeting American distribution. CE marking under the EU Radio Equipment Directive and REACH substance restrictions constrain material choices and market access protocols for European-bound shipments. Stakeholders must monitor evolving battery transportation rules from IATA and national postal regulators, as lithium-cell integration in rechargeable models introduces compliance complexity that can delay regional launches.
Market Dynamics
Enterprise IT refresh cycles and gaming peripheral upgrades are converging to reshape demand composition, while FCC Part 15 and CE marking directives are compressing design-to-market timelines for RF-enabled peripherals.
Growth Catalysts
- Bluetooth Low Energy mandates:FCC emission limits and EU Radio Equipment Directive certification requirements are accelerating chipset upgrades toward lower-power architectures, expanding battery life specifications that enterprise buyers prioritize for hybrid deployments.
- Mechanical switch customization:Gaming and developer segments are driving demand for hot-swappable key switches, creating aftermarket ecosystem revenue streams that extend product lifecycles beyond traditional replacement cycles.
- Remote workstation portability:United States-based knowledge workers are standardizing compact tenkeyless and 75% layouts as primary input devices, collapsing the distinction between office and home peripherals.
Market Restraints
- Lithium-ion cell supply concentration:Rechargeable keyboard battery packs depend on cylindrical cell production concentrated in East Asian manufacturing clusters, exposing margins to raw material transport cost volatility and IATA shipping rule changes.
- RF latency floor:Bluetooth protocol stack overhead maintains input lag above dedicated 2.4 GHz RF implementations, constraining addressable market share within competitive gaming segments where sub-1ms response thresholds dominate purchasing criteria.
- Membrane assembly cost compression:Budget consumer segments face pricing pressure from integrated laptop keyboards and touchscreen input methods, limiting volume recovery in entry-level wireless categories.
Strategic Opportunities
- India PLI scheme alignment:Electronics manufacturing incentive structures are attracting ODM partnerships for export-oriented keyboard assembly, creating tariff-advantaged supply routes into Middle Eastern and African distribution channels.
- Multi-device pairing convergence:Bluetooth 5.3 and LE Audio protocol integration enables seamless switching between laptops, tablets, and smartphones, opening unified peripheral categories that previously required separate device purchases.
- Ergonomic certification tailwinds:Corporate wellness programs and OSHA-adjacent workplace safety guidelines in North American enterprises are mandating adjustable split-keyboard configurations for repetitive strain injury prevention.
Industry Challenges
- Firmware security validation:Wireless dongle and Bluetooth stack implementations require ongoing vulnerability patching, forcing manufacturers to maintain software engineering capabilities that membrane-era vendors rarely possessed.
- Antenna design complexity:Metal chassis preferences among premium mechanical keyboard buyers interfere with RF propagation, demanding specialized engineering talent for enclosure-integrated antenna tuning that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Keyboard Market |
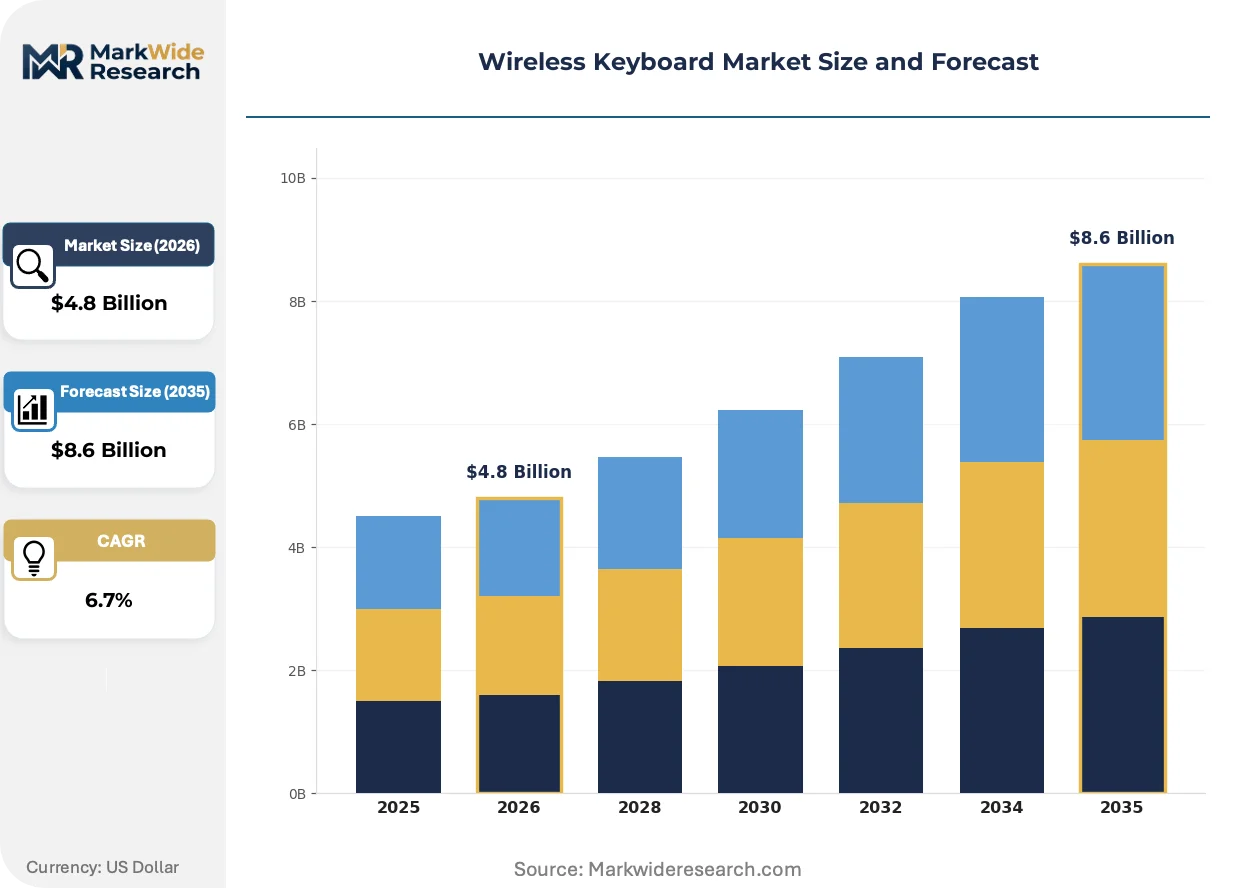
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Membrane, Scissor, Chiclet Connection Technology: Bluetooth, RF, Infrared, NFC End User: Home Users, Gamers, Professionals, Educational Institutions Form Factor: Full-size, Tenkeyless, Compact, Ergonomic |
| Companies Covered | ASUS, Apple, Logitech, Akko, NuPhy, Keychron, SteelSeries, Redragon, Razer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Keyboard Market Emerging Trajectories
Radio frequency architecture decisions and power management integration are compressing traditional hardware boundaries, while procurement patterns are fragmenting across direct-to-enterprise and enthusiast community channels.
Low-profile optical switches are collapsing the thickness gap between mechanical precision and notebook-style portability. Corporate procurement teams in financial services and technology verticals are specifying these configurations for executive travel kits. The structural consequence is collapsing premium pricing tiers that previously separated full-travel mechanical from scissor-switch membrane categories.
CE marking under the EU Radio Equipment Directive and REACH substance restrictions are tightening material disclosure requirements for plastic housings and circuit board substrates. Manufacturers must now document full supply chain chemical composition before European customs clearance. German and French distribution partners are demanding pre-certified SKU configurations that eliminate regional launch delays.
Direct-to-consumer configuration tools are displacing traditional retail assortment planning for enthusiast-grade peripherals. Buyers in the United States and United Kingdom are specifying switch types, keycap materials, and case colors through web-based interfaces that bypass distributor markup. This channel compression is most visible among software developers and content creators who prioritize tactile feedback customization over immediate retail availability.
Wireless Keyboard Market Segmentation
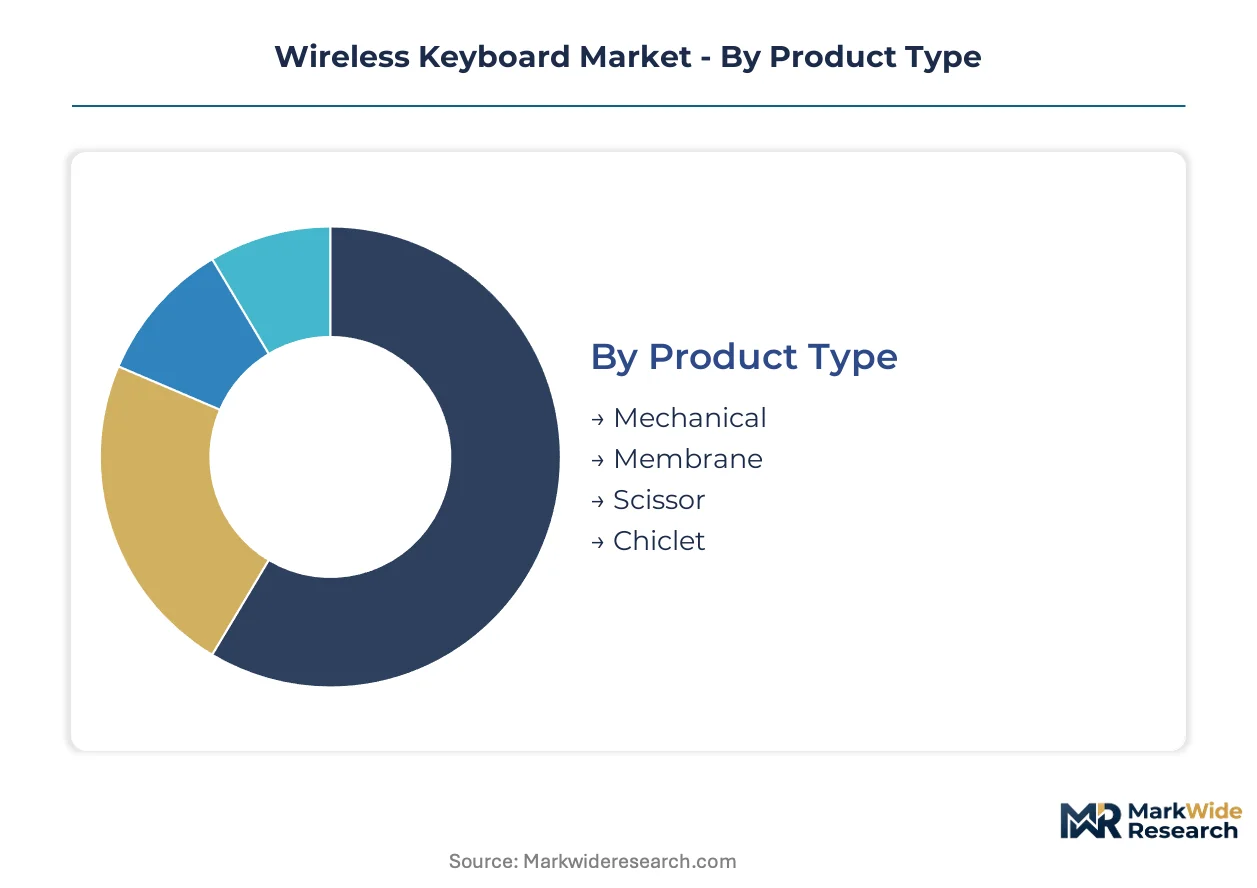
Wireless keyboard segmentation reveals divergent engineering priorities across user workflows. Switch mechanism selection and connectivity protocol decisions fundamentally reshape procurement patterns among enterprise buyers and enthusiast communities.
Product Type:
Mature mechanical switch technology commands premium positioning while membrane assemblies retain cost-sensitive volume leadership across mass retail channels.
- Mechanical:Individual spring-actuated switches deliver tactile feedback and durability ratings exceeding fifty million keystrokes. United States-based software developers and competitive gamers prioritize hot-swappable PCB configurations that enable switch customization without soldering equipment.
- Membrane:Rubber dome matrices bonded to circuit substrates achieve sub-fifteen-dollar price points through automated assembly processes. Budget-conscious home users in India and Southeast Asia sustain volume demand despite shorter actuation lifecycles.
- Scissor:X-shaped stabilizer mechanisms enable ultra-low travel distances typical of laptop-style integration. Corporate procurement teams specify these for executive travel kits requiring minimal bag depth.
- Chiclet:Isolated square keycaps with scissor-derived mechanisms balance aesthetics against dust resistance. Consumer electronics bundling agreements with PC OEMs drive shipment concentration.
Membrane retains volume leadership; mechanical holds the steepest expansion curve.
Connection Technology:
Cost tier stratification separates royalty-free protocol implementations from licensed certification requirements that inflate bill-of-materials costs.
- Bluetooth:Standardized wireless protocol enabling multi-device pairing across laptops, tablets, and smartphones. FCC Part 15 emission compliance and Bluetooth SIG certification costs constrain entry-level manufacturer participation.
- RF:Dedicated 2.4 GHz transceiver implementations achieve sub-1ms latency through proprietary dongle pairings. Esports competitors in South Korea and Germany prioritize these configurations for tournament-grade reliability.
- Infrared:Line-of-sight optical transmission requires unobstructed transmitter-receiver alignment. Legacy conference room installations and specialized industrial environments sustain niche demand.
- NFC:Near-field pairing protocols enable tap-to-connect workflows for shared workstation environments. Enterprise security-conscious financial services verticals pilot these for rapid user authentication handoffs.
Bluetooth dominates shipment volumes; RF captures the highest per-unit margins in gaming-specialized channels.
End User:
Application-driven specification divergence separates ergonomic certification requirements from aesthetic customization priorities across buyer personas.
- Home Users:Price-sensitive residential purchasers prioritize plug-and-play simplicity over advanced configuration options. Retail shelf placement and bundled mouse combinations drive purchase decisions.
- Gamers:RGB lighting synchronization, macro programmability, and N-key rollover specifications define competitive positioning. Mechanical switch actuation force preferences fragment across first-person shooter versus real-time strategy player communities.
- Professionals:Enterprise IT departments specify wireless peripherals for hybrid workforce deployments. OSHA-adjacent ergonomic guidelines in United States corporations increasingly mandate adjustable split-keyboard configurations.
- Educational Institutions:K-12 and higher education procurement operates through volume discount frameworks with extended warranty requirements. Spill resistance and reinforced keycap attachments rank above performance specifications.
Home users retain volume leadership; professionals are climbing the fastest on hybrid work infrastructure investments.
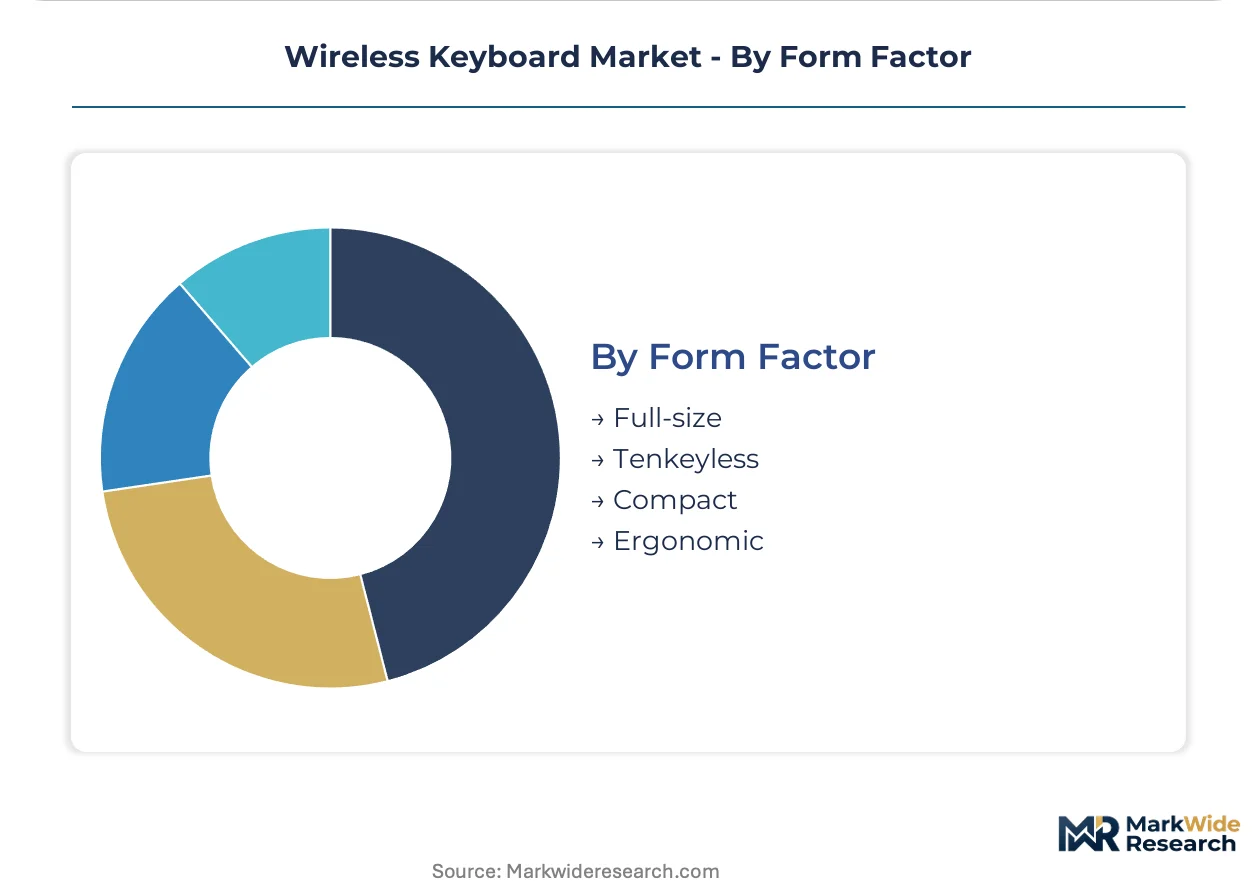
Form Factor:
Customer type stratification separates full-travel traditionalists from mobile-first minimalists seeking bag-friendly dimensions.
- Full-size:Standard 104-key layouts including numeric keypads sustain data entry professional productivity. Accounting and financial analyst workstations in New York and London maintain preference for complete numpad inclusion.
- Tenkeyless:Eighty-seven key configurations eliminate numeric pads while preserving function rows. Software developers and content creators prioritize mouse proximity and desk space efficiency.
- Compact:Sixty-percent and smaller layouts compress arrow keys and function rows through layer programming. Digital nomad communities and coffee shop remote workers drive adoption.
- Ergonomic:Split-keyboard angles and tenting mechanisms address repetitive strain injury prevention. Corporate wellness program mandates in California and Massachusetts technology employers accelerate specification.
Full-size retains volume leadership; compact gains share fastest among location-independent knowledge workers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electronics manufacturing incentives and workplace safety regulations are reshaping procurement patterns across major demand centers. Corporate IT refresh cycles and gaming peripheral upgrades sustain volume leadership in developed markets, while export-oriented assembly investments concentrate in emerging supply hubs.
United States
Enterprise hybrid workforce deployments and gaming peripheral upgrades drive sustained demand for mechanical and ergonomic configurations. FCC Part 15 emission regulations mandate specific RF chipset architectures for products entering American distribution channels. Austin and Seattle technology corridors anchor corporate procurement decision-making for professional-grade peripherals.
Germany
Esports competitors and software developers prioritize sub-1ms latency RF implementations for tournament-grade reliability. CE marking under the EU Radio Equipment Directive and REACH substance restrictions constrain material choices for European-bound shipments. Berlin and Munich industrial design clusters specialize in compact tenkeyless layouts for mobile professionals.
China
Domestic gaming community expansion and original design manufacturer capacity sustain both consumption and export production. MIIT radio transmission standards and GB certification requirements shape Bluetooth and RF protocol implementations for local and international markets. Shenzhen and Dongguan electronics manufacturing belts concentrate global keyboard assembly capacity for premium mechanical configurations.
India
PLI scheme electronics manufacturing incentives attract ODM partnerships for export-oriented keyboard assembly operations. BIS quality certification and TRAI wireless equipment regulations establish compliance frameworks for domestic market entry. Karnataka and Tamil Nadu technology corridors develop tariff-advantaged supply routes into Middle Eastern and African distribution channels.
South Korea
Professional esports infrastructure investments sustain demand for specialized low-latency gaming peripherals. MFDS and KCC certification requirements govern wireless device market access protocols. Seoul Capital Area technology clusters drive specification standards for competitive gaming switch actuation preferences.
Wireless Keyboard Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Enterprise direct-sales infrastructure and enthusiast community engagement represent distinct competitive moats. Three archetypes dominate: ecosystem-integrated technology giants, gaming-specialized peripheral manufacturers, and community-driven compact layout specialists. Strategic moves center on ODM partnership restructuring and direct-to-consumer configuration platform deployment.
Within the ecosystem-integrated tier, Apple exemplifies proprietary lock-in strategies over cross-platform compatibility. Gaming-specialized manufacturers Razer and SteelSeries occupy positions emphasizing mechanical switch customization and RGB synchronization ecosystems. Community-driven specialists Keychron and NuPhy represent enthusiast-focused compact form factor development, anchoring loyalty through tenkeyless and 75% layout innovation.
| Leading Market Players |
|---|
| ASUS |
| Apple |
| Logitech |
| Akko |
| NuPhy |
| Keychron |
| SteelSeries |
| Redragon |
| Razer |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container rates from Shenzhen to Los Angeles directly compress margins on mechanical keyboard imports while amplifying price spreads between FCC-certified premium SKUs and uncertified economy alternatives. This freight corridor cost volatility reinforces supply concentration in Guangdong province and forces distributors to segment inventory allocation across certification tiers.
Pricing Analysis
Certification level creates the primary spread between Bluetooth SIG-qualified premium units and pre-certified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FCC Part 15 compliance costs, mechanical switch grade, and after-sales warranty bundling. Cost compression in membrane assemblies intensifies because integrated laptop keyboards eliminate standalone peripheral necessity at entry price points. Educational institutions exhibit highest price sensitivity through volume discount frameworks, while esports competitors absorb premium positioning for sub-1ms RF latency specifications.
Supply Chain Analysis
PCB substrate and lithium-ion cylindrical cells feed from concentrated East Asian manufacturing clusters in China, South Korea, and Japan. Key switch mechanisms draw from precision metal stamping operations in Dongguan and Taoyuan, while Bluetooth RF chipsets hinge on semiconductor fabrication in Hsinchu and Seoul. Single-source vulnerability in rare-earth magnet supply for speaker-integrated models exposes assembly schedules to export restriction volatility. Distribution runs through ODM-direct enterprise contracts and Amazon-first consumer channels with diminishing traditional retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antenna engineering talent scarcity constrains premium metal chassis development cycles, separating vendors with in-house RF capabilities from commodity assemblers dependent on external design houses.
For Market Incumbents: Insulate enterprise margin structures through captive FCC pre-certification pipelines that accelerate SKU launch velocity against emerging competitors. Deepen backward integration into mechanical switch production to offset raw material transport cost volatility from East Asian suppliers. Prioritize firmware security engineering capabilities that membrane-era entrants rarely possess, converting vulnerability patching competence into contractual renewal leverage with financial services buyers. For New Entrants and Emerging Players: Build out direct-to-consumer configuration platforms targeting software developers in Austin and Seattle technology corridors with hot-swappable PCB customization tools. The most penetrable white-space sits in ergonomic split-keyboard configurations for California corporate wellness mandates, bypassing established gaming peripheral incumbents. Pursue India PLI scheme alignment for tariff-advantaged export routes into Middle Eastern distribution channels rather than competing on domestic US retail shelf placement. For Investors and Strategic Acquirers: CE marking enforcement under the EU Radio Equipment Directive reshapes the acquisition landscape toward pre-certified SKU libraries that eliminate European customs delay risk. Long-term viability favors targets with established ODM partnerships in Karnataka and Tamil Nadu technology corridors over pure-brand distributors lacking manufacturing influence. Watch Bluetooth 5.3 LE Audio protocol adoption rates as the inflection signal separating unified peripheral platform investments from legacy single-device category plays.| Strategic Initiative | Industry Significance |
|---|---|
| ODM Partnership Restructuring | Asset-light manufacturing through Dongguan and Shenzhen design houses compresses capital requirements for premium mechanical configurations. |
| Direct-to-Consumer Configuration Platform | Web-based switch and keycap customization tools bypass distributor markup while capturing developer community loyalty. |
| FCC Pre-Certification Pipeline Investment | Accelerated Part 15 emission testing protocols compress design-to-market timelines for enterprise procurement cycles. |
| Ergonomic Certification Program | OSHA-adjacent workplace safety alignment opens California and Massachusetts corporate wellness procurement channels. |
| Firmware Security Capability Buildout | In-house vulnerability patching teams address financial services buyer requirements for wireless dongle stack integrity. |
Methodological Framework
A spread of perspectives from enterprise IT procurement managers, ODM engineering directors, esports team equipment coordinators, and FCC compliance consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Bluetooth SIG certification databases, SEC 10-K peripheral segment disclosures, and IATA lithium battery shipping rule amendments. Bottom-up shipment aggregation across ODM production lines and top-down enterprise procurement budget analysis were triangulated against customs import records.
Demand-supply balance modeling across the projection horizon incorporated switch mechanism type, connectivity protocol, end-user application, and regional regulatory cluster segmentation dimensions. CAGRs were derived from fitted growth curves against historical refresh cycle patterns and projected hybrid workforce infrastructure investments. Key inputs included FCC Part 15 enforcement trend trajectories and PLI scheme incentive qualification timelines for Indian assembly operations.
Stress conditions across lithium-ion cell supply disruptions, CE marking documentation delays, and Bluetooth protocol stack vulnerability exposures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise IT refresh cadence and gaming peripheral upgrade elasticity. Cross-checking against hyperscaler capex disclosures and commercial real estate occupancy data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Mobile Phone Power Accessories Market