
 Sports Electronics Devices Market | 2026-2036
Sports Electronics Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Electronics Devices Market Outlook
IEC 62368-1 safety certification for audio and wearable electronics is unwinding competitive access across the sports electronics landscape. Garmin Ltd. leverages integrated GPS chipset design to sustain premium positioning in outdoor athlete segments. Apple Inc. dominates smartwatch-based fitness ecosystems through vertical control over silicon and software. Catapult Sports anchors elite team analytics with player-tracking hardware deployed across professional football and rugby leagues.
Sports electronics devices encompass sensor-embedded hardware engineered for motion capture, biometrics, and real-time telemetry in athletic contexts, typically integrating accelerometers operating at sampling rates above 100 Hz and wireless protocols enabling sub-50-millisecond latency. Their commercial purpose centers on quantifying human performance to inform training load management and injury risk reduction. Wearables and fitness trackers command the deepest margin pools as subscription-based coaching platforms attach to hardware ecosystems. Bluetooth-enabled devices lead volume shipments while GPS-integrated systems capture premium pricing in outdoor and team applications. NFC deployments remain nascent, concentrated in access-control and payment-integrated athlete bands at institutional facilities.
FCC Part 15 governs unlicensed radio emissions for U.S.-marketed wearables, while the EU AI Act imposes conformity obligations on algorithmic coaching recommendations processed within European jurisdictions. FDA oversight of certain heart-rate monitoring claims as wellness versus medical devices shapes product labeling and liability exposure for manufacturers. Stakeholders must monitor evolving interoperability mandates from ISO and IEC working groups as federated data standards between rival platforms determine ecosystem lock-in intensity.
Market Dynamics
Professional sports teams now mandate biometric monitoring for injury prevention, compressing procurement cycles from annual to quarterly refresh rates across North American leagues and forcing hardware vendors to embed predictive analytics directly into wearable firmware.
Growth Catalysts
- Collegiate athletic program expansion:NCAA Division I universities in the United States tripled spending on athlete monitoring systems, creating institutional demand for GPS-enabled wearables and force-plate technology.
- EU AI Act algorithmic transparency:Performance analytics platforms serving European professional clubs must now disclose training data provenance, accelerating compliance investment by software vendors.
- Accelerometer sampling rate advancement:MEMS sensors operating above 100 Hz enable granular motion capture for pitching biomechanics and swimming stroke analysis, opening high-precision segments previously served by laboratory equipment.
Market Restraints
- Silicon supply concentration:GPS chipset fabrication depends on TSMC and Samsung Foundry capacity in Taiwan and South Korea, exposing outdoor sports device manufacturers to foundry allocation volatility.
- IEC 62368-1 certification timeline:Audio-integrated wearables face extended safety testing cycles, delaying product launches by 4-7 months for smaller hardware vendors.
- Smartphone substitution threat:Advanced IMU arrays in flagship handsets reduce standalone fitness tracker necessity among casual athletes, compressing entry-tier device volumes.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives attract wearable assembly to Tamil Nadu and Karnataka, reducing landed costs for devices targeting South Asian fitness applications.
- NFC-integrated athlete access bands:Stadium credentialing and payment convergence at institutional facilities in Germany and France creates bundled hardware-software service models.
- Sensor fusion convergence:Integration of PPG, accelerometer, and galvanic skin response streams enables multi-modal stress-recovery indices for military and first-responder training programs.
Industry Challenges
- Firmware engineering talent scarcity:Real-time signal processing expertise for sub-50-millisecond latency protocols commands premium compensation, constraining vendor R&D scaling.
- Interoperability standardization delays:ISO and IEC working groups have not finalized federated data exchange formats, perpetuating ecosystem lock-in between rival platform architectures.
- Legacy system integration friction:Professional team analytics departments struggle to correlate new wearable telemetry with decade-old video analysis databases, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Electronics Devices Market |
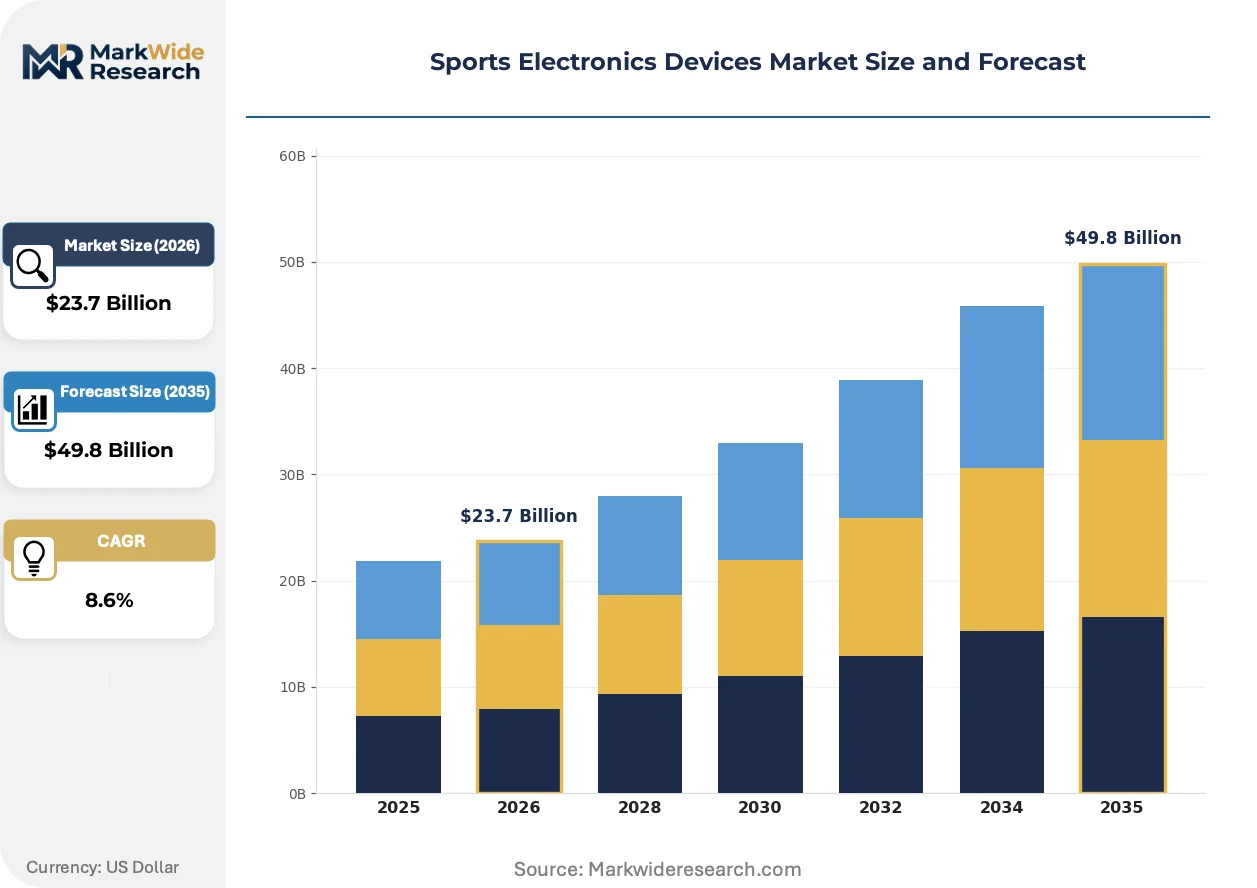
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Headphones, Smart Glasses, Fitness Trackers End User: Athletes, Coaches, Fitness Enthusiasts, Teams Technology: Bluetooth, GPS, RFID, NFC Application: Performance Monitoring, Health Tracking, Training Assistance, Communication |
| Companies Covered | Garmin Ltd., Fitbit (Google), Apple Inc., Polar Electro, Adidas AG, Samsung Electronics Co. Ltd., Catapult Sports, Hawk-Eye Innovations (Sony Corporation), Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Electronics Devices Market Strategic Shifts
Sensor miniaturization and edge computing deployment are compressing the latency-performance tradeoff, enabling real-time coaching interventions that previously required post-session laboratory analysis.
Photoplethysmography is bifurcating from simple heart-rate monitoring into multi-wavelength blood oxygen and hydration status estimation. Elite endurance athletes in cycling and triathlon now demand continuous SpO2 trending during altitude training camps. This capability compression is forcing mid-tier vendors to license optical module IP or exit the performance segment entirely.
The EU AI Act imposes conformity obligations on algorithmic coaching recommendations processed within European jurisdictions. Performance analytics platforms must now maintain audit trails for training load algorithms affecting athlete health decisions. German Bundesliga and English Premier League clubs are demanding vendor documentation of model training data provenance before contract renewal.
Athlete procurement departments now unbundle hardware acquisition from analytics subscriptions, treating sensors as commoditized endpoints while negotiating platform access fees separately. This pattern disrupts integrated vendor business models most visibly across United States collegiate athletic conferences, where procurement consortiums aggregate buying power for software licensing while sourcing wearables through separate RFP processes.
Sports Electronics Devices Market Segmentation
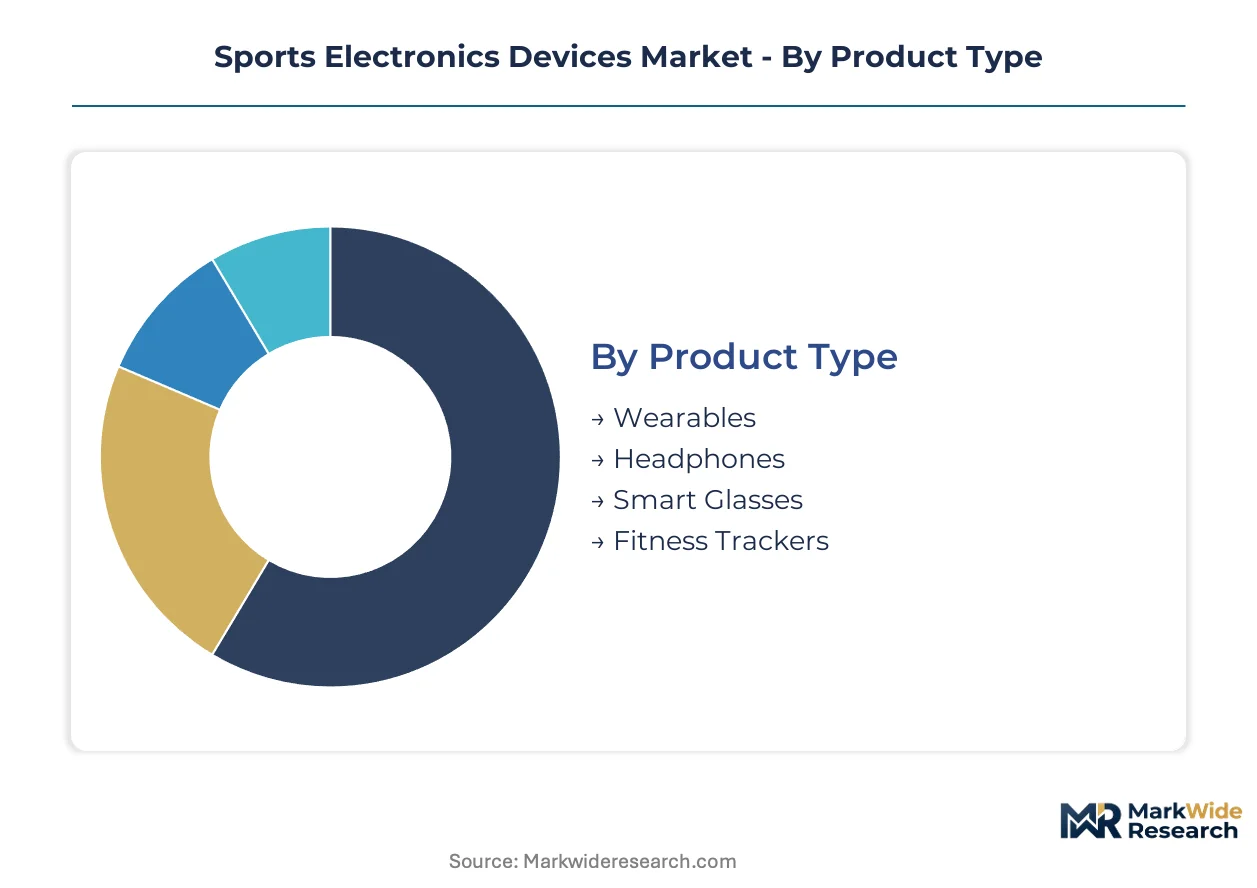
Sports electronics segmentation reveals where hardware commoditization ends and software monetization begins. Margin pools concentrate in ecosystems that lock recurring analytics subscriptions to proprietary sensor hardware.
Product Type:
Premium margin capture follows sensor integration depth rather than device category alone, with multi-modal biometric fusion commanding sustained pricing power.
- Wearables:Full-stack devices embedding accelerometers above 100 Hz, PPG optical modules, and galvanic skin response sensors enable training load algorithms. NCAA Division I programs in the United States now mandate GPS-enabled wearables for rostered athletes, compressing procurement to quarterly refresh cycles.
- Headphones:Audio-integrated biometric monitoring requires IEC 62368-1 safety certification, extending testing timelines by 4-7 months. Bone conduction variants serving open-water swimmers and trail runners bypass ear canal occlusion while maintaining situational awareness.
- Smart Glasses:Optical waveguide displays with sub-50-gram mass targets overlay real-time pace and power metrics for cyclists.
- Fitness Trackers:Entry-tier wristbands face smartphone IMU substitution, compressing volumes among casual athletes.
The dominant share belongs to wearables, while smart glasses are closing the gap fastest through augmented reality training overlays.
End User:
Procurement authority and budget scale vary sharply across this dimension, with institutional buyers demanding predictive analytics APIs while consumers prioritize hardware aesthetics.
- Athletes:Individual competitors in endurance sports drive continuous SpO2 and hydration monitoring adoption. German Bundesliga footballers now negotiate contract clauses permitting personal wearable data ownership.
- Coaches:Staff require dashboard consolidation across 20-30 athlete telemetry streams with sub-50-millisecond latency for real-time substitution decisions.
- Fitness Enthusiasts:Subscription coaching platform attachment rates determine lifetime value for this price-sensitive cohort.
- Teams:Professional rugby and football franchises unbundle hardware from analytics licensing, treating sensors as commoditized endpoints.
Teams command the largest contract values, though coaches are expanding their procurement influence fastest through performance department budget autonomy.
Technology:
Wireless protocol selection dictates use case viability, with latency requirements and range constraints filtering applications.
- Bluetooth:Dominates volume shipments for smartphone-tethered fitness trackers and heart rate straps. FCC Part 15 compliance is standard for U.S. market entry.
- GPS:Multi-constellation chipsets from TSMC-fabricated designs enable meter-level positioning for outdoor athlete tracking. Supply concentration in Taiwan and South Korea exposes manufacturers to foundry allocation volatility.
- RFID:Passive tags support inventory and equipment tracking within training facilities.
- NFC:Stadium credentialing and payment convergence at German and French institutional facilities drives athlete access band deployments.
Bluetooth maintains volume leadership, while NFC is gaining share fastest through bundled hardware-software service models.
Application:
Functional use case segmentation maps directly to regulatory exposure, with health-adjacent claims triggering FDA wellness-versus-medical device scrutiny.
- Performance Monitoring:Real-time telemetry for load management and injury risk reduction. EU AI Act conformity obligations now require audit trails for algorithmic coaching recommendations processed in European jurisdictions.
- Health Tracking:Continuous biometric trending including heart rate variability and sleep architecture. FDA oversight of certain heart-rate monitoring claims shapes product labeling and liability exposure.
- Training Assistance:Form correction through motion capture and haptic feedback.
- Communication:Push-to-talk and alert systems for team coordination during sessions.
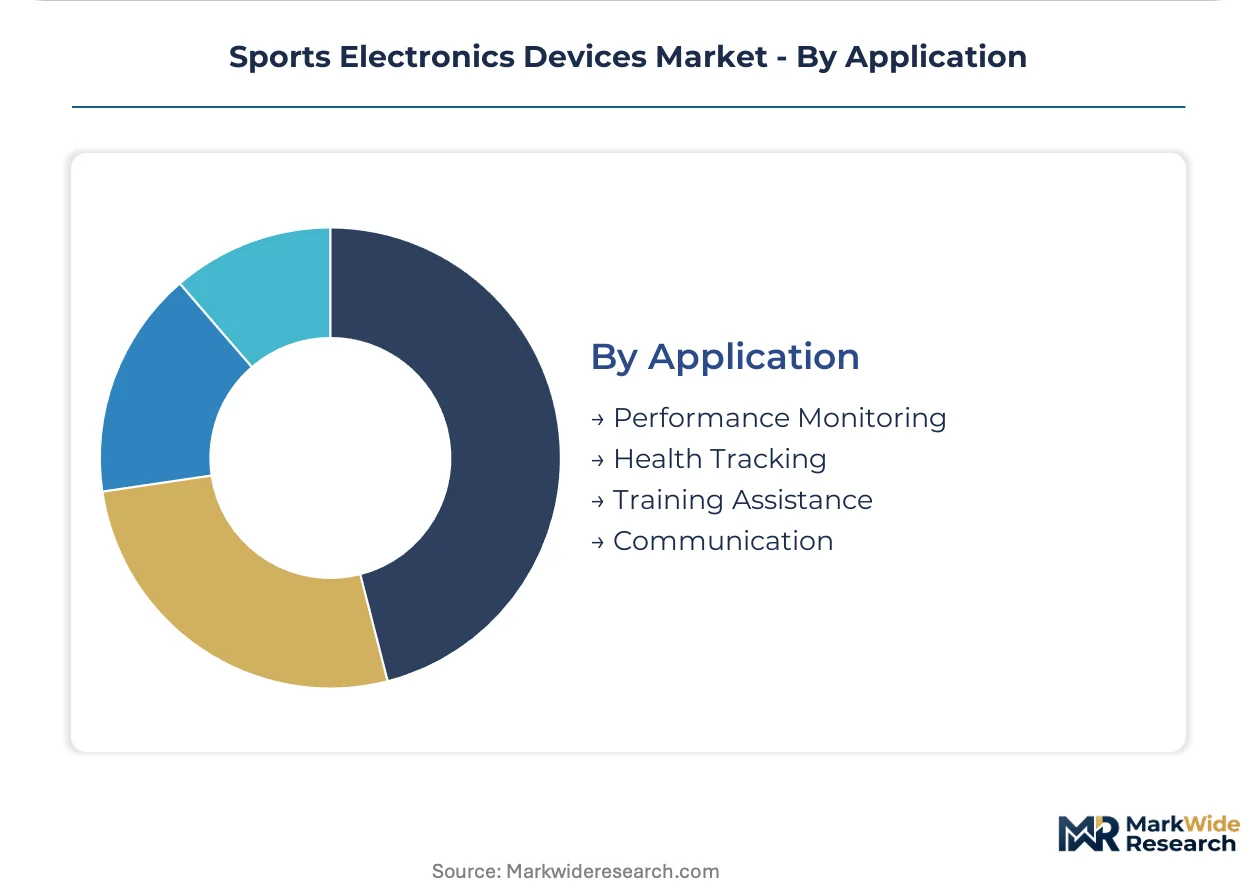
Performance monitoring holds the dominant share, while health tracking is climbing the fastest as optical sensor multi-wavelength expansion enables blood oxygen and hydration estimation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors trans-Pacific electronics distribution, while Taiwan's Hsinchu Science Park foundry output underwrites GPS chipset supply for outdoor athlete tracking devices.
United States
NCAA Division I athletic programs in Texas and California drive institutional procurement of GPS-enabled wearables, with quarterly refresh cycles now standard. FCC Part 15 governs unlicensed radio emissions for Bluetooth fitness trackers. Greater Boston's Route 128 corridor hosts Catapult Sports analytics development for professional football and rugby leagues.
Germany
Bundesliga clubs in Munich and Dortmund mandate vendor documentation of algorithmic training data provenance under EU AI Act conformity obligations. German national data protection authorities enforce GDPR compliance on athlete biometric storage. The Stuttgart region concentrates precision MEMS sensor fabrication for high-frequency accelerometers.
China
MIIT certification requirements for wireless transmission equipment filter market entry for foreign wearable brands. Yangtze River Delta manufacturing clusters in Suzhou and Hangzhou assemble fitness trackers for export markets. Domestic demand for marathon and triathlon equipment accelerates in Shanghai and Beijing metropolitan areas.
Japan
METI industrial standards for wearable device safety shape product development timelines for audio-integrated sports electronics. Kansai region precision manufacturers supply optical PPG modules for heart rate monitoring. Osaka-based engineering firms specialize in sub-50-millisecond latency protocols for real-time coaching systems.
India
Production-linked incentive schemes in Tamil Nadu and Karnataka attract wearable assembly operations for South Asian fitness applications. BIS certification mandates for electronic goods extend product launch timelines by 3-4 months. Bangalore's electronics manufacturing clusters now export Bluetooth-enabled fitness trackers to Middle Eastern markets.
Sports Electronics Devices Market Competitive Environment
Listed leaders compete with private specialists across integrated hardware-software ecosystems, creating a tiered structure where scale-driven platforms face niche precision vendors. The vendor base concentrates around three strategic archetypes: full-stack ecosystem owners controlling silicon-to-cloud verticals, specialist analytics firms serving elite team sports, and component-integrated device manufacturers. M&A activity targets predictive analytics capabilities, while capacity expansion concentrates in India and Vietnam assembly corridors.
Within the full-stack ecosystem tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify platform control through captive silicon design and subscription service attachment. Garmin Ltd. occupies a position bridging consumer outdoor recreation and institutional athlete monitoring. Catapult Sports anchors the specialist analytics segment, representing pure-play team performance software vendors unbundling hardware procurement from platform licensing. These three archetypes illustrate competitive positioning across divergent margin pools: ecosystem lock-in, precision outdoor positioning, and elite team data services.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Fitbit (Google) |
| Apple Inc. |
| Polar Electro |
| Adidas AG |
| Samsung Electronics Co. Ltd. |
| Catapult Sports |
| Hawk-Eye Innovations (Sony Corporation) |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
IEC 62368-1 safety certification gates both supplier qualification timelines and price differentiation between audio-integrated wearables and standard fitness trackers, compressing margins for vendors unable to absorb 4-7 month testing delays while enabling premium positioning for certified incumbents serving collegiate athletic programs.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement consortia from individual athlete retail purchases, with NCAA Division I programs commanding 30-40% unit discounts on GPS-enabled wearables through multi-year analytics platform bundles. Three-tier pricing structure across premium, standard, and economy levels tracks sensor fusion depth rather than device category alone, with multi-modal biometric fusion sustaining pricing power. Cost compression in entry-tier fitness trackers is intensifying because smartphone IMU substitution reduces standalone device necessity among casual athletes. Fitness enthusiasts exhibit highest price sensitivity, while professional team procurement departments prioritize predictive analytics API access over per-unit hardware costs.
Supply Chain Analysis
TSMC and Samsung Foundry capacity in Taiwan and South Korea anchors GPS chipset fabrication for outdoor athlete tracking devices, creating single-source vulnerability for multi-constellation positioning modules. Raw material dependencies span precision MEMS accelerometers from Stuttgart-region fabricators, optical PPG modules from Kansai manufacturers, and Bluetooth SoC designs from fabless semiconductor houses. Tariff exposure runs through trans-Pacific distribution corridors terminating at the Port of Los Angeles-Long Beach complex. Distribution runs through direct-to-institution sales teams for elite team sports, consumer electronics retail for fitness enthusiasts, and procurement consortiums for collegiate athletic conferences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in sensor fusion convergence for military and first-responder training programs, as unbundled hardware-software procurement patterns across collegiate and professional sports create niche entry points for specialized analytics vendors.
For Market Incumbents: Compound ecosystem lock-in through captive silicon design and subscription service attachment, defending against smartphone IMU substitution by embedding predictive analytics directly into wearable firmware. Prioritize backward integration into optical PPG module production to secure multi-wavelength SpO2 capability without licensing IP from Kansai-region suppliers. Capacity addition in Tamil Nadu and Karnataka assembly corridors reduces landed costs for South Asian fitness applications.
For New Entrants and Emerging Players: Lead with NFC-integrated athlete access bands targeting German and French institutional facilities, where stadium credentialing and payment convergence creates bundled hardware-software service models with lower certification barriers than biometric wearables. Target India PLI scheme beneficiaries for contract manufacturing partnerships. Pursue direct-to-team sales bypassing established procurement consortiums in United States collegiate athletic conferences.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor fusion convergence segments, as multi-modal biometric integration demands combined R&D investment in accelerometer, PPG, and galvanic skin response streams. Long-term viability favors acquisition targets with real-time signal processing expertise for sub-50-millisecond latency protocols, given firmware engineering talent scarcity constraining vendor scaling. Watch ISO and IEC federated data standard finalization as inflection indicator for ecosystem lock-in intensity reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Multi-modal biometric integration enables military training program contracts beyond consumer fitness. |
| India PLI Scheme Manufacturing Entry | Tamil Nadu assembly corridors reduce landed costs for Bluetooth-enabled fitness tracker exports. |
| EU AI Act Compliance Infrastructure | Algorithmic audit trail capabilities secure Bundesliga and Premier League contract renewals. |
| NFC Access Band Bundling | German stadium credentialing convergence creates recurring service revenue from hardware endpoints. |
| Optical Module Backward Integration | In-house PPG production escapes licensing dependency on Osaka-based engineering specialists. |
Study Parameters
A spread of perspectives from wearable hardware engineering directors, collegiate athletic procurement officers, professional team performance analysts, and FCC regulatory consultants converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings of listed ecosystem vendors, FDA wellness device classification databases, and EU AI Act implementation guidance documents. Bottom-up shipment estimates by product category and top-down market sizing by end-user segment were triangulated against TSMC foundry allocation disclosures and NCAA athletic expenditure surveys.
Segmentation dimensions modeled include product type hierarchy, end-user procurement authority structure, wireless protocol selection, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical refresh cycle compression and forward projection of collegiate biometric monitoring budget expansion. Forecast inputs incorporated MEMS sensor sampling rate advancement curves and EU AI Act compliance investment trajectories across the analysis window.
Underlying assumptions cover sustained foundry capacity allocation for GPS chipsets and continued collegiate athletic program spending growth, with deviation risk concentrated in smartphone IMU substitution acceleration and ISO/IEC interoperability standardization delays. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and India PLI scheme uptake rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Global Power Adapter Market