
 Active Damping Smartphone Case Market | 2026-2036
Active Damping Smartphone Case Market Size, Share, and Industry Trends Forecast 2026-2036
Active Damping Smartphone Case Market Outlook
Military-grade drop certification is bifurcating the competitive landscape into premium performance tiers and mass-market alternatives. OtterBox leverages its heritage in ruggedized protection to sustain pricing power at the top tier. Spigen competes through manufacturing scale across polycarbonate and TPU hybrid configurations. Mous Products Ltd. differentiates via AiroShock material technology and precision-fit engineering.
An active damping smartphone case integrates shock-absorbing materials—typically TPU, polycarbonate, or silicone composites—with engineered air-gap structures or non-Newtonian fluid layers to dissipate impact energy and suppress resonant vibrations during device use. The primary commercial purpose centers on protecting fragile internal components such as camera stabilization modules and MEMS gyroscopes while maintaining slim industrial design profiles. Hybrid case configurations now lead volume shipments by combining rigid polycarbonate frames with soft TPU bumpers to optimize both structural integrity and damping coefficient. Shock absorption features command the widest margin pools as consumers prioritize drop-test performance over water resistance or cosmetic customization. Enterprise customer channels represent the fastest-growing structural segment as fleet procurement programs standardize on protective accessories for field-deployed devices.
FCC electromagnetic compatibility standards constrain material selection and internal damping layer composition for cases sold in the United States. The EU's REACH regulation and RoHS directive restrict phthalate plasticizers and heavy metal stabilizers in TPU formulations, compelling reformulation of soft-case chemistries across export-oriented supply chains. China's GB standards for electronic accessories mandate specific flammability ratings that shape polycarbonate resin sourcing decisions. Stakeholders must monitor evolving e-waste extended producer responsibility frameworks as these will increasingly govern end-of-life collection obligations and material recyclability specifications.
Market Dynamics
Professional photographers and mobile content creators are driving a bifurcation in demand toward vibration-free capture capabilities, forcing manufacturers to engineer precision-fit damping architectures that protect MEMS gyroscopes and optical image stabilization modules without compromising industrial design.
Growth Catalysts
- REACH-compliant TPU reformulation:The EU's REACH restrictions on phthalate plasticizers compel supply chains to adopt bio-based polymer alternatives, opening premium positioning for certified sustainable formulations.
- Enterprise fleet standardization:Field-deployed device procurement programs now mandate military-grade drop certification, creating institutional pull for shock-absorbing accessories across logistics and construction verticals.
- Samsung Galaxy ecosystem loyalty:South Korea's concentrated premium smartphone attachment rates generate disproportionate demand for precision-engineered damping cases calibrated to specific device dimensions.
Market Restraints
- Polycarbonate resin cost volatility:Fluctuations in petrochemical feedstocks compress margins for hybrid case configurations dependent on rigid frame materials.
- Guangdong supply concentration:Molding and assembly capacity clusters in China's Pearl River Delta create single-point vulnerability for export-oriented brands.
- FCC electromagnetic compatibility constraints:Material selection for internal damping layers faces restrictive testing protocols that extend product development cycles.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging e-waste collection obligations in the EU and select US states incentivize closed-loop recycling partnerships for TPU recovery.
- Non-Newtonian fluid integration:Convergence of shear-thickening materials with thin-film manufacturing enables next-generation impact dissipation without bulk.
- India's BIS certification pathway:Formal adoption of electronics accessory standards creates first-mover advantage for compliant suppliers in an underpenetrated market.
Industry Challenges
- MEMS calibration expertise scarcity:Engineering talent capable of optimizing damping coefficients for gyroscope protection remains concentrated among specialized component suppliers.
- Dual certification timeline compression:Simultaneous pursuit of military drop ratings and electromagnetic compatibility approval strains quality assurance bandwidth.
- Precision-fit IP fragmentation:Device-specific dimensional patents held by OEMs complicate third-party case engineering for flagship smartphone releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Damping Smartphone Case Market |
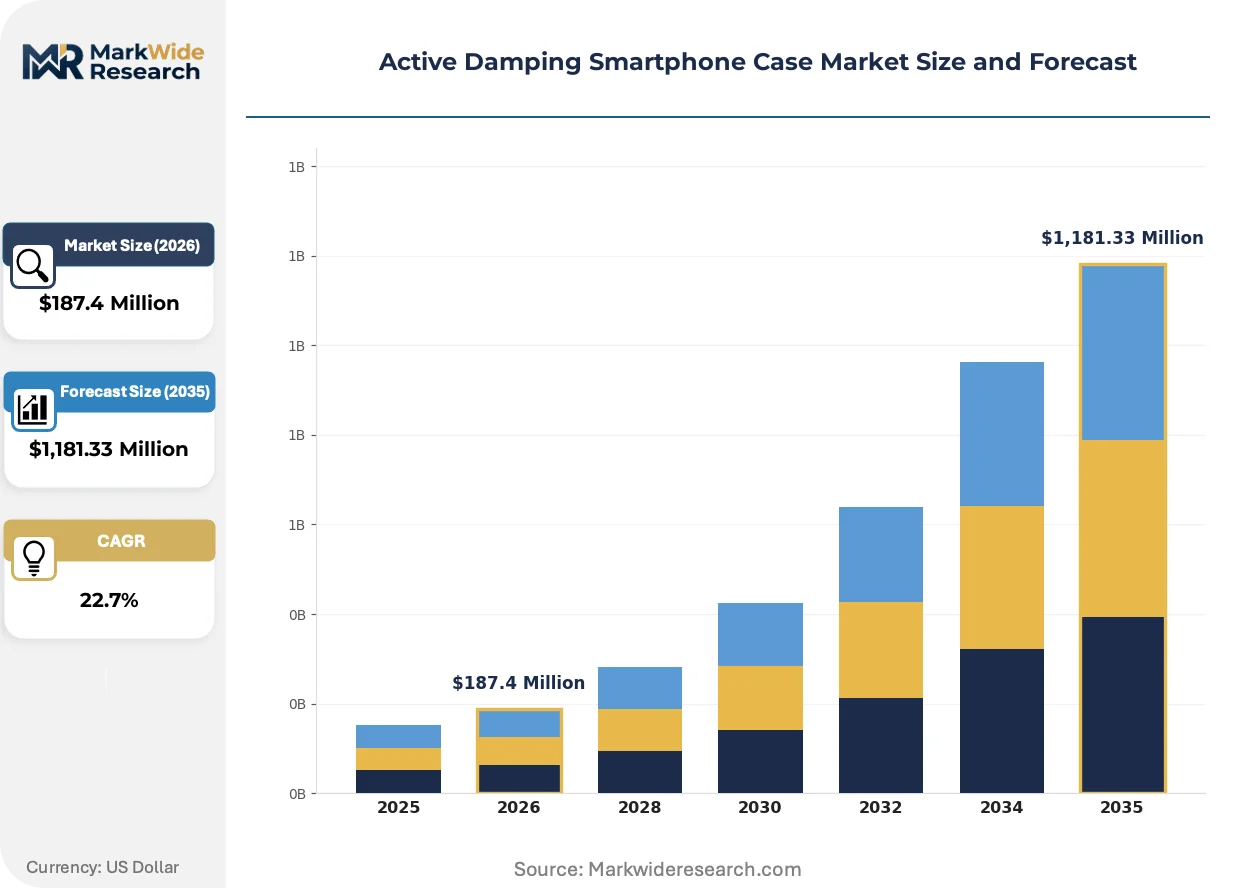
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Case, Soft Case, Hybrid Case, Wallet Case Material: TPU, Polycarbonate, Silicone, Metal Feature: Shock Absorption, Water Resistance, Custom Fit, Anti-Slip Customer Type: Consumers, Retailers, Distributors, Enterprises |
| Companies Covered | OtterBox, Spigen, Mous Products Ltd., Tech21, RhinoShield, i-BLADES, R-JUST, Belkin International, Incipio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Damping Smartphone Case Market Strategic Shifts
Material science advances and regulatory chemistry mandates are converging to reshape competitive differentiation, with sustainability credentials and precision-engineered damping architectures emerging as the primary axes of value creation.
Non-Newtonian fluid layers embedded within slim case profiles deliver superior impact dissipation compared to traditional air-gap structures. Mobile content creators adopting gimbal-free shooting workflows demand this performance tier for vibration-free footage. Silicone composite damping is supplanting conventional TPU bumpers in premium configurations as manufacturers optimize for both drop-test metrics and industrial design minimalism.
REACH and RoHS directives now explicitly restrict heavy metal stabilizers in soft-case chemistries exported to European markets. Reformulation costs fall disproportionately on mid-tier manufacturers lacking captive polymer development capabilities. Hybrid case producers sourcing from Taiwan and South Korea have accelerated bio-based TPU qualification programs to maintain market access.
Direct-to-creator distribution via specialized photography equipment retailers is eroding traditional electronics accessory channels. Mobile filmmakers and independent content producers now research damping specifications through vertical community platforms before purchase. This behavioral shift concentrates most visibly in South Korea and Japan, where influencer-led certification reviews drive rapid product lifecycle compression.
Active Damping Smartphone Case Market Segmentation
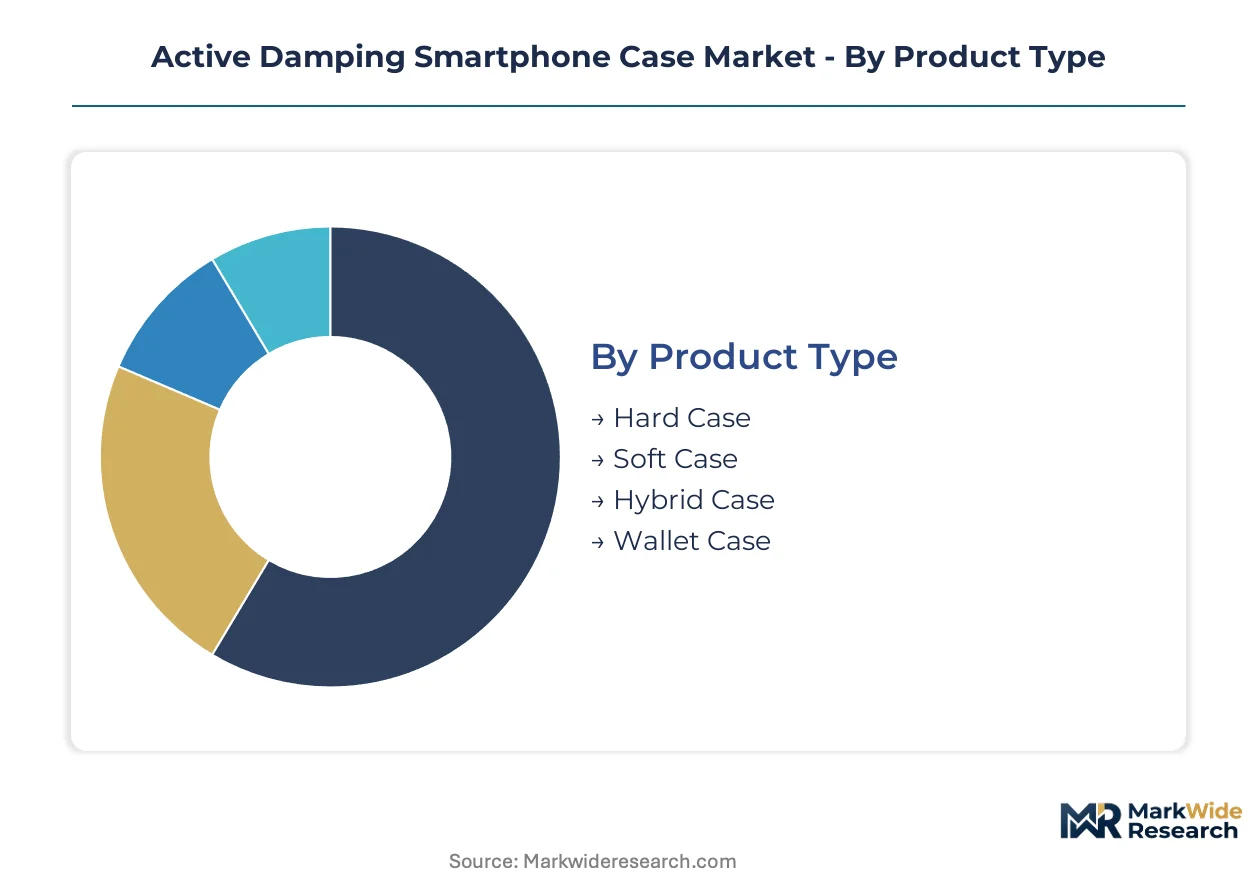
Segmentation in the active damping smartphone case market reveals how regulatory chemistry mandates and precision engineering requirements split demand across material grades and certification tiers. Manufacturers must align product architectures with distinct buyer risk profiles and compliance obligations.
Product Type:
REACH and RoHS material restrictions bifurcate case construction methods between compliant soft-layer formulations and rigid structural alternatives.
- Hybrid Case:Combines rigid polycarbonate frames with TPU bumpers to optimize structural integrity alongside damping coefficients. South Korean mobile content creators drive disproportionate demand for this configuration as vibration-free capture becomes essential for gimbal-free shooting workflows.
- Soft Case:Manufactured primarily from TPU or silicone composites with engineered air-gap structures to dissipate impact energy. EU REACH restrictions on phthalate plasticizers compel supply chain reformulation toward bio-based polymer alternatives for European market access.
- Hard Case:Polycarbonate-dominant construction emphasizing drop-test performance over damping flexibility. FCC electromagnetic compatibility standards constrain internal layer composition for US-bound shipments.
- Wallet Case:Multi-functional design integrating card storage with baseline protection. Enterprise fleet procurement programs rarely specify this form factor due to bulk constraints on field-deployed devices.
Established volume favors Hybrid Case; emerging adoption favors Soft Case as sustainability credentials reshape procurement criteria.
Material:
Cost tier differentiation separates premium bio-based formulations from commodity petrochemical derivatives.
- TPU:Thermoplastic polyurethane delivers optimal damping coefficients through Shore hardness tuning and air-gap integration. Professional photographers prioritize REACH-certified TPU variants for gyroscope protection in precision-fit configurations calibrated to flagship device dimensions.
- Polycarbonate:Rigid resin provides structural backbone for hybrid architectures but faces margin compression from petrochemical feedstock volatility. Guangdong-based molding clusters dominate global supply for this material category.
- Silicone:Silicone composite damping supplants conventional TPU in premium configurations as manufacturers optimize for drop-test metrics and industrial design minimalism simultaneously.
- Metal:Aluminum or magnesium alloy inserts add mass for specific impact distribution applications. FCC electromagnetic compatibility testing protocols extend development cycles for metal-inclusive designs.
Volume concentration sits with TPU; steepest expansion trajectory belongs to Silicone as content creator demand accelerates.
Feature:
Application-specific requirements concentrate margin pools around performance certifications rather than cosmetic differentiation.
- Shock Absorption:Engineered dissipation layers—air-gap structures or non-Newtonian fluid integration—protect MEMS gyroscopes and optical image stabilization modules. Military-grade drop certification commands the widest margin pools as enterprise fleet standardization mandates institutional procurement.
- Water Resistance:IP-rated sealing adds cost without addressing core damping functionality. Logistics and construction verticals occasionally specify this feature for extreme field conditions.
- Custom Fit:Precision engineering to specific device dimensions requires OEM dimensional data access. Device-specific patents held by smartphone manufacturers complicate third-party engineering for flagship releases.
- Anti-Slip:Surface texturing improves handling security without structural performance enhancement. Mass-market channels prioritize this cosmetic feature for price-sensitive segments.
Procurement weighting favors Shock Absorption; influencer-led review channels elevate Custom Fit visibility fastest.
Customer Type:
Supply concentration and margin structure vary sharply between direct-to-creator distribution and institutional procurement channels.
- Enterprises:Fleet procurement programs across logistics and construction verticals mandate military-grade drop certification, creating institutional pull for shock-absorbing accessories at volume pricing. Standardization decisions centralize with IT asset management functions.
- Consumers:Individual buyers research damping specifications through vertical community platforms before purchase, concentrating visibly in South Korea and Japan where influencer certification reviews compress product lifecycles.
- Retailers:Electronics accessory channels face erosion from specialized photography equipment retailers serving mobile filmmaker segments. Inventory turns favor SKUs with demonstrable drop-test credentials.
- Distributors:Wholesale intermediaries manage regional compliance certification burdens for export-oriented brands. India's BIS certification pathway creates first-mover advantage for compliant suppliers in underpenetrated markets.
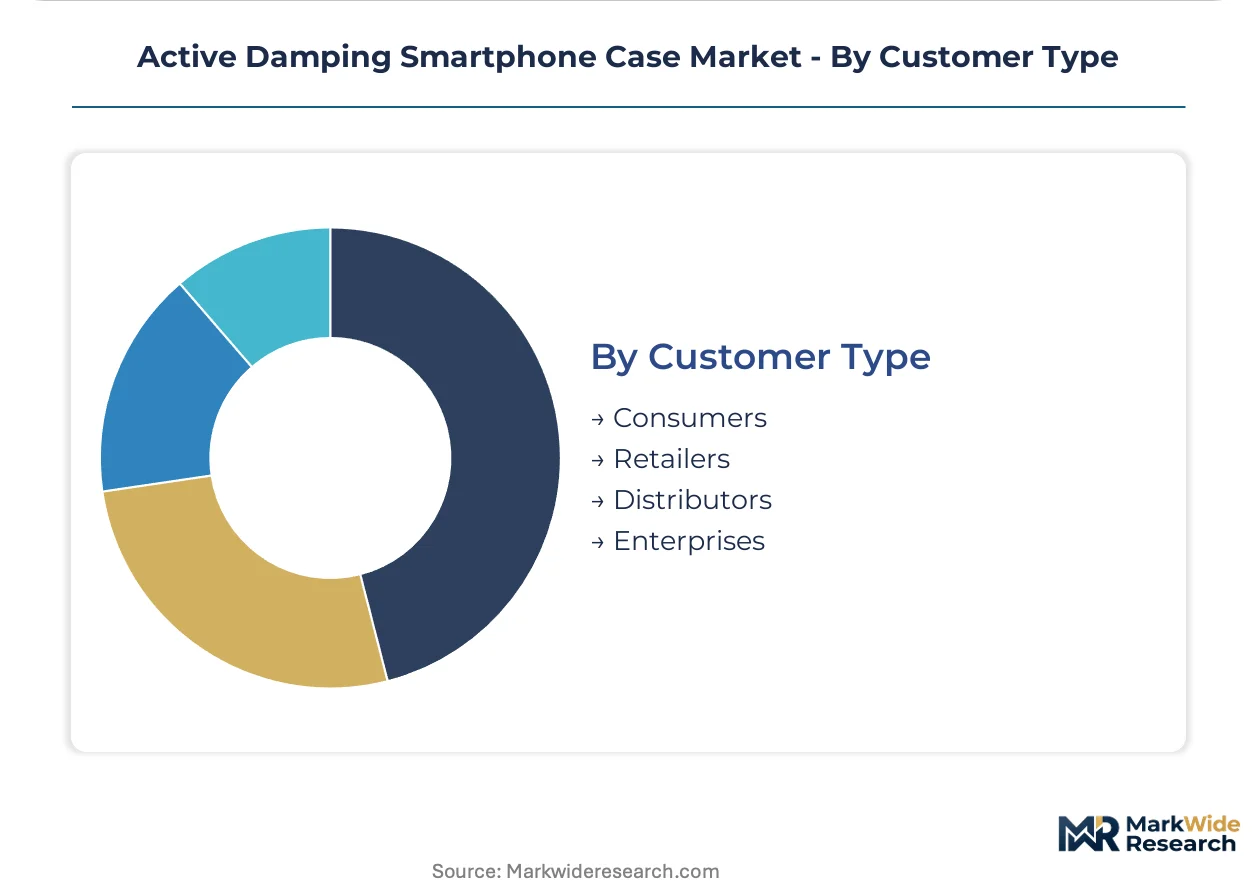
Revenue scale currently sits with Consumers; procurement velocity is climbing fastest among Enterprises as fleet standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers face divergent compliance burdens across destination markets. South Korea generates the strongest import demand for precision-engineered damping cases. China's Pearl River Delta dominates molding capacity for global supply.
South Korea
Samsung Galaxy ecosystem loyalty drives premium attachment rates for precision-fit accessories. MFDS consumer safety standards govern electronics accessory chemical composition. Seoul Capital Area hosts design studios calibrating damping coefficients for flagship device dimensions.
United States
Enterprise fleet procurement across logistics verticals mandates military-grade drop certification. FCC electromagnetic compatibility testing constrains internal damping layer material selection. California-based mobile content creators research vibration-free specifications through vertical community platforms.
China
GB standards for electronic accessories mandate specific flammability ratings shaping polycarbonate resin sourcing. Guangdong Province concentrates molding and assembly capacity for export-oriented brands. Shenzhen suppliers accelerate REACH-compliant TPU qualification programs for European market access.
Germany
Industrial photographer segments prioritize MEMS gyroscope protection for field-deployed measurement devices. ECHA REACH enforcement restricts phthalate plasticizers in soft-case formulations. Bavaria-based distributors manage EU extended producer responsibility compliance for TPU recovery programs.
India
BIS certification pathway for electronics accessories creates first-mover positioning in underpenetrated procurement channels. DGFT import regulations shape supply chain routing for premium case categories. Maharashtra industrial zones develop molding capacity for domestic-brand damping case production.
Active Damping Smartphone Case Market Competitive Environment
Concentration sits with heritage ruggedization specialists and precision-engineering boutiques. The competitive structure tiers across military-grade certification holders, manufacturing-scale hybrids, and material-science differentiators. Three archetypes dominate: legacy protection brands leveraging drop-test heritage, Asian fabricators optimizing polycarbonate-TPU cost curves, and damping-technology specialists commercializing non-Newtonian formulations. Strategic moves center on REACH-compliant chemistry partnerships and direct-to-creator distribution channel capture.
Within the heritage ruggedization tier, OtterBox occupies a position sustained by military-grade certification credibility. Among Asian-scale fabricators, Spigen exemplifies manufacturing breadth across hybrid material configurations. On the precision-engineering vector, Mous Products Ltd. represents material-science differentiation through proprietary damping architectures.
| Leading Market Players |
|---|
| OtterBox |
| Spigen |
| Mous Products Ltd. |
| Tech21 |
| RhinoShield |
| i-BLADES |
| R-JUST |
| Belkin International |
| Incipio |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day polycarbonate resin lead times from Guangdong suppliers tether pricing power to Pearl River Delta molding capacity, compressing margins for hybrid case configurations when petrochemical feedstock volatility spikes. REACH-compliant TPU reformulation costs and FCC electromagnetic compatibility testing cycles further stratify price positions across export-oriented supply chains.
Pricing Analysis
Enterprise fleet buyers anchor contract-based long-term offtake structures that secure volume pricing for military-grade drop-certified configurations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based TPU formulations from commodity petrochemical derivatives, with certification grade and volume scale as primary price differentiation drivers. Cost compression in mid-tier hybrid configurations is intensifying because polycarbonate resin cost volatility feeds directly into rigid frame material expenses. Individual mobile content creators in South Korea and Japan exhibit lowest price sensitivity, prioritizing vibration-free capture performance over unit economics.
Supply Chain Analysis
Inventory buffers at Shenzhen distributors typically cover thirty-to-forty-five days of TPU and polycarbonate resin requirements before replenishment from Guangdong molding clusters. Supply concentrates in China, South Korea, and Taiwan, with polycarbonate resin sourcing decisions shaped by GB standards flammability mandates and REACH-compliant TPU qualification programs. Raw material dependencies rest on petrochemical feedstocks, bio-based polymer alternatives, and non-Newtonian fluid formulations. Single-source vulnerability concentrates in Guangdong Province molding capacity for export-oriented brands. Distribution runs through wholesale intermediaries managing regional compliance certification burdens, direct-to-creator channels via specialized photography equipment retailers, and enterprise fleet procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as mobile content creator demand splits procurement channels away from traditional electronics accessory retail, creating niche positioning for precision-engineered damping specialists and REACH-certified chemistry boutiques.
For Market Incumbents: Consolidate manufacturing scale advantages through captive TPU formulation partnerships that lock in REACH-compliant chemistry access before mid-tier competitors complete bio-based polymer qualification. Defend margin position by deepening backward integration into polycarbonate resin sourcing from Taiwan and South Korea suppliers, insulating hybrid case production from Guangdong supply concentration risks. Channel control through direct-to-creator distribution partnerships with specialized photography equipment retailers represents the critical defensive lever against influencer-led review platform disruption. For New Entrants and Emerging Players: Direct-to-creator service-layer gaps in vibration-free capture calibration and MEMS gyroscope protection specification guidance expose incumbent blind spots. Target India's BIS certification pathway for electronics accessories as the most penetrable geography, where underdeveloped domestic molding capacity delays local-brand competitive response. Go-to-market angle centers on compliance-first positioning that accelerates market access ahead of established export-oriented brands navigating DGFT import regulation complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across REACH-compliant TPU formulation sub-segments as bio-based polymer scale economies mature. Long-term viability across the projection horizon favors acquisition targets with proprietary damping architectures—non-Newtonian fluid integration capabilities or precision-fit engineering IP—rather than pure manufacturing-scale fabricators. Signal to monitor: enterprise fleet procurement program standardization rates across logistics and construction verticals, which indicate institutional demand inflection for military-grade certified accessories.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Partnership | Secures European market access for TPU formulations under ECHA enforcement timelines. |
| Direct-to-Creator Channel Capture | Bypasses eroding electronics accessory retail through specialized photography equipment partnerships. |
| Non-Newtonian Fluid Integration | Enables next-generation impact dissipation without bulk for gimbal-free mobile filmmakers. |
| Enterprise Fleet Certification | Locks in institutional procurement volume through military-grade drop-test standardization. |
| India BIS Certification First-Mover | Establishes compliant positioning in underpenetrated procurement channels ahead of domestic competition. |
Study Parameters
Cross-validation between primary interviews with supply chain managers at Guangdong molding facilities and secondary analysis of MFDS consumer safety standards filings anchors the qualitative findings. The research combines direct conversations with TPU formulation chemists, enterprise IT asset management directors, mobile content creator equipment reviewers, and REACH compliance consultants with validation against FCC electromagnetic compatibility testing protocols, ECHA substance restriction databases, and BIS electronics accessory certification records. Bottom-up shipment estimates from polycarbonate and TPU resin consumption patterns triangulate against top-down value projections across the analysis window.
Sensitivity analysis around petrochemical feedstock cost assumptions and REACH enforcement timing variations stress-tests projection robustness. The analytical framework segments volume and value outputs by product type (hybrid, soft, hard, wallet), material grade (TPU, polycarbonate, silicone, metal), feature tier (shock absorption, water resistance, custom fit, anti-slip), and customer archetype (enterprise fleet, individual consumer, retailer, distributor) across the modeling period. CAGRs derive from regression analysis of historical attachment rate trends calibrated to Samsung Galaxy ecosystem loyalty metrics and mobile content creator equipment upgrade cycles.
Material uncertainties—regulatory enforcement acceleration in EU extended producer responsibility frameworks, polycarbonate resin supply disruptions from Pearl River Delta logistics constraints, and MEMS calibration expertise scarcity limiting precision-fit engineering capacity—sit outside the modeled envelope. Forecasts reflect documented assumptions about enterprise fleet standardization adoption curves and bio-based TPU cost reduction trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Global Power Adapter Market