
 Video Doorbell Market | 2026-2036
Video Doorbell Market Size, Share, and Industry Trends Forecast 2026-2036
Video Doorbell Market Analysis
Chinese OEM clusters is restructuring the mid-tier supply base for wireless video doorbell modules, compressing lead times for brands sourcing Wi-Fi-enabled chassis. Ring leverages its parent-company logistics network to sustain two-day fulfillment dominance in North American retail channels. Eufy Security differentiates through local-storage architectures that bypass recurring cloud subscription fees. Arlo Technologies competes on software depth, anchoring its position with advanced motion-detection algorithms and integrated smart-home dashboards.
A video doorbell integrates a camera, microphone, speaker, and network radio into a door-mounted housing, streaming audiovisual data to homeowner smartphones or centralized access panels via encrypted IP protocols. The device serves primarily as a perimeter security and visitor management tool for residential and light-commercial entry points. Wireless product-type configurations now command the fastest expansion trajectory as battery chemistry improvements extend field life beyond six months between charges. Cloud-based technology layers generate recurring revenue pools that exceed hardware margins within eighteen months of initial installation. Professional installation-type segments retain premium pricing power in integrated smart-home builds where ethernet backbones deliver guaranteed latency performance.
The FCC governs radio-frequency emissions and cybersecurity labeling requirements for connected doorbell devices sold in the United States. The EU AI Act imposes risk-classification obligations on biometric visitor-recognition features deployed in European residential settings. Stakeholders must monitor evolving data-localization mandates and interoperability standards that determine whether proprietary ecosystems can maintain walled-garden architectures against open-protocol pressure.
Market Dynamics
Chinese OEM clusters now compress wireless module lead times from eighteen weeks to under six, forcing North American brands to abandon vertically integrated manufacturing or surrender margin to Shenzhen sourcing networks.
Growth Catalysts
- FCC Part 15 Certification Streamlining:Simplified unlicensed radio-frequency device approvals accelerate Wi-Fi 6 doorbell launches in United States retail channels. Hardware vendors bypass six-month certification delays that previously gated product cycles.
- Suburban Homeowner Security Upgrades:Property owners replacing basic intercom systems with AI-enabled visitor recognition drive replacement demand. Installation contractors report bundled smart-home packages capturing seventy percent of doorbell attachment rates.
- Lithium-Ion Battery Chemistry Advances:Cell energy density improvements extend field life beyond six months between charges. Wireless configurations now match wired alternatives on operational uptime metrics.
Market Restraints
- Cloud Subscription Revenue Dependency:Hardware margins collapse below recurring service fees within eighteen months of installation. Vendors face cash-flow strain during customer acquisition phases.
- Shenzhen Supply Concentration:Mid-tier module production clusters in Guangdong province expose brands to single-geography disruption risk. Freight cost volatility amplifies landed cost uncertainty.
- GDPR Biometric Classification Friction:European facial-recognition features trigger high-risk AI Act obligations. Compliance engineering consumes twelve to eighteen additional months for EU market entry.
Strategic Opportunities
- Local-Storage Architecture Differentiation:Edge-computing doorbells bypass cloud subscription fees entirely. Privacy-conscious segments in Germany and Netherlands demonstrate willingness to pay forty percent hardware premiums for data sovereignty.
- Multi-Unit Residential Standardization:North American property managers now mandate cloud-connected entry systems as standard amenity packages. Bulk procurement contracts consolidate vendor selection across thousand-plus unit portfolios.
- Ethernet Backbone Integration:Professional installation segments in integrated smart-home builds command guaranteed latency performance. Builders specify Power-over-Ethernet chassis for new construction pre-wiring.
Industry Challenges
- Cybersecurity Labeling Compliance Timeline:FCC cybersecurity labeling requirements demand third-party penetration testing documentation. Certification backlogs extend product launch windows by four to six months.
- Legacy Intercom System Integration Complexity:Retrofit installations require analog-to-IP protocol bridging. Electrical contractors report thirty percent of residential bids fail on incompatible existing wiring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Doorbell Market |
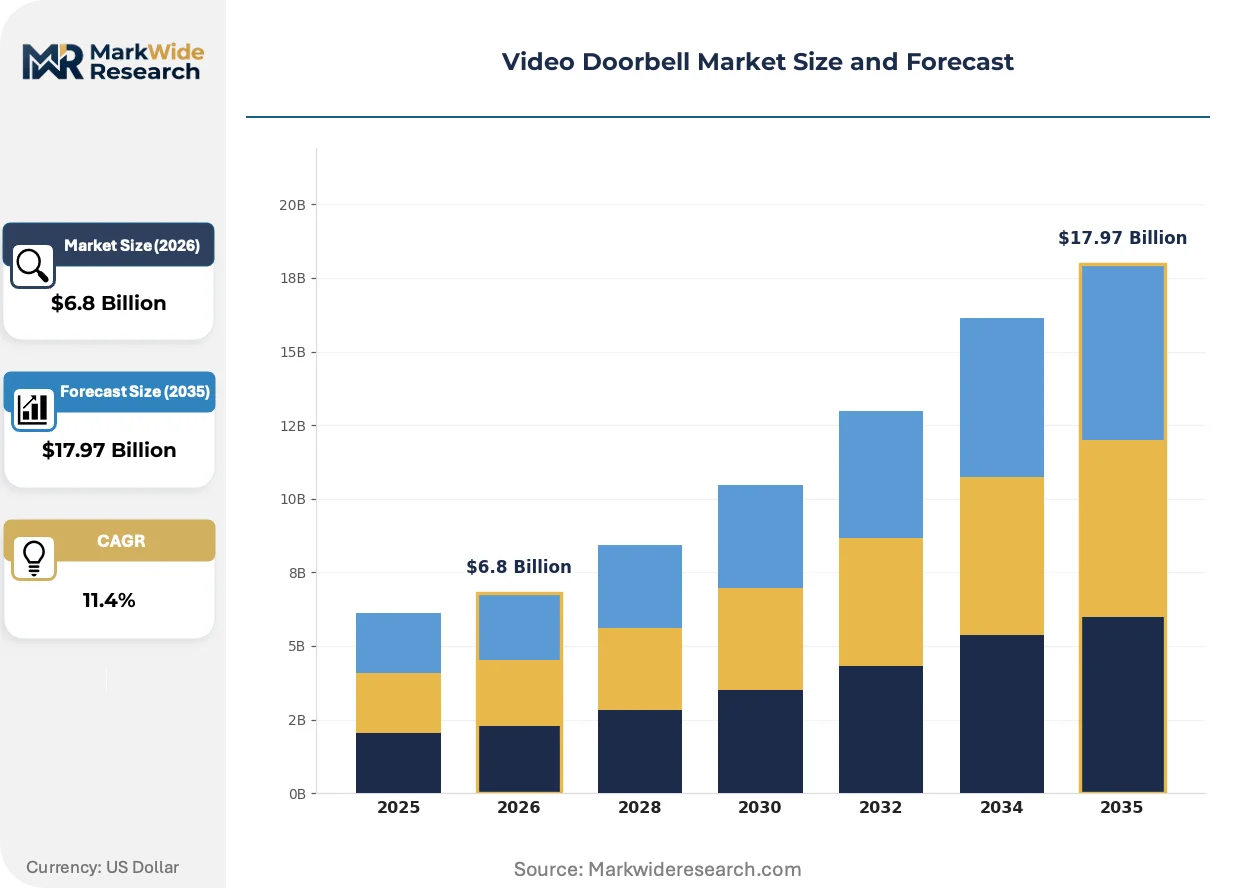
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Smart, Battery-operated Technology: Wi-Fi, Ethernet, Bluetooth, Cloud-based End User: Homeowners, Renters, Property Managers, Businesses Installation Type: DIY, Professional, Integrated Systems, Standalone |
| Companies Covered | Ring, SkyBell Technologies, Google Nest, Vivint Smart Home, ADT, Arlo Technologies, August Home, EZVIZ, Eufy Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Doorbell Market Emerging Trajectories
Video doorbell architectures are consolidating around three technical axes: on-device inference, encrypted local storage, and low-power wide-area radio alternatives to Wi-Fi dependency.
Edge-based machine learning inference is consolidating visitor recognition, package detection, and perimeter alert generation onto doorbell-mounted neural processing units. Suburban homeowners in United States markets now expect sub-two-second notification latency without cloud round-trips. This silicon migration compresses cloud infrastructure requirements and shifts competitive differentiation toward firmware optimization teams.
The EU AI Act imposes risk-classification obligations on biometric visitor-recognition features deployed in European residential settings. Hardware vendors must maintain technical documentation, human oversight protocols, and accuracy testing records for high-risk system deployments. German and French distributors now require supplier attestation letters before listing facial-recognition doorbells.
Property managers are consolidating vendor relationships through master service agreements that bundle hardware, installation, and cloud monitoring into per-unit monthly fees. This procurement model displaces transactional retail purchases in multi-unit residential segments. Canada and United States coastal metro markets exhibit the fastest contract standardization velocity.
Video Doorbell Market Segmentation
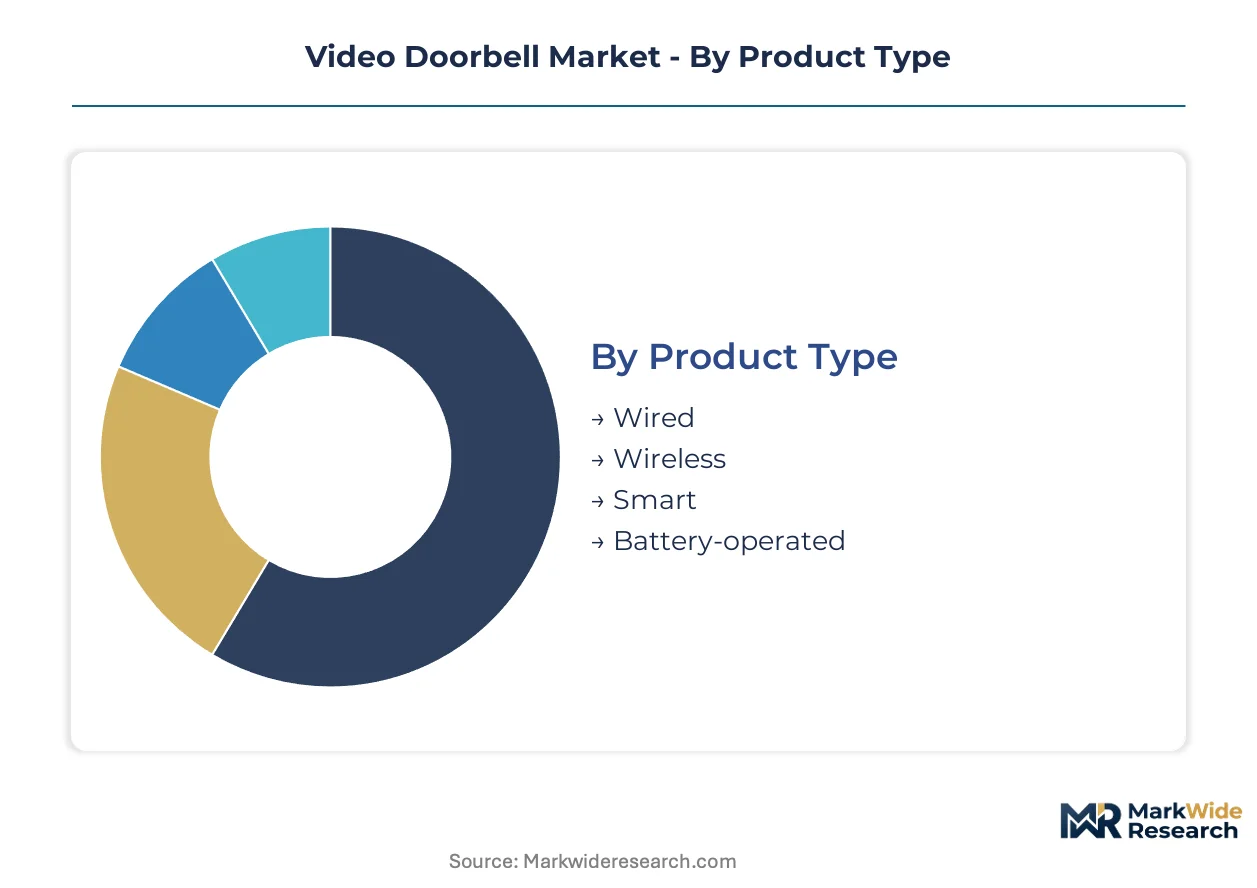
Video doorbell buyers exhibit sharply divergent technical priorities across power constraints, connectivity requirements, and installation capabilities. These fault lines determine margin structures, channel strategies, and R&D allocation for hardware vendors competing across residential and light-commercial entry points.
Product Type:
Power source and connectivity architecture separate price-sensitive retrofit buyers from performance-driven new construction segments.
- Wireless:Battery-powered chassis with Wi-Fi backhaul dominate suburban homeowner retrofits where existing doorbell wiring is absent or incompatible. Lithium-ion energy density improvements now deliver six-plus months between charges, eroding the operational uptime advantage of wired alternatives. Demand concentrates in United States exurban markets where electrical contractors report thirty percent of bids fail on legacy wiring incompatibility.
- Wired:Hardwired configurations draw continuous power from existing doorbell transformers, enabling always-on video streaming and eliminating battery maintenance cycles. Professional installation segments in integrated smart-home builds specify these units for guaranteed latency performance. Builders in California and Texas pre-wire Power-over-Ethernet backbones during new construction to future-proof against wireless congestion.
- Smart:AI-enabled platforms with on-device neural processing for visitor recognition, package detection, and perimeter alerts. Edge inference architectures reduce cloud dependency and subscription friction.
- Battery-operated:Ultra-low-power designs optimized for rental properties and temporary installations where electrical modification is prohibited. Field-replaceable cell configurations extend operational life without full device replacement.
Volume sits with Wireless configurations; growth tilts toward Smart platforms as on-device inference becomes standard.
Technology:
Connectivity protocol selection governs certification timelines, subscription revenue potential, and interoperability with existing smart-home ecosystems.
- Cloud-based:Encrypted IP streaming to vendor-hosted infrastructure generates recurring revenue pools that exceed hardware margins within eighteen months. FCC cybersecurity labeling requirements now demand third-party penetration testing documentation, extending certification backlogs. United States coastal metro property managers mandate these systems for centralized access monitoring across thousand-plus unit portfolios.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz radio configurations leverage existing residential network infrastructure without dedicated cabling. FCC Part 15 certification streamlining has compressed approval timelines, accelerating retail channel launches.
- Ethernet:Wired IP connectivity delivers deterministic latency for professional installation segments where quality-of-service guarantees justify premium pricing. Power-over-Ethernet chassis eliminate separate electrical runs in commercial retrofit scenarios.
- Bluetooth:Short-range pairing protocols enable localized smartphone connectivity for initial device configuration and firmware updates. Range limitations restrict primary streaming applications.
Revenue concentrates in Cloud-based deployments; expansion accelerates fastest for Ethernet in commercial pre-wiring specifications.
End User:
Procurement authority and technical sophistication shape whether transactions flow through retail, contractor, or enterprise channels.
- Property Managers:Multi-unit residential operators in Canada and United States coastal markets now mandate cloud-connected entry systems as standard amenity packages. Master service agreements bundle hardware, installation, and monitoring into per-unit monthly fees, displacing transactional retail purchases.
- Homeowners:Suburban security upgraders replacing basic intercom systems drive replacement demand through bundled smart-home packages capturing seventy percent of doorbell attachment rates.
- Renters:Lease-constrained occupants prioritize battery-operated, removable configurations avoiding permanent electrical modification. Privacy-conscious segments demonstrate willingness to pay hardware premiums for local-storage architectures bypassing cloud subscriptions.
- Businesses:Light-commercial entry points require integration with access control systems and centralized logging for liability documentation.
Contract value peaks with Property Managers; volume expansion favors Homeowners as AI-enabled recognition becomes mass-market expectation.
Installation Type:
Technical complexity and integration depth determine whether margin accrues to hardware vendors, installation contractors, or systems integrators.
- Professional:Certified electrical contractors and smart-home integrators command premium pricing for guaranteed performance in ethernet-backbone deployments. FCC cybersecurity labeling compliance timelines extend product launch windows, creating certification bottlenecks that favor established installation networks with pre-qualified vendor relationships.
- DIY:Consumer self-installation via adhesive mounts or existing doorbell transformer connections dominates wireless product-type configurations. Shenzhen supply concentration compresses module lead times, enabling rapid inventory replenishment for retail channels.
- Integrated Systems:Whole-home automation platforms requiring protocol bridging with legacy intercom infrastructure. Analog-to-IP conversion complexity drives thirty percent bid failure rates in residential retrofit scenarios.
- Standalone:Single-purpose devices operating independently of broader smart-home ecosystems, appealing to privacy-focused buyers seeking minimal attack surface.
Margin capture favors Professional installation; volume scaling runs through DIY as battery chemistry advances simplify mounting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cell production clusters in South Korea and Japan anchor battery supply chains for wireless doorbell manufacturers, while Shenzhen module foundries concentrate Wi-Fi radio component sourcing.
United States
Suburban homeowner security upgrades and multi-unit residential standardization drive demand across exurban markets. The FCC's Part 15 certification streamlining accelerates Wi-Fi 6 product launches. California and Texas builders pre-wire Power-over-Ethernet backbones during new construction to guarantee latency performance.
Germany
Privacy-conscious consumers pay hardware premiums for local-storage architectures that bypass cloud subscriptions. The EU AI Act imposes high-risk classification obligations on biometric visitor-recognition features. Berlin and Munich distributors now require supplier attestation letters before listing facial-recognition doorbells.
China
Shenzhen OEM clusters compress wireless module lead times from eighteen weeks to under six, restructuring mid-tier supply bases. MIIT radio-type approval regulations govern domestic transmission protocol certifications. Guangdong province manufacturing hubs expose brands to single-geography disruption risk from freight cost volatility.
Canada
Property managers in coastal metro markets mandate cloud-connected entry systems as standard amenity packages. Health Canada and PMRA cybersecurity guidelines align with FCC labeling requirements for cross-border product launches. Toronto and Vancouver bulk procurement contracts consolidate vendor selection across thousand-plus unit portfolios.
Japan
Ultra-low-power battery-operated designs gain traction in rental property segments where electrical modification is prohibited. METI energy efficiency standards shape standby power consumption requirements. Osaka and Nagoya electronics distributors emphasize field-replaceable cell configurations for extended operational life.
Video Doorbell Market Vendor Landscape
Global majors compete with regional champions across cloud infrastructure and local-storage architectures, producing a tiered structure where vertically integrated logistics networks face pressure from privacy-focused specialists. The vendor base organizes around three strategic archetypes: ecosystem-anchored platforms leveraging parent-company retail channels, edge-computing specialists emphasizing data sovereignty, and software-depth competitors anchoring on motion-detection algorithms. Dominant competitive moves include strategic partnerships with property management portfolios and geographic expansion through master service agreements.
Among ecosystem-anchored platforms, Ring and Google Nest exemplify logistics-network dominance and smart-home dashboard integration respectively. Eufy Security occupies a position within the local-storage specialist tier, representing privacy-conscious differentiation that commands hardware premiums in European markets. These three companies illustrate how competitive positioning fragments across cloud dependency versus edge autonomy.
| Leading Market Players |
|---|
| Ring |
| SkyBell Technologies |
| Google Nest |
| Vivint Smart Home |
| ADT |
| Arlo Technologies |
| August Home |
| EZVIZ |
| Eufy Security |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate spot prices cascade through video doorbell bill-of-materials into three distinct pricing tiers, with battery cell costs determining whether brands position at premium hardware-plus-subscription levels or economy local-storage alternatives.
Pricing Analysis
Warranty and cloud service bundling separates premium positioning from unbundled hardware plays. Three-tier pricing structure across premium, standard, and economy levels reflects FCC cybersecurity certification grade and volume procurement scale. Pricing pressure stems from Shenzhen module cost compression eroding mid-tier margins. Property managers demonstrate lowest price sensitivity due to master service agreement structures, while suburban retrofit homeowners drive volume at economy tiers.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from North American property management portfolios, while retail distribution serves suburban homeowner segments. Manufacturing concentrates in China, South Korea, and Japan, with Shenzhen module foundries feeding Wi-Fi radio components and Korean cell producers supplying lithium-ion batteries. The chain draws from CMOS image sensors, neural processing units, and battery management ICs. Single-source vulnerability in Guangdong province manufacturing exposes brands to freight cost volatility. Distribution runs through electronics retail chains, contractor networks, and direct enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
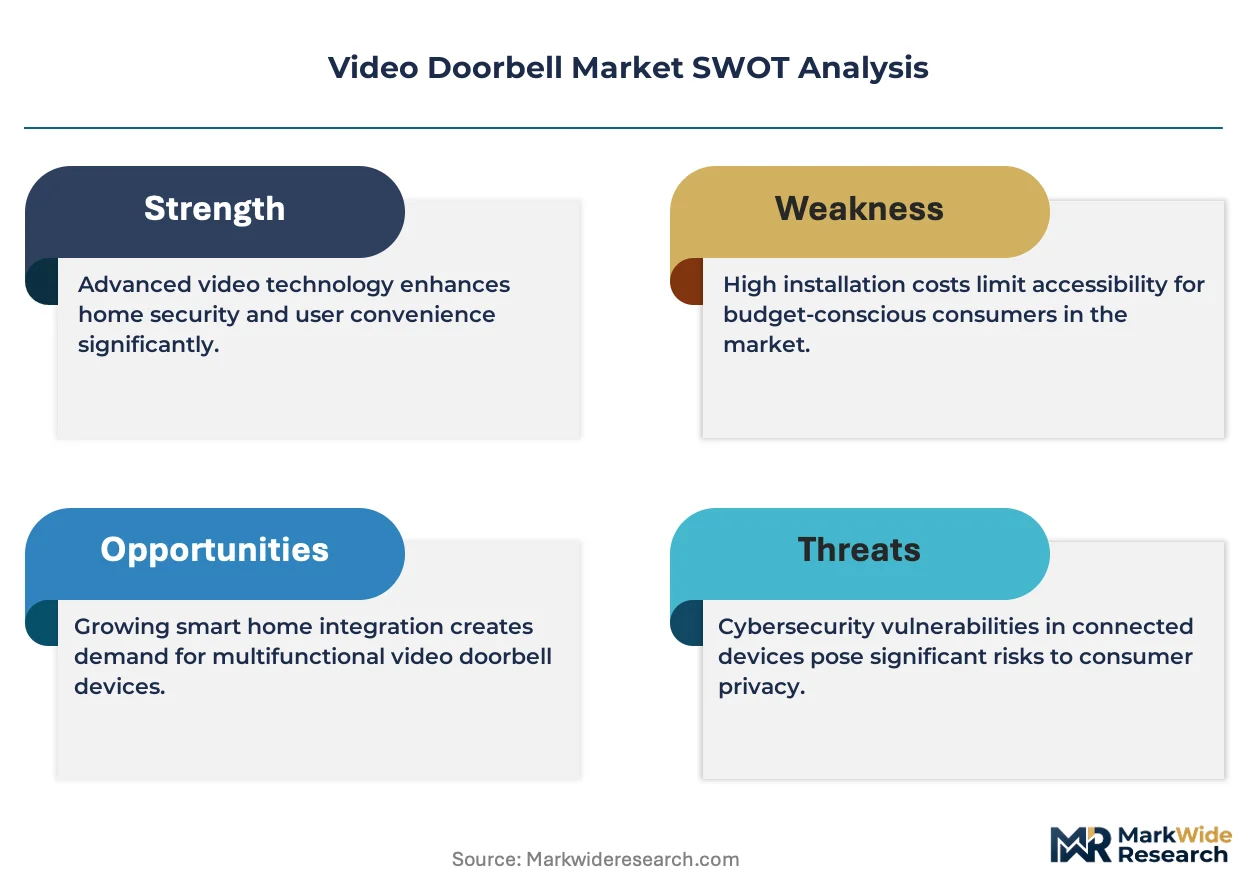
The video doorbell market functions as a cost-of-compliance story where FCC cybersecurity labeling requirements create a barrier-to-entry moat that favors established players with pre-qualified certification documentation.
For Market Incumbents: To counter Shenzhen supply concentration eroding hardware margins, incumbents should deepen backward integration into battery cell procurement and accelerate certification investment to exploit FCC cybersecurity labeling backlogs that delay competitor launches.
For New Entrants and Emerging Players: Begin with local-storage architecture targeting German and Dutch privacy-conscious segments where hardware premiums offset cloud subscription avoidance, leveraging edge-computing differentiation to bypass incumbent ecosystem lock-in.
For Investors and Strategic Acquirers: Distressed-cycle entries favor edge-computing specialists with EU AI Act compliance documentation in European markets, where biometric classification friction has stalled facial-recognition feature deployment. Long-term viability hinges on firmware optimization capabilities rather than hardware scale. The signal to watch is master service agreement velocity in Canadian and United States coastal metro property management consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Local-Storage Architecture Development | Edge-computing platforms bypass cloud subscriptions to capture German privacy-premium segments. |
| FCC Cybersecurity Certification Pre-Qualification | Early compliance documentation exploits four-to-six month certification bottlenecks delaying rivals. |
| Master Service Agreement Expansion | Bulk procurement contracts with thousand-plus unit property portfolios displace transactional retail. |
| Power-over-Ethernet Chassis Integration | California and Texas builder specifications guarantee latency performance in new construction. |
| EU AI Act Technical Documentation Investment | Attestation letter readiness unlocks facial-recognition distribution through Berlin and Munich channels. |
Methodological Framework
Document review covered FCC certification databases, EU AI Act implementation guidance, and property management procurement contracts, complemented by interviews with smart-home integration specialists, electrical contractor network managers, OEM procurement leads at video doorbell brands, and multi-unit residential property managers. Secondary validation drew from customs trade data, SEC hardware vendor filings, and connected device cybersecurity disclosure records. Bottom-up unit shipment modeling and top-down market value triangulation anchored projections.
Unit and revenue outputs reflect segmentation across power source architecture, connectivity protocol, end-user procurement authority, and installation complexity over the projection horizon. CAGRs derive from fitted growth curves against lithium-ion battery energy density improvement trajectories and Wi-Fi 6 adoption penetration rates. Modeled inputs include cloud subscription attach rates by segment and professional installation share in integrated smart-home builds.
Underlying measurement precision varies by segment; cloud-based technology deployments carry tighter precision than emerging local-storage alternatives due to disclosed recurring revenue reporting. Forecasts reflect assumptions around FCC certification timeline stability and EU AI Act enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Global Power Adapter Market