
 Electronic Insect Killer Market | 2026-2036
Electronic Insect Killer Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Insect Killer Market Analysis
Commercial hospitality buyers is rotating toward professional-grade zapper trap installations as residential consumers trim discretionary outdoor spending. Dynatrap leverages its North American distribution network to anchor premium positioning in resort and restaurant channels. Foshan GreenYellow Electric Technology Co. Ltd. dominates manufacturing scale for UV light trap exports across Asia-Pacific markets. Rentokil-PCI Pvt. Ltd. competes through integrated pest management contracts that bundle electronic units with service protocols.
Electronic insect killers are electromechanical devices that attract flying arthropods using ultraviolet emission at wavelengths between 365 and 385 nanometers, then eliminate them via high-voltage grid electrocution or adhesive capture surfaces. These systems serve commercial kitchens, agricultural processing facilities, and residential patios by reducing vector populations without residual chemical application. UV light trap configurations command the deepest margin pools due to recurring consumable sales of replacement bulbs and glue boards, while solar-powered killer units represent the fastest-expanding technology segment as off-grid installation demand rises in rural agricultural zones. Electromagnetic technology remains a niche category with limited hardware differentiation, constraining manufacturer pricing power.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act shape product compliance pathways for devices incorporating chemical attractants, while FCC oversight governs electromagnetic emission thresholds for ionizing technology variants. CE marking and EU RoHS substance restrictions dictate material composition standards for manufacturers exporting into European commercial channels. Stakeholders must monitor evolving state-level restrictions on neonictinoid-based attractant synergists, as regulatory shifts could force reformulation of hybrid chemical-electronic systems already deployed in agricultural settings.
Market Dynamics
Commercial hospitality procurement is rotating toward professional-grade UV trap installations as EPA pesticide restrictions accelerate substitution away from residual chemical applications. This structural shift compresses replacement cycles and elevates compliance-driven specification requirements across food service and lodging verticals.
Growth Catalysts
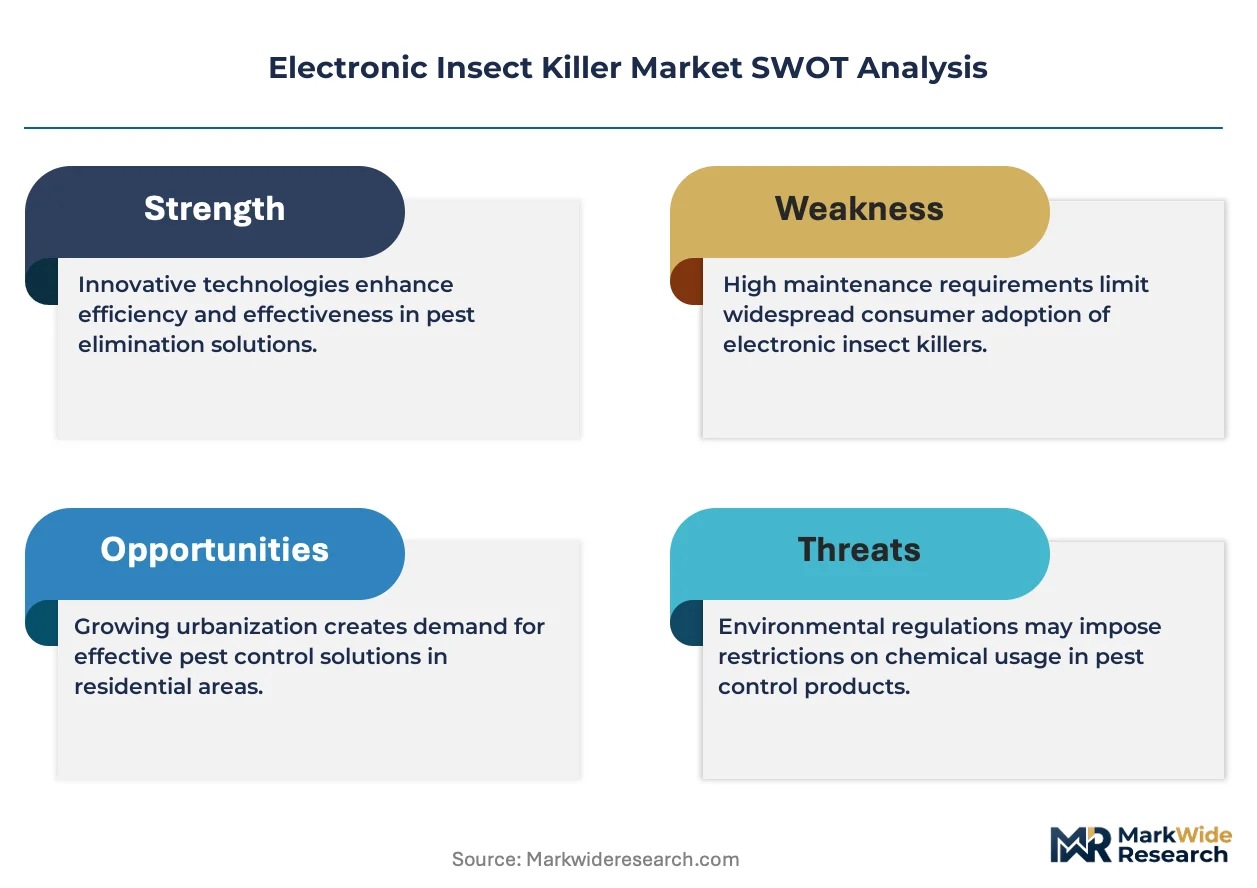
- EPA FIFRA Registration Pathways:Federal pesticide regulations under the Federal Insecticide, Fungicide, and Rodenticide Act are accelerating hospitality sector migration toward electrocution-based vector control systems that bypass chemical attractant compliance burdens.
- UV LED Diode Efficiency Gains:Solid-state ultraviolet emitters at 365-385 nanometer wavelengths are reducing bulb replacement frequency and energy draw, expanding total cost-of-ownership advantages against legacy fluorescent tube configurations.
- Southeast Asia Urban Density:Tropical climates in Indonesia, Thailand, and Vietnam sustain year-round mosquito breeding cycles that compress hardware replacement intervals and drive recurring consumable demand for glue boards and UV lamps.
Market Restraints
- High-Voltage Grid Component Concentration:Transformer and capacitor sourcing for electrocution grids concentrates among East Asian contract manufacturers, exposing lead times to regional logistics volatility.
- Electromagnetic Technology Margins:Ionizing variants lack hardware differentiation against UV trap alternatives, constraining manufacturer pricing power and compressing segment profitability.
- Neonicotinoid Attractant Restrictions:State-level prohibitions on synergist chemicals in hybrid chemical-electronic systems are forcing agricultural segment reformulation and shortening product lifecycle viability.
Strategic Opportunities
- India Rural Electrification Gaps:Off-grid agricultural zones present unmet demand for solar-powered killer units with photovoltaic-integrated battery storage and dusk-to-dawn activation sensors.
- EU RoHS Material Compliance:Substance restriction mandates under EU RoHS directives are creating specification advantages for manufacturers with certified lead-free solder and halogen-free housing portfolios in European commercial channels.
- IoT Sensor Convergence:Integration of electrocution counters and environmental monitoring modules enables predictive maintenance contracts and remote trap performance verification for integrated pest management providers.
Industry Challenges
- UV Spectral Calibration Expertise:Shortage of photometric testing technicians capable of validating 365-385 nanometer output consistency is extending product certification timelines for new market entrants.
- Legacy Electromechanical Integration:Retrofitting adhesive capture surfaces into existing high-voltage grid housings requires mechanical redesign to maintain IP ratings and safety certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Insect Killer Market |
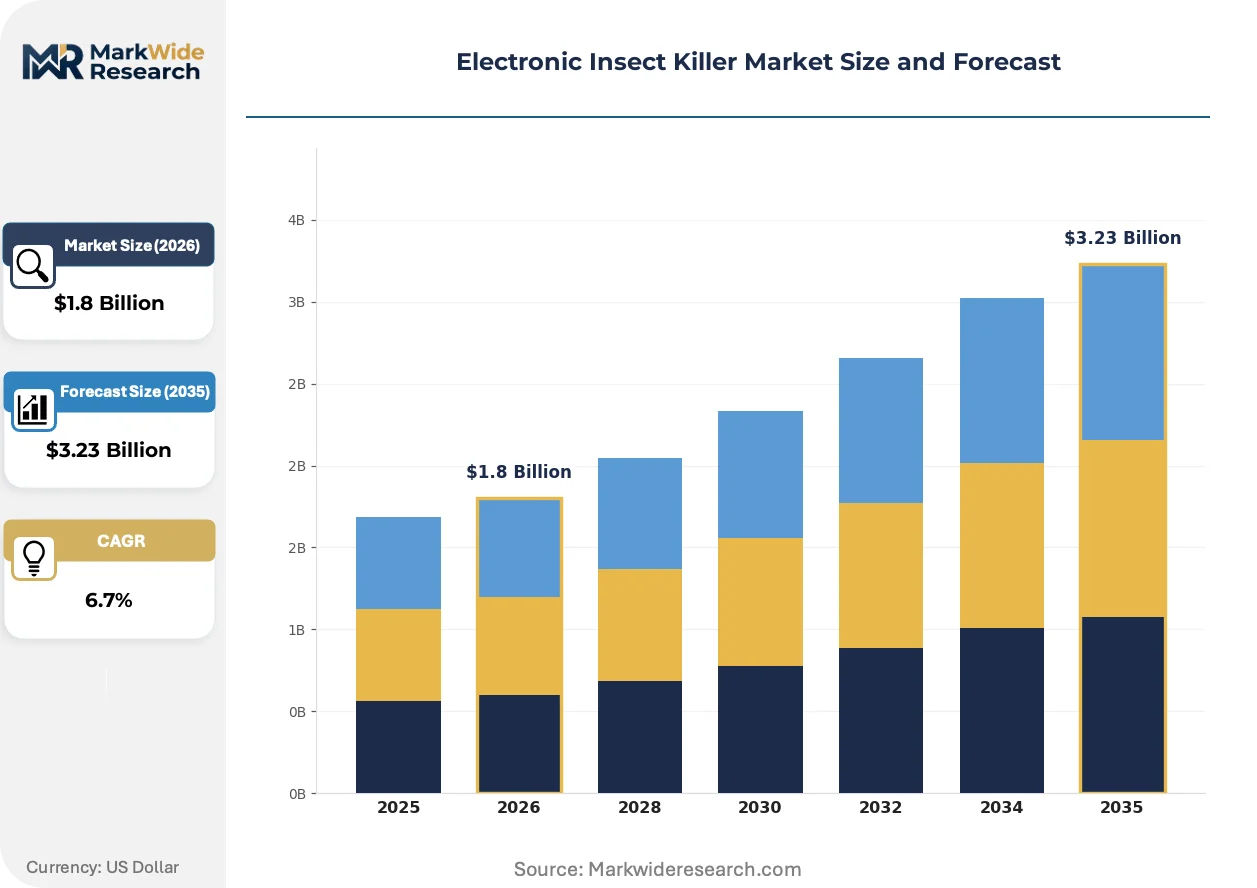
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Swatter, Zapper Trap, UV Light Trap, Solar-Powered Killer Technology: Ultraviolet, Electromagnetic, Ionizing, Chemical Repellents End User: Residential, Commercial, Agricultural, Industrial Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Armatron Co., Livin Well, Aspectek, Rentokil-PCI Pvt. Ltd., Pelsis Ltd., Koolatron, FUTURA DIRECT LTD, Dynatrap, Foshan GreenYellow Electric Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Insect Killer Market Emerging Trajectories
Product architectures are compressing physical footprints while expanding connectivity layers, shifting competitive differentiation from raw catch volume toward data-enabled service integration and predictive maintenance capabilities.
Photocatalytic oxidation chambers paired with UV-A excitation are miniaturizing into countertop and under-counter configurations for commercial kitchen deployment. Fast-casual restaurant chains in the United States are specifying these compact units to satisfy health inspector documentation requirements without sacrificing floor space. The form factor reduction is miniaturizing addressable installation locations and fragmenting procurement decisions from centralized facilities management to individual franchise operators.
CE marking enforcement under EU RoHS substance restrictions is compelling Asian contract manufacturers to retool soldering processes and eliminate restricted heavy metals from printed circuit assemblies. European commercial channel distributors are now requiring batch-level material composition documentation as a condition of listing. Food processing facilities in Germany and France are responding by consolidating supplier relationships with RoHS-certified original equipment manufacturers capable of providing continuous compliance attestation.
After-sales service unbundling is separating hardware procurement from consumable replenishment and technical maintenance across hospitality buyer segments. Resort and casino operators in Singapore and Macau are negotiating trap installation as capital expenditure while outsourcing bulb replacement and glue board exchange to third-party facility service contractors. This bifurcation is most visible in Southeast Asia, where integrated pest management providers are capturing recurring revenue streams that hardware manufacturers previously controlled through direct consumable sales.
Electronic Insect Killer Market Segmentation
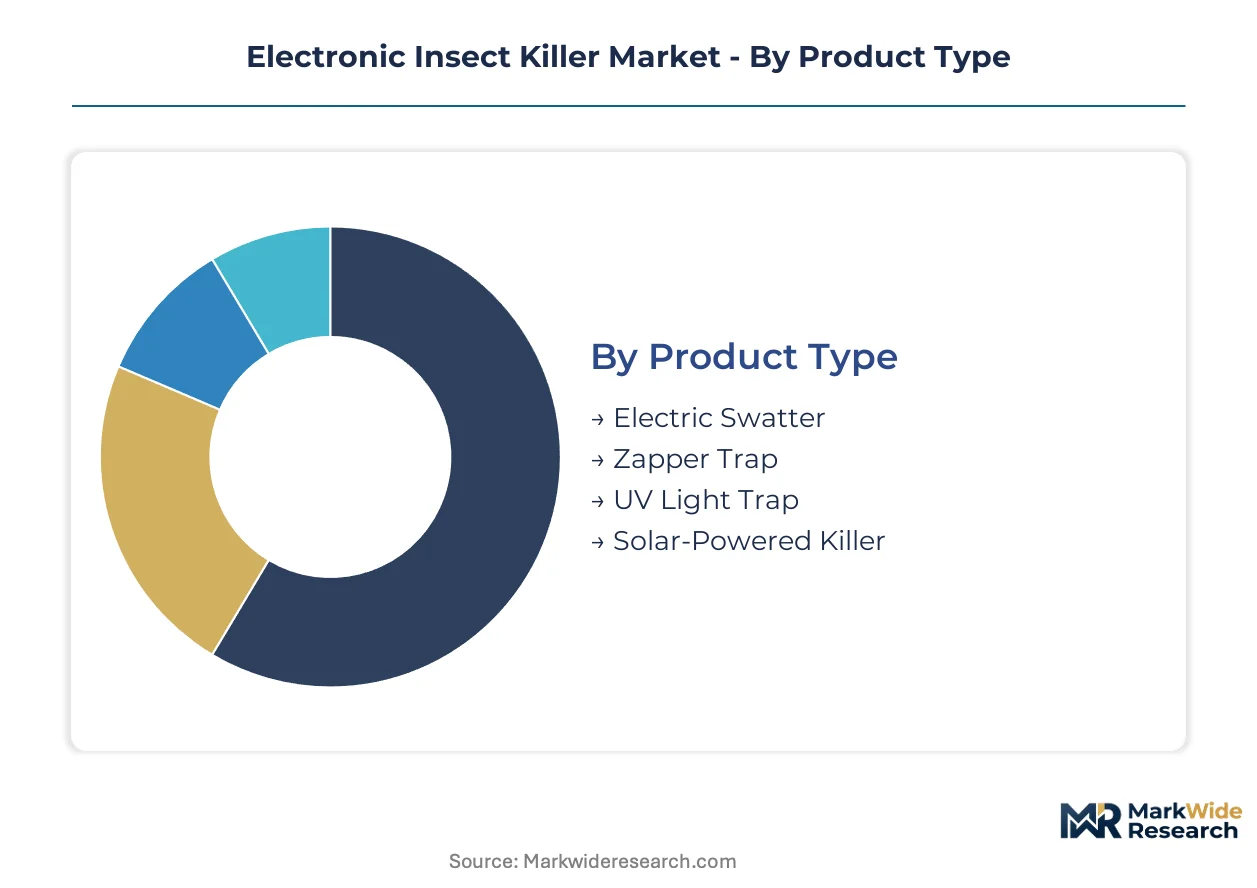
Segmentation reveals how procurement patterns diverge between chemical-dependent agricultural buyers and compliance-driven commercial operators. UV trap configurations generate recurring revenue through consumable replacement cycles, while solar-powered units unlock rural electrification gaps.
Product Type:
Domestic manufacturing concentrates on electric swatters and entry-level zappers for local retail channels, while UV light trap and solar-powered killer exports dominate cross-border trade into Southeast Asian and European markets.
- Electric Swatter:Handheld battery-powered devices utilizing 500-3000 volt grids for immediate arthropod elimination. Demand clusters in Indian and Indonesian residential markets where grid electricity remains intermittent and portable solutions command preference.
- Zapper Trap:Stationary electrocution units with protective housings for outdoor patio deployment. Commercial hospitality procurement in Thailand and Vietnam favors weatherized aluminum enclosures rated for tropical humidity exposure.
- UV Light Trap:Adhesive capture systems using 365-385 nanometer emission spectra. Professional kitchen installations across Singapore and Malaysia specify these units to satisfy vector documentation requirements without chemical residue concerns.
- Solar-Powered Killer:Photovoltaic-integrated units with dusk-to-dawn sensors and battery storage. Off-grid agricultural zones in rural India present unmet demand as electrification gaps persist.
UV Light Trap commands the established base. The steepest expansion runs through Solar-Powered Killer.
Technology:
Cost tiers separate premium UV diode systems from commoditized electromagnetic alternatives, with ionizing variants occupying a narrow niche and chemical repellents facing regulatory compression.
- Ultraviolet:Solid-state emitters at 365-385 nanometer wavelengths reduce energy draw and extend bulb longevity versus legacy fluorescent tubes. German food processing facilities now mandate UV LED configurations to satisfy EU energy efficiency directives.
- Electromagnetic:Ionizing field generators that disrupt insect nervous systems through low-frequency emission. Limited hardware differentiation constrains manufacturer pricing power and compresses segment profitability.
- Ionizing:Corona discharge systems producing ozone as secondary byproduct. FCC emission thresholds govern deployment in US residential channels, restricting market penetration.
- Chemical Repellents:Hybrid systems incorporating synthetic attractant synergists. State-level neonicotinoid prohibitions in California and New York force agricultural segment reformulation and shorten product lifecycle viability.
Ultraviolet technology anchors current procurement volumes. Ionizing systems face the steepest regulatory headwinds.
End User:
Application requirements dictate specification divergence, with commercial buyers prioritizing compliance documentation and agricultural operators emphasizing coverage area per unit cost.
- Residential:Patio and indoor deployment for vector reduction without professional service integration. Brazilian and Mexican consumers favor portable units through Mercado Libre and Amazon marketplace channels.
- Commercial:Food service, hospitality, and healthcare facilities requiring inspector-verifiable catch documentation. Singaporean resort operators now specify IoT-enabled traps with electrocution counters for remote performance verification.
- Agricultural:Large-area protection for crop processing and livestock facilities. Vietnamese rice milling cooperatives deploy solar-powered units across un-electrified post-harvest storage sites.
- Industrial:Warehouse and manufacturing plant installations with high-bay mounting requirements. German automotive suppliers specify IP65-rated housings for foundry and paint shop environments.
Commercial end users generate the deepest margin pools. Agricultural segments are climbing the fastest as rural electrification investments lag.
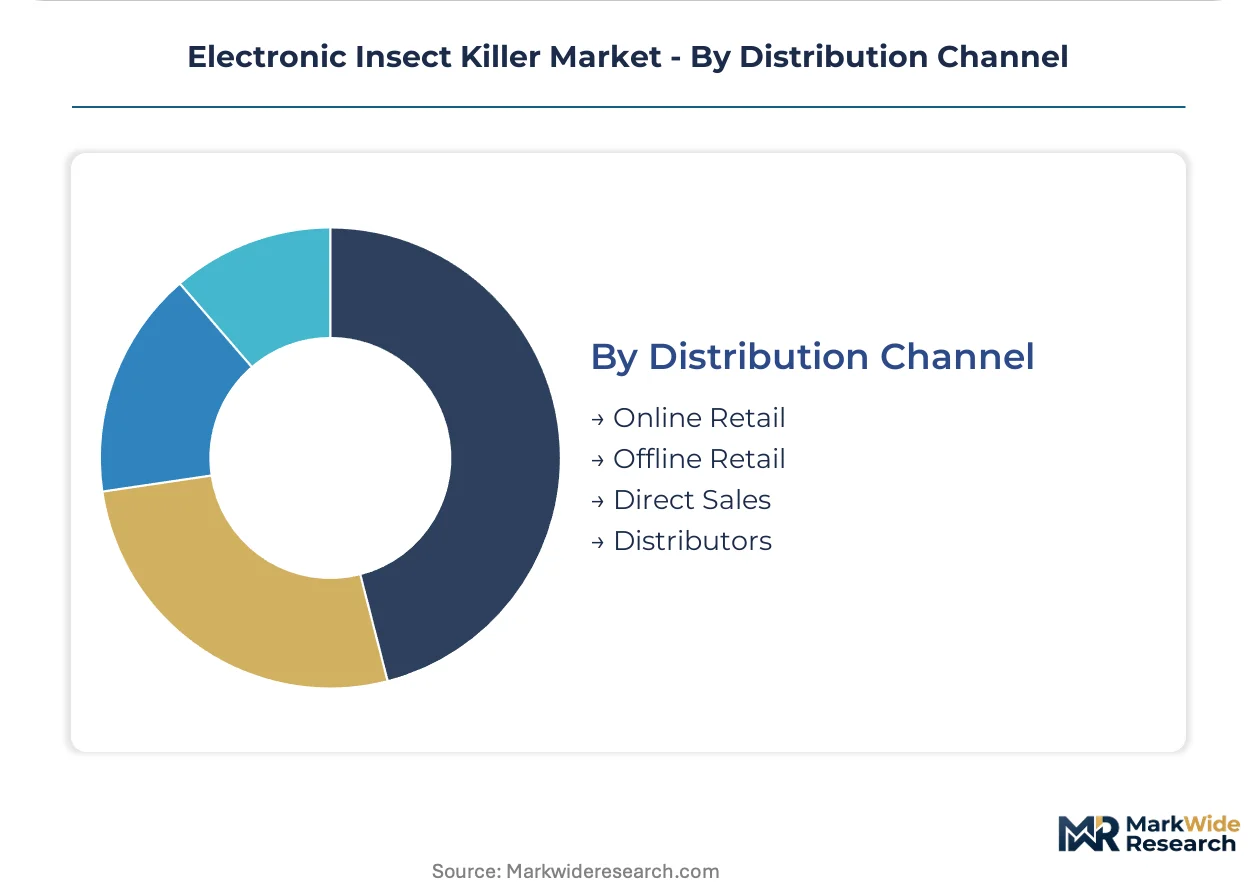
Distribution Channel:
Volume concentration favors offline retail for immediate-need residential purchases, while commercial procurement migrates toward direct manufacturer relationships and distributor networks for specification compliance.
- Online Retail:Marketplace platforms enabling price-transparent comparison for standardized electric swatters and entry-level zappers. Indonesian consumers purchase through Tokopedia and Shopee with same-day delivery in Jakarta and Surabaya.
- Offline Retail:Hardware stores and garden centers stocking seasonal inventory for impulse residential purchases. US Home Depot and Lowe's locations concentrate floor space in southern states with extended mosquito seasons.
- Direct Sales:Manufacturer-to-end-user contracts for large hospitality and agricultural deployments. Dynatrap and Rentokil-PCI field teams negotiate integrated pest management bundles directly with casino and resort operators in Macau.
- Distributors:Regional wholesalers providing localized technical support and spare parts inventory. Foshan GreenYellow Electric Technology routes Asian-Pacific exports through Singapore-based distributors with RoHS compliance certification.
Offline retail commands the established base. Direct sales channels are gaining share fastest as commercial buyers consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foshan GreenYellow Electric Technology Co. Ltd. anchors manufacturing scale for UV light trap exports flowing from China into Southeast Asian hospitality markets and European commercial channels. Trade corridors concentrate on Singapore-based distributors providing RoHS compliance certification for EU-bound shipments.
United States
EPA FIFRA registration pathways accelerate hospitality sector migration toward electrocution-based vector control systems. State-level neonicotinoid prohibitions in California and New York force agricultural segment reformulation of hybrid chemical-electronic units. Southern states including Florida and Texas concentrate retail floor space at Home Depot and Lowe's locations for seasonal residential purchases.
China
Contract manufacturers in Guangdong Province dominate transformer and capacitor sourcing for electrocution grids. MIIT oversees electromagnetic emission thresholds for ionizing technology variants under GB standards. The Pearl River Delta cluster houses Foshan GreenYellow Electric Technology's production facilities serving Asia-Pacific export demand.
Germany
Food processing facilities mandate UV LED configurations to satisfy EU energy efficiency directives. ECHA REACH substance restrictions and RoHS compliance requirements dictate material composition standards for commercial channel entry. Automotive suppliers in Baden-Württemberg specify IP65-rated housings for foundry and paint shop installations.
Singapore
Resort and casino operators negotiate trap installation as capital expenditure while outsourcing maintenance to third-party facility service contractors. The national environmental agency enforces vector control documentation requirements for commercial hospitality venues. Integrated pest management providers capture recurring revenue streams through bulb replacement and glue board exchange contracts.
India
Off-grid agricultural zones present unmet demand for solar-powered killer units with photovoltaic-integrated battery storage. BIS certification requirements govern electrical safety standards for domestic market entry. Rice milling cooperatives in rural Maharashtra and Karnataka deploy solar-powered units across un-electrified post-harvest storage sites.
Electronic Insect Killer Market Vendor Landscape
Player mix skews toward contract manufacturers with captive component sourcing and integrated pest management service bundlers. Market structure fragments across three tiers: premium UV diode system specialists, mid-scale electromechanical fabricators, and commodity electric swatter assemblers. Strategic archetypes include hospitality-focused solution bundlers, solar-powered unit innovators, and RoHS-certified export specialists. Competitive moves concentrate on distributor network expansion for specification compliance and technology licensing for UV LED efficiency gains.
Among Asia-Pacific manufacturers, Foshan GreenYellow Electric Technology Co. Ltd. occupies a position exemplifying scale-driven export specialization. Dynatrap represents the premium-tier archetype anchoring North American distribution networks. Rentokil-PCI Pvt. Ltd. sits within the service-integration tier, bundling electronic units with maintenance protocols. These three entities collectively illustrate the competitive tension between hardware commoditization and recurring revenue capture through service unbundling.
| Leading Market Players |
|---|
| Armatron Co. |
| Livin Well |
| Aspectek |
| Rentokil-PCI Pvt. Ltd. |
| Pelsis Ltd. |
| Koolatron |
| FUTURA DIRECT LTD |
| Dynatrap |
| Foshan GreenYellow Electric Technology Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day transformer lead times from Guangdong contract manufacturers concentrate pricing power among incumbent UV trap specialists while compressing margins for electromagnetic variant assemblers lacking captive component sourcing. This inventory compression cascades through commercial hospitality procurement channels, where specification compliance requirements elevate cost thresholds for RoHS-certified entrants against commodity electric swatter producers.
Pricing Analysis
UV LED diode systems command 40-60% premiums over legacy fluorescent tube configurations, while electromagnetic technology occupies a narrow price band lacking hardware differentiation against adhesive capture alternatives. Pricing stratifies across premium UV diode configurations, standard fluorescent tube units, and economy-grade electric swatters driven by certification tier and after-sales service bundling. Cost compression in the electromagnetic segment intensifies as ionizing variants face substitution pressure from UV trap efficiency gains. Commercial hospitality buyers exhibit the lowest price sensitivity due to compliance documentation requirements, whereas residential consumers in Indian and Indonesian markets prioritize unit cost over performance specifications.
Supply Chain Analysis
Inventory cycles for high-voltage grid components stretch to twelve weeks during peak Southeast Asian procurement seasons, constraining responsiveness to tropical climate-driven replacement demand. Transformer and capacitor sourcing concentrates in China, South Korea, and Taiwan, with UV LED diode fabrication anchored in Chinese and German semiconductor facilities. Electrocution grid assemblies draw from East Asian contract manufacturers, while adhesive capture surface substrates source from Malaysian and Thai polymer processors. Single-source vulnerability in Guangdong Province transformer supply exposes lead times to regional logistics volatility. Distribution runs through Singapore-based RoHS-certified wholesalers for EU-bound shipments and direct manufacturer relationships for North American hospitality deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated pest management providers and hospitality procurement consortia, fragmenting hardware manufacturers' direct channel control while elevating service-bundling requirements for market access.
For Market Incumbents: Compound service revenue capture by unbundling hardware procurement from consumable replenishment and predictive maintenance contracts, defending against solar-powered unit innovators penetrating rural agricultural gaps through photovoltaic-integrated battery storage advantages. Prioritize backward integration into UV LED diode sourcing to secure supply continuity against East Asian component volatility. For New Entrants and Emerging Players: CE marking fast-track through EU RoHS-certified contract manufacturers unlocks specification-compliant entry into German and French food processing channels, bypassing incumbent distributor relationships. Target solar-powered killer deployment across un-electrified Indian rice milling cooperatives and Vietnamese post-harvest storage sites. Pursue integrated pest management provider partnerships rather than direct hospitality sales to accelerate recurring revenue capture. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because consumable replacement cycles for UV lamps and glue boards generate predictable cash flows decoupled from hardware replacement demand. Acquisition targets should demonstrate RoHS certification portfolios and established distributor relationships in Singapore or European commercial channels. Monitor EPA state-level neonicotinoid restriction expansion as an inflection signal for hybrid chemical-electronic system obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| UV LED Efficiency Licensing | Technology transfer agreements with German diode manufacturers accelerate energy compliance in EU food processing facilities. |
| RoHS Certification Investment | Lead-free solder retooling enables batch-level documentation for European commercial channel distributor listings. |
| IoT Sensor Integration | Electrocution counter modules enable predictive maintenance contracts with Singaporean integrated pest management providers. |
| Solar-Powered Unit Scale-Up | Photovoltaic-integrated production expansion addresses unmet demand across rural Indian agricultural electrification gaps. |
| Direct Hospitality Sales Expansion | Manufacturer-to-casino negotiations in Macau bypass third-party facility service contractor margin capture. |
Methodological Framework
A standing panel of commercial kitchen procurement managers, integrated pest management service directors, agricultural cooperative equipment buyers, and UV LED component sourcing specialists provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against EPA FIFRA registration databases, EU ECHA REACH substance restriction filings, and BIS electrical safety certification records. Trade data from customs authorities in China, Singapore, and Germany triangulated against SEC 10-K disclosures from listed electronics manufacturers. Bottom-up unit shipment estimates from contract manufacturers converged with top-down hospitality procurement budget allocations.
Output consistency was validated against external benchmarks including energy efficiency directive compliance filings and integrated pest management contract value disclosures. The analytical framework modeled demand across product type, technology generation, end-user vertical, and distribution channel dimensions throughout the forecast period. CAGRs were derived from replacement cycle compression observations in tropical climate zones and regulatory substitution effects in US commercial hospitality segments. Forecast inputs incorporated UV LED diode efficiency improvement curves and rural electrification investment lag indicators.
The analysis sits within stated boundaries; outcomes outside sustained EPA pesticide restriction enforcement or accelerated Southeast Asian urban density trends would require recalibration. Forecasts reflect assumptions regarding component supply continuity and certification pathway stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Video Doorbell Market