
 United Kingdom Cat Litter Market | 2026-2036
United Kingdom Cat Litter Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Cat Litter Market Analytics
Plant-based fiber substrates are broadening the material palette beyond traditional bentonite clay as cost curves flatten and retail shelf space shifts. Pettex Limited anchors its position through deep vertical integration with UK mineral extraction operations. Mars Incorporated differentiates via veterinary-endorsed formulations targeting multi-cat households. Church & Dwight Co., Inc. competes on brand recognition built through sustained above-the-line investment in British pet media.
United Kingdom cat litter comprises absorbent granular or pelletized substrates engineered to capture feline waste moisture and neutralize ammonia volatilization, typically achieving 200-400% liquid absorption by mass depending on base material. The product serves pet owners, veterinary practices, and animal welfare organizations requiring hygienic, manageable waste containment. Clumping clay formulations still occupy the largest revenue pool due to established consumer habit and lower per-kilogram pricing, yet biodegradable segments derived from wood and paper feedstocks are capturing the fastest growth as retailers reallocate shelf space to ESG-aligned assortments. Corn-based materials sustain premium positioning through compostability claims and reduced dust generation.
The UK's Animal Welfare Act 2006 and Environment Agency waste classification rules shape product disposal pathways and compositional claims, while REACH compliance governs chemical additives in deodorizing formulations. Trading Standards and the Advertising Standards Authority scrutinize biodegradability assertions, forcing reformulation transparency. Stakeholders must monitor evolving extended producer responsibility frameworks for pet care packaging and assess whether in-house production of alternative substrates or supplier partnerships offer more resilient margin structures.
Market Dynamics
The EU Green Deal's sustainability targets are pressuring UK manufacturers to abandon sodium bentonite clay mining in favor of biodegradable feedstocks, restructuring raw material sourcing and reformulation roadmaps across the supply base.
Growth Catalysts
- Extended Producer Responsibility frameworks:The UK's evolving EPR rules for pet care packaging incentivize lightweight, compostable substrates that reduce end-of-life disposal costs for retailers and municipal waste handlers.
- Urban apartment density:Greater London's concentrated multi-cat households generate disproportionate demand for odor-control formulations with space-efficient storage footprints.
- Wood fiber pelletization:Advanced compression technologies enable consistent clumping performance in plant-based alternatives, narrowing the functional gap with traditional bentonite clay.
Market Restraints
- Bentonite import dependency:UK manufacturers rely on Wyoming-sourced sodium bentonite clay, exposing margin structures to transatlantic shipping rate volatility and dollar-denominated input costs.
- REACH compliance friction:ECHA's chemical additive scrutiny for deodorizing formulations extends product development timelines and restricts fragrance compound options.
- Composting infrastructure gaps:Municipal facilities lack dedicated streams for biodegradable cat waste, undermining compostability claims and consumer willingness to pay premiums.
Strategic Opportunities
- Scotland and Northern England penetration:These regions exhibit lower plant-based litter adoption rates than the South East, presenting whitespace for regional distribution partnerships.
- Veterinary clinic channel:Direct supply relationships with veterinary practices enable formulation endorsements and recurring bulk purchasing agreements.
- EU Green Deal alignment:Early certification to EU sustainability standards positions UK exporters for post-regulatory harmonization advantages in continental markets.
Industry Challenges
- Biodegradability certification timelines:Advertising Standards Authority substantiation requirements for compostability claims demand extended laboratory testing protocols.
- Legacy clay production asset stranding:Existing mineral extraction and processing equipment faces accelerated depreciation as reformulation timelines compress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Cat Litter Market |
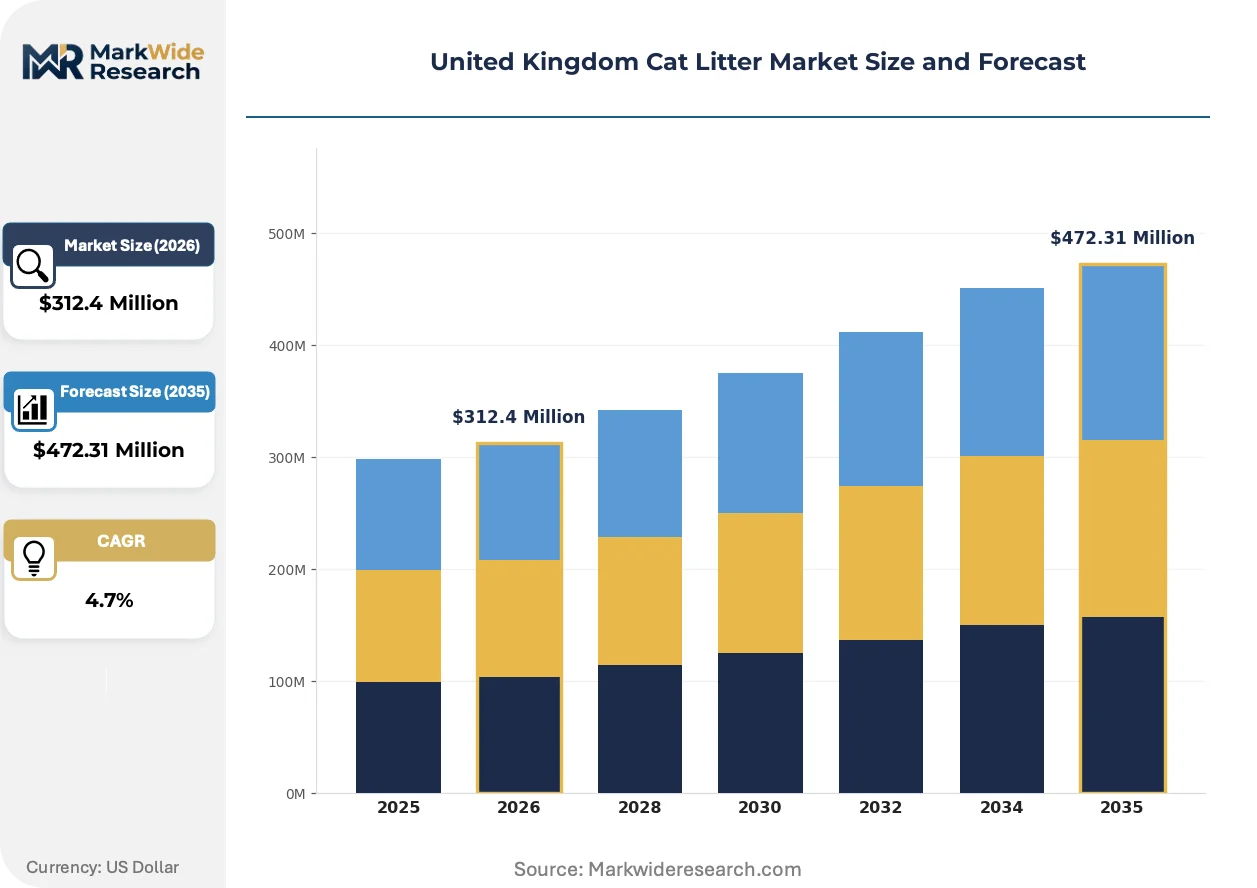
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clumping, Non-Clumping, Crystal, Biodegradable Material: Clay, Wood, Paper, Corn Form: Granular, Pellet, Sheet, Film End User: Households, Veterinary Clinics, Animal Shelters, Pet Stores |
| Companies Covered | The Clorox Company, Pettex Limited, Mars Incorporated, Omlet, R Plevin & Sons Ltd, Nestlé S.A. (Purina), Pets Choice Ltd., UK Best Cat Litter Ltd, Church & Dwight Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Cat Litter Market Evolving Landscape
Material science advances and regulatory stringency are converging to transform substrate composition, manufacturing processes, and retail assortment strategies across British pet care channels.
Enzymatic odor-neutralization coatings are unifying antimicrobial protection with ammonia-binding functionality in single-layer pellet structures. Premium pet-owning households in Greater London are adopting these enhanced formulations at accelerating rates despite 40-60% price premiums over uncoated alternatives. This convergence is compressing the addressable market for standalone deodorizing additives and reformulating competitive differentiation around integrated substrate performance.
REACH authorization procedures for fragrance compounds and dust-suppressant additives are tightening permissible chemical portfolios in deodorizing formulations. UK manufacturers face reformulation costs and supply chain requalification requirements that disproportionately burden mid-tier producers with limited R&D bandwidth. The clumping clay segment is responding with simplified unscented variants that preempt regulatory exposure while targeting fragrance-sensitive multi-cat households.
Subscription-based replenishment models are displacing episodic supermarket purchasing among urban professional demographics. Direct-to-consumer platforms and veterinary practice auto-ship programs capture recurring revenue streams that traditional grocery and pet specialty retailers struggle to replicate. This behavioral shift concentrates most visibly in Greater London and the South East, where delivery logistics density supports same-day or next-day fulfillment expectations.
United Kingdom Cat Litter Market Segmentation
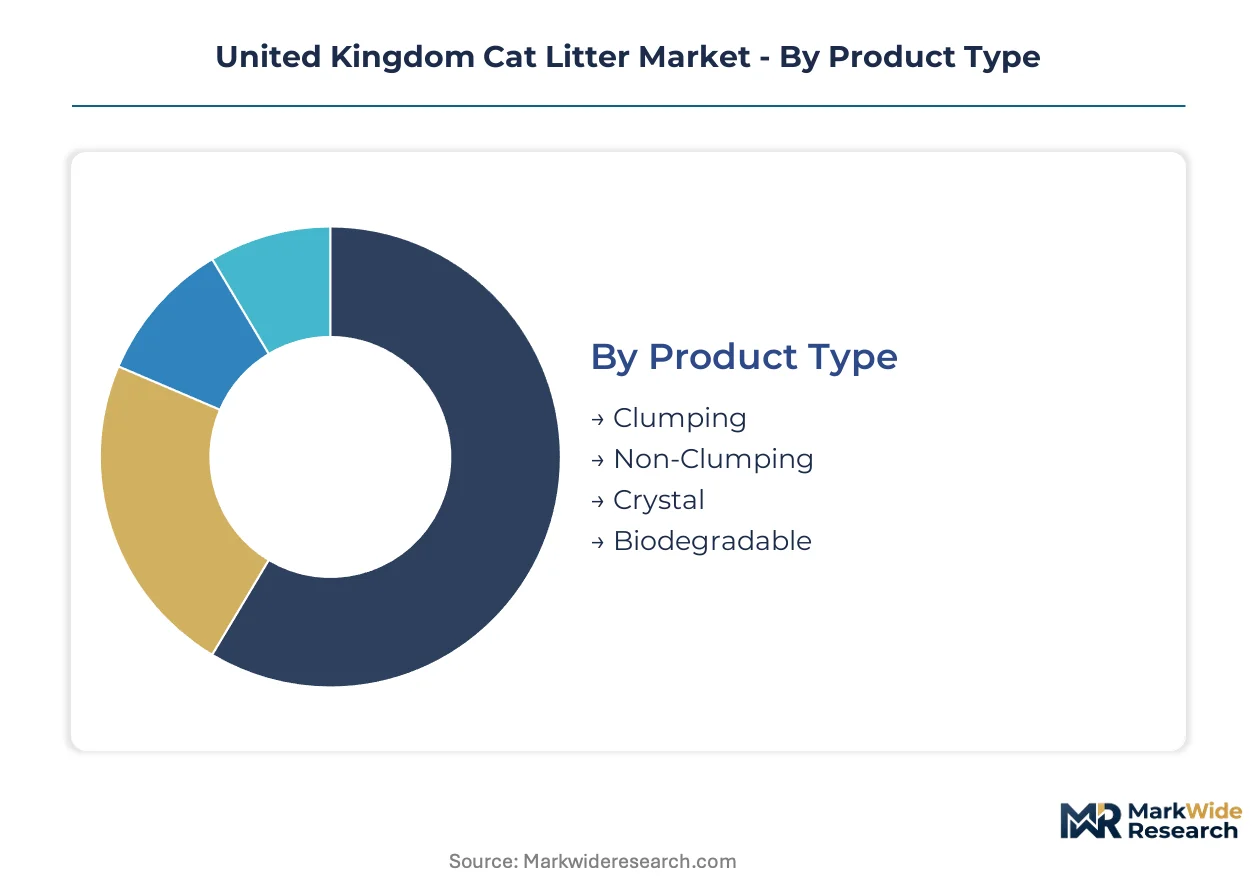
Segmentation in the United Kingdom cat litter market reveals how substrate technology, material sourcing, and distribution channel economics create distinct competitive arenas. Manufacturers optimize formulation and pricing strategies against specific performance requirements and disposal constraints that vary by user type.
Product Type:
Clumping formulations command volume leadership through established consumer habit, while biodegradable alternatives capture premium expansion as regulatory pressure intensifies.
- Clumping:Sodium bentonite clay aggregates form solid masses upon liquid contact, enabling selective waste removal and extended substrate life. Multi-cat households in Greater London and the South East favor these formulations for odor containment in confined apartment spaces.
- Biodegradable:Plant-based substrates from wood, paper, or agricultural residues decompose in composting environments or landfill conditions. EU Green Deal alignment pressures and retailer ESG mandates are accelerating shelf space reallocation toward these alternatives despite higher per-kilogram pricing.
- Non-Clumping:Absorbent clay or mineral substrates require complete tray replacement, maintaining cost-sensitive household penetration through lower unit pricing.
- Crystal:Silica gel formulations deliver extended odor control through moisture absorption without clumping, targeting single-cat professional demographics with convenience positioning.
Mature deployment sits with Clumping. Newer deployment is concentrated in Biodegradable.
Material:
Mineral extraction economics versus agricultural feedstock availability determines margin structures and supply resilience across substrate categories.
- Clay:Wyoming-sourced sodium bentonite dominates manufacturing inputs, exposing UK producers to dollar-denominated cost volatility and transatlantic logistics constraints. REACH compliance for dust suppressants adds regulatory friction to traditional formulations.
- Wood:Compression pelletization of softwood fibers achieves clumping performance parity with clay alternatives. Scottish timber operations and Scandinavian import streams provide regional sourcing diversification.
- Paper:Recycled cellulose substrates target fragrance-sensitive households and veterinary environments requiring low-dust specifications.
- Corn:Agricultural residue processing delivers compostability certification and reduced particulate generation, sustaining premium positioning in urban professional segments.
Supply security favors Wood and Paper with domestic or near-shore sourcing. Import dependency constrains Clay flexibility.
Form:
Physical substrate architecture shapes manufacturing capital requirements, packaging economics, and end-use handling convenience.
- Granular:Crushed and screened mineral or plant particles provide familiar texture acceptance and rapid liquid dispersion. Bentonite and wood fiber variants both deploy this form factor for maximum retail distribution coverage.
- Pellet:Compression-molded cylinders reduce dust generation and enable precise dosing measurement. Advanced pelletization equipment investment is concentrating production scale among integrated manufacturers.
- Sheet:Layered absorbent pads target specific tray configurations and travel applications with disposable convenience.
- Film:Thin substrate membranes serve niche odor-barrier and disposable liner applications with minimal material throughput.
Manufacturing scale concentrates in Granular. Pellet capacity expansion is climbing the fastest as plant-based adoption accelerates.
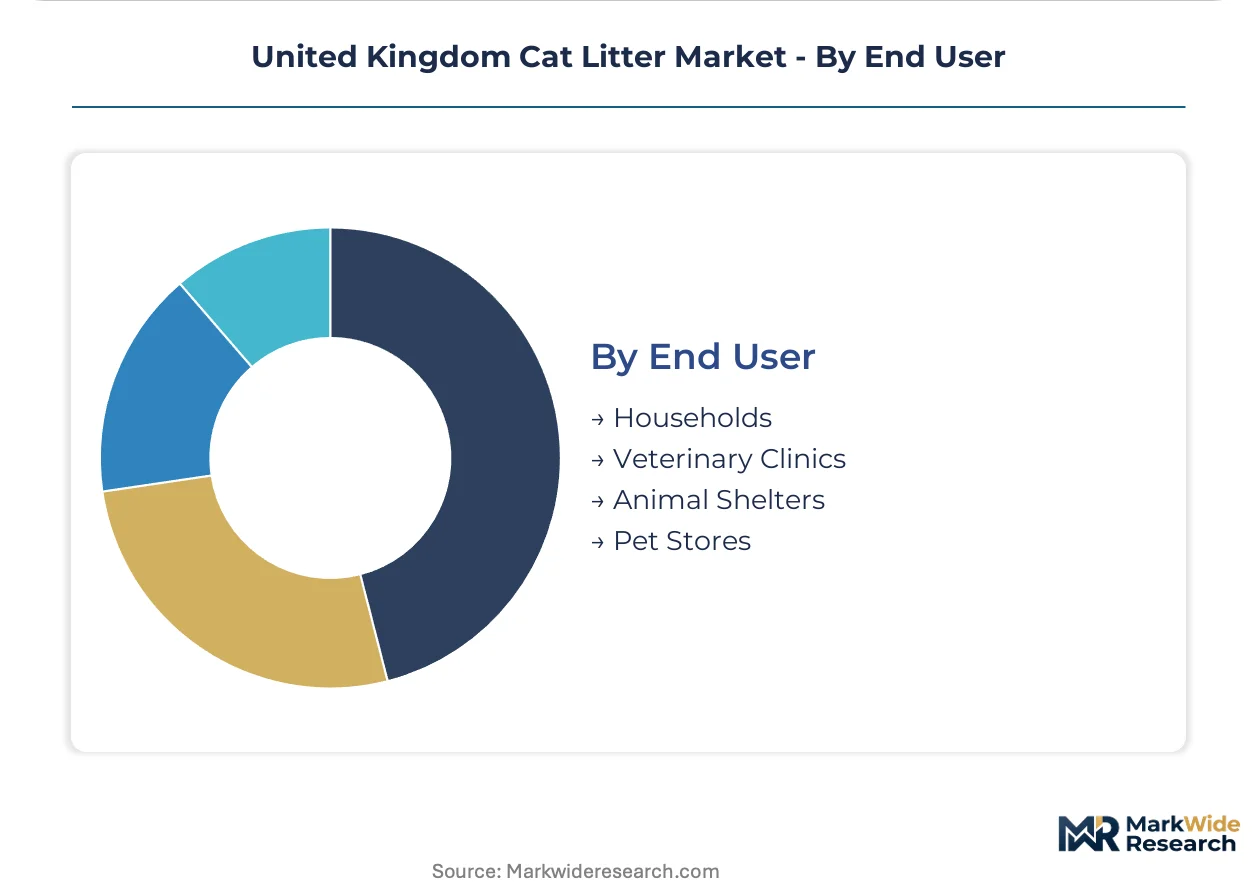
End User:
Purchasing frequency, volume scale, and formulation sophistication requirements diverge sharply across institutional and consumer channels.
- Households:Individual consumers drive assortment breadth through fragmented channel preferences spanning supermarkets, pet specialty retailers, and direct-to-consumer platforms. Subscription auto-ship penetration is highest in Greater London professional demographics.
- Veterinary Clinics:Clinical environments demand low-dust, unscented formulations with bulk packaging efficiency. Direct supply relationships enable formulation endorsement and recurring procurement agreements.
- Animal Shelters:High-volume, cost-optimized substrates prioritize absorption capacity over premium performance features given population turnover and budget constraints.
- Pet Stores:Specialty retail channels curate premium and novel formulations for enthusiast consumers, serving as product launch platforms before mass market expansion.
Volume concentration sits with Households. Margin expansion is concentrating in Veterinary Clinics through professional endorsement premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London and the South East concentrate demand through dense apartment living and premium pet ownership rates. Scotland and Northern England present underpenetrated whitespace for plant-based substrate adoption.
Greater London
Multi-cat households in high-density apartments drive disproportionate demand for odor-control and space-efficient formulations. The Environment Agency's waste classification rules shape disposal pathways for biodegradable substrates. Veterinary practices in Camden and Kensington serve as endorsement channels for premium enzymatic formulations.
South East England
Professional demographics in Brighton, Oxford, and Guildford sustain subscription-based replenishment models through direct-to-consumer platforms. EU Green Deal alignment pressures filter through retail ESG mandates reallocated toward compostable assortments. The M25 corridor hosts distribution hubs serving same-day fulfillment expectations.
Midlands
Cost-sensitive household penetration maintains non-clumping clay volumes through supermarket channel dominance. Trading Standards scrutiny of biodegradability claims extends laboratory testing timelines for regional manufacturers. Birmingham and Leicester industrial zones process recycled paper feedstocks for low-dust veterinary formulations.
Scotland
Scottish timber operations provide regional sourcing diversification for wood fiber pelletization. The Scottish Environment Protection Agency's waste regulations diverge from England on composting infrastructure standards. Aberdeen and Glasgow retail channels exhibit lower plant-based adoption rates than southern counterparts.
Northern England
Yorkshire and Lancashire manufacturing bases anchor bentonite clay processing despite reformulation pressures. REACH compliance friction for chemical additives disproportionately burdens mid-tier producers with limited R&D bandwidth. Manchester distribution partnerships present whitespace expansion opportunities for biodegradable substrate suppliers.
United Kingdom Cat Litter Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers hedge against clay asset stranding. The vendor base spans integrated mineral extractors, multinational pet care conglomerates, and regional specialists. Three archetypes prevail: vertically integrated clay producers, plant-based substrate innovators, and veterinary-channel specialists. Competitive moves concentrate on supplier partnerships for alternative feedstocks and certification investments for EU Green Deal alignment.
Among UK-based operators, Pettex Limited exemplifies the integrated extraction archetype through captive mineral sourcing. Mars Incorporated and Church & Dwight Co., Inc. occupy multinational positions leveraging brand recognition and sustained media investment. Nestlé S.A. (Purina) and The Clorox Company represent scale-driven players with portfolio breadth spanning multiple substrate technologies.
| Leading Market Players |
|---|
| The Clorox Company |
| Pettex Limited |
| Mars Incorporated |
| Omlet |
| R Plevin & Sons Ltd |
| Nestlé S.A. (Purina) |
| Pets Choice Ltd. |
| UK Best Cat Litter Ltd |
| Church & Dwight Co., Inc. |
| Others |
Value Network & Pricing Analysis
Material science expertise concentrated in Yorkshire and Lancashire manufacturing corridors widens pricing spreads between premium enzymatic formulations and economy clay substrates, as labor-cost differentials compound raw material volatility across tiers.
Pricing Analysis
Volume leadership in clumping clay generates thin margins per kilogram, while biodegradable segments command substantial premiums through compostability certification and reduced dust claims. Price differentiation rests on REACH compliance tier and veterinary endorsement status, with fragrance-free clinical grades sustaining the widest spreads. Cost compression in the clay tier intensifies due to dollar-denominated bentonite imports, though supermarket private-label buyers exhibit the highest price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Wyoming-sourced sodium bentonite, as UK manufacturers lack domestic mineral extraction alternatives for traditional clumping formulations. Raw material dependencies extend to Scottish timber operations for wood fiber, Scandinavian pulp imports for paper substrates, and agricultural residue processors for corn-based alternatives. Tariff exposure on transatlantic shipping routes threatens margin stability. Distribution runs through supermarket chains, pet specialty retailers, and direct-to-consumer platforms serving Greater London's same-day fulfillment expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK cat litter supply remains constrained by limited domestic mineral extraction capacity, with Wyoming bentonite dependency propping pricing power across the clumping segment despite reformulation pressures.
For Market Incumbents: Deploy backward integration into Scottish timber supply to secure wood fiber pelletization feedstocks against Scandinavian import volatility. Accelerate enzymatic coating R&D to differentiate integrated substrate performance before mid-tier competitors replicate the technology. Channel control through veterinary practice direct supply relationships defends margin position against subscription-based entrants. For New Entrants and Emerging Players: The forty-to-sixty percent price premium gap between coated enzymatic formulations and uncoated alternatives creates entry space for hybrid mid-tier positioning. Scotland and Northern England retail channels show lower plant-based penetration than southern counterparts, presenting whitespace for regional distribution partnerships. A veterinary endorsement-first go-to-market angle builds credibility before mass retail expansion. For Investors and Strategic Acquirers: Re-rating potential sits with wood fiber pelletization specialists given EU Green Deal alignment and retailer ESG mandate acceleration. Long-term viability favors substrate technology platforms with multi-feedstock flexibility over single-mineral dependence. The signal to watch is Advertising Standards Authority compostability certification timelines, as substantiated claims unlock premium shelf space reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive Scottish softwood sourcing insulates against Scandinavian pulp price volatility and EPR compliance costs. |
| Enzymatic Coating R&D Investment | Integrated odor-neutralization technology narrows the functional gap with clay while commanding premium positioning. |
| Veterinary Channel Direct Supply | Clinical endorsement unlocks recurring bulk procurement and professional credibility transfer to household segments. |
| Compostability Certification Acceleration | Advertising Standards Authority substantiation enables retailer ESG-driven shelf space reallocation toward biodegradable assortments. |
| Subscription Platform Development | Auto-ship replenishment captures recurring revenue streams that episodic supermarket purchasing cannot replicate. |
Research Methodology
Multi-period observation of substrate technology adoption rates, pricing tier migrations, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with plant managers at Yorkshire mineral processing facilities, procurement leads at major supermarket chains, veterinary practice managers, and R&D directors at alternative feedstock innovators. Secondary validation drew from Environment Agency waste classification guidance, REACH authorization databases, UK timber trade statistics, and retail audit data tracking shelf space reallocation. Bottom-up volume modeling across product type, material, and end-user segments triangulated against top-down market sizing from import records and production capacity estimates.
Segment-weighting approaches applied differential growth assumptions to biodegradable versus clay substrate categories, with material sourcing constraints and EU Green Deal compliance timelines informing trajectory divergence across the projection horizon. End-user segmentation modeled household, veterinary clinic, animal shelter, and pet store channels separately, while geographic clustering captured Greater London apartment density effects against Scotland and Northern England whitespace. CAGRs derived from elasticity-adjusted volume projections and pricing tier spread compression dynamics, with wood fiber pelletization capacity buildout and enzymatic coating penetration serving as key forecast inputs.
Underlying measurement precision varies by segment; biodegradable substrate adoption carries tighter precision than crystal silica formulations given regulatory visibility. Forecasts reflect assumptions about composting infrastructure development, REACH fragrance compound restrictions, and EPR framework implementation that could shift materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
GCC Dog Food Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Pet Collar Market