
 Global Personal Loans Market | 2026-2036
Global Personal Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Loans Market Outlook
Debt consolidation among salaried households is rebalancing toward medical expense financing as healthcare cost burdens intensify. SoFi Technologies leverages its technology stack to dominate graduate refinancing and adjacent unsecured products. LendingClub Corp. anchors its model on marketplace efficiency, connecting institutional capital directly to prime consumer segments. Upstart Network Inc. differentiates through AI-powered underwriting that extends credit access beyond traditional FICO boundaries.
Personal loans constitute unsecured or secured consumer credit instruments issued by banks, credit unions, fintech platforms, or peer-to-peer networks, typically structured as fixed-term installment contracts with stated interest rates, principal amortization schedules, and predefined use restrictions or flexibility clauses. Their primary commercial purpose is to bridge liquidity gaps for individuals without requiring collateral liquidation or equity dilution. Unsecured loans occupy the largest share of origination volume, though peer-to-peer lending registers the fastest structural expansion as retail investors seek yield alternatives to conventional fixed income. Online platforms command the dominant approval channel position, while traditional banks retain margin concentration in jumbo secured products and relationship-driven underwriting.
The Consumer Financial Protection Bureau in the United States enforces disclosure standards and fair lending protocols that shape product design and marketing practices across originators. The European Banking Authority and the United Kingdom's Financial Conduct Authority impose capital adequacy and conduct rules that constrain fintech market entry while elevating compliance costs for cross-border operators. Stakeholders must monitor evolving open banking mandates and alternative data regulations to calibrate underwriting models and channel investments.
Market Dynamics
Open banking mandates and embedded finance integration are compressing origination timelines while fragmenting borrower acquisition channels across traditional and digital-first lenders.
Growth Catalysts
- PSD2 and UK Open Banking:Standardized API access to transaction data enables real-time income verification, reducing underwriting friction for thin-file borrowers across the European Union and United Kingdom.
- Embedded lending at point-of-sale:E-commerce checkout integrations and buy-now-pay-later migration into term-loan structures capture borrower intent at transaction moments.
- Alternative data proliferation:Utility payment histories, rental records, and gig-economy platform data expand addressable populations beyond FICO-reliant scoring models.
Market Restraints
- Deposit funding volatility:Regional banks face rising cost of funds as rate-sensitive savers migrate to money-market instruments, compressing net interest margins on unsecured portfolios.
- Cross-border regulatory fragmentation:Divergent licensing requirements between the United Kingdom's Financial Conduct Authority and national EU regulators prevent seamless passporting of fintech operations.
- Secured credit substitution:Home equity line availability and mortgage cash-out refinancing resurface as rate environments shift, siphoning prime borrower demand from unsecured products.
Strategic Opportunities
- India's credit-underserved tier-2 cities:Fintech-bank partnerships in Jaipur, Indore, and Kochi deploy vernacular-language interfaces and Aadhaar-linked e-KYC to penetrate salary-backed borrower segments outside metro footprints.
- Climate-linked personal lending:Green home improvement and electric vehicle retrofit financing products align with EU Green Deal disclosure requirements and attract institutional ESG capital.
- Payroll-integrated repayment:Employer-sponsored earned-wage-access platforms evolve into salary-deducted installment products, reducing default probability through automated collection.
Industry Challenges
- AI model explainability requirements:The EU AI Act's credit-scoring provisions mandate human-interpretable underwriting logic, complicating neural-network deployment and necessitating surrogate model development.
- Legacy core system migration:Traditional banks face multi-year transformation timelines to replace COBOL-based loan origination platforms with API-native architectures capable of real-time decisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Loans Market |
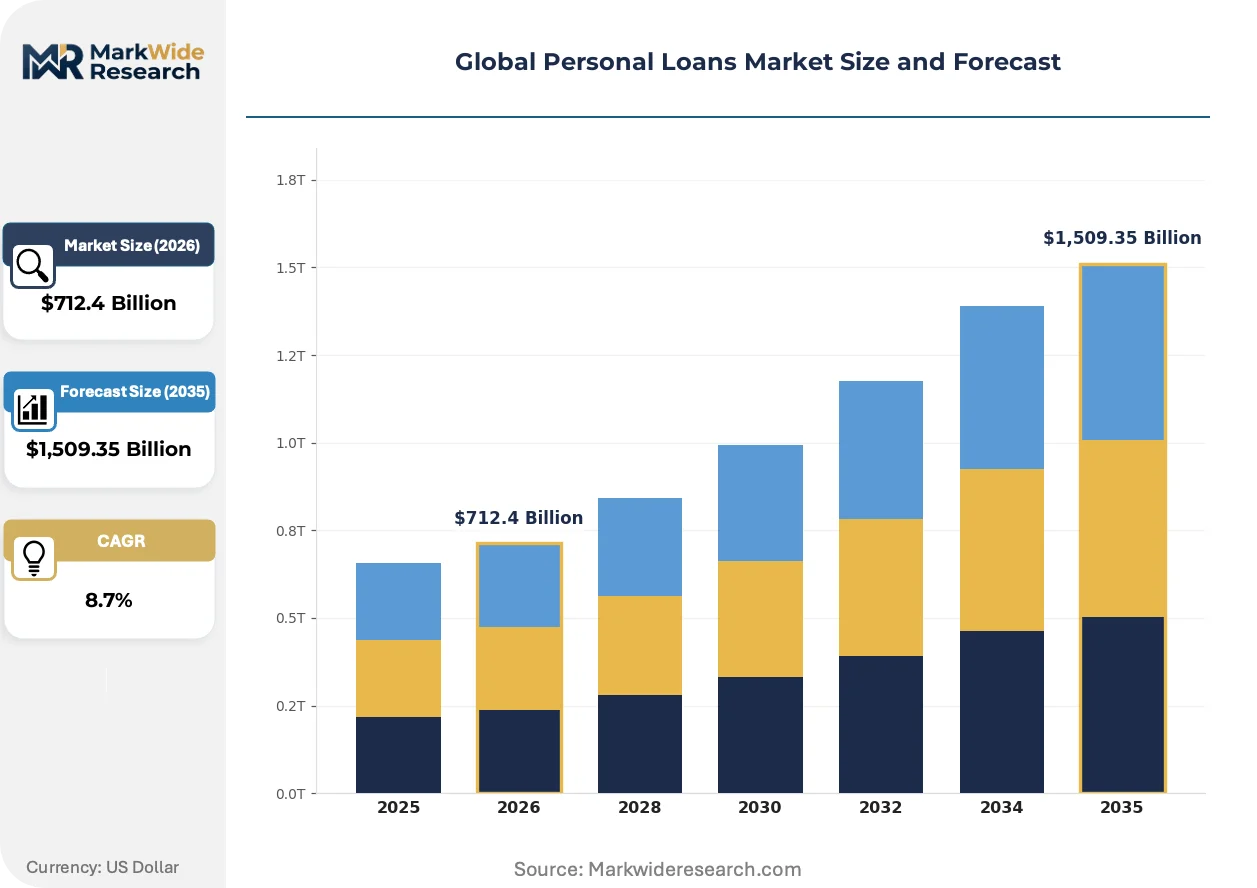
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,509.35 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Peer-to-Peer Lending, Fixed Rate Loans Borrower Profile: First-Time Borrowers, Salary Earners, Students, Self-Employed Individuals Loan Purpose: Debt Consolidation, Home Improvement, Medical Expenses, Emergency Funds Approval Channel: Online Platforms, Traditional Banks, Credit Unions, Financial Technology Firms |
| Companies Covered | American Express Co., SoFi Technologies Inc., LendingClub Corp., Citigroup Inc., Avant LLC, Prosper Marketplace Inc., Upstart Network Inc., Funding Circle Holdings Plc, Wells Fargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Loans Market Strategic Shifts
Algorithmic underwriting and real-time data pipelines are displacing batch-processed credit decisions, compressing approval windows from days to minutes while elevating model governance requirements.
Machine learning risk models are expanding into subprime and near-prime segments previously served by payday and title lenders. Fintech platforms deploy gradient-boosted ensembles on alternative data streams to score borrowers with sparse credit files. This expansion is compressing the market for high-cost fringe credit while drawing regulatory scrutiny on fairness testing and disparate impact.
The Consumer Financial Protection Bureau's Section 1033 rulemaking mandates standardized data portability for consumer financial information. This industrial consequence forces banks to build API infrastructure for borrower-permissioned data sharing with competing platforms. Subprime-focused fintechs and credit unions are most affected, responding through consortium investments in compliance middleware and consent-management tools.
Borrowers increasingly expect instant disbursement and mobile-first servicing, displacing branch-based relationship origination. Digital-native lenders capture this preference through single-session application-to-funding workflows, while traditional banks retrofit mobile interfaces onto legacy decision engines. India and Southeast Asia display the most visible acceleration, where super-app ecosystems embed lending into ride-hailing and e-commerce user journeys.
Global Personal Loans Market Segmentation
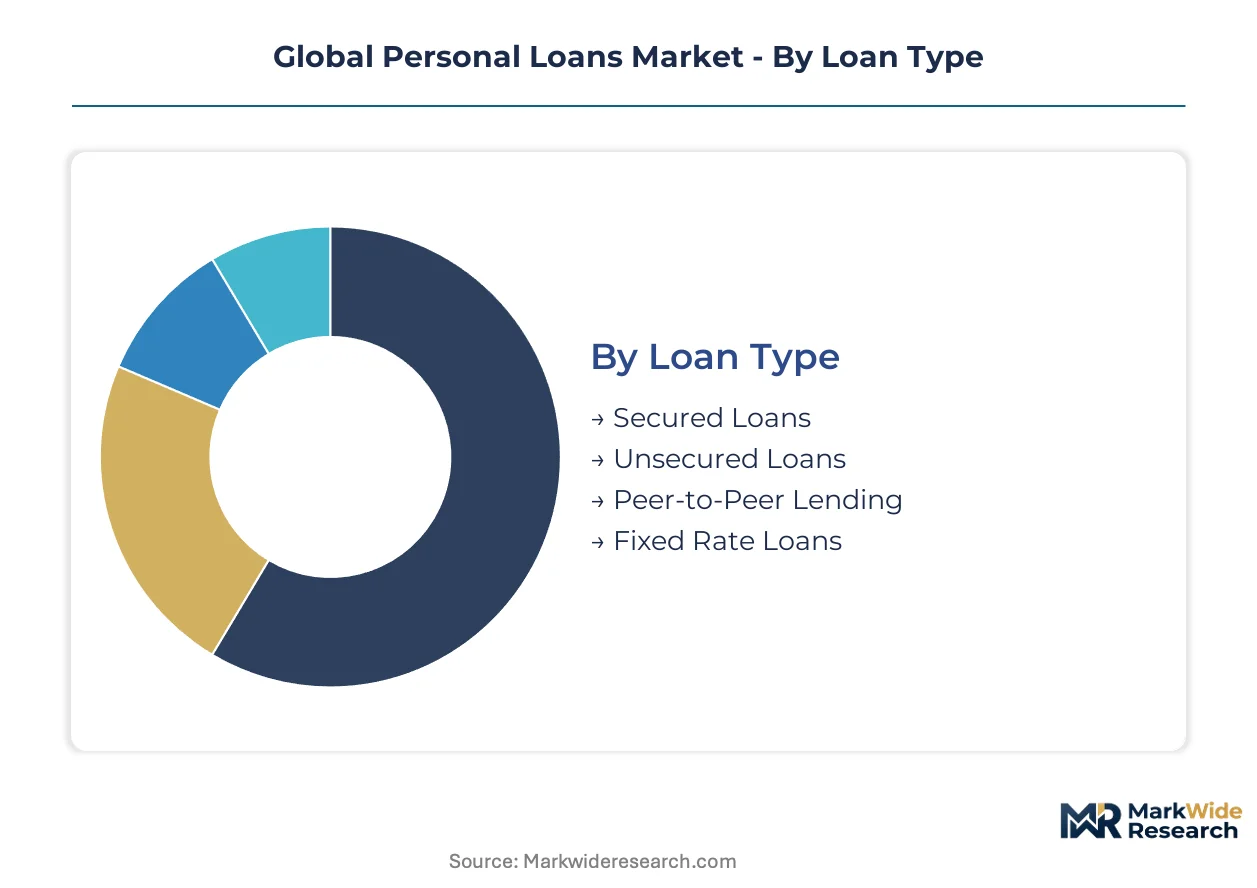
Segmentation in personal lending reveals how risk appetite, regulatory exposure, and technology adoption fragment origination economics across borrower types and distribution channels. Lenders calibrate product design, pricing models, and capital allocation against these dimensions to optimize portfolio yield while managing default probability.
Loan Type:
Borrower collateral willingness and regulatory capital treatment differentiate demand patterns across this category.
- Unsecured Loans:These products require no pledged assets, relying instead on cash-flow underwriting and credit scoring. Salary earners in India and Southeast Asia drive origination volumes as fintech platforms deploy alternative data to approve thin-file applicants previously excluded from formal credit.
- Peer-to-Peer Lending:Retail investors fund borrower obligations through marketplace platforms, earning yield spreads above conventional deposits. Regulatory frameworks in the United Kingdom and European Union constrain platform operations through conduct rules and capital requirements, though institutional participation continues expanding.
- Secured Loans:Collateral-backed instruments typically carry lower interest rates due to reduced loss-given-default. Vehicle titles and savings deposits serve as common pledge assets across emerging markets.
- Fixed Rate Loans:Interest rate certainty protects borrowers against central bank policy shifts. These products attract risk-averse segments seeking predictable amortization schedules.
Unsecured loans lead volumes today; peer-to-peer lending is gaining share fastest.
Borrower Profile:
Income stability and documentation accessibility determine underwriting cost and approval velocity for each segment.
- Salary Earners:Predictable cash flows enable automated income verification through payroll API integrations. This segment commands the lowest acquisition costs and fastest time-to-yes across digital platforms.
- Self-Employed Individuals:Irregular revenue streams demand enhanced documentation or alternative data proxies. Open banking mandates in the European Union and United Kingdom are compressing verification friction for this historically underserved category.
- First-Time Borrowers:Absence of credit history requires behavioral scoring and thin-file algorithms. Fintech partnerships with regional banks in India target this segment through Aadhaar-linked e-KYC infrastructure.
- Students:Future income potential rather than current cash flow drives underwriting logic. Graduate refinancing products dominate this space in the United States.
Salary earners anchor origination volumes; self-employed individuals show the steepest expansion trajectory as verification technology improves.
Loan Purpose:
Use-case specificity shapes product structure, term length, and lender specialization strategies.
- Debt Consolidation:Borrowers refinance multiple obligations into single installment contracts, reducing total interest burden. Salaried households in the United States concentrate demand as credit card balances accumulate.
- Medical Expenses:Healthcare cost burdens are rebalancing borrower intent away from traditional consolidation. This purpose segment attracts specialized lenders with provider network integrations.
- Home Improvement:Collateral-enhancing expenditures often qualify for secured structures or preferential rates. Green retrofit financing aligns with EU Green Deal disclosure requirements.
- Emergency Funds:Unplanned liquidity needs demand instant disbursement capabilities. Digital-native lenders capture this intent through mobile-first application workflows.
Debt consolidation dominates current origination; medical expense financing is climbing the fastest as healthcare cost pressures intensify.
Approval Channel:
Technology infrastructure and regulatory licensing determine which entities can originate at scale.
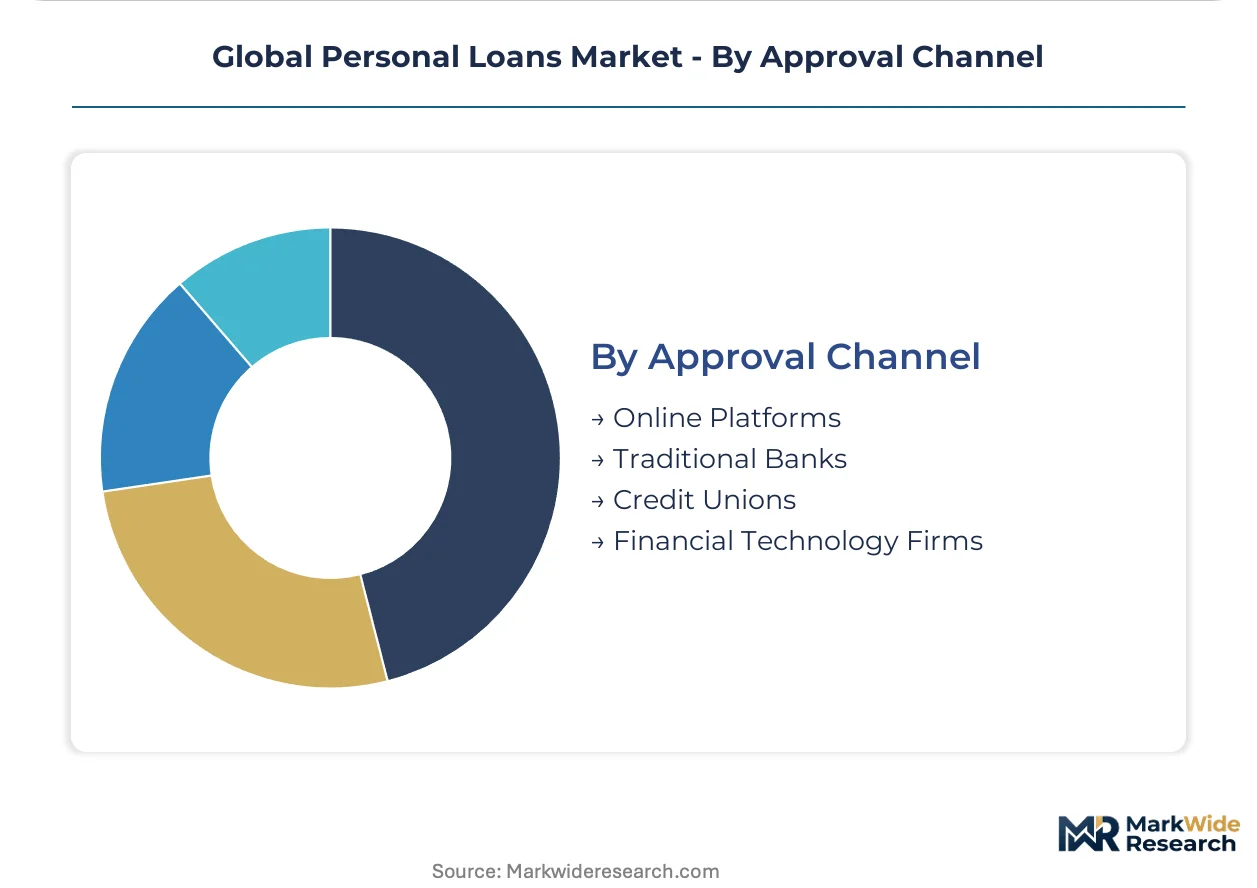
- Online Platforms:API-native architectures enable real-time decisioning and instant disbursement. These channels command dominant approval share as borrower expectations shift toward mobile-first experiences.
- Traditional Banks:Relationship-driven underwriting and branch networks retain margin concentration in jumbo secured products. Legacy core systems constrain transformation timelines for real-time capabilities.
- Credit Unions:Member-owned structures emphasize community-based lending with favorable rate terms. CFPB Section 1033 rulemaking in the United States forces infrastructure investments for data portability compliance.
- Financial Technology Firms:Embedded finance integrations capture borrower intent at point-of-sale moments. Super-app ecosystems in India and Southeast Asia deploy lending within ride-hailing and e-commerce user journeys.
Online platforms lead approval volumes today; financial technology firms are expanding most quickly through embedded distribution partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fintech lending operations toward jurisdictions with streamlined licensing frameworks, as compliance cost differentials between the European Union, United Kingdom, and Asia-Pacific markets reshape capital allocation strategies for cross-border platforms.
United States
Salary-backed debt consolidation and medical expense financing drive origination volumes among middle-income households. The Consumer Financial Protection Bureau enforces Section 1033 data portability mandates that force incumbent banks to share borrower-permissioned transaction histories with competing platforms. Digital lending clusters concentrate in San Francisco and New York, where venture-backed fintechs deploy real-time decisioning engines.
United Kingdom
Peer-to-peer marketplace lending attracts yield-seeking retail investors disillusioned with conventional deposit rates. The Financial Conduct Authority imposes conduct rules and capital requirements that elevate compliance barriers for platform entrants. London anchors European fintech operations, with embedded finance partnerships proliferating across e-commerce checkout integrations.
India
Fintech-bank collaborations target credit-underserved salary earners in tier-2 cities beyond metropolitan footprints. The Reserve Bank of India regulates digital lending through guidelines manduring direct bank- borrower relationships and capping all-in interest costs. Jaipur, Indore, and Kochi emerge as focal points for vernacular-language mobile applications linked to Aadhaar-based e-KYC infrastructure.
Germany
Open banking-enabled income verification compresses underwriting friction for self-employed borrowers with irregular revenue documentation. The Federal Financial Supervisory Authority enforces PSD2 compliance timelines that standardize API access to account transaction data. Berlin hosts challenger bank operations integrating automated credit decisioning into retail banking interfaces.
Singapore
Cross-border remittance-linked lending products serve migrant worker populations with predictable salary flows. The Monetary Authority of Singapore licenses digital banks under frameworks permitting restricted deposit-taking and unsecured consumer credit origination. The city-state functions as Southeast Asian headquarters for regional expansion into Indonesia, Vietnam, and Philippines markets.
Global Personal Loans Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with technology-integrated platforms capturing borrower acquisition while legacy banks retain balance-sheet concentration in relationship-driven underwriting. Market structure tilts toward fragmentation as regulatory licensing requirements prevent seamless cross-border passporting. Three archetypes dominate: API-native fintechs deploying alternative data scoring, incumbent banks retrofitting legacy cores for real-time decisioning, and peer-to-peer marketplaces connecting retail capital directly to consumer obligations. Competitive moves center on strategic partnerships embedding lending at point-of-sale moments and vertical integration into payroll-integrated repayment infrastructure.
Among United States-based technology lenders, SoFi Technologies, LendingClub Corp., and Upstart Network Inc. exemplify divergent strategic positioning within the unsecured consumer credit segment. SoFi anchors graduate refinancing and adjacent product expansion through technology stack leverage. LendingClub occupies marketplace efficiency positioning, connecting institutional capital pools directly to prime borrower segments. Upstart represents AI-powered underwriting extension, deploying machine learning models that expand credit access beyond traditional FICO boundaries. Each entity sits within distinct competitive tiers—integrated full-stack banking, capital-light marketplace, and algorithmic risk innovation—reflecting heterogeneous bets on borrower acquisition economics and model governance requirements.
| Leading Market Players |
|---|
| American Express Co. |
| SoFi Technologies Inc. |
| LendingClub Corp. |
| Citigroup Inc. |
| Avant LLC |
| Prosper Marketplace Inc. |
| Upstart Network Inc. |
| Funding Circle Holdings Plc |
| Wells Fargo |
| Others |
Value Chain & Pricing Dynamics
Borrower migration toward instant disbursement and mobile-first servicing is forcing originators to restructure cost bases and compress acquisition economics, which in turn narrows margin tolerance and intensifies rate competition across digital channels.
Pricing Analysis
Direct-to-borrower digital platforms command the dominant channel-margin layer, bypassing intermediary markups that inflate rates at branch-based originators. Three-tier pricing structure across prime, near-prime, and subprime risk bands reflects FICO-equivalent scoring thresholds and alternative data validation depth. Pricing pressure stems from fintech-funded customer acquisition subsidies and deposit-cost volatility at regional banks. Salary earners with payroll-integrated verification show lowest price sensitivity; thin-file first-time borrowers face widest rate dispersion due to risk-premium uncertainty.
Supply Chain Analysis
Workforce availability for algorithmic underwriting engineers concentrates in San Francisco, New York, and Bangalore, creating talent bottlenecks that delay model deployment timelines. Capital provision draws from institutional investors in the United States, retail deposit bases in Germany, and marketplace funders in the United Kingdom. Single-source vulnerability sits with cloud infrastructure providers hosting real-time decisioning engines. Distribution runs through API-native platforms, embedded finance partnerships, and legacy branch networks in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with borrower preference shifting toward premium-grade automated underwriting and instant fulfillment capabilities that reward technology-differentiated originators.
For Market Incumbents: Deepen API infrastructure investment to defend against embedded-finance disintermediation at point-of-sale moments. Acquire alternative data scoring capabilities to match fintech approval velocity. Prioritize payroll-integrated repayment partnerships that reduce default probability through automated collection infrastructure. For New Entrants and Emerging Players: Self-employed borrowers with irregular documentation represent the most penetrable white-space segment as open banking mandates compress verification friction. Target tier-2 Indian cities beyond metro footprints where vernacular-language interfaces and Aadhaar-linked e-KYC remain underdeployed. Pursue climate-linked product positioning to attract institutional ESG capital seeking green home improvement exposure. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithmic underwriting specialists possessing explainable AI frameworks compliant with emerging EU AI Act provisions. Long-term viability favors platforms with diversified funding sources beyond single retail depositor bases. Watch for regulatory clarity on alternative data permissibility as the primary inflection indicator for model expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Data Scoring Investment | Expands addressable population beyond FICO-reliant models into thin-file segments. |
| Embedded Finance Partnership | Captures borrower intent at e-commerce checkout through API-integrated lending. |
| Payroll-Integrated Repayment Infrastructure | Reduces default probability via employer-sponsored salary deduction mechanisms. |
| Open Banking API Compliance | Enables real-time income verification for self-employed borrowers under PSD2 mandates. |
| Climate-Linked Product Development | Aligns with EU Green Deal disclosure requirements to attract ESG-focused institutional capital. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with chief risk officers at digital lending platforms, heads of consumer banking at regional institutions, fintech partnership leads at Indian banks, and regulatory compliance directors at cross-border operators. Secondary validation drew from CFPB disclosure filings, ECB statistical reports, RBI digital lending guidelines, and marketplace platform prospectuses. Bottom-up origination volume estimates triangulated against top-down credit bureau aggregates.
Segment-weighting approaches distributed value and volume across loan type, borrower profile, approval channel, and geographic regulatory cluster dimensions. CAGRs derived from fitted growth curves calibrated to historical origination trajectories and forward-looking policy rate assumptions. Model inputs incorporated open banking penetration rates, alternative data regulatory permissibility indices, and deposit funding cost movements.
Underlying measurement precision varies by segment; salary-earner unsecured products carry tighter precision than self-employed thin-file categories due to documentation standardization. Forecasts reflect assumptions around central bank policy trajectories, regulatory enforcement intensity on AI explainability, and fintech-bank partnership durability. Material deviation in PSD2 compliance timelines or CFPB Section 1033 implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Household Finances Market