
 Debt Settlement Market | 2026-2036
Debt Settlement Market Size, Share, and Industry Trends Forecast 2026-2036
Debt Settlement Market Insights
Individual debtor demand is expanding across fragmented income brackets as inflation pressures push middle-income households toward professional debt relief. Freedom Debt Relief leverages technology-driven enrollment platforms to sustain volume leadership in unsecured debt negotiation. National Debt Relief anchors its position through attorney-backed settlement protocols that differentiate service credibility. Pacific Debt Relief specializes in hardship-based creditor negotiations, competing on fee transparency rather than scale.
Debt settlement encompasses negotiated reduction of unsecured obligations through third-party intermediaries who consolidate accounts and broker lump-sum payoffs, typically charging fees of 15-25% of enrolled debt after successful resolution. The process involves escrow account management, creditor communication cessation, and strategic default timing to maximize discount rates on principal balances. Credit card debt dominates service type volume given its prevalence and negotiability, while medical debt represents the fastest-growing segment as healthcare cost burdens outpace wage growth. Online platforms now lead distribution channel growth by reducing customer acquisition costs and enabling real-time progress tracking.
The Consumer Financial Protection Bureau enforces fee-timing restrictions under Telemarketing Sales Rule amendments, while state attorneys general in California and New York impose licensing and disclosure mandates that shape operational compliance costs. The Federal Trade Commission's advance-fee ban fundamentally structures provider revenue models around performance-based compensation. Stakeholders must monitor evolving state-level fee caps and the integration of artificial intelligence into creditor scoring algorithms that could alter negotiation leverage dynamics.
Market Dynamics
The Consumer Financial Protection Bureau's fee-timing enforcement is compressing provider margins and forcing operational restructuring across the debt settlement industry. Providers must reengineer revenue recognition around performance-based compensation models while maintaining enrollment volumes.
Growth Catalysts
- Telemarketing Sales Rule amendments:The FTC's advance-fee ban is filtering out predatory operators and consolidating legitimate provider market presence.
- Healthcare cost inflation:Medical debt burdens are expanding the addressable population seeking professional negotiation services.
- Credit card utilization:Rising revolving balances among middle-income households are sustaining demand for unsecured debt relief programs.
Market Restraints
- State licensing fragmentation:California and New York impose divergent disclosure mandates that multiply compliance overhead.
- Credit score damage:Strategic default requirements deter risk-averse debtors from enrolling in settlement programs.
- Attorney network concentration:Credible legal backing concentrates in metropolitan markets, limiting rural service penetration.
Strategic Opportunities
- Artificial intelligence integration:Machine learning creditor scoring algorithms are creating negotiation leverage advantages for early adopters.
- Hardship-based specialization:Documented financial distress protocols open underserved segments resistant to traditional enrollment.
- Real-time tracking platforms:Digital escrow transparency is reducing customer acquisition costs and improving retention metrics.
Industry Challenges
- Compliance talent scarcity:Regulatory interpretation expertise commands premium compensation in a thin labor pool.
- Legacy system integration:Escrow management platforms require costly reconfiguration to meet state audit standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Debt Settlement Market |
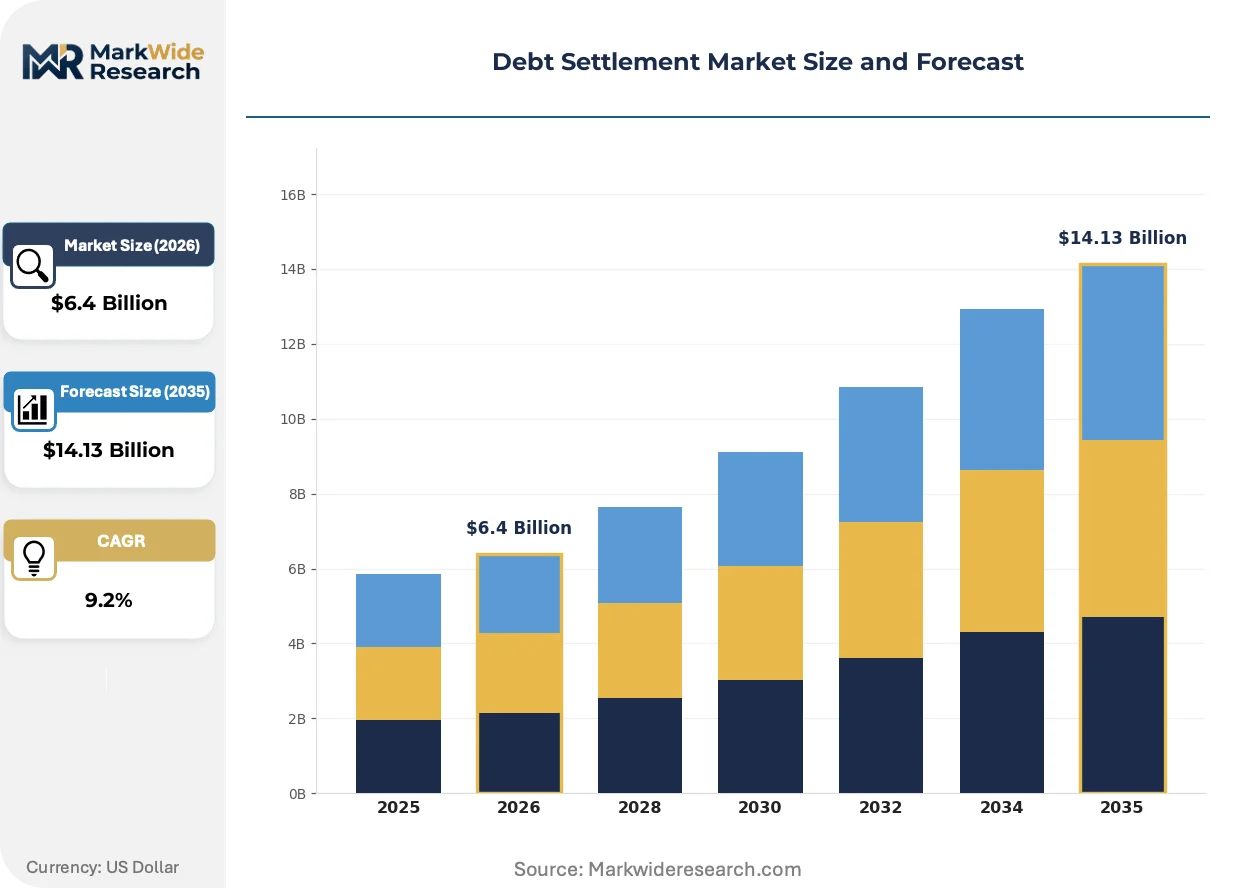
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $14.13 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Negotiation Services, Repayment Plans, Financial Counseling, Legal Assistance Customer Type: Individual Debtors, Small Enterprises, Freelancers, Non-Profit Organizations Debt Type: Credit Card Debt, Medical Debt, Personal Loans, Student Loans, Utility Bills Distribution Channel: Online Platforms, Call Centers, Financial Advisors, Retail Branches |
| Companies Covered | Pacific Debt Relief, InCharge Debt Solutions, Freedom Debt Relief, Century Support Services, New Era Debt Solutions, National Debt Relief, CuraDebt, Americor Debt Relief, Accredited Debt Relief, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debt Settlement Market Trends and Innovations
Technology deployment is restructuring how providers acquire, enroll, and retain debtors while regulatory pressure accelerates consolidation among compliant operators.
Artificial intelligence-driven creditor behavior prediction is electrifying settlement strategy formulation. Mid-sized providers are adopting these tools fastest to compete with volume leaders. The technology is compressing negotiation timelines and improving lump-sum discount capture rates.
The Consumer Financial Protection Bureau's enforcement actions against misleading fee practices are mandating plain-language disclosure redesign. Providers must restructure marketing materials and sales scripts to avoid civil penalty exposure. Digital-first enrollment platforms are responding fastest by embedding compliance checkpoints into automated workflows.
Debtor preference for self-service transparency is displacing phone-heavy enrollment models. Online escrow dashboards and mobile progress tracking are replacing traditional account manager relationships. This shift is most visible among tech-comfortable households aged 35-50 seeking medical debt resolution.
Debt Settlement Market Segmentation
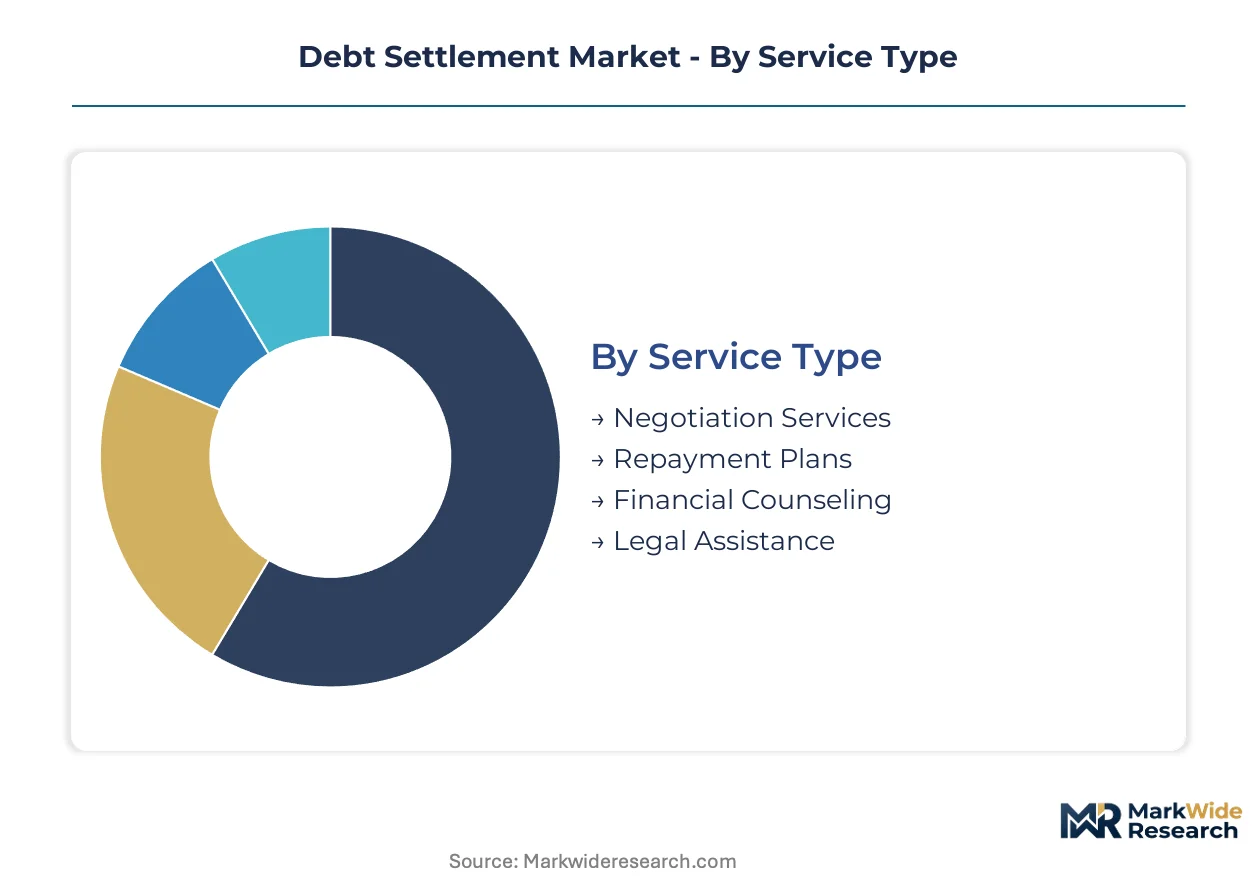
Debt settlement providers configure service architectures around distinct debtor profiles and obligation types. Each segmentation dimension shapes pricing models, compliance requirements, and customer acquisition strategies differently.
Service Type:
Upgrade cycles in service delivery technology are compressing legacy phone-based models into integrated digital platforms.
- Negotiation Services:Direct creditor bargaining for lump-sum balance reductions, typically 40-60% of principal. Demand clusters among credit card debtors in high-cost metropolitan areas where attorney-backed protocols command premium fees.
- Repayment Plans:Structured installment schedules negotiated with reduced interest or principal. Small enterprises in California and New York drive volume where state licensing mandates require documented hardship verification.
- Financial Counseling:Budget restructuring and creditor communication management. Freelancers seeking medical debt resolution favor this entry-level service tier.
- Legal Assistance:Attorney representation for litigation threats and judgment defense. Non-profit organizations utilize this segment for member protection programs.
Volume placements concentrate in Negotiation Services; the faster expansion belongs to Financial Counseling as digital self-service tools reduce acquisition costs.
Customer Type:
Cost tier differentiation separates high-touch enterprise accounts from automated individual debtor workflows.
- Individual Debtors:Households with $10,000-$100,000 in unsecured obligations seeking principal reduction. Medical debt burdens among middle-income households in Texas and Florida sustain the largest addressable population.
- Small Enterprises:Businesses with vendor debt and equipment financing requiring structured resolution. Commercial negotiation protocols demand higher fee percentages due to complex creditor hierarchies.
- Freelancers:Independent contractors with irregular income streams and tax-adjacent obligations. Hardship documentation requirements favor platforms with automated bank statement analysis.
- Non-Profit Organizations:Mission-driven entities managing operational debt while preserving donor-facing credibility. Grant-dependent cash flows necessitate specialized escrow timing.
Individual Debtors dominate current enrollment; Small Enterprises are climbing the fastest as post-pandemic business debt matures into settlement-eligible status.
Debt Type:
Application-specific negotiation tactics vary dramatically across obligation categories based on creditor sophistication and legal enforceability.
- Credit Card Debt:Revolving unsecured balances with established charge-off timelines and standardized settlement protocols. Issuer concentration among national banks enables predictable discount modeling.
- Medical Debt:Healthcare provider obligations with charity care eligibility overlays and credit reporting restrictions. Hospital system consolidation in Ohio and Pennsylvania creates regional negotiation leverage variations.
- Personal Loans:Fixed-term unsecured credit from fintech lenders and credit unions. Originator diversity fragments settlement standardization.
- Student Loans:Federally backed and private education debt with limited settlement permissibility. Income-driven repayment alternatives constrain professional service penetration.
- Utility Bills:Municipal and private service arrears with disconnection leverage asymmetry. State public utility commission oversight shapes negotiation boundaries.
Credit Card Debt maintains the steepest enrollment volume; Medical Debt is gaining share fastest as healthcare cost inflation outpaces wage growth.
Distribution Channel:
Customer acquisition economics favor digital channels where real-time progress transparency reduces churn.
- Online Platforms:Self-service enrollment with AI-driven qualification scoring and escrow dashboards. Tech-comfortable debtors aged 35-50 in suburban markets prefer this channel.
- Call Centers:Agent-assisted sales with scripted compliance checkpoints. Higher conversion rates accompany elevated customer acquisition costs.
- Financial Advisors:Referral-based placement through certified financial planner networks. Trust transfer from fiduciary relationships improves retention metrics.
- Retail Branches:Physical presence for document notarization and cash escrow deposits. Rural penetration depends on this channel where digital literacy gaps persist.
Online Platforms capture the majority of new enrollments; Financial Advisors show the fastest channel expansion as fiduciary referral networks formalize debt settlement partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household debt-to-income ratios in the United States concentrate the largest share of professional debt settlement demand. Credit card utilization and medical cost inflation sustain enrollment volumes across metropolitan markets.
United States
The Consumer Financial Protection Bureau enforces fee-timing restrictions under Telemarketing Sales Rule amendments. State attorneys general in California and New York impose divergent licensing mandates that multiply compliance overhead. Miami and Houston anchor medical debt enrollment clusters where hospital system consolidation creates regional negotiation leverage variations.
Canada
Provincial insolvency regulations and consumer proposal alternatives shape debt relief service architectures differently across Ontario and British Columbia. The Office of the Superintendent of Bankruptcy oversees licensed insolvency trustee networks that intersect with settlement providers. Toronto concentrates fintech-enabled enrollment platform development.
United Kingdom
Individual Voluntary Arrangements and Debt Relief Orders provide statutory alternatives that constrain pure settlement service penetration. The Financial Conduct Authority regulates debt advice and insolvency practitioners through permission-based authorization frameworks. London hosts credit counseling charity headquarters that influence service standard development.
Australia
Part IX debt agreements under the Bankruptcy Act structure formal alternatives to commercial settlement negotiation. The Australian Financial Security Authority administers personal insolvency regulatory frameworks. Sydney and Melbourne concentrate licensed debt agreement administrator operations.
Germany
Consumer insolvency proceedings with residual debt discharge after six years limit demand for third-party settlement intermediation. The Federal Financial Supervisory Authority exercises indirect oversight through credit industry conduct standards. Frankfurt hosts consumer credit counseling association coordination.
Debt Settlement Market Competitive Landscape
Established providers occupy the standard tier; emerging entrants pursue digital-first enrollment automation and AI-driven creditor scoring. The market structure concentrates around three operational archetypes: volume-scaled negotiators with technology-heavy acquisition platforms, attorney-backed specialists competing on settlement credibility, and hardship-focused boutiques emphasizing fee transparency. Consolidation pressure from compliance cost inflation favors acquisition activity among mid-sized operators. Strategic differentiation centers on escrow technology investment and state licensing coverage expansion.
Among technology-scaled negotiators, Freedom Debt Relief and National Debt Relief exemplify divergent positioning within the volume tier. Pacific Debt Relief occupies a position within the hardship-specialist archetype. These three entities anchor the competitive spectrum from mass-market automation to documented-distress protocol specialization.
| Leading Market Players |
|---|
| Pacific Debt Relief |
| InCharge Debt Solutions |
| Freedom Debt Relief |
| Century Support Services |
| New Era Debt Solutions |
| National Debt Relief |
| CuraDebt |
| Americor Debt Relief |
| Accredited Debt Relief |
| Others |
Pricing and Supply Chain Analysis
Attorney-backed premium protocols diverge sharply from automated volume services, with the former commanding elevated fee percentages through licensed legal coverage while the latter compress margins through technology-driven customer acquisition economies. This bifurcation manifests in supply chain configurations where premium-tier providers anchor escrow management through specialized legal networks in California and New York, whereas mass-market operators source technology infrastructure from cloud-based platform vendors to minimize fixed-cost exposure.
Pricing Analysis
Volume-scaled negotiators sacrifice margin percentage for enrollment throughput, while hardship-specialist boutiques preserve elevated fee structures through documented-distress certification requirements. Three-tier pricing structure across premium attorney-backed, standard technology-enabled, and economy self-service levels differentiates based on creditor communication protocols and escrow transparency depth. Pricing pressure stems from the FTC's advance-fee ban forcing performance-based compensation reconfiguration. Small enterprises with complex creditor hierarchies exhibit lowest price sensitivity; individual debtors facing medical burdens in Texas and Florida show highest sensitivity to upfront cost transparency.
Supply Chain Analysis
Reverse-logistics flows of returned settlement funds and failed-negotiation escrow reversals concentrate operational complexity in provider back-office functions across the United States, Canada, and United Kingdom. Technology infrastructure draws from domestic cloud services, licensed attorney networks, and specialized compliance software vendors. Single-source vulnerability concentrates in attorney-network availability for litigation-threat protocols. Distribution runs through direct-to-consumer digital platforms, call center agent networks, and certified financial planner referral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where custody of escrow technology and attorney-network relationships determines competitive durability. Players are pursuing downstream control over debtor-facing digital platforms to lock in enrollment volumes and reduce customer acquisition cost leakage.
For Market Incumbents: Lock in attorney-network exclusivity in high-enrollment metropolitan markets to defend against technology-enabled entrants. Consolidate mid-sized operators facing compliance cost inflation to expand state licensing coverage. Escrow technology vendors represent a substitute threat requiring proprietary platform investment or long-term supply agreements.
For New Entrants and Emerging Players: AI-driven qualification scoring platforms offer the lowest-friction entry vector for capturing tech-comfortable debtors aged 35-50. Freelancers with irregular income streams and automated bank statement analysis needs represent the most penetrable white-space segment. Pursue hardship-based specialization with fee-transparency positioning to differentiate from volume-scaled incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by technology-scaled volume leaders seeking attorney-network augmentation. Long-term viability hinges on regulatory compliance infrastructure that survives CFPB enforcement evolution. Watch for state-level fee cap legislation as the inflection signal determining margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Attorney Network Expansion | Licensed legal coverage in California and New York commands premium fee positioning. |
| AI-Driven Creditor Scoring | Machine learning algorithms compress negotiation timelines and improve discount capture rates. |
| Digital Escrow Platform Development | Real-time transparency reduces customer acquisition costs and improves retention metrics. |
| State Licensing Coverage Extension | Multi-jurisdiction compliance capability filters predatory competitors and consolidates market presence. |
| Hardship Documentation Automation | Automated bank statement analysis opens underserved segments resistant to traditional enrollment. |
Research Methodology
SEC filings, CFPB enforcement action databases, and state attorney general disclosure records formed the secondary backbone, cross-referenced with primary interviews with debt settlement operations executives, licensed attorney network coordinators, compliance officers, and certified financial planner referral partners. Bottom-up enrollment volume analysis from provider disclosures combined with top-down household debt burden estimates from Federal Reserve and Bureau of Labor Statistics sources enabled triangulation across data approaches.
Historical trendline analysis of enrollment volumes and fee realization rates informed the projection framework across the analysis window. Segmentation dimensions modeled include service type architecture, customer profile tiering, debt category negotiability, and distribution channel economics. CAGRs derived from regression analysis of enrollment growth against household debt-to-income ratio movements and healthcare cost inflation trajectories. Artificial intelligence adoption curves and state regulatory filing volumes served as industry-specific forecast inputs.
The model holds under stable CFPB enforcement intensity and continued healthcare cost inflation; deviation in federal fee-timing rule amendments or state-level fee cap legislation would shift trajectory. Practitioners should monitor state attorney general licensing mandate evolution and AI creditor-scoring algorithm adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Household Finances Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market