
 Global Personal Finance Tools and Market | 2026-2036
Global Personal Finance Tools and Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Finance Tools and Market Insights
Southeast Asia's fintech corridor is rewriting how personal finance tools reach first-time digital banking users. Intuit Inc. leverages its TurboTax and Mint ecosystem to anchor North American household financial management. Quicken Inc. sustains loyalty among desktop-native users migrating gradually to cloud interfaces. Revolut Ltd. competes aggressively on multi-currency budgeting features across European and Asia-Pacific urban centers.
Personal finance tools encompass software applications and digital platforms that aggregate bank feeds, categorize transactions, project cash flows, and automate savings allocations through API-connected data pipelines. These systems serve commercial purposes by reducing cognitive load in financial decision-making and improving household liquidity management for individuals and micro-enterprises. Budgeting apps and expense trackers command the largest user bases, while investment platforms capture disproportionate revenue per subscriber through advisory fee structures. Cloud-based solutions and mobile applications are displacing desktop software as the dominant delivery model, though hybrid platforms retain traction among privacy-sensitive segments.
The US Consumer Financial Protection Bureau shapes disclosure requirements for automated financial advice tools, while the EU's GDPR and PSD2 frameworks mandate granular consent protocols for open banking data flows. Japan's FSA and METI coordinate on fintech sandbox approvals that determine market entry timelines for foreign platform providers. Stakeholders must monitor evolving data localization mandates and interoperability standards as these will determine which delivery models achieve regulatory clearance in priority jurisdictions.
Market Dynamics
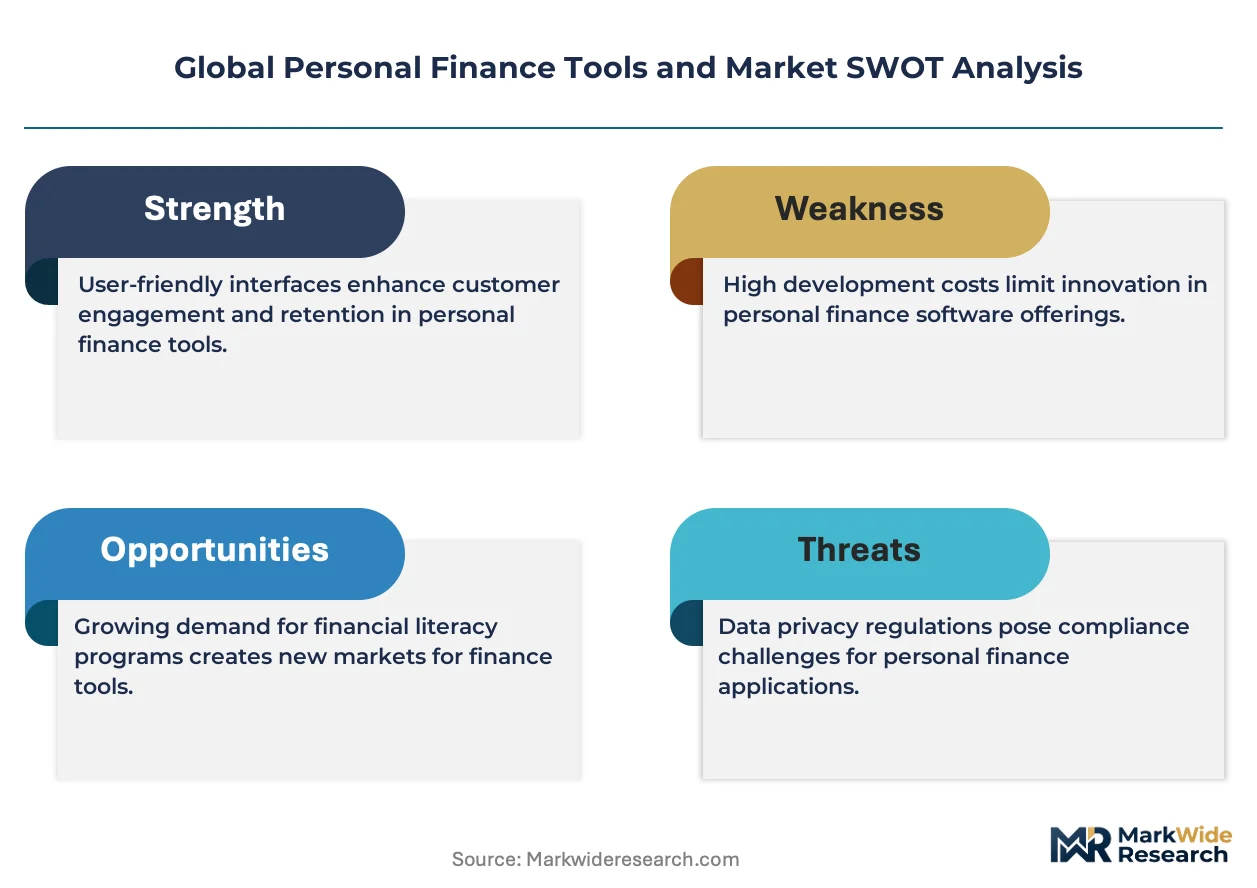
Open banking mandates and API standardization are compressing data access costs and forcing platform business models toward freemium-to-advisory revenue stacks. This structural shift rewards aggregators with direct bank integrations while marginalizing screen-scraping intermediaries.
Growth Catalysts
- PSD2 Data-Sharing Mandates:European regulators force incumbent banks to expose standardized APIs, lowering entry barriers for third-party budgeting platforms and accelerating feature parity between neobanks and standalone apps.
- Embedded Finance Integration:E-commerce and gig-economy platforms in Southeast Asia embed savings nudges and micro-investment triggers directly at transaction points, converting casual users into active wealth builders.
- Real-Time Payment Rails:FedNow in the United States and similar instant settlement systems in Brazil and India enable cash-flow forecasting with sub-hour granularity, unlocking subscription pricing for liquidity management tools.
Market Restraints
- Data Localization Requirements:India's RBI and Saudi Arabia's SAMR mandate domestic server placement for financial data, fragmenting cloud infrastructure economics and raising compliance overhead for cross-border platforms.
- Screen-Scraping Dependency:Markets without mature open banking frameworks rely on brittle credential-sharing protocols, creating service disruption risk and liability exposure when banks change authentication flows.
- Advisory Licensing Friction:Securities regulators in Germany, Australia, and Canada impose fiduciary standards on automated investment recommendations, extending go-to-market timelines for hybrid robo-advisory features.
Strategic Opportunities
- Micro-Enterprise Cash Management:Sole proprietors and unincorporated gig workers in Mexico and Indonesia lack tailored tools, presenting white space between consumer budgeting and full small-business accounting suites.
- Carbon-Linked Spending Analytics:EU CSRD disclosure requirements and consumer preference shifts in Scandinavia create demand for transaction-level emissions tracking integrated with everyday expense categorization.
- Voice-First Interfaces:Smart speaker penetration in South Korean and US households enables hands-free balance inquiries and savings transfers, opening distribution channels beyond smartphone app stores.
Industry Challenges
- AI Model Explainability:Regulators in the European Union under the AI Act demand transparent logic for creditworthiness and spending recommendations, complicating black-box machine learning deployments.
- Legacy Core Banking Integration:Regional banks in Japan and Italy operate on decades-old COBOL architectures, forcing fintech partners to maintain expensive middleware layers for data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Finance Tools and Market |
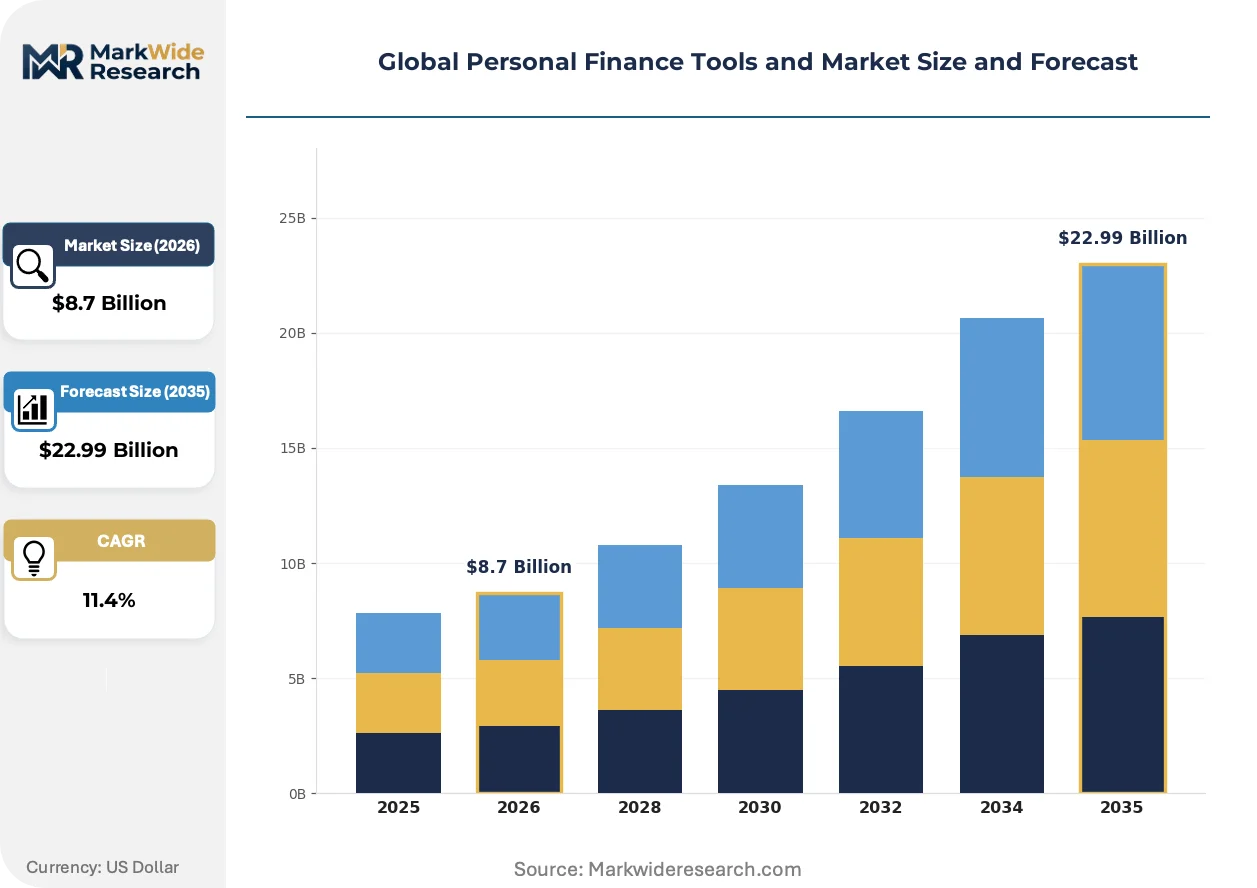
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Budgeting Apps, Investment Platforms, Expense Trackers, Savings Tools End User: Individuals, Small Business Owners, Students, Households Service Type: Financial Advisory, Wealth Management, Tax Services, Credit Counseling Delivery Model: Cloud-Based Solutions, Mobile Applications, Desktop Software, Hybrid Platforms |
| Companies Covered | Intuit Inc., Quicken Inc., PayPal Holdings Inc., Revolut Ltd., You Need A Budget LLC, The Infinite Kind, Buxfer Inc., Moneyspire Inc., PocketSmith Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Finance Tools and Market Trends and Innovations
Generative interfaces and predictive cash-flow engines are compressing the cognitive load of financial decision-making, shifting competitive advantage from data aggregation toward actionable foresight.
Embedded large language models are collapsing the interface complexity of budgeting software. Young professionals in the United States and United Kingdom interact with natural-language queries rather than static dashboards. This compression eliminates menu hierarchies and reduces onboarding friction for first-time users.
The EU AI Act's risk classification framework imposes documentation burdens on automated financial advice tools. Providers must maintain technical files and human oversight protocols for high-risk algorithmic systems. German and French regulators are already requesting conformity assessments from robo-advisory platforms ahead of full enforcement.
Subscription fatigue among millennials is fragmenting willingness to pay for standalone budgeting apps. Users in Canada and Australia increasingly expect financial wellness features bundled within primary banking relationships. Neobanks capture this demand by integrating savings automation and spending insights without separate login credentials.
Global Personal Finance Tools and Market Segmentation
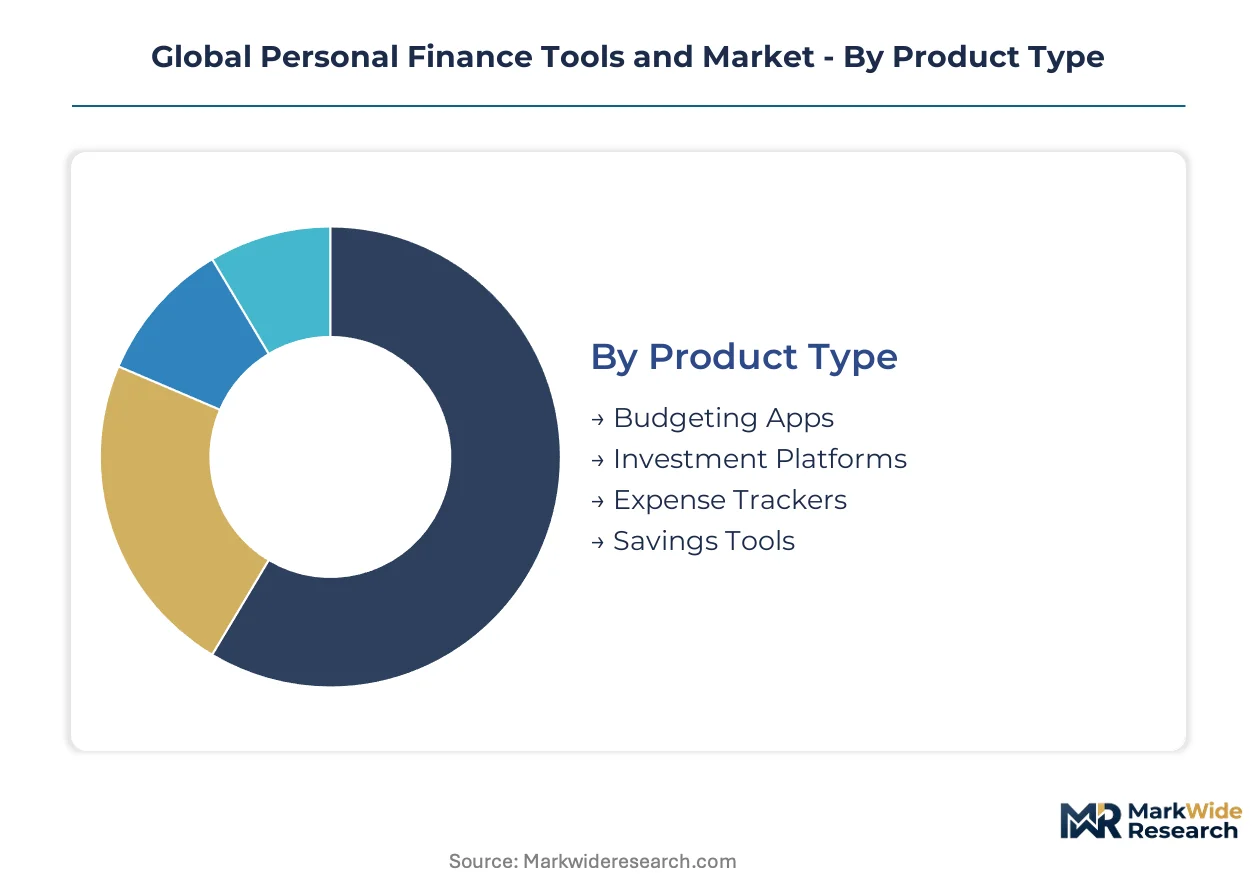
Personal finance tools fragment across four distinct category systems, each mapping to different monetization velocities and user retention profiles. Product type and delivery model cycles run shortest, while service type relationships extend across years. Understanding these turnover differentials clarifies where platform investments compound fastest.
Product Type:
Budgeting apps refresh user interfaces quarterly to sustain engagement, while investment platforms lock subscribers through portfolio migration costs. Savings tools turn over slowest as behavioral habits cement. Expense trackers sit in the middle, with seasonal spikes around tax periods driving replacement decisions.
- Budgeting Apps:Transaction aggregation engines with automated categorization and spend-limit alerts. Demand concentrates among young professionals in the United States and United Kingdom where subscription fatigue pressures freemium conversion rates.
- Investment Platforms:Robo-advisory interfaces with portfolio rebalancing and tax-loss harvesting automation. German and Australian regulators impose fiduciary licensing requirements that extend go-to-market timelines for algorithmic recommendation features.
- Expense Trackers:Receipt capture and merchant-level spend analysis tools targeting gig workers and freelancers. Brazil and India drive volume through real-time payment rail integration.
- Savings Tools:Round-up mechanisms and goal-based allocation systems. Scandinavian markets show accelerating demand for carbon-linked spending analytics embedded within savings nudges.
Budgeting apps anchor the volume base while investment platforms gain share at the steepest rate.
End User:
Customer lifetime value spreads widest across this dimension, with small business owners generating multiple revenue streams per account and students converting poorly to paid tiers. Individual users fragment into subsegments based on wealth tier and financial sophistication.
- Individuals:Retail consumers managing personal cash flows through bank-aggregated dashboards. United States and Canadian users increasingly expect financial wellness features bundled within primary banking relationships rather than standalone subscriptions.
- Small Business Owners:Sole proprietors and unincorporated gig workers requiring micro-enterprise cash management capabilities. Mexico and Indonesia present white space between consumer budgeting and full accounting suites.
- Students:First-time digital banking users with limited transaction histories and high price sensitivity. Southeast Asian fintech corridors target this cohort through embedded finance integration at educational payment points.
- Households:Multi-user financial management with shared goal-setting and consolidated net worth tracking. South Korean and United States smart speaker penetration enables voice-first balance inquiries and savings transfers.
Individuals generate the largest addressable base while small business owners deliver the highest revenue per subscriber.
Service Type:
Regulatory burden scales sharply upward through this category, with credit counseling requiring licensing in most jurisdictions and tax services facing seasonal capacity constraints. Wealth management commands premium pricing but faces fiduciary standard enforcement.
- Financial Advisory:Automated or hybrid human-algorithm guidance on allocation and product selection. EU AI Act documentation requirements impose technical file maintenance and human oversight protocols on providers.
- Wealth Management:Holistic portfolio construction across asset classes with rebalancing and drawdown strategies. Swiss and Singapore private banking hubs influence feature roadmaps for platform providers.
- Tax Services:Liability estimation, deduction optimization, and filing preparation workflows. United States CFPB disclosure requirements shape automated advice tool transparency standards.
- Credit Counseling:Debt restructuring guidance and repayment plan negotiation support. India's RBI data localization mandates fragment cloud infrastructure economics for cross-border counseling platforms.
Tax services capture peak seasonal engagement while wealth management extends customer lifetime value furthest.
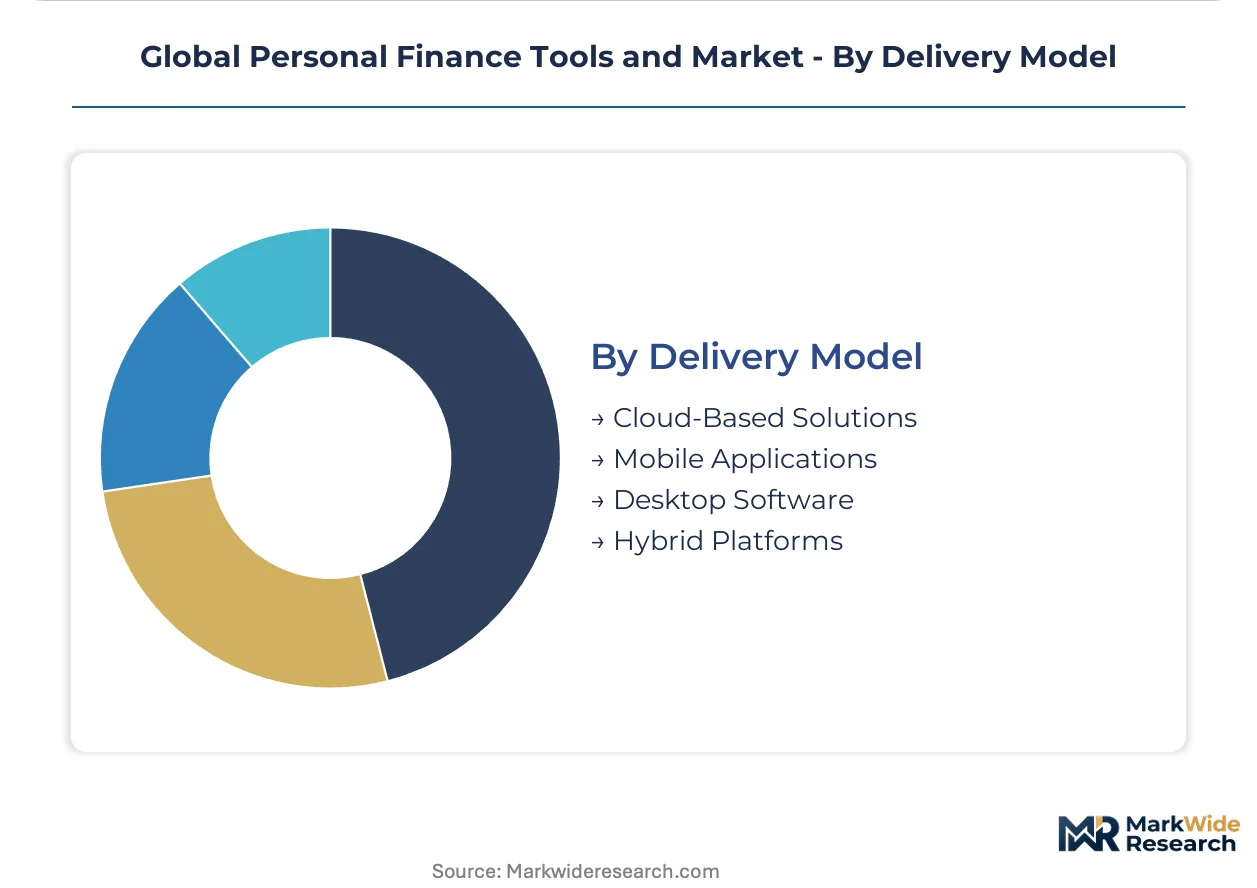
Delivery Model:
Infrastructure economics diverge dramatically here, with cloud-native platforms achieving marginal cost near zero and hybrid systems carrying privacy-sensitive premium pricing. Desktop software retention correlates with age demographics.
- Cloud-Based Solutions:Browser-accessible platforms with real-time synchronization across devices. Japan and Italy's legacy COBOL banking architectures force expensive middleware layers for data synchronization.
- Mobile Applications:Smartphone-native interfaces with biometric authentication and push notification engagement. Southeast Asian e-commerce and gig-economy platforms embed savings triggers directly at transaction points.
- Desktop Software:Locally installed applications with offline functionality and manual import capabilities. Privacy-sensitive segments in Germany and Switzerland sustain demand despite cloud migration pressure.
- Hybrid Platforms:Dual deployment allowing cloud sync with local data custody options. Saudi Arabia's SAMR domestic server requirements raise compliance overhead for cross-border hybrid providers.
Mobile applications command the steepest user acquisition growth while hybrid platforms defend margin through privacy differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure providers cluster disproportionately in the United States and Western Europe, while user acquisition engines concentrate in high-mobile-penetration Asian markets. Regulatory fragmentation around data localization and open banking mandates forces platform operators to maintain jurisdiction-specific deployment stacks.
United States
Millennial and Gen Z consumers drive fintech penetration through embedded banking relationships rather than standalone subscriptions. The Consumer Financial Protection Bureau shapes disclosure requirements for automated financial advice tools. Silicon Valley and New York Metro host the dominant cloud infrastructure clusters serving North American household financial management platforms.
Germany
Privacy-sensitive segments sustain demand for hybrid deployment models with local data custody options. BaFin and the Federal Financial Supervisory Authority impose fiduciary licensing requirements on algorithmic investment recommendations. Frankfurt's financial services cluster anchors compliance-heavy wealth management feature development for EU market entry.
United Kingdom
Open banking APIs under PSD2 lower entry barriers for third-party budgeting platforms and accelerate feature parity. The Financial Conduct Authority mandates granular consent protocols for data-sharing infrastructure. London's fintech corridor concentrates neobank innovation targeting multi-currency budgeting across European urban centers.
Japan
Legacy COBOL banking architectures force fintech partners to maintain expensive middleware layers for data synchronization. METI and the Financial Services Agency coordinate on sandbox approvals that determine market entry timelines for foreign platform providers. Tokyo's metropolitan area anchors smart speaker penetration enabling voice-first balance inquiries.
India
First-time digital banking users in Southeast Asian fintech corridors adopt tools through embedded finance at transaction points. The Reserve Bank of India mandates domestic server placement for financial data, fragmenting cloud infrastructure economics. Mumbai and Bangalore concentrate real-time payment rail integration development for cash-flow forecasting tools.
Global Personal Finance Tools and Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying API infrastructure and categorization engines. The vendor base separates into consolidated banking-integrated platforms and fragmented standalone budgeting applications. Three archetypes dominate: full-stack neobanks with embedded financial wellness, pure-play aggregators with direct bank connections, and legacy desktop software vendors migrating to cloud interfaces. Competitive moves concentrate on M&A for bank API access and strategic partnerships with real-time payment rail operators.
Among North American platform providers, Intuit Inc. and Quicken Inc. occupy positions spanning tax preparation through household budgeting, while Revolut Ltd. exemplifies the multi-currency neobank archetype competing across European and Asia-Pacific urban centers. These three entities represent contrasting strategic postures: ecosystem bundling, desktop-to-cloud migration, and geographic expansion through regulatory arbitrage.
| Leading Market Players |
|---|
| Intuit Inc. |
| Quicken Inc. |
| PayPal Holdings Inc. |
| Revolut Ltd. |
| You Need A Budget LLC |
| The Infinite Kind |
| Buxfer Inc. |
| Moneyspire Inc. |
| PocketSmith Ltd. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cloud infrastructure providers in the United States and Western Europe determines both tiered pricing spreads and supply chain resilience for personal finance platforms. Regulatory chokepoints around India's RBI data localization mandates and Saudi Arabia's SAMR domestic server requirements fragment cloud economics and force jurisdiction-specific deployment stacks that widen price differentiation between compliant and non-compliant service tiers.
Pricing Analysis
GDPR and PSD2 consent protocols dictate the pricing tier structure for personal finance tools across European markets. Three-tier pricing structure across premium, standard, and economy levels separates white-glove wealth management interfaces from basic budgeting aggregators and freemium entry points. Price differentiation rests on advisory licensing depth and real-time payment rail integration sophistication. Cost compression in the standard tier is intensifying because neobanks bundle financial wellness features without separate subscription fees. Students and first-time digital banking users in Southeast Asia exhibit the highest price sensitivity, while small business owners in Mexico and Indonesia accept premium pricing for micro-enterprise cash management capabilities.
Supply Chain Analysis
Export-control restrictions on AI training hardware and encryption technologies limit flows of advanced analytics components to certain jurisdictions. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, while API middleware development clusters in India and Poland. Raw material dependencies include specialized data center semiconductors, biometric authentication modules, and open banking protocol licenses. Single-source vulnerability around legacy COBOL banking system integration in Japan and Italy forces expensive custom middleware layers. Distribution runs through direct-to-consumer app stores, embedded finance partnerships with e-commerce platforms, and white-label arrangements with regional banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal finance tools sector is entering a cyclical recovery phase as interest rate stabilization restores consumer appetite for investment-linked advisory features. Subscription fatigue troughs are reversing as embedded finance partnerships demonstrate viable unit economics for standalone platforms.
For Market Incumbents: Entrench ecosystem bundling advantages by deepening TurboTax-Mint integration workflows and accelerating direct bank API access through strategic acquisitions. Neobank competitive pressure demands defensive certification investment in EU AI Act conformity assessments for algorithmic advisory features. Channel control through primary banking relationship capture represents the critical defensive lever against standalone app displacement.
For New Entrants and Emerging Players: Micro-enterprise cash management for sole proprietors in Mexico and Indonesia represents the most penetrable entry point between consumer budgeting and full accounting suites. Carbon-linked spending analytics for Scandinavian retail users presents adjacent white space as EU CSRD disclosure requirements mature. Voice-first interface development for South Korean and United States smart speaker penetration offers differentiated distribution beyond saturated app stores.
For Investors and Strategic Acquirers: Specialist API infrastructure providers with direct bank integration capabilities and proven categorization engines command scarcity premiums in consolidation scenarios. Long-term viability across the analysis window favors platforms with regulatory sandbox approvals in multiple jurisdictions. The signal to watch is FedNow and instant payment rail adoption velocity as a proxy for liquidity management tool subscription pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Bank API Acquisition | PSD2-mandated data access in the United Kingdom and European Union accelerates feature parity against screen-scraping intermediaries. |
| Embedded Finance Partnership | Southeast Asian e-commerce platforms convert casual users into active wealth builders through transaction-point savings triggers. |
| Regulatory Sandbox Entry | Japan's METI and FSA coordination on fintech approvals determines market entry timelines for foreign platform providers. |
| Voice-First Interface Development | Smart speaker penetration in South Korean and United States households opens distribution channels beyond smartphone app stores. |
| Carbon Analytics Integration | EU CSRD disclosure requirements and Scandinavian consumer preferences create demand for transaction-level emissions tracking. |
Research Methodology
Desk research of SEC filings, open banking protocol documentation, and regulatory sandbox approval records preceded structured interviews with neobank product executives, API infrastructure engineers, regulatory compliance officers, and embedded finance partnership leads. Primary fieldwork with platform developers and secondary validation through CFPB disclosure guidance and EU AI Act technical documentation established demand-side and supply-side parameters. Bottom-up aggregation of subscriber counts and top-down market sizing through fintech penetration rates enabled cross-verification.
Assumptions around open banking API standardization velocity, real-time payment rail deployment schedules, and advisory licensing friction timelines were held fixed across baseline scenarios while tariff exposure and data localization mandate expansion were stress-tested. Segmentation modeling incorporated product type, end user archetype, service tier, and delivery model dimensions alongside regional regulatory cluster differentiation. CAGRs were derived through logistic adoption curve fitting and spend-per-subscriber trajectory analysis. Forecast inputs included generative interface development cycles and voice-first platform penetration curves.
Practitioners should monitor PSD2 implementation variance across EU member states and FedNow adoption velocity among regional US banks for early signals of platform competitive positioning shifts. Forecasts reflect these documented assumptions regarding regulatory harmonization and consumer subscription willingness. Material shifts in India's RBI data localization enforcement or Saudi Arabia's SAMR domestic server requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Household Finances Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Renters Insurance Market