
 Credit Scores, Credit Reports and Credit Check Services Market | 2026-2036
Credit Scores, Credit Reports and Credit Check Services Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Scores, Credit Reports and Credit Check Services Market Insights
Alternative data is rebalancing scoring economics as utility payment histories and rental records supplement traditional trade-line information. Experian leverages proprietary analytics platforms to anchor its position across North American consumer segments. Equifax sustains competitive differentiation through employer services verticals that extend credit data into workforce verification. TransUnion dominates emerging market expansion with localized bureau partnerships in Latin America and Africa.
Credit scores, credit reports and credit check services constitute data-driven risk assessment products that aggregate payment behavior, debt obligations, and public record information into standardized numerical outputs or narrative files for underwriting decisions. FICO and VantageScore model variants process hundreds of behavioral variables through proprietary algorithms to produce three-digit risk indicators. Service type segmentation reveals credit monitoring and identity monitoring as the fastest-growing revenue pools, while individual credit check services remain the mature volume base where margin compression pressures incumbent pricing. API integrations as a distribution channel are displacing direct sales for enterprise clients seeking real-time decisioning infrastructure.
The US Consumer Financial Protection Bureau enforces Fair Credit Reporting Act compliance, mandating dispute resolution timelines and adverse action notice requirements that shape product design for American operators. India's RBI and CEA oversee credit information company licensing under the Credit Information Companies Regulation Act, creating localized barriers to foreign bureau entry. The EU GDPR and proposed AI Act impose algorithmic transparency obligations on automated scoring systems used within European lending decisions. Stakeholders must monitor evolving open banking mandates and alternative data consent frameworks to anticipate which data assets will retain proprietary value versus commoditized utility.
Market Dynamics
Open banking API proliferation is fragmenting data ownership across credit bureaus, fintech platforms, and utility providers, forcing incumbents to rebuild scoring architectures around real-time permissioned data flows rather than static repository models.
Growth Catalysts
- India's CICRA licensing expansion:The RBI and CEA are authorizing new credit information companies to cover underbanked rural populations, creating fresh demand for alternative data scoring infrastructure.
- Digital lending platforms:Southeast Asian neobanks require embedded credit decisioning APIs that pull multi-source behavioral data for instant loan origination.
- Utility payment digitization:Smart meter rollouts and mobile money penetration generate structured repayment histories that feed non-traditional scoring algorithms.
Market Restraints
- Data localization mandates:India's RBI requires domestic storage of credit information, raising infrastructure costs for foreign bureau operators seeking market entry.
- Consent framework fragmentation:Divergent GDPR, CCPA, and emerging national privacy laws create compliance complexity for cross-border scoring services.
- Legacy system interdependence:Major lenders maintain decades-old core banking platforms that resist real-time API integration with modern scoring engines.
Strategic Opportunities
- Employer-verified income data:Workforce information systems in the US and UK offer new income validation channels that reduce verification fraud in thin-file segments.
- Embedded finance partnerships:E-commerce checkout flows and ride-hailing apps create distribution nodes for instant credit eligibility checks at point-of-need.
- Rental payment reporting:Property management software platforms capture monthly housing payments that currently escape traditional credit files.
Industry Challenges
- Algorithmic audit expertise:The EU AI Act demands explainability documentation for automated scoring decisions, requiring scarce machine learning interpretability specialists.
- Legacy-to-cloud migration:Decades of batch-processed credit archives must be restructured for real-time query architectures without disrupting dispute resolution timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Scores, Credit Reports and Credit Check Services Market |
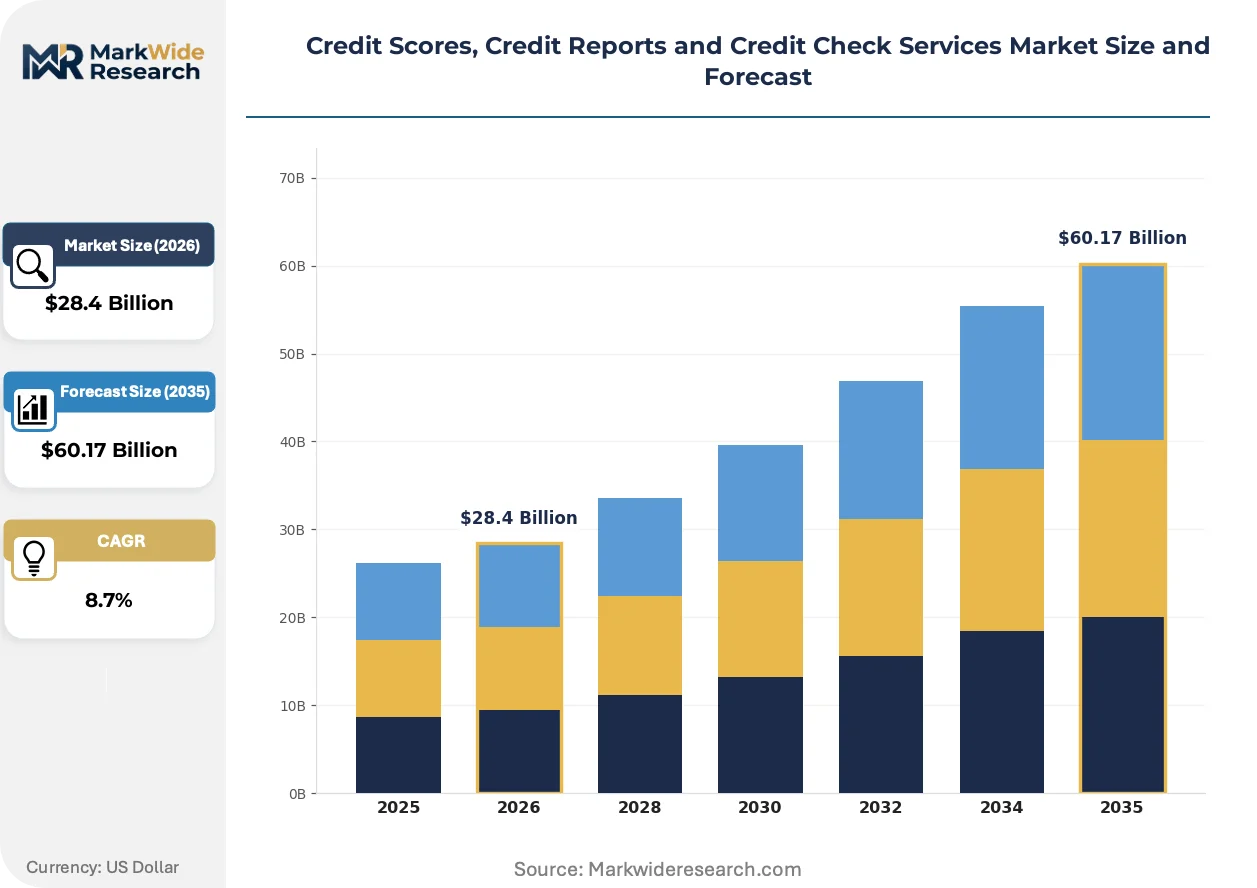
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Credit Score Model: FICO, VantageScore, Experian Plus, TransUnion Auto Score, CE Score Service Type: Individual Credit Check, Business Credit Check, Identity Monitoring, Fraud Detection, Credit Monitoring End User: Financial Institutions, Insurance Providers, Telecommunication Companies, Real Estate Agencies, Debt Collectors Distribution Channel: Online Platforms, Direct Sales, Partner Networks, API Integrations, Retail Outlets |
| Companies Covered | Experian, Equifax, TransUnion, MyFICO, Credit Karma, Moody’s Corporation, CRIF High Mark, Creditsafe Business Solutions, Credit Sesame, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Scores, Credit Reports and Credit Check Services Market Trends and Innovations
Real-time data streaming is collapsing the latency between consumer behavior change and credit risk recalculation, compressing the feedback loops that traditionally separated scoring model updates from market conditions.
Federated learning architectures are unifying distributed data sources without centralizing raw consumer information. Major retail banks in Germany and Singapore are piloting privacy-preserving scoring collaborations that pool pattern recognition across institutions while keeping individual records siloed. This approach is unifying competitive bureaus around shared model development without triggering data ownership disputes that have historically blocked industry-wide innovation.
The EU AI Act's risk classification system imposes documentation burdens on automated credit decisions that affect consumer access to essential services. Lenders operating across European markets must maintain algorithmic impact assessments and human oversight protocols that increase compliance overhead. Subprime and near-prime product lines face the steepest adjustment costs as regulators scrutinize scoring thresholds that trigger adverse action notices.
Buyers now expect credit monitoring to integrate with broader financial wellness dashboards rather than standalone alert services. Neobank customers in Brazil and Nigeria demand unified interfaces that combine score tracking with budgeting tools and savings recommendations. This bundling pressure is squeezing pure-play monitoring providers who lack adjacent product ecosystems to retain subscriber relationships beyond initial enrollment periods.
Credit Scores, Credit Reports and Credit Check Services Market Segmentation
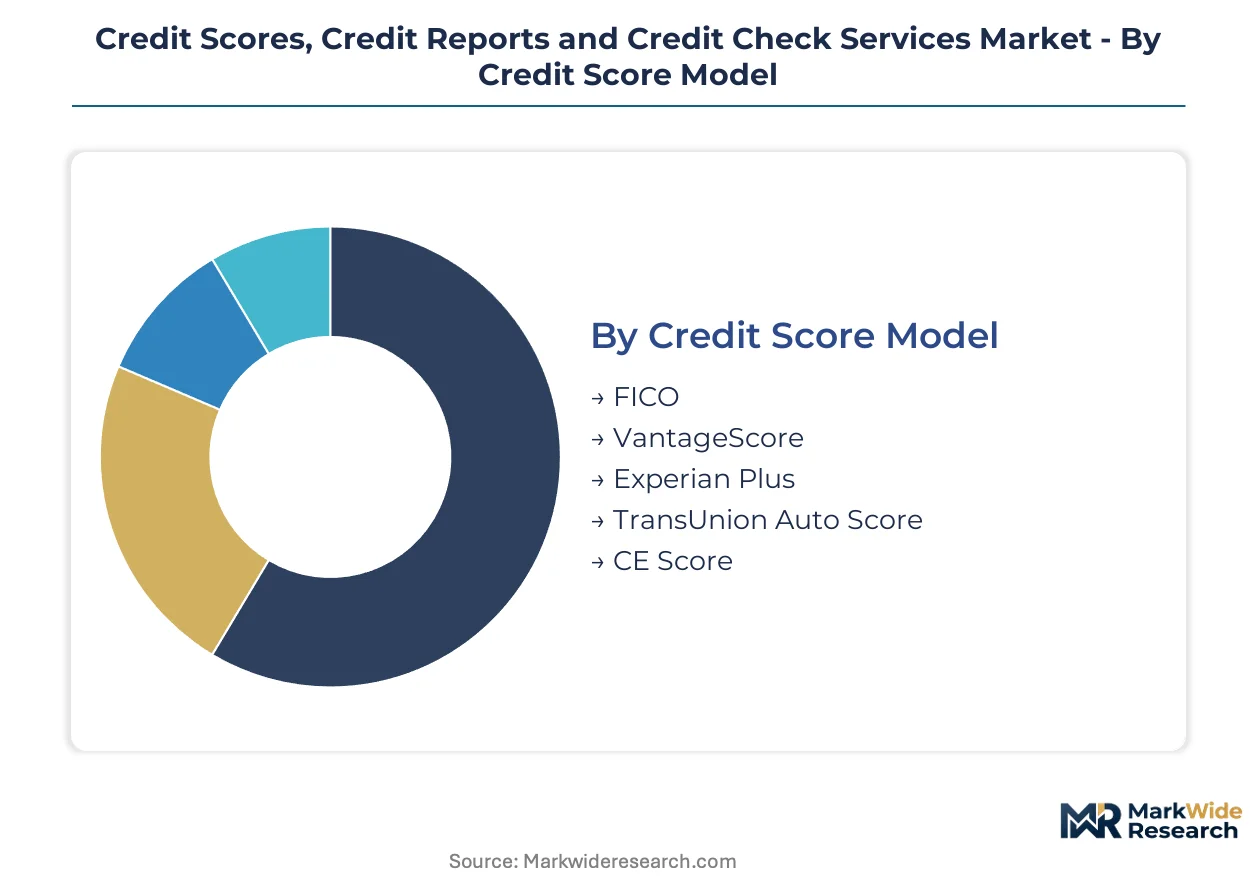
Segmentation in credit scoring services reveals how risk assessment products fragment across technical architectures, service delivery modes, and buyer sophistication levels. Each dimension exposes different margin structures and competitive moats that shape vendor positioning strategies.
Credit Score Model:
FICO and VantageScore dominate enterprise underwriting, but specialized variants now capture niche verticals with tailored algorithmic weightings.
- FICO:The original three-digit scoring architecture processes payment history, credit utilization, and account age through proprietary weighting schemes. US mortgage originators and auto lenders mandate FICO scores for regulatory compliance, cementing its position in high-stakes lending decisions despite licensing fees that squeeze thin-margin fintech budgets.
- VantageScore:Developed jointly by the three major bureaus, this model incorporates trended data and utility payments to score thin-file consumers excluded from traditional frameworks. Digital lenders in India and Brazil deploy VantageScore variants for first-time borrower segments where FICO produces insufficient data returns.
- Experian Plus:Bureau-specific enhancement layering alternative data atop core scoring outputs for deeper risk granularity.
- TransUnion Auto Score:Vehicle-financing specialized variant weighting dealership payment patterns and loan-to-value ratios.
- CE Score:Consumer empowerment focused model emphasizing educational transparency and dispute accessibility features.
FICO leads volumes today; VantageScore is gaining share fastest.
Service Type:
Revenue concentration shifts from one-time report sales toward recurring monitoring subscriptions with embedded identity protection.
- Credit Monitoring:Continuous surveillance of bureau file changes triggers alerts for new inquiries, balance shifts, or derogatory marks. US neobanks bundle monitoring into premium account tiers, while standalone providers in Brazil face churn pressure as bundled alternatives proliferate.
- Identity Monitoring:Dark web scanning and SSN tracking extend beyond credit files to encompass broader fraud exposure. Post-Equifax breach regulatory settlements in the US created permanent demand baselines, with employer-sponsored programs now driving enterprise contract growth.
- Individual Credit Check:Single-pull report products for consumer self-assessment or rental application support.
- Business Credit Check:Commercial entity risk evaluation incorporating trade payment data and public filing histories.
- Fraud Detection:Real-time transaction scoring and synthetic identity flagging for payment processors.
Individual credit checks dominate transaction volumes; identity monitoring climbs the fastest.
End User:
Financial institutions command premium pricing for real-time decisioning infrastructure, while adjacent verticals accept batch-processed alternatives at lower price points.
- Financial Institutions:Banks, credit unions, and digital lenders require millisecond-latency scoring APIs integrated into loan origination systems. India's RBI mandates bureau connectivity for all regulated lenders, creating compulsory demand that insulates vendors from cyclical credit cycle pressures.
- Insurance Providers:Property and casualty underwriters incorporate credit-based insurance scores into premium calculations where state regulations permit. US auto insurers in Michigan and Florida face the tightest restrictions, compressing addressable market scope relative to less regulated states.
- Telecommunication Companies:Postpaid account approval and device financing decisions utilize lightweight scoring variants with reduced data requirements.
- Real Estate Agencies:Tenant screening applications prioritize rental payment histories and eviction records over traditional credit metrics.
- Debt Collectors:Skip tracing and recovery prioritization leverage bureau locate services and bankruptcy flag monitoring.
Financial institutions anchor current revenue; insurance providers represent the steepest expansion trajectory.
Distribution Channel:
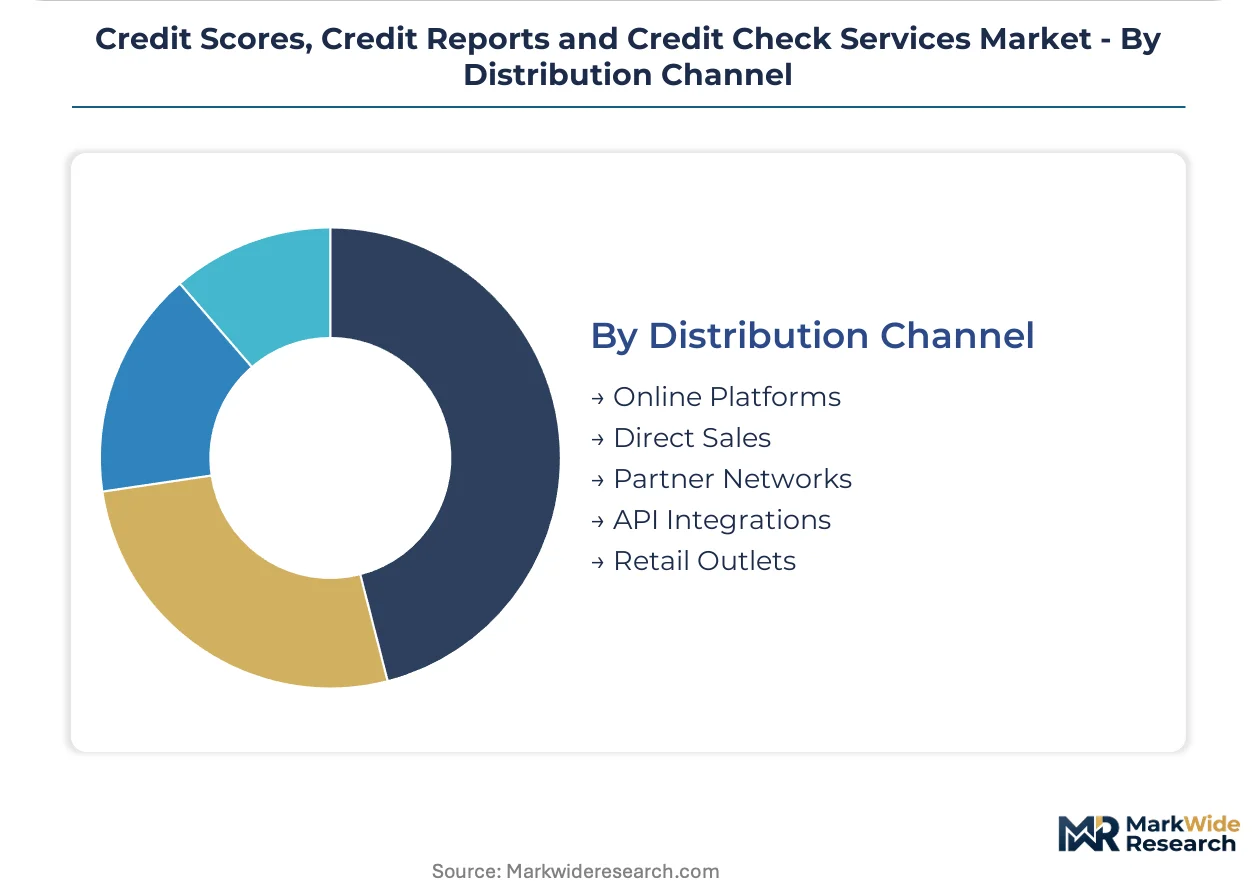
API integrations are displacing direct sales for enterprise procurement, while retail outlets persist for consumer-facing products in underbanked geographies.
- API Integrations:RESTful endpoints embed scoring directly into lender workflows, eliminating manual report retrieval. Southeast Asian digital banks require sub-second response times for instant loan decisions, forcing vendors to rearchitect legacy batch systems around cloud-native query infrastructure.
- Online Platforms:Consumer-direct web portals and mobile applications deliver self-service score access and dispute filing. Brazil's open banking framework mandates free annual report access through centralized interfaces, commoditizing basic delivery while creating upsell opportunities for premium analytics.
- Direct Sales:Enterprise relationship management for large lender contracts with customized model development.
- Partner Networks:Affiliate arrangements with financial advisors and mortgage brokers for referral-based distribution.
- Retail Outlets:Physical presence in bank branches and postal facilities for populations with limited digital access.
Online platforms generate the highest consumer volumes; API integrations expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Experian-anchored UK credit bureau cluster shapes European scoring standards, while India's CICRA licensing expansion and Southeast Asia's digital lending surge create distinct regional growth vectors across emerging and developed markets.
United States
Digital lenders in California and Texas drive real-time API demand for instant credit decisioning. The CFPB enforces Fair Credit Reporting Act compliance with strict dispute resolution timelines. Chicago hosts TransUnion's North American headquarters, where employer services verticals extend credit data into workforce verification systems.
India
Rural underbanked populations and neobank expansion generate demand for alternative data scoring infrastructure. The RBI and CEA authorize new credit information companies under CICRA licensing mandates. Mumbai's financial district concentrates CRIF High Mark and bureau partnerships targeting thin-file consumer segments.
Germany
Federated learning pilots among retail banks reshape privacy-preserving scoring collaborations. The EU AI Act imposes algorithmic transparency obligations on automated lending decisions. Frankfurt's fintech cluster experiments with explainable machine learning for subprime risk assessment documentation.
Brazil
Open banking frameworks mandate free annual report access, commoditizing basic delivery while creating premium analytics upsell opportunities. The central bank's Pix instant payment system generates structured transaction histories for non-traditional algorithms. São Paulo's neobank ecosystem bundles credit monitoring into unified financial wellness dashboards.
Singapore
Southeast Asian digital banks require sub-second scoring response times for instant loan origination. The Monetary Authority of Singapore's open banking directives fragment data ownership across bureaus and fintech platforms. The city-state's API infrastructure hub hosts real-time permissioned data flow architectures displacing static repository models.
Credit Scores, Credit Reports and Credit Check Services Market Competitive Landscape
Global majors compete with regional champions across data sourcing methodologies and regulatory compliance depth. The market exhibits tiered consolidation with three dominant bureaus anchoring developed economies while licensed regional operators capture underbanked segments. Strategic archetypes include repository-centric incumbents rebuilding around open banking APIs, alternative data specialists aggregating utility and rental payments, and embedded finance platforms integrating scoring at point-of-need. Competitive moves concentrate on federated learning partnerships for privacy-preserving model development and cloud-native infrastructure migration to support real-time query architectures.
Among the established repository-centric tier, Experian, Equifax, and TransUnion occupy positions exemplifying divergent geographic and vertical strategies. Experian anchors North American consumer segments through proprietary analytics platforms. Equifax sits within employer services verticals that extend credit data into workforce verification. TransUnion exemplifies emerging market expansion through localized bureau partnerships in Latin America and Africa. CRIF High Mark represents the regional licensing archetype, occupying a position within India's CICRA-regulated credit information company tier targeting underbanked rural populations.
| Leading Market Players |
|---|
| Experian |
| Equifax |
| TransUnion |
| MyFICO |
| Credit Karma |
| Moody's Corporation |
| CRIF High Mark |
| Creditsafe Business Solutions |
| Credit Sesame |
| Others |
Pricing and Supply Chain Analysis
Machine learning interpretability specialists in Frankfurt and Singapore command premium compensation that widens pricing spreads between algorithmic audit-ready premium tiers and basic compliance-economy offerings. Labor-cost differentials between EU-based explainability teams and offshore analytics centers directly feed into three-tier pricing structures across enterprise scoring services.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and regulatory compliance documentation dominates pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates real-time API-enabled decisioning from batch-processed file retrievals. Price differentiation hinges on certification depth—FCRA-compliant US offerings versus GDPR-aligned EU variants—and customization granularity for lender-specific model weightings. Pricing pressure stems from open banking API commoditization of raw credit data, squeezing repository-centric margins. Thin-file fintech segments exhibit highest price sensitivity; mortgage originators tolerate premium licensing for FICO score mandates.
Supply Chain Analysis
Direct-to-lender API channels handle hyperscale digital bank demand while partner networks serve mid-tier credit union procurement. Raw data sourcing concentrates in India, the United States, and Brazil where credit information company licensing creates localized supply nodes. The supply chain draws from proprietary bureau repositories, utility payment aggregators, and employer-verified income platforms as core inputs. Single-source vulnerability around legacy mainframe batch systems poses structural risk as real-time query volumes surge. Distribution runs through cloud-native API gateways displacing direct sales for enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The credit scoring market functions as a stable compounder anchored by compulsory bureau connectivity mandates that generate recurring revenue insulated from cyclical credit downturns.
For Market Incumbents: Deepen federated learning partnerships to pool model development costs while preserving data ownership boundaries against open banking fragmentation. Prioritize cloud-native infrastructure migration to support sub-second API response times that Southeast Asian digital lenders demand. Vertical integration into employer-verified income data reduces fraud exposure in thin-file segments where synthetic identity risk concentrates. For New Entrants and Emerging Players: The mid-market price-point gap between Experian-Equifax-TransUnion premium suites and free annual report commoditization offers white-space entry. Target India's CICRA-licensed credit information company tier where rural underbanked coverage expansion creates infrastructure demand. Brazil's open banking framework mandates free basic access but leaves premium analytics upsells unregulated. Embedded finance partnerships with ride-hailing and e-commerce platforms provide lowest-friction distribution for instant eligibility checks. For Investors and Strategic Acquirers: Private equity firms with fintech portfolio holdings are the most active acquirer in this space, seeking API infrastructure to bolt onto existing lending platforms. Long-term viability rests on regulatory compliance depth as algorithmic transparency mandates proliferate. Acquisition target archetype: regional credit bureaus with CICRA-equivalent licenses in underbanked markets. Watch EU AI Act enforcement intensity as inflection indicator for compliance-cost trajectory across automated scoring.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Enables Experian, Equifax and TransUnion to share model development without centralizing consumer raw data. |
| Cloud-Native API Migration | Supports sub-second scoring response times that Singapore's MAS open banking directives require. |
| Alternative Data Licensing | Utility payment digitization in India and Brazil feeds non-traditional algorithms for thin-file segments. |
| Employer Services Vertical Expansion | Equifax extends credit data into workforce verification systems reducing income fraud in US lending. |
| Embedded Finance Integration | Credit Karma and neobanks deploy point-of-need eligibility checks within e-commerce checkout flows. |
Research Methodology
Direct dialogue with chief risk officers at digital lenders, regulatory compliance leads at credit bureaus, API product managers at fintech platforms, and data protection officers navigating GDPR-EU AI Act overlap grounded qualitative findings. Secondary validation drew from CFPB enforcement actions, RBI CICRA licensing circulars, EU AI Act risk classification documentation, and SEC 10-K filings from publicly traded bureaus. Bottom-up triangulation across service type segmentation and top-down macroeconomic scenario testing converged on market size estimates.
Segmented outputs across credit score model variants, service delivery modes, end-user verticals, and distribution channel architectures structured the analytical framework across the projection horizon. CAGRs derived from regression analysis against digital lending penetration curves and open banking API adoption rates. Modeled inputs included India's rural underbanked coverage expansion timelines and Southeast Asian neobank origination volume trajectories.
Caveats apply where RBI data localization enforcement intensity or EU AI Act algorithmic audit implementation delays could materially shift the outlook. Forecasts rest on assumptions regarding open banking consent framework standardization and legacy system modernization pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
Household Finances Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market