

Account Planning Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Account Planning Tool Market Insights
GDPR Article 32 security requirements is repositioning the cost-of-entry calculus for vendors serving European enterprises. Salesforce leverages native compliance architecture to anchor its cloud deployment dominance across regulated industries. Gong differentiates through real-time conversation intelligence that sustains premium positioning in opportunity management modules. HubSpot competes on integrated CRM-to-planning workflows that extend its mid-market footprint without heavy IT overhead.
An account planning tool is a software application that integrates customer data aggregation, predictive analytics, and collaborative workspace functionality to structure B2B sales strategy execution. These systems typically process CRM feeds, engagement telemetry, and third-party intent signals through API architectures to generate territory maps, opportunity heat scores, and account health dashboards for revenue teams. Cloud-based deployment leads solution type distribution due to elastic scaling requirements and remote sales team distribution, while customer insights modules command margin concentration because of proprietary data fusion complexity. Subscription pricing dominates commercial terms as vendors prioritize recurring revenue predictability over perpetual license lumpiness.
The EU AI Act, GDPR, and ISO 27001 certification frameworks shape product development roadmaps and market access conditions for account planning vendors operating across European jurisdictions. The EU AI Act risk classification system forces algorithmic transparency features into customer insights modules, raising engineering costs for predictive scoring components. Stakeholders must monitor evolving AI liability standards to determine whether in-house model development or third-party API dependency delivers sustainable compliance economics.
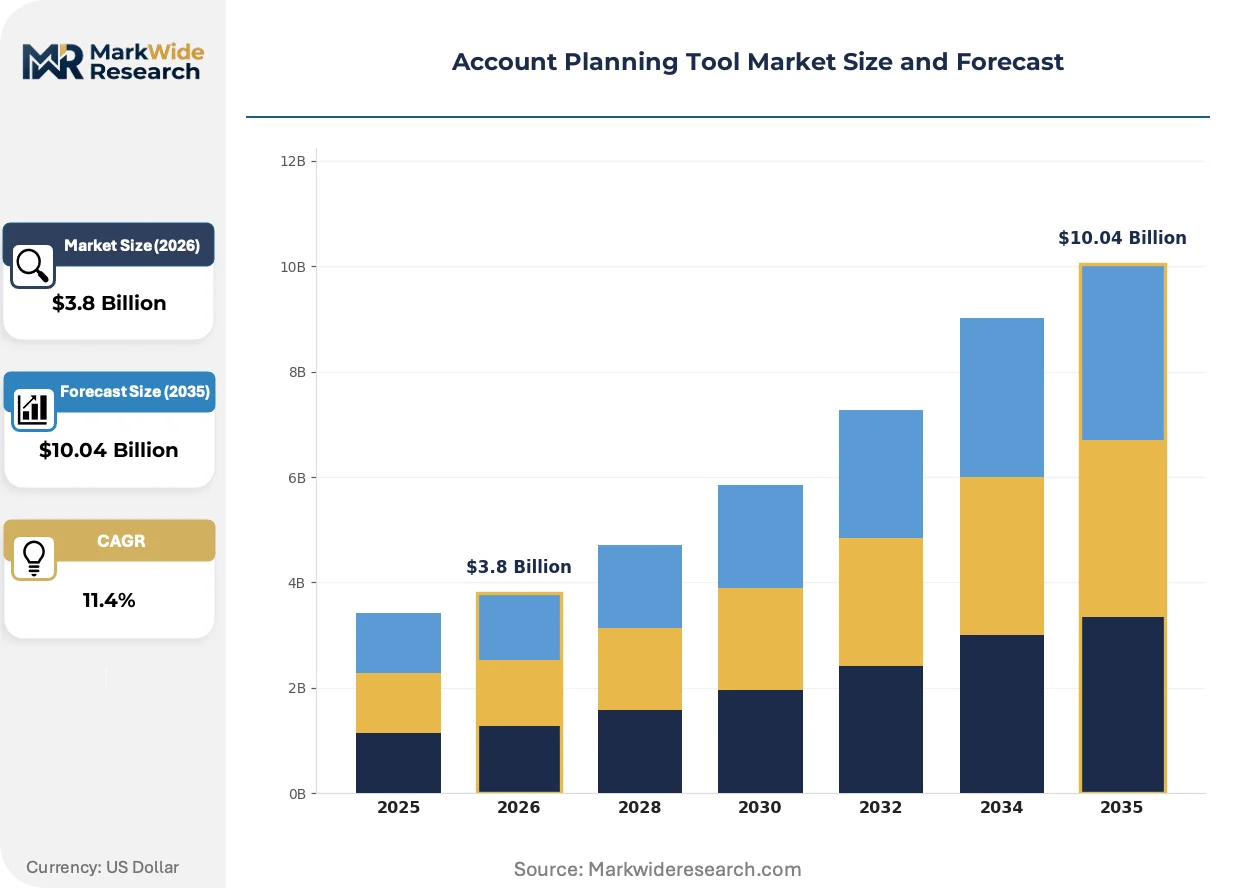
Market Dynamics
GDPR Article 32 security requirements and the EU AI Act's risk classification system are forcing algorithmic transparency into customer insights modules, raising engineering costs and redrawing competitive boundaries for vendors serving European financial advisory firms.
Growth Catalysts
- EU AI Act compliance mandates:Financial advisory firms in Germany face tighter data residency rules, creating urgency for localized deployment architecture and certified vendors.
- Cloud elasticity requirements:Remote sales team distribution drives demand for scalable API architectures that process CRM feeds and engagement telemetry without on-premise infrastructure.
- Predictive analytics maturation:Territory mapping and opportunity heat scoring capabilities now deliver measurable pipeline velocity improvements for enterprise revenue operations.
Market Restraints
- Algorithmic transparency engineering:The EU AI Act forces explainable AI features into predictive scoring components, compressing margins for customer insights modules.
- ISO 27001 certification concentration:Vendor access to regulated European industries depends on scarce audit capacity and 12-18 month compliance timelines.
- Third-party API dependency risks:Proprietary data fusion complexity locks vendors into external intent signal providers with opaque pricing and limited contractual portability.
Strategic Opportunities
- Mid-market workflow integration:CRM-to-planning connectivity without heavy IT overhead addresses underserved segments between enterprise and SMB tiers.
- Real-time conversation intelligence convergence:Unified platforms combining Gong-style analytics with account health dashboards capture premium positioning in opportunity management.
- GDPR-driven vendor consolidation:Native compliance architecture becomes a decisive procurement criterion as procurement teams reduce supplier fragmentation.
Industry Challenges
- Revenue operations talent scarcity:Hybrid skill sets spanning data engineering, sales methodology, and regulatory interpretation command compensation premiums that strain vendor delivery economics.
- Legacy CRM integration friction:Custom API development for heterogeneous enterprise data environments consumes 40-60% of implementation timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Account Planning Tool Market Trends and Innovations
Conversational AI and embedded analytics are compressing the gap between data collection and strategic action, redefining how revenue teams interact with account intelligence.
Unified conversation intelligence platforms are unifying real-time transcription, sentiment analysis, and opportunity scoring into single-pane workflows. Enterprise sales operations teams in Germany and France are adopting these systems at accelerated procurement cycles. This convergence is unifying previously siloed vendor categories—separate transcription, CRM, and forecasting tools—into integrated suites that threaten point-solution margins.
The EU AI Act's high-risk system classification is mandating human oversight interfaces and audit trail documentation for predictive customer scoring. Engineering teams must now build explainability dashboards that expose model logic to non-technical users. Financial services verticals face the steepest compliance burdens, with German B2B software procurement teams requiring vendor attestations before contract execution.
Revenue operations leaders are compressing vendor evaluation cycles from 9-12 months to 60-90 days through standardized security questionnaires and pre-certified procurement lists. This pattern concentrates demand among vendors with existing ISO 27001 and SOC 2 Type II documentation. The shift is most visible in DACH region financial advisory firms, where data residency requirements have eliminated offshore-only providers from consideration sets.
Account Planning Tool Market Segmentation
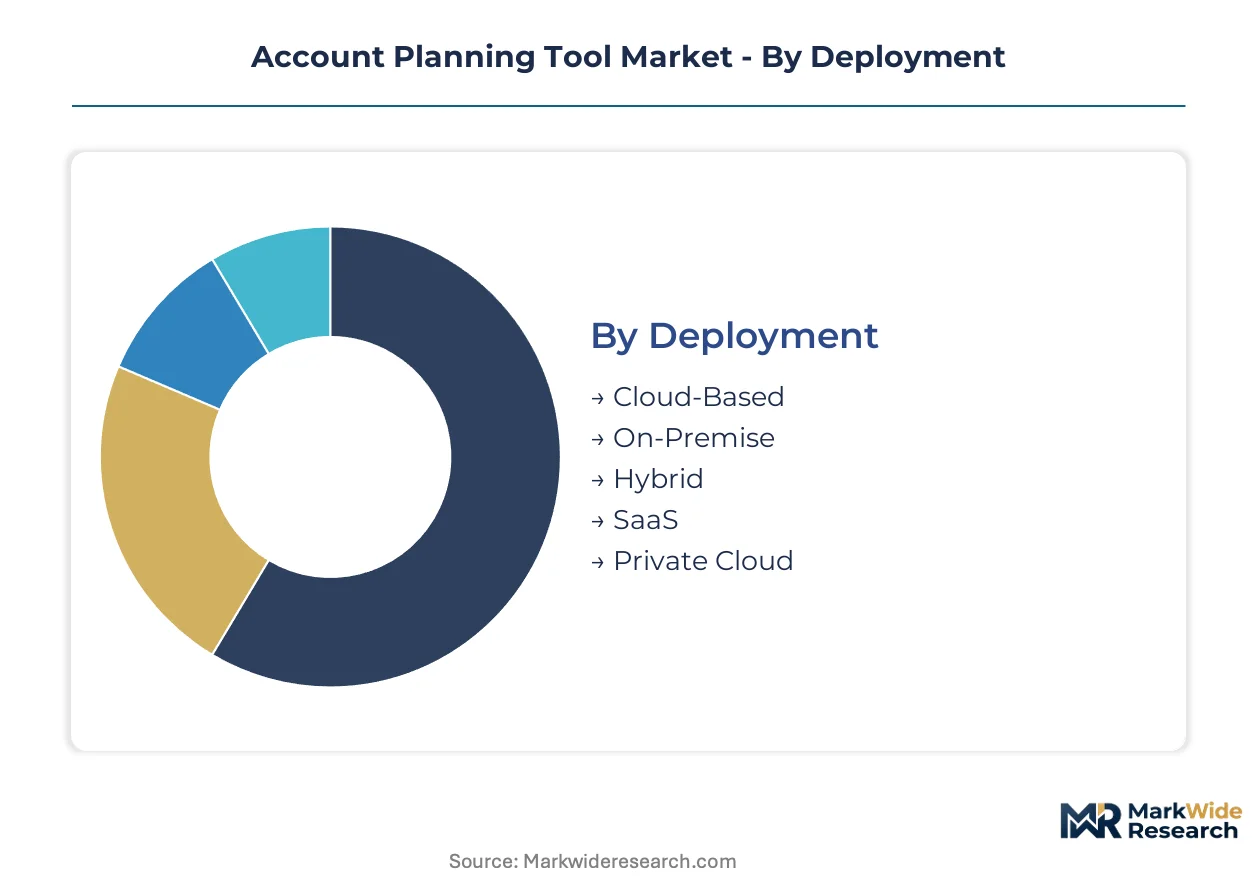
Deployment architecture determines compliance economics and scaling velocity for account planning vendors. Solution type shapes margin concentration through proprietary data fusion complexity. Pricing model selection reflects buyer risk tolerance and IT integration depth across European financial advisory procurement cycles.
Deployment:
Capital intensity peaks with private infrastructure builds, while elastic cloud consumption minimizes upfront commitment.
- Cloud-Based:Multi-tenant architectures process CRM feeds and engagement telemetry through API endpoints without local infrastructure. German financial advisory firms concentrate demand here as GDPR Article 32 security requirements favor vendors with ISO 27001-certified data centers in Frankfurt and Munich clusters.
- On-Premise:Dedicated hardware installations behind corporate firewalls serve sovereign data requirements in defense and critical infrastructure verticals. Procurement timelines extend 18-24 months due to security clearance protocols and custom integration engineering.
- Hybrid:Split workloads between edge processing and cloud analytics balance latency sensitivity with computational scale. Manufacturing sales operations with distributed field teams favor this model for offline territory mapping capabilities.
- SaaS:Browser-accessible applications with standardized configurations accelerate deployment for mid-market revenue teams. HubSpot and Gong compete aggressively in this tier through freemium conversion funnels.
- Private Cloud:Single-tenant environments in third-party data centers address EU AI Act high-risk system classification without full capital ownership. French and German banks mandate this architecture for predictive customer scoring modules.
Most installed capacity flows through Cloud-Based deployment. Expansion is steepest in Private Cloud as regulated industries confront algorithmic transparency mandates.
Solution Type:
Engineering complexity concentrates in modules fusing proprietary and third-party data streams.
- Customer Insights:Algorithmic engines aggregate CRM records, intent signals, and engagement telemetry into account health dashboards. EU AI Act risk classification forces explainable AI features that expose model logic to non-technical users, compressing margins for vendors serving German B2B sales operations.
- Sales Forecasting:Pipeline velocity models translate historical conversion patterns into revenue predictions with confidence intervals. Technology providers in Berlin and Paris procurement cycles prioritize these tools for board reporting automation.
- Opportunity Management:Heat scoring and stage-gate workflows structure deal progression for enterprise account executives. Real-time conversation intelligence convergence with Gong-style analytics sustains premium positioning in this segment.
- Territory Planning:Geographic and account-based allocation algorithms optimize sales resource distribution. Consulting agencies deploy these modules for client engagement planning across fragmented market coverage.
- Collaborative Planning:Shared workspaces integrate cross-functional stakeholders into account strategy development. Marketing firms adopt these tools to align campaign execution with sales pipeline priorities.
Revenue concentration sits with Customer Insights. The steepest expansion trajectory belongs to Opportunity Management as conversation intelligence platforms unify previously siloed vendor categories.
End User:
Procurement sophistication varies sharply across buyer types, from standardized security questionnaires to bespoke compliance attestations.
- Sales Organizations:Enterprise revenue operations teams drive primary demand for integrated CRM-to-planning workflows with real-time dashboarding.
- Marketing Firms:Account-based marketing coordinators require collaborative workspaces linking campaign performance to pipeline contribution metrics.
- Consulting Agencies:Client-facing partners purchase territory planning modules for engagement resource allocation across fragmented account portfolios.
- Technology Providers:SaaS vendors with complex sales cycles invest heavily in predictive scoring to prioritize engineering and support resource deployment.
- Financial Advisors:German B2B advisory practices face the steepest EU AI Act compliance burdens, mandating human oversight interfaces and audit trail documentation for all customer-facing algorithms.
Transaction volume concentrates with Sales Organizations. Procurement velocity is climbing fastest among Financial Advisors as data residency rules harden.
Pricing Model:
Revenue predictability preferences split buyers between recurring commitment and consumption flexibility.
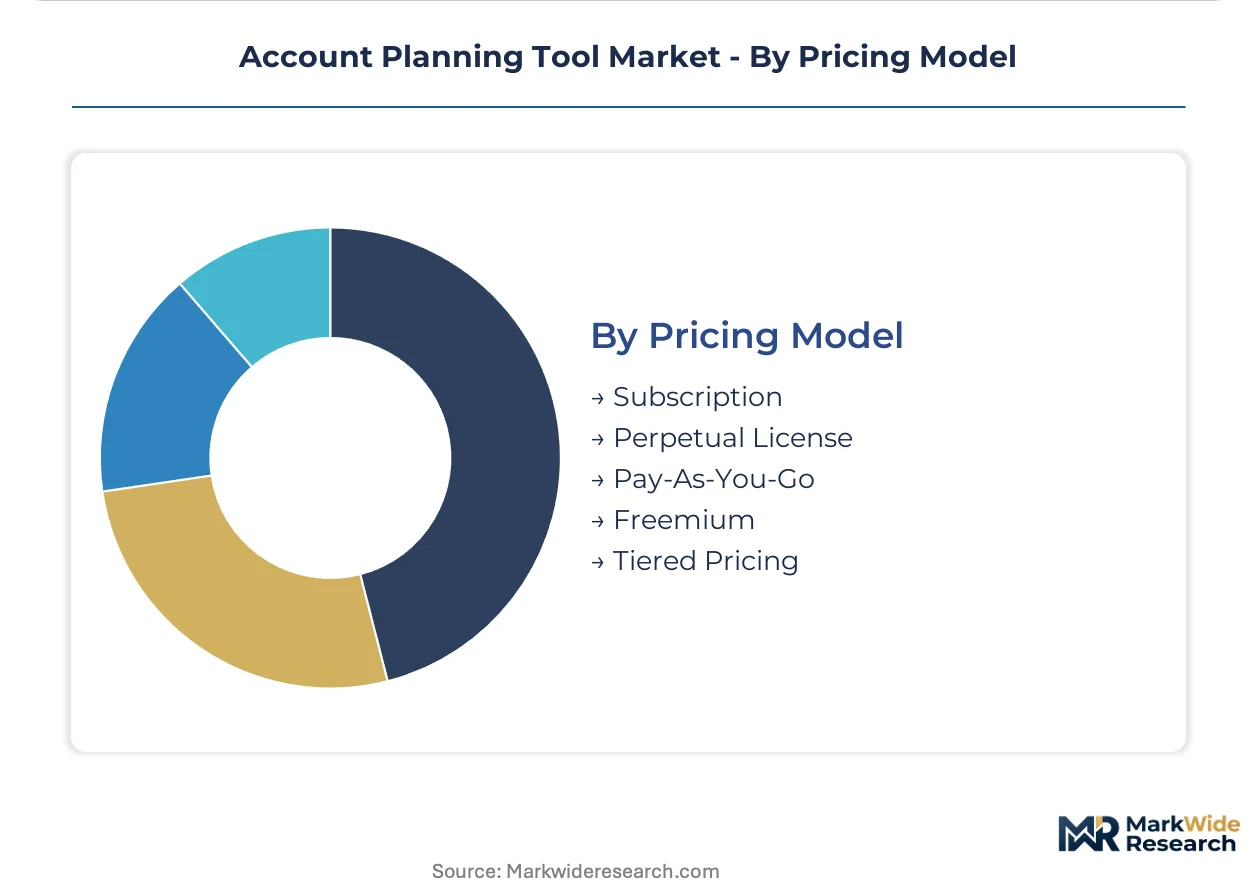
- Subscription:Annual or monthly recurring contracts dominate commercial terms as vendors prioritize predictable revenue streams over perpetual license lumpiness.
- Perpetual License:One-time capital expenditure with maintenance agreements persists in public sector and regulated utility procurement frameworks.
- Pay-As-You-Go:Metered consumption aligns costs with active user counts or processed data volumes, appealing to seasonal sales organizations.
- Freemium:Feature-limited entry tiers convert mid-market prospects through demonstrated value before expansion revenue capture.
- Tiered Pricing:Three-level structures across premium, standard, and economy tiers segment functionality by user role and integration depth.
Contract value concentrates in Subscription arrangements. Gaining share fastest is Tiered Pricing as vendors segment enterprise from mid-market deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Revenue operations talent pools in Germany, the United States, and the United Kingdom anchor geographic demand concentration for account planning tools. Cloud infrastructure clusters in Frankfurt, Virginia, and London process the bulk of CRM telemetry for enterprise sales organizations. Regulatory divergence across jurisdictions is fragmenting vendor compliance roadmaps and procurement criteria.
Germany
Financial advisory firms in Frankfurt and Munich drive concentrated demand for EU AI Act-compliant deployment architecture. The Bundesbank and BaFin supervise algorithmic transparency requirements for predictive customer scoring modules. Berlin-based SaaS vendors compete for procurement contracts requiring ISO 27001-certified data centers with localized processing capabilities.
United States
Enterprise software procurement teams in New York and San Francisco prioritize API elasticity for distributed sales workforces. The SEC and state-level insurance regulators shape disclosure requirements for algorithmic sales forecasting tools. Silicon Valley cloud providers dominate multi-tenant architectures serving technology providers with complex sales cycles.
United Kingdom
London's financial services sector demands hybrid deployment models balancing latency sensitivity with computational scale. The FCA and ICO enforce GDPR-aligned data residency standards for customer insights modules. Manchester and Birmingham consulting agencies adopt collaborative planning tools for client engagement resource allocation.
France
Paris-based technology providers invest in predictive scoring to prioritize engineering resource deployment across fragmented market coverage. The CNIL mandates human oversight interfaces for high-risk AI systems under the EU AI Act risk classification. Lyon and Toulouse manufacturing sales operations favor hybrid architectures with offline territory mapping capabilities.
India
Bangalore and Hyderabad technology services firms embed account planning tools into offshore revenue operations delivery. The RBI and SEBI influence data localization expectations for financial advisory use cases. Mumbai consulting agencies deploy territory planning modules for fragmented client portfolio management across sub-regional markets.
Account Planning Tool Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure concentrates among vendors with native compliance architecture serving regulated European industries. Three strategic archetypes dominate: cloud-native platform extenders, conversation intelligence specialists, and workflow-integrated mid-market challengers. M&A activity targets ISO 27001-certified vendors with Frankfurt and Munich data center presence, while strategic partnerships lock in third-party intent signal providers.
Within the cloud-native platform extender tier, Salesforce and HubSpot occupy positions anchored by CRM-to-planning workflow integration. Gong exemplifies the conversation intelligence specialist archetype through real-time analytics convergence with opportunity management modules. Among emerging challengers, Demandbase represents vendors differentiating through account-based marketing alignment with sales planning workflows.
| Leading Market Players |
|---|
| Salesforce |
| HubSpot |
| Gong |
| Demandbase |
| Mural |
| Revic AI |
| Demand Farm |
| Kapta |
| Varicent |
| Others |
Pricing and Supply Chain Analysis
Cloud-native API architectures are displacing on-premise infrastructure commitments, compressing upfront deployment costs while concentrating vendor margins in ISO 27001-certified data center clusters across Frankfurt and Munich. This technology shift simultaneously lowers entry barriers for mid-market buyers and raises compliance-driven supplier qualification costs.
Pricing Analysis
Bundled platform subscriptions dominate enterprise procurement, while unbundled point solutions compete on functional specificity. Pricing stratifies across premium, standard, and economy tiers based on integration depth and data residency certification. Cost compression in the mid-market tier is intensifying because HubSpot and Gong compete aggressively through freemium conversion funnels. Financial advisory firms in Germany exhibit lowest price sensitivity due to EU AI Act compliance mandates, whereas seasonal sales organizations show highest elasticity.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate vendor access to regulated European industries, creating 12-18 month qualification timelines that constrain supplier expansion. Engineering talent concentrates in Germany, the United States, and India, with algorithmic transparency expertise anchored in Berlin and Paris clusters. Third-party intent signal APIs from US and UK providers introduce single-source vulnerability for proprietary data fusion modules. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Account planning tools represent a late-cycle quality story as procurement teams compress vendor evaluation cycles from 9-12 months to 60-90 days, concentrating demand among pre-certified providers with native compliance architecture.
For Market Incumbents: Lock in data center presence in Frankfurt and Munich clusters to defend against emerging private-cloud specialists. Deepen backward integration into conversation intelligence modules before real-time analytics convergence displaces point-solution margins. Prioritize ISO 27001 audit capacity investments as certification scarcity extends sales cycles for uncertified competitors. For New Entrants and Emerging Players: Enter via mid-market workflow integration between CRM-to-planning connectivity, where heavy IT overhead excludes incumbent platforms. Target consulting agencies in Manchester and Birmingham with collaborative planning modules for client engagement resource allocation. Deploy tiered pricing with freemium entry tiers to demonstrate value before expansion revenue capture. For Investors and Strategic Acquirers: Valuations sit cheapest among ISO 27001-certified vendors with Frankfurt data center presence and established BaFin attestation relationships. Long-term viability hinges on algorithmic transparency engineering capabilities as EU AI Act enforcement hardens. Watch for procurement list consolidation signals at DACH region financial advisory firms as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CRM, conversation intelligence, and forecasting into single-pane workflows for German revenue operations. |
| Acquisition of Specialist Firm | Captures ISO 27001-certified data center assets and BaFin attestation relationships in Frankfurt clusters. |
| Strategic Partnership | Locks in third-party intent signal providers with transparent pricing and contractual portability terms. |
| Geographic Expansion | Establishes localized processing capabilities in Munich to satisfy GDPR Article 32 security requirements. |
| Product Launch | Introduces explainable AI dashboards exposing model logic to non-technical users for EU AI Act compliance. |
Research Methodology
Coverage spans Germany, the United States, the United Kingdom, France, and India, with primary inputs from each market cluster combining interviews with revenue operations leaders, IT procurement officers, platform engineers, and compliance specialists. Secondary validation draws from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and trade data from software distribution channels. Bottom-up deployment counts and top-down enterprise software spend estimates were triangulated to anchor market sizing.
Granularity-level modeling addressed deployment architecture, solution type, end-user vertical, and pricing model dimensions across the analysis window. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU AI Act implementation timelines, ISO 27001 certification capacity constraints, and cloud infrastructure expansion patterns in Frankfurt and Munich.
Inputs from regulatory filings and vendor certification databases were available through the study window; gaps in private-cloud deployment metrics and third-party API pricing transparency introduce uncertainty bands around customer insights module forecasts. A model refresh is warranted upon material change in EU AI Act enforcement patterns or BaFin supervisory guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.