
 Augmented Analytics in BFSI Market | 2026-2036
Augmented Analytics in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Analytics in BFSI Market Analysis
ISO 27001 certification is bifurcating the competitive landscape between enterprise-grade vendors and emerging challengers. SAS Institute leverages decades of statistical computing heritage to anchor high-assurance government banking contracts. Microsoft Corporation extends its Azure cloud fabric to dominate hybrid deployment architectures across North American credit unions. IBM Corporation specializes in quantum-safe encryption integration for augmented analytics pipelines serving tier-one banks.
Augmented analytics in BFSI denotes the application of machine learning and natural language processing to automate data preparation, insight generation, and narrative explanation for financial decision-makers. These systems typically process structured transactional data alongside unstructured regulatory filings to surface anomaly patterns in sub-second response windows. Fraud detection applications currently command the largest solution spend, while predictive analytics capabilities are expanding fastest as insurers embed telematics-driven pricing models. Cloud-based deployment is maturing rapidly, though on-premises configurations retain stronghold status among Swiss and German private banks bound by data sovereignty requirements.
Banking regulators in the United States, the European Union, and India are tightening algorithmic accountability mandates. The SEC's predictive data analytics rule and the EU AI Act's high-risk system obligations are forcing platform vendors to embed explainability modules and audit trails directly into analytics workflows. Stakeholders must monitor how divergent national AI governance frameworks reshape cross-border software licensing and data residency architectures.
Market Dynamics
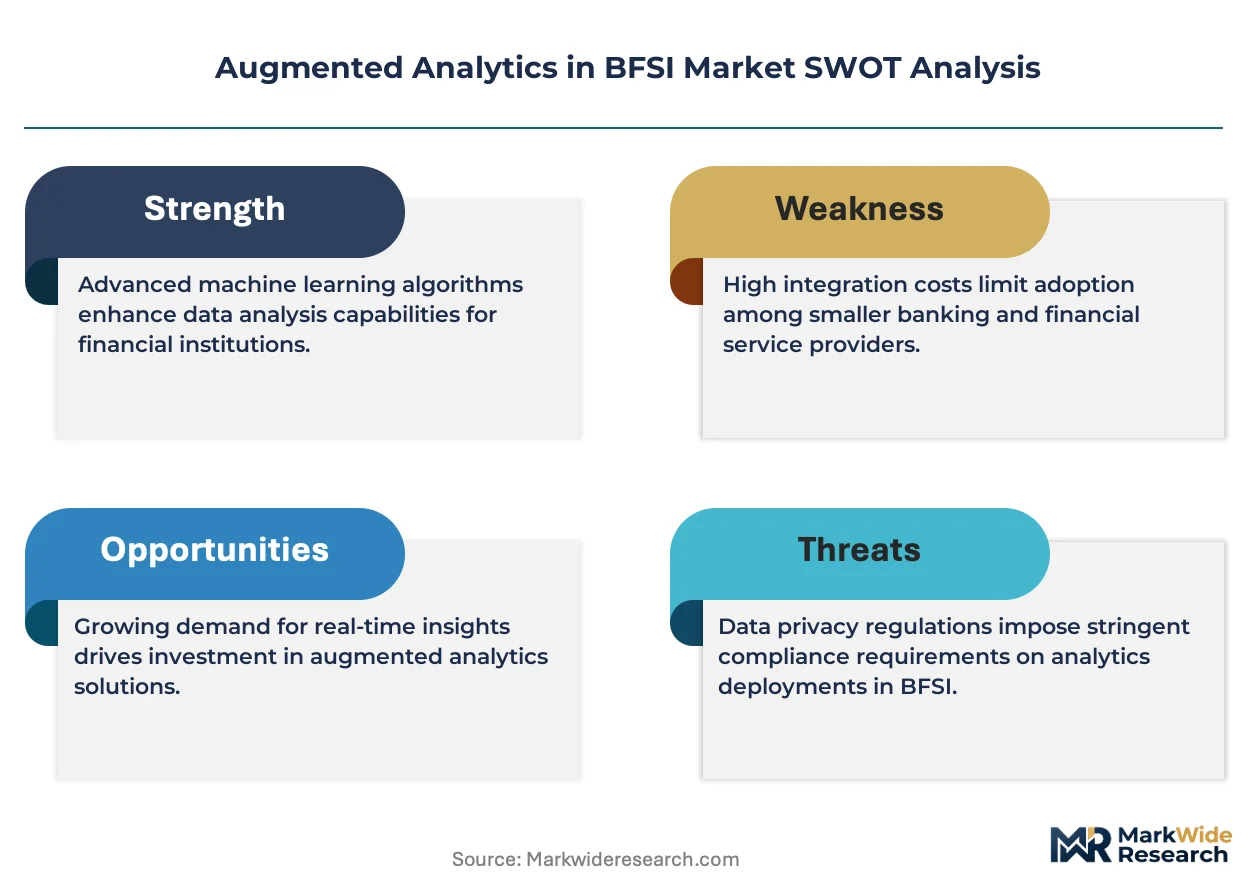
The EU AI Act's risk-based classification system is compressing vendor development cycles as banks demand embedded explainability modules before contract renewals. Algorithmic accountability mandates now sit at the center of procurement scoring rubrics, forcing platform re-engineering ahead of deployment deadlines.
Growth Catalysts
- Explainability Mandates:The EU AI Act's high-risk system obligations require audit trails in analytics workflows, creating built-in demand for transparent ML pipelines in European banking.
- Telematics Integration:Insurers embedding IoT-driven pricing models are expanding predictive analytics spend as connected vehicle data streams mature.
- Cloud Migration:North American credit unions accelerating hybrid deployments are pulling Azure and AWS infrastructure investments into augmented analytics budgets.
Market Restraints
- Data Sovereignty Requirements:Swiss and German private banks binding workloads to on-premises configurations are limiting addressable cloud revenue pools for SaaS vendors.
- Quantum-Safe Migration Costs:Tier-one banks preparing cryptographic transitions face 18-24 month pipeline delays as quantum-safe encryption integration absorbs capital.
- Talent Scarcity:The shortage of ML engineers with financial domain expertise is inflating implementation timelines and professional services dependency.
Strategic Opportunities
- Indian Regulatory Tailwind:RBI's algorithmic lending guidelines are opening captive data center buildouts as domestic banks modernize underwriting infrastructure.
- Natural Language Interface Convergence:Voice-activated query layers combining NLP with graph databases are creating new workflow categories for relationship managers.
- Sub-Segment Penetration:Community banks below $10B asset thresholds remain underserved by enterprise platforms, presenting white-space for modular deployments.
Industry Challenges
- ISO 27001 Certification Timelines:Emerging vendors face 12-18 month accreditation windows that gate government banking contract eligibility.
- Core System Integration Complexity:Augmented analytics platforms must bridge decades-old COBOL-based transaction engines, inflating professional services ratios.
- Model Drift Monitoring:Continuous validation requirements under SEC predictive data analytics rules are expanding operational overhead for US sell-side deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Analytics in BFSI Market |
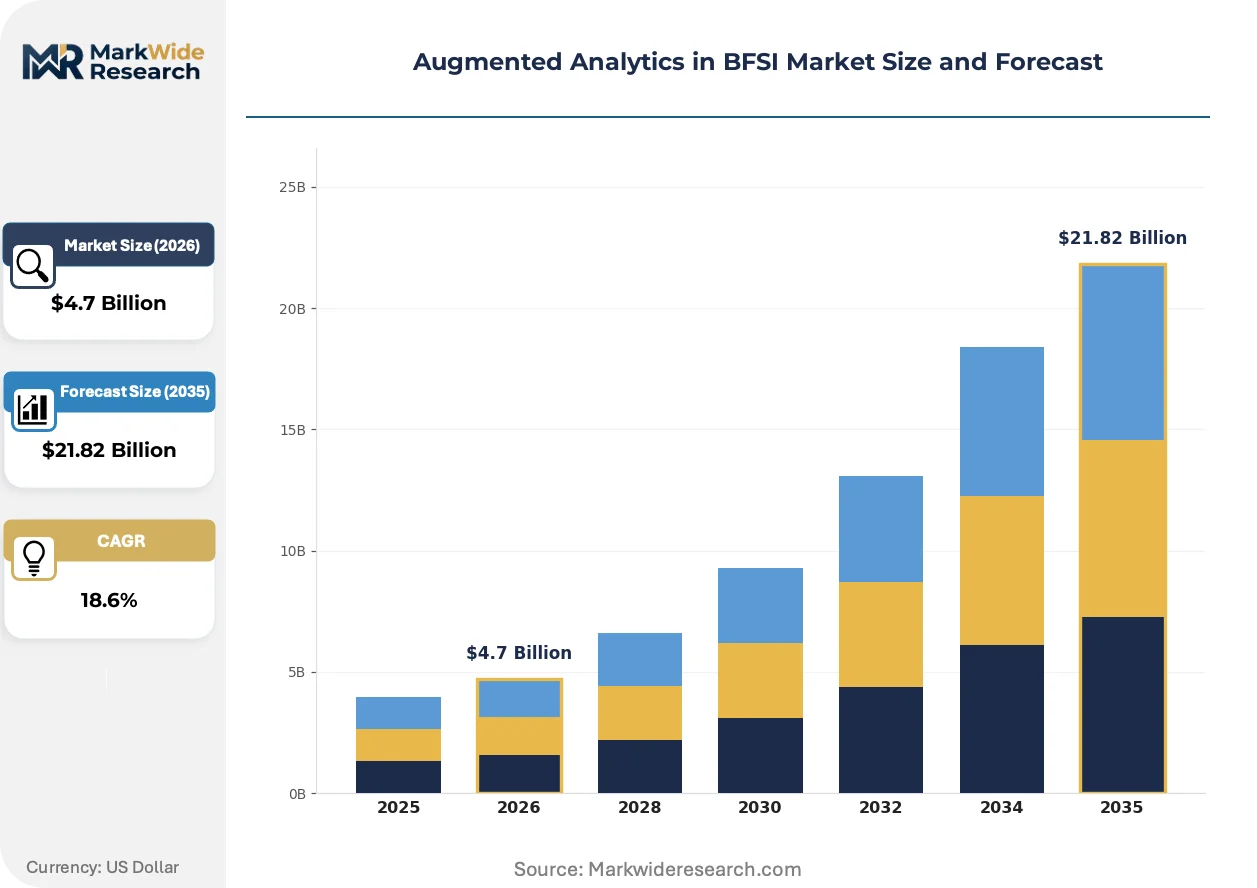
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Insights, Regulatory Compliance End User: Banks, Insurance Companies, Investment Firms, Fintechs Deployment: On-premises, Cloud-based, Hybrid, Managed Services Solution: Self-service Analytics, Data Visualization, Predictive Analytics, Machine Learning |
| Companies Covered | SAS Institute, Salesforce, Microsoft Corporation, Tableau, QlikTech International AB, SAP SE, Oracle Corporation, TIBCO Software, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Analytics in BFSI Market Emerging Trajectories
Self-service analytics platforms are redistributing decision authority from centralized data science teams to front-line underwriters and branch managers. This democratization is compressing insight-to-action cycles while introducing new governance complexities.
Natural language generation is bifurcating dashboard consumption patterns. The technology translates statistical outputs into narrative summaries for non-technical executives. Regional bank C-suites are adopting these interfaces faster than money-center peers, compressing the traditional business intelligence vendor landscape into specialized and generalist tiers.
The SEC's predictive data analytics rule is mandating algorithmic accountability disclosures for broker-dealer recommendations. Compliance teams are embedding model cards and bias detection checkpoints directly into production pipelines. US wealth management divisions are absorbing the largest compliance cost burdens, reconfiguring vendor selection criteria around auditability scores.
Relationship managers are bypassing centralized IT procurement for departmental analytics subscriptions. This shadow adoption pattern is fragmenting enterprise license negotiations and expanding vendor management complexity. The behavior is most pronounced in US commercial banking divisions where line-of-business autonomy remains culturally entrenched.
Augmented Analytics in BFSI Market Segmentation
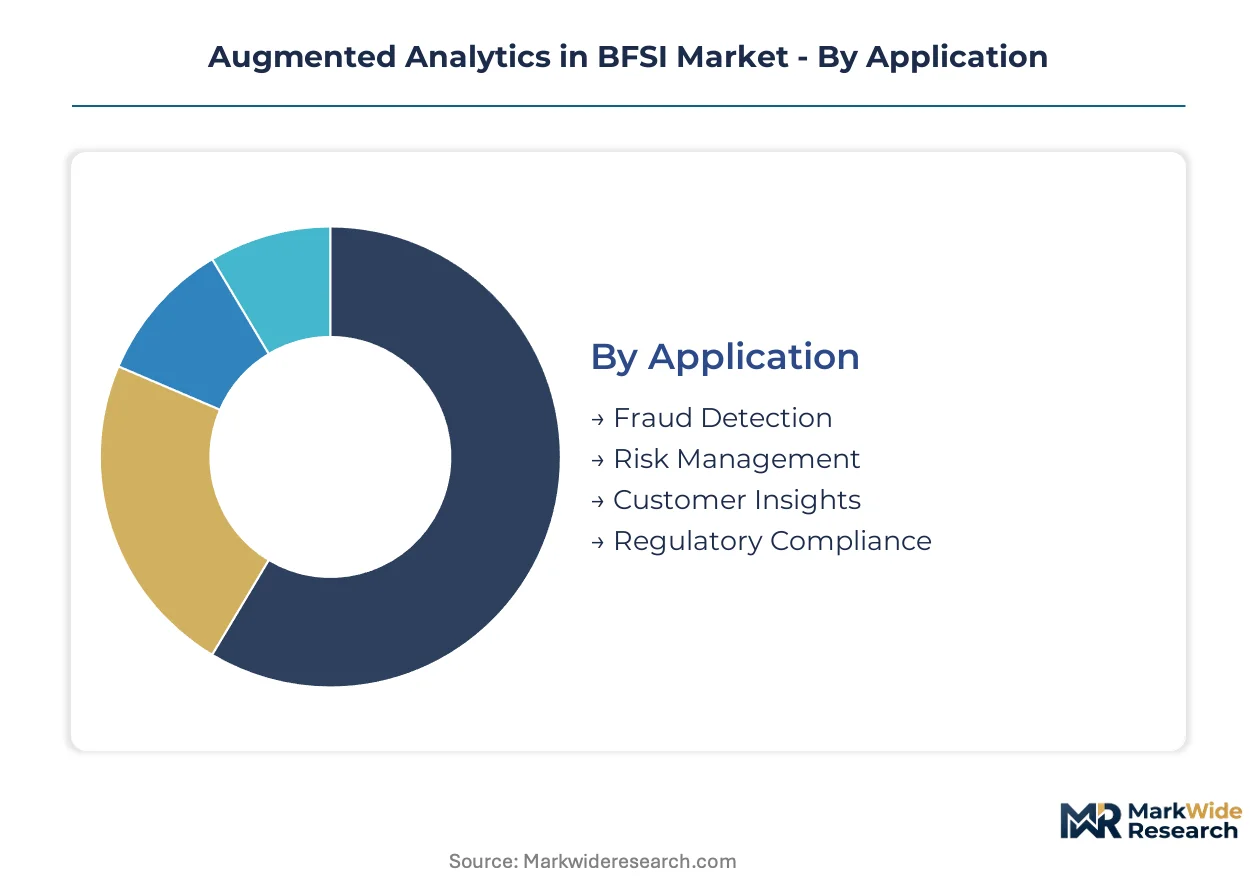
Segmentation in augmented analytics for BFSI reveals how procurement authority is fragmenting across line-of-business buyers, cloud architects, and compliance officers. Each dimension carries distinct vendor selection criteria, pricing tolerance, and integration complexity that reshape competitive positioning.
Application:
Fraud detection solutions face acute substitution pressure from specialized point solutions, while regulatory compliance modules benefit from vendor lock-in through audit trail dependencies.
- Fraud Detection:Real-time transaction monitoring systems employing anomaly detection algorithms process sub-second decision windows. Demand concentrates in US card issuers absorbing chargeback liability shifts, driven by network mandate deadlines for 3D Secure 2.0 compliance.
- Risk Management:Credit scoring and portfolio stress-testing platforms integrate alternative data streams for underwriting augmentation. European banks under ECB supervision are expanding procurement as climate risk stress-testing mandates harden.
- Customer Insights:Behavioral analytics for cross-sell optimization and churn prediction.
- Regulatory Compliance:Automated reporting and audit trail generation for Basel III, GDPR, and SEC disclosures.
Fraud detection retains volume leadership; regulatory compliance holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade deployments from modular subscriptions, with mid-market buyers demanding pre-configured industry templates.
- Banks:Universal and commercial banks deploy end-to-end platforms spanning data preparation through narrative generation. US money-center institutions are building captive data science centers, compressing external vendor spend for core analytics infrastructure.
- Insurance Companies:Property-casualty and life carriers embed telematics and wearables data into pricing models. Predictive analytics spend is climbing fastest as connected vehicle data streams mature in North American auto lines.
- Investment Firms:Asset managers and broker-dealers prioritizing alpha generation and execution optimization.
- Fintechs:Digital-native lenders and payment platforms with cloud-native architecture preferences.
Banks dominate current procurement volumes; insurance companies are gaining share fastest.
Deployment:
Volume concentration tilts toward hybrid architectures as regulatory uncertainty prolongs cloud commitment decisions.
- On-premises:Dedicated infrastructure configurations serving data sovereignty requirements. Swiss and German private banks bind sensitive workloads to domestic facilities, limiting SaaS vendor addressable markets in these jurisdictions.
- Cloud-based:Multi-tenant SaaS and single-tenant private cloud deployments. North American credit unions are accelerating hybrid cloud migrations, pulling Azure and AWS infrastructure investments into augmented analytics budgets.
- Hybrid:Split workloads across on-premises and cloud environments with orchestration layers.
- Managed Services:Fully outsourced analytics operations with SLAs for insight delivery and model maintenance.
Cloud-based deployments lead absolute spend; hybrid configurations are expanding most quickly.
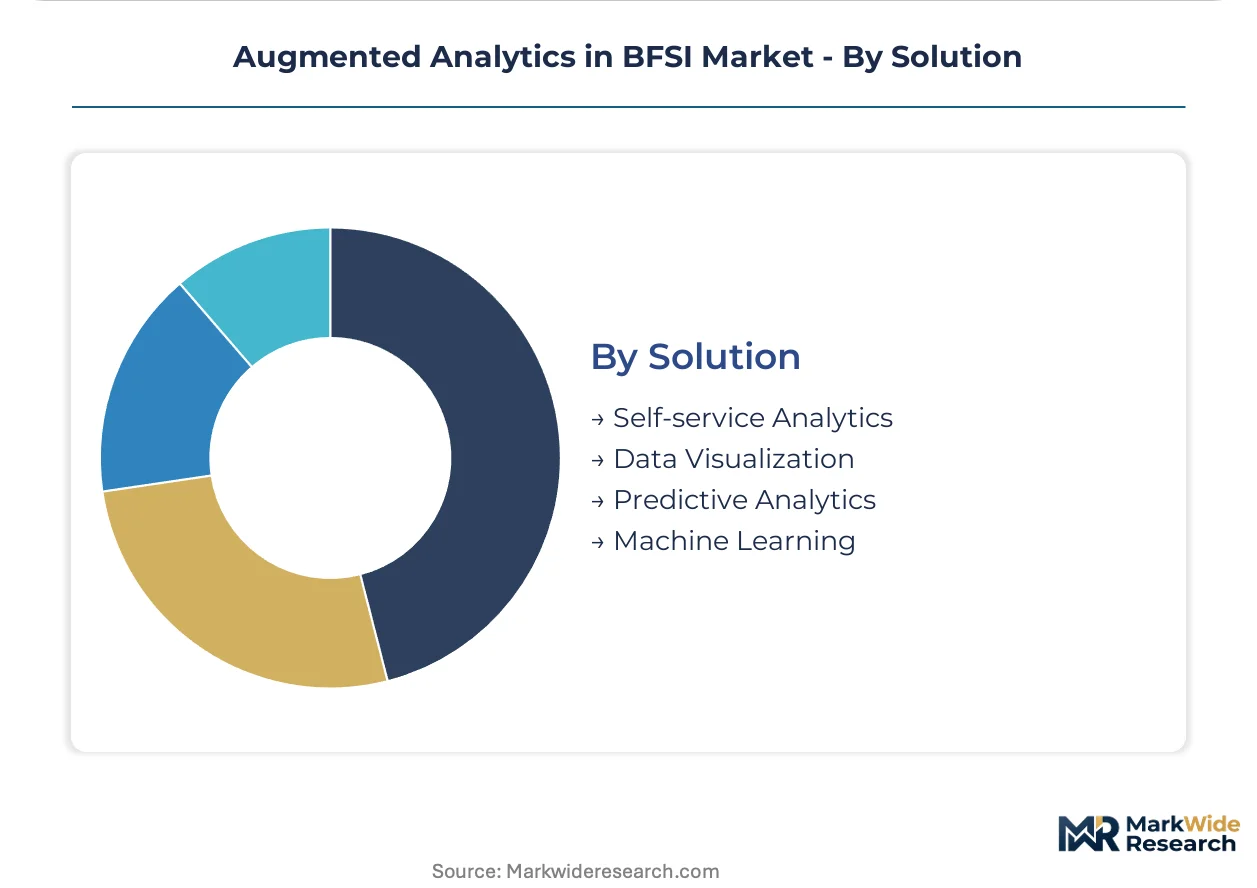
Solution:
Customer type divergence separates self-service democratization from centralized model governance, with procurement authority shifting toward departmental buyers.
- Self-service Analytics:Business-user-facing platforms enabling drag-and-drop exploration and automated insight generation. Regional bank branch managers and relationship managers are adopting these interfaces faster than money-center peers, compressing traditional BI vendor relevance.
- Predictive Analytics:Forward-looking models for forecasting, scenario simulation, and optimization. Insurers embedding IoT-driven pricing models are expanding category spend as telematics data streams achieve production scale.
- Data Visualization:Interactive dashboards and reporting layers for executive consumption.
- Machine Learning:Custom model development environments and MLOps pipelines for data science teams.
Self-service analytics commands the largest installed base; predictive analytics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory pressure from the EU AI Act and SEC algorithmic accountability rules is accelerating procurement cycles across banking centers. Jurisdictions with mature data governance frameworks command premium vendor attention, while emerging markets present white-space opportunities for modular deployments.
United States
JPMorgan Chase and Bank of America are building captive data science centers, compressing external vendor spend for core infrastructure. The SEC's predictive data analytics rule mandates algorithmic accountability disclosures for broker-dealer recommendations. New York and Charlotte banking clusters absorb the largest compliance cost burdens, reconfiguring vendor selection criteria around auditability scores.
Germany
ECB climate risk stress-testing mandates are expanding procurement of portfolio analytics platforms among supervised institutions. The EU AI Act's high-risk system obligations require embedded explainability modules in analytics workflows. Frankfurt's banking district anchors demand for quantum-safe encryption integration as tier-one banks prepare cryptographic transitions.
Switzerland
Private banks binding sensitive workloads to domestic facilities limit SaaS vendor addressable markets despite strong institutional wealth. FINMA guidance on operational resilience reinforces data sovereignty requirements for core banking analytics. Zurich and Geneva private banking clusters maintain on-premises configurations, preserving hybrid deployment complexity.
India
RBI algorithmic lending guidelines are opening captive data center buildouts as domestic banks modernize underwriting infrastructure. The central bank's regulatory sandbox framework permits controlled deployment of AI-driven credit scoring models. Mumbai and Bangalore financial technology corridors concentrate fintech-native platform adoption, pulling cloud infrastructure investments into augmented analytics budgets.
United Kingdom
FCA consumer duty rules are forcing wealth managers to demonstrate algorithmic fairness in recommendation engines. The Prudential Regulation Authority's operational resilience expectations extend to third-party analytics providers. London's asset management district is embedding model cards and bias detection checkpoints directly into production pipelines, expanding compliance overhead.
Augmented Analytics in BFSI Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, creating bifurcated procurement channels. Enterprise-grade vendors leverage decades of statistical computing heritage to anchor high-assurance government banking contracts, while cloud-native challengers exploit hybrid deployment architectures. Three archetypes dominate: heritage statistical computing houses, hyperscale cloud platforms, and vertical specialists in fraud detection. Competitive moves concentrate on quantum-safe encryption integration and ISO 27001 accreditation acceleration.
Within the heritage computing tier, SAS Institute exemplifies the high-assurance government contract anchor. Microsoft Corporation occupies a position across hybrid deployment architectures, particularly among North American credit unions accelerating cloud migrations. IBM Corporation represents the quantum-safe encryption specialization vector for tier-one bank pipelines. These three entities illustrate how certification heritage, cloud fabric extension, and cryptographic transition capabilities are reshaping competitive positioning.
| Leading Market Players |
|---|
| SAS Institute |
| Salesforce |
| Microsoft Corporation |
| Tableau |
| QlikTech International AB |
| SAP SE |
| Oracle Corporation |
| TIBCO Software |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 27001 certification gates both vendor qualification and price tiering across European and North American banking procurement, compressing emerging challengers into lower-margin segments while enterprise-grade platforms command premium positioning. This bifurcation concentrates pricing power with heritage statistical computing vendors and hyperscale cloud providers, leaving modular specialists to compete on implementation speed rather than solution depth.
Pricing Analysis
Certification level creates the primary spread between enterprise-grade and challenger pricing tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001 accreditation status, quantum-safe encryption integration, and embedded explainability module depth. Cost compression in the standard tier is intensifying because mid-market banks demand pre-configured industry templates without customization premiums. Community banks below $10 billion in assets exhibit the highest price sensitivity, while tier-one institutions prioritize auditability scores over license cost.
Supply Chain Analysis
The United States and India anchor cloud infrastructure provisioning for augmented analytics platforms, with Germany and Switzerland retaining on-premises hardware specialization for data sovereignty-bound deployments. Software supply draws from open-source ML frameworks, proprietary statistical computing engines, and quantum-safe cryptographic libraries. Single-source vulnerability concentrates in cloud orchestration layers controlled by hyperscale providers. Distribution runs through direct enterprise sales teams for tier-one banks, while regional credit unions and community banks source through value-added resellers and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority fragmentation across line-of-business buyers, compliance officers, and cloud architects is creating niche entry points for specialized vendors outside the heritage computing tier. This demand-side shift rewards modular deployment capabilities over monolithic platform breadth.
For Market Incumbents: Compound certification heritage into quantum-safe encryption integration pipelines, accelerating ISO 27001 accreditation programs for partner ecosystems to defend against cloud-native challengers exploiting hybrid deployment architectures. Deepen vertical integration into MLOps tooling to capture professional services revenue currently leaking to system integrators. Prioritize captive data center co-location offerings for Swiss and German private banks resisting cloud migration. For New Entrants and Emerging Players: Lead with natural language interface convergence targeting relationship managers in US commercial banking divisions, where shadow adoption patterns bypass centralized IT procurement. Target community banks below $10 billion asset thresholds with pre-configured fraud detection templates requiring minimal implementation services. Position through departmental subscription models rather than enterprise license negotiations to exploit line-of-business autonomy. For Investors and Strategic Acquirers: The EU AI Act's high-risk system obligations reshape the acquisition landscape toward vendors with embedded explainability modules and production-grade audit trails. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than algorithmic performance alone. Target acquisition candidates combining vertical specialization in telematics-driven insurance pricing with cloud-native architecture. Watch RBI algorithmic lending guideline enforcement as the signal indicating Indian market readiness for scaled platform deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Encryption Integration | Frankfurt's tier-one banks prioritize cryptographic transition readiness in vendor selection scoring. |
| Natural Language Interface Development | Regional bank C-suites adopt narrative generation faster than money-center peers, compressing BI vendor relevance. |
| Captive Data Center Buildout | Mumbai and Bangalore corridors pull cloud infrastructure investments into domestic underwriting modernization. |
| ISO 27001 Accreditation Acceleration | Government banking contract eligibility gates revenue access for emerging platform vendors. |
| Telematics Data Pipeline Integration | North American auto insurers expand predictive analytics spend as connected vehicle streams mature. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, ECB supervisory disclosures, RBI circulars, and hyperscaler capex reports. Chief data officers, compliance leads at tier-one banks, cloud procurement officers at North American credit unions, and integration specialists at system integrators provided structured input. Bottom-up sizing of deployment volumes triangulates against top-down IT budget allocation analysis across banking, insurance, and investment firm segments.
Segmentation dimensions modeled span application type, end-user institution category, deployment architecture, and solution modality across the projection horizon. CAGRs derive from logistic adoption curve fitting against regulatory deadline schedules and cloud migration velocity indicators. Forecast inputs incorporate algorithmic lending guideline enforcement trajectories, climate risk stress-testing mandate expansion, and telematics data stream commercialization timelines.
Forecasts assume regulatory continuity in EU AI Act implementation, SEC predictive data analytics rule enforcement, and RBI algorithmic lending frameworks; material policy shifts would require re-modeling. Specific risk factors include divergent national AI governance frameworks reshaping cross-border software licensing, quantum computing advancement accelerating cryptographic transition deadlines, and talent scarcity inflating implementation timelines beyond modeled assumptions. Recalibration cycles align with material shifts in regulatory enforcement patterns and cloud provider infrastructure expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Network Analytics Services Market
Analytics
Cyprus ICT Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
UK Video Analytics Market
Analytics
Global Customer Analytics Market
Analytics
Cloud Performance Management Market
Analytics
Geospatial Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Contact Center Analytics Market
Analytics
Legal Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Europe Speech Analytics Market
Analytics
Global Telco Data Monetization Market
Analytics
Global in-Store Analytics Market
Analytics
Multi-Touch Attribution Market
Analytics
Regression Analysis Tool Market