
 Webcasting Software Market | 2026-2036
Webcasting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Webcasting Software Market Insights
Multi-source procurement for streaming infrastructure is shifting toward bundled platform subscriptions as enterprises consolidate vendor relationships. Cisco Webex leverages its hardware-software integration to anchor large-deployment accounts. Zoom Webinars competes through aggressive channel partnerships with event-management agencies. ON24 specializes in data-rich engagement workflows that differentiate its offering for B2B marketing use cases.
Webcasting software delivers real-time audiovisual transmission over IP networks, typically supporting 720p to 4K resolution, adaptive bitrate streaming, and concurrent viewer counts exceeding 10,000 participants for single events. Its primary commercial purpose is to replicate or extend the reach of physical presentations, training sessions, and shareholder meetings to distributed audiences without requiring dedicated broadcast infrastructure. Cloud-Based deployment leads the feature dimension because IT departments prioritize elastic scaling and zero-maintenance updates over capital-intensive on-premise installations. Engagement Tools within the Feature segment command attention from product teams, since interactive polling, Q&A moderation, and gamified feedback loops directly correlate with customer retention metrics and renewal rates.
FCC guidelines on closed-captioning accessibility, GDPR data-processing requirements enforced by European regulators, and HIPAA safeguards for healthcare transmissions in the United States collectively shape product roadmaps and territorial go-to-market strategies. Vendors must certify compliance with these frameworks before accessing procurement pipelines in regulated sectors such as government, healthcare, and financial services. Stakeholders should monitor how emerging AI-generated content disclosure rules and evolving cross-border data-localization mandates will alter feature development priorities and hosting architecture decisions.
Market Dynamics
Enterprise IT consolidation is compressing vendor relationships from multi-source streaming infrastructure toward unified platform subscriptions, forcing specialized webcasting vendors to embed deeper into collaboration suites or risk displacement.
Growth Catalysts
- GDPR-Aligned Data Residency Mandates:European enterprises now require region-locked hosting for webcasting data, creating procurement preference for vendors with certified EU data centers in Germany, France, and the Netherlands.
- Healthcare Transmission Expansion:HIPAA-covered entities in the United States are deploying webcasting for remote patient education and clinical training, driving demand for encrypted, audit-logged platforms.
- Adaptive Bitrate Streaming Maturation:The technology enables 4K-quality delivery over variable consumer bandwidth, removing infrastructure barriers for mass-audience corporate events previously limited to broadcast television.
Market Restraints
- Cloud Concentration Risk:Three hyperscale providers control over 70 percent of underlying streaming infrastructure, creating single-point-of-failure exposure for webcasting platforms dependent on their edge networks.
- FCC Closed-Captioning Compliance Costs:Real-time captioning accuracy requirements for live webcasts impose per-minute transcription expenses that compress margins on high-volume, low-ticket events.
- Latency-Quality Tradeoffs:Sub-five-second streaming delays required for interactive polling degrade video resolution, limiting use cases where simultaneous broadcast fidelity and audience participation are both mandatory.
Strategic Opportunities
- AI-Generated Content Disclosure Rules:Emerging regulatory frameworks in the European Union and United States will mandate labeling of synthetic media in webcasts, creating first-mover advantage for platforms with built-in provenance verification.
- Japan's Hybrid Event Infrastructure:Corporate culture in Tokyo and Osaka sustains demand for simultaneous physical-virtual event formats underserved by Western-centric platform designs.
- Edge Computing Convergence:Integration of localized processing nodes with webcasting stacks enables sub-second latency for factory-floor training applications in German automotive and Japanese electronics manufacturing.
Industry Challenges
- Real-Time Encoding Specialist Scarcity:Talent capable of optimizing H.265 and AV1 codecs for live streaming commands premium compensation, constraining platform engineering velocity.
- Legacy Video Conferencing Migration Complexity:Enterprises running decade-old on-premise telepresence systems face data migration and user retraining costs that delay webcasting platform replacement cycles.
- Cross-Border Data Localization Friction:Conflicting sovereignty requirements between German BSI standards, French CNIL guidance, and emerging Indian data-protection rules fragment hosting architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Webcasting Software Market |
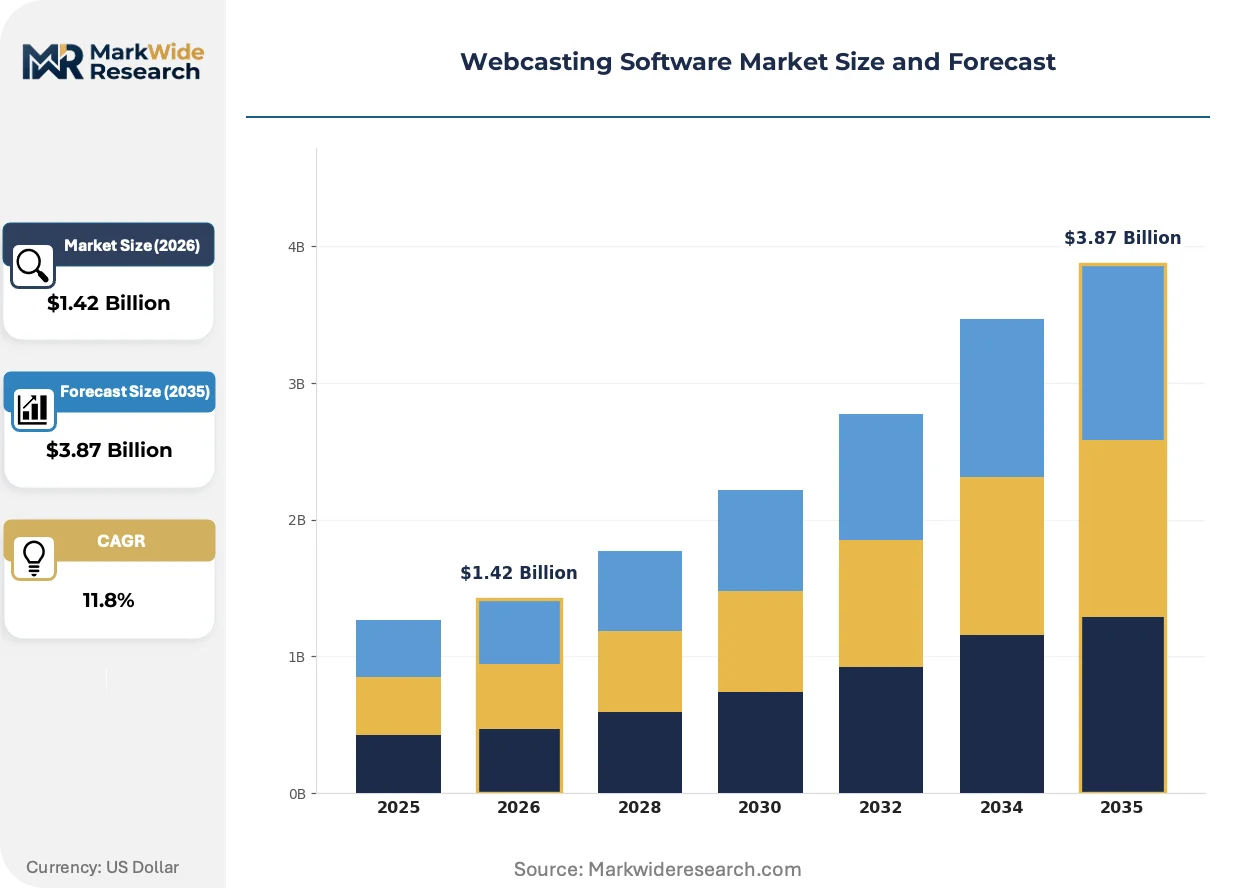
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Corporate, Education, Government, Healthcare Feature: Live Streaming, Recording, Analytics, Engagement Tools Service Type: Technical Support, Consulting, Customization, Training |
| Companies Covered | Cisco Webex, BigMarker, ClickMeeting, Zoho Meeting, Microsoft Teams, Zoom Webinars, ON24, WebinarNinja, GoToWebinar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Webcasting Software Market Trends and Innovations
Artificial intelligence is embedding throughout the webcasting stack, from automated content moderation to predictive bandwidth allocation, compressing production timelines and expanding self-service deployment.
Edge-native streaming architecture is unifying content ingestion, transcoding, and delivery into geographically distributed nodes. Manufacturing and energy sector buyers in Germany and Japan are adopting these stacks for site-specific training broadcasts that cannot tolerate public internet latency. The technology is unifying what previously required separate CDN, encoding, and origin-server contracts into single-vendor edge deployments.
The EU AI Act's transparency requirements for automated decision-making systems are forcing webcasting platforms to document algorithmic content recommendations and automated moderation actions. Vendors serving financial services and government sectors in France and Germany must now maintain audit trails for AI-driven Q&A filtering and speaker prioritization. Healthcare webcast providers face overlapping compliance with both AI Act documentation mandates and HIPAA audit requirements for patient-facing content.
Enterprise buyers are consolidating event technology spend through centralized procurement functions that evaluate webcasting alongside virtual event management and audience analytics. Marketing operations teams in United States technology and pharmaceutical verticals are displacing point-solution webcasting contracts with bundled platform subscriptions spanning registration, streaming, and post-event engagement. This concentration is most visible in California and Massachusetts, where SaaS procurement centralization has advanced fastest among Fortune 500 headquarters clusters.
Webcasting Software Market Segmentation
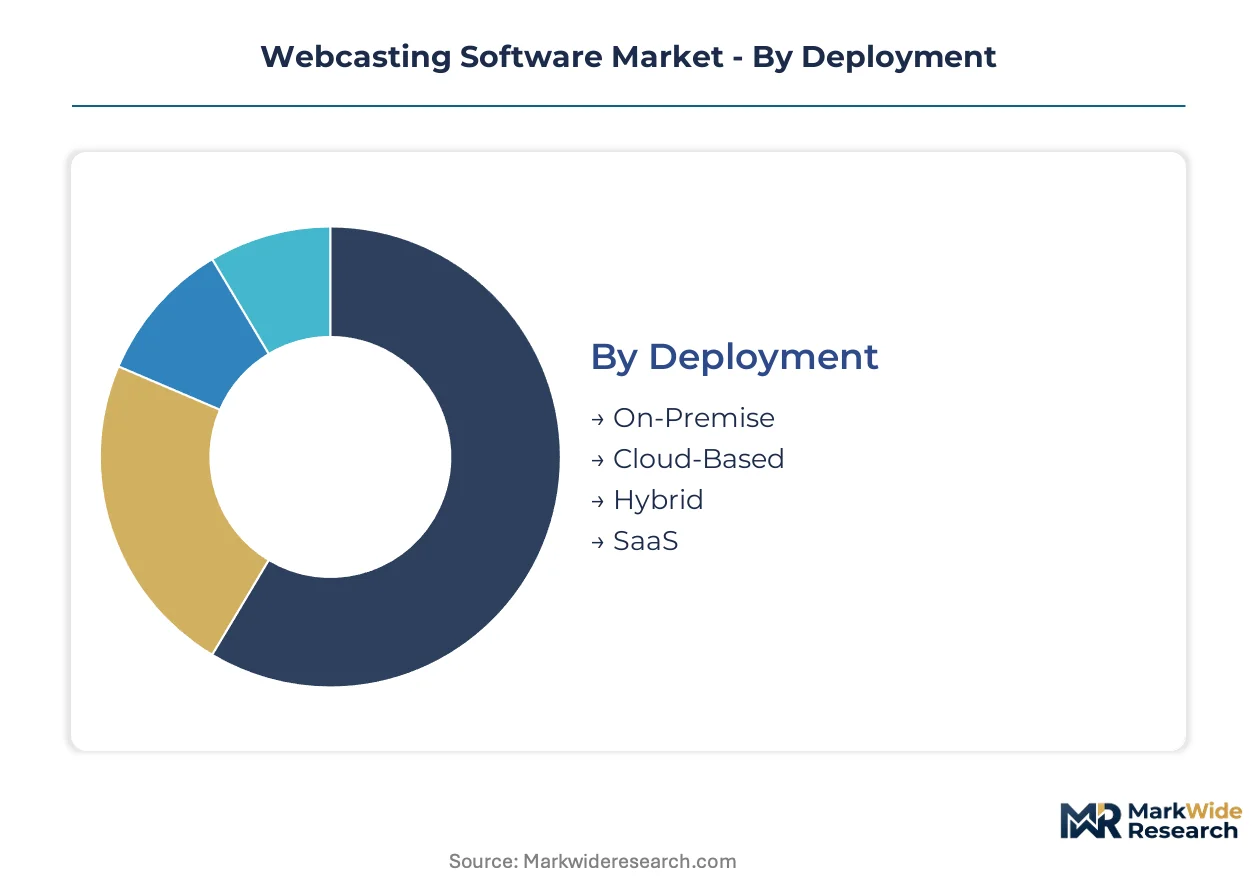
Webcasting software procurement varies sharply by deployment architecture and end-use compliance burden. Buyers in regulated sectors weight certification requirements differently than commercial enterprises, creating tiered pricing and feature packaging across segments.
Deployment:
Cloud-Based deployments require GDPR certification for EU data residency, while On-Premise installations demand SOC 2 Type II attestation for financial services procurement.
- Cloud-Based:Elastic infrastructure hosted across AWS, Azure, or Google Cloud regions enables automatic scaling from hundreds to tens of thousands of concurrent viewers. German automotive manufacturers and Japanese electronics firms favor this model for zero-maintenance updates and region-locked EU data centers meeting BSI standards.
- SaaS:Multi-tenant subscription platforms deliver pre-configured webcasting stacks through browser-based access. United States pharmaceutical marketing teams and United Kingdom financial services compliance officers prioritize this segment for rapid deployment without infrastructure procurement cycles.
- On-Premise:Dedicated hardware installations in enterprise data centers serve classified government briefings and HIPAA-covered hospital networks requiring air-gapped transmission paths.
- Hybrid:Split architectures route sensitive content through private infrastructure while leveraging public cloud edge nodes for global distribution, common among French defense contractors and Canadian provincial healthcare authorities.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
Corporate buyers concentrate spend in bundled platform subscriptions, while Healthcare and Government segments impose specialized compliance documentation.
- Corporate:Fortune 500 technology and pharmaceutical headquarters in California and Massachusetts consolidate event technology procurement through centralized marketing operations functions. These buyers displace point-solution contracts with integrated registration, streaming, and analytics platforms.
- Healthcare:HIPAA-covered entities in Texas and Florida deploy encrypted, audit-logged webcasting for remote patient education and clinical training programs. Real-time captioning accuracy requirements impose per-minute transcription costs that compress margins on high-volume medical seminars.
- Education:University IT departments in Massachusetts and Oxford select platforms with LMS integration and automated lecture capture for hybrid learning models.
- Government:Federal agencies in Washington DC and Brussels-based EU institutions mandate FedRAMP or equivalent sovereignty certifications for classified briefing distribution.
Corporate captures the largest revenue share, with Healthcare expanding most quickly.
Feature:
Engagement Tools command premium pricing due to direct correlation with customer retention metrics, while Analytics faces commoditization pressure.
- Engagement Tools:Interactive polling, Q&A moderation, and gamified feedback loops differentiate platforms for B2B marketing use cases. ON24 specializes in data-rich engagement workflows that track prospect behavior across multi-touch event sequences.
- Live Streaming:Adaptive bitrate technology enables 4K-quality delivery over variable consumer bandwidth. Manufacturing buyers in Stuttgart and Osaka factory floors require sub-second latency for real-time training broadcasts.
- Recording:Automated post-event editing and searchable transcript generation serve compliance documentation needs in legal and financial services verticals.
- Analytics:Attendee engagement scoring and pipeline attribution dashboards face integration pressure from standalone business intelligence platforms.
Live Streaming dominates current deployments, with Engagement Tools gaining share fastest.
Service Type:
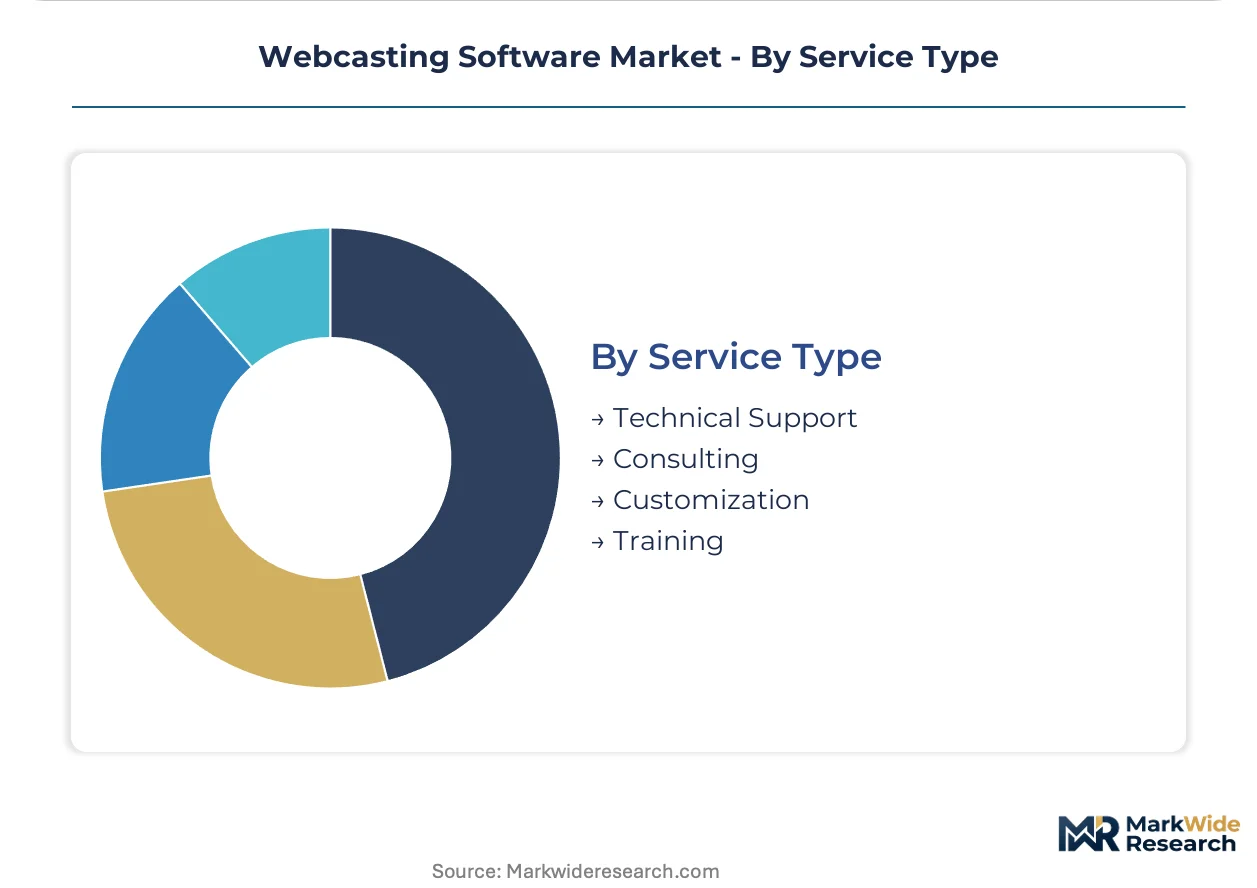
Technical Support and Customization segments fragment by buyer sophistication, with Consulting concentrated in complex multi-vendor integrations.
- Technical Support:Tiered response-time guarantees differentiate premium from standard service levels. Enterprise accounts in New York and London financial districts negotiate dedicated engineering liaisons for mission-critical shareholder meetings.
- Consulting:Change management and workflow redesign services assist legacy video conferencing migration from decade-old on-premise telepresence systems. German automotive and Japanese electronics manufacturers utilize these services for edge computing convergence projects.
- Customization:White-label branding and API integration development serve marketing agencies managing client event portfolios across multiple simultaneous webcasts.
- Training:Administrator certification and end-user onboarding programs reduce support ticket volume for self-service platform deployments.
Technical Support leads service revenue, with Consulting showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping hosting architecture decisions as vendors seek cost-efficient compliance with divergent data-sovereignty mandates. Enterprises in jurisdictions with lighter certification burdens attract platform investment, while strict regimes like Germany and France command premium pricing for certified infrastructure.
United States
FCC closed-captioning requirements and HIPAA safeguards for healthcare transmissions create dual compliance tracks for domestic vendors. California and Massachusetts technology headquarters consolidate procurement through centralized marketing operations, displacing point-solution contracts with bundled platform subscriptions. Texas and Florida healthcare systems deploy encrypted webcasting for remote patient education, driving demand for audit-logged platforms with real-time captioning accuracy.
Germany
BSI standards and GDPR-aligned data residency mandates require region-locked hosting in certified EU data centers. Stuttgart automotive manufacturers favor cloud-based deployments with zero-maintenance updates for factory-floor training broadcasts. Bavarian industrial clusters adopt edge-native streaming architecture to achieve sub-second latency for real-time equipment demonstrations.
Japan
METI industrial guidance and corporate culture in Tokyo and Osaka sustain demand for simultaneous physical-virtual event formats. Japanese electronics manufacturers utilize edge computing convergence for site-specific training broadcasts that cannot tolerate public internet latency. Kansai region factory floors require localized processing nodes to enable real-time quality assurance demonstrations.
United Kingdom
Post-Brexit data-protection alignment creates procurement friction for platforms serving both UK and EU enterprises. London financial services compliance officers prioritize SaaS deployments for rapid rollout without infrastructure procurement cycles. Oxford and Cambridge university IT departments select platforms with LMS integration for hybrid learning models.
France
CNIL guidance and EU AI Act transparency requirements force documentation of algorithmic content recommendations for government and financial services sectors. Paris-based defense contractors adopt hybrid architectures routing sensitive content through private infrastructure while leveraging public cloud edge nodes. Île-de-France pharmaceutical marketing teams demand engagement tools with prospect behavior tracking across multi-touch event sequences.
Webcasting Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent collaboration-suite integration. The vendor base clusters around three strategic archetypes: hardware-software integrated suites, data-rich engagement specialists, and browser-first SaaS platforms. Consolidation pressure from enterprise IT procurement functions favors bundled subscriptions over point solutions. Dominant competitive moves include strategic partnerships with event-management agencies and API-based embedding into broader productivity ecosystems.
Within the hardware-integrated tier, Cisco Webex and Microsoft Teams exemplify platform consolidation strategies. Zoom Webinars occupies a position among aggressive channel partnership models. ON24 sits within the data-rich engagement specialist archetype. These three anchors illustrate how vendor differentiation increasingly depends on workflow depth rather than streaming infrastructure alone.
| Leading Market Players |
|---|
| Cisco Webex |
| BigMarker |
| ClickMeeting |
| Zoho Meeting |
| Microsoft Teams |
| Zoom Webinars |
| ON24 |
| WebinarNinja |
| GoToWebinar |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement consolidation toward bundled platform subscriptions is compressing vendor margins and forcing hyperscale infrastructure commitments that reshape cost structures across the webcasting stack.
Pricing Analysis
Input-cost pass-through from hyperscale cloud infrastructure fees and real-time transcription services shapes SaaS-tiered subscription models across the market. Pricing stratifies across enterprise-grade, mid-market, and self-service tiers based on concurrent viewer capacity and GDPR certification level. Cost compression in the mid-market tier is intensifying because channel partners demand volume rebates for event-management agency portfolios. Healthcare and government buyers show least price sensitivity due to mandatory HIPAA and FedRAMP compliance requirements that eliminate unqualified vendors.
Supply Chain Analysis
Direct-to-enterprise channels handle Fortune 500 demand while agency-mediated distribution serves mid-market marketing operations. Cloud infrastructure concentrates in the United States, Germany, and Japan where certified data centers satisfy GDPR and BSI sovereignty mandates. The stack draws from hyperscale compute, specialized H.265/AV1 encoding hardware, and real-time captioning API services. Single-source vulnerability in edge network provisioning creates concentration exposure when three providers control underlying streaming infrastructure. Distribution runs through platform-native marketplaces and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as enterprise buyers mandate sub-second latency and AI-generated content provenance verification, elevating late-cycle differentiation over price competition.
For Market Incumbents: Hedge against displacement by embedding deeper into Microsoft Teams and Salesforce ecosystems through API-first architecture. Invest in EU data center certification to defend procurement pipelines against GDPR-aligned residency mandates. Prioritize edge-native streaming stacks for German automotive and Japanese electronics manufacturing accounts.
For New Entrants and Emerging Players: Capture white-space in hybrid event infrastructure serving Japan's simultaneous physical-virtual corporate culture. Target underpenetrated edge computing convergence projects for factory-floor training applications. Lead with localized processing nodes and sub-second latency guarantees as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with data-rich engagement specialists possessing proprietary behavioral analytics and multi-touch attribution engines. Long-term viability hinges on workflow depth rather than streaming infrastructure ownership. Monitor AI-generated content disclosure rule implementation as the critical inflection signal for compliance-ready platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API embedding into Microsoft Teams and Salesforce ecosystems secures enterprise retention. |
| Geographic Expansion | Certified EU data centers in Germany unlock GDPR-constrained procurement pipelines. |
| Acquisition of Specialist Firm | Edge computing startups enable sub-second latency for factory-floor training broadcasts. |
| Product Launch | AI provenance verification tools capture first-mover advantage under emerging EU AI Act rules. |
| Strategic Partnership | Channel alliances with event-management agencies accelerate mid-market penetration. |
Research Methodology
Bottom-up enterprise IT procurement modeling reconciled against top-down hyperscale infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners were cross-validated against secondary sources including SEC filings, hyperscaler capex disclosures, and GDPR certification registries. Triangulation between demand-side deployment surveys and supply-side capacity announcements ensures segmentation integrity.
Input-output matrices map deployment architecture, end-use vertical, and feature dimension to concurrent viewer capacity and pricing tier across the projection horizon. Segmentation dimensions include cloud versus on-premise deployment, corporate versus healthcare versus government end-use, and engagement tools versus live streaming versus analytics feature sets. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Forecast inputs incorporate GDPR enforcement intensity and AI Act transparency requirement timelines.
Regulatory enforcement delays, hyperscale pricing volatility, and enterprise procurement freeze decisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding cloud migration velocity and compliance certification adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Human Identification Analysis Software Market
Software & Services
Global CMDB Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Global Voting Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Content Curation Software Market
Software & Services
Global Data Quality Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Workshop Management Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Vacation Rental Software Market