
 Asia-Pacific Algae Omega-3 Ingredient Market | 2026-2036
Asia-Pacific Algae Omega-3 Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Algae Omega-3 Ingredient Market Outlook
Modular capsule-and-powder bundling is consolidating buyer choice across the Asia-Pacific algae omega-3 landscape, as brands seek flexible dosing formats for diverse consumer segments. DSM Nutritional Products leverages its fermentation technology leadership to anchor supply security for high-DHA strains. Xiamen Huison Biotech Co Ltd sustains cost-competitive cultivation at scale across Fujian province. BASF SE differentiates through pharmaceutical-grade certification pipelines that command premium positioning in regulated channels.
Asia-Pacific algae omega-3 ingredients comprise lipid extracts from phototrophic or heterotrophic microalgae, typically yielding eicosapentaenoic acid and docosahexaenoic acid concentrations between 15% and 50% by oil weight through controlled fermentation or raceway pond cultivation, primarily serving human nutraceutical and functional food fortification applications. Oil formats currently occupy the largest share of finished goods value, while powder forms are gaining fastest in infant formula and sports nutrition applications where dispersion stability matters. Pharmaceutical grade commands the deepest margin pool due to batch-level DHA verification and contaminant screening protocols that exceed food-grade thresholds.
China's SAMR enforces novel food ingredient registrations for algae-derived DHA oils, while Australia's TGA governs complementary medicine claims and therapeutic good manufacturing practice for omega-3 finished products. India's FSSAI and CDSCO jointly oversee import purity standards and health supplement labeling, creating a multi-layered compliance architecture that shapes regional market access costs. Stakeholders must monitor divergence between national pharmacopeial specifications and emerging harmonization efforts across ASEAN member states.
Market Dynamics
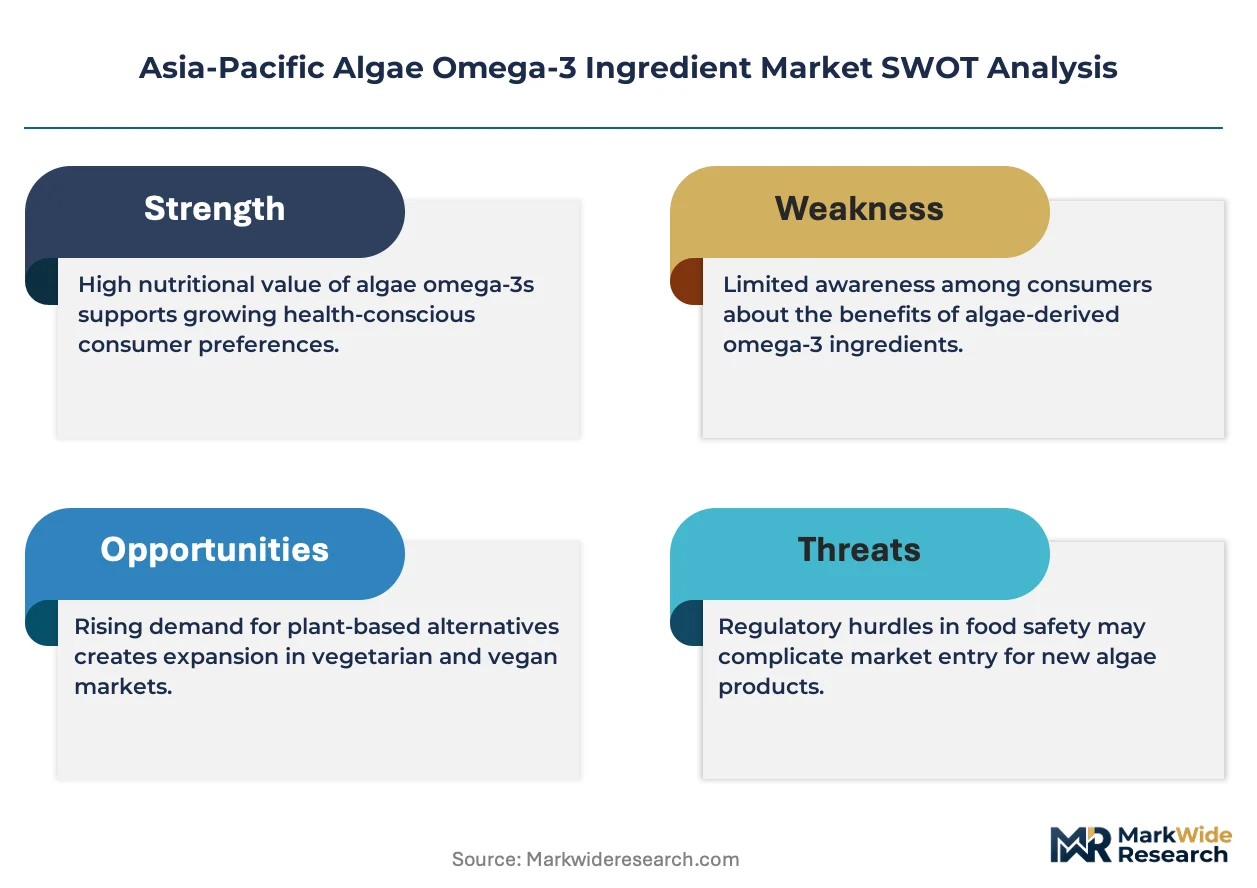
China's tightening GB standards for novel food ingredients are compressing supplier margins while accelerating consolidation among fermentation-capable producers across the Asia-Pacific algae omega-3 landscape.
Growth Catalysts
- SAMR Novel Food Registrations:China's mandatory approval pathway for algae-derived DHA oils is filtering out subscale suppliers and rewarding batch-traceable producers with preferred supplier status among infant formula manufacturers.
- Phototrophic Cultivation Advances:Raceway pond optimization in Fujian and Hainan provinces is reducing per-kilogram DHA extraction costs for regional contract manufacturers serving Australian nutraceutical brands.
- Sports Nutrition Powder Demand:Dispersion-stable microencapsulation formats are penetrating protein premix applications across Southeast Asian functional food processors seeking clean-label omega-3 fortification.
Market Restraints
- Heterotrophic Feedstock Volatility:Glucose and yeast extract input costs fluctuate with Brazilian sugarcane harvest cycles, compressing margins for fermentation-based producers during Q2-Q3 procurement windows.
- Concentrated Strain Ownership:Proprietary high-DHA Schizochytrium and Crypthecodinium strains remain concentrated among three global technology licensors, limiting independent cultivation expansion across Asia-Pacific.
- Fish Oil Price Arbitrage:Peruvian anchovy catch recoveries periodically collapse the omega-3 price spread, triggering buyer switching toward marine sources in cost-sensitive Southeast Asian markets.
Strategic Opportunities
- India's FSSAI Supplement Window:Health supplement notification pathways are opening for algae DHA powders, creating first-mover positioning for suppliers establishing analytical partnerships with Mumbai and Hyderabad testing laboratories.
- TGA Pharmaceutical-Grade Pipeline:Australia's complementary medicine GMP certification is enabling premium positioning for batch-verified DHA oils targeting prescriptive nutraceutical channels.
- ASEAN Harmonization Momentum:Emerging mutual recognition frameworks for novel food safety assessments are reducing redundant registration burdens across Thailand, Vietnam, and Indonesia.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial bioprocess engineers with heterotrophic algae experience command premium compensation across Guangdong and Jiangsu province manufacturing clusters.
- Pharmaceutical-Grade Certification Timelines:Batch-level DHA verification and contaminant screening protocols exceed 18-month validation cycles, delaying revenue recognition for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Algae Omega-3 Ingredient Market |
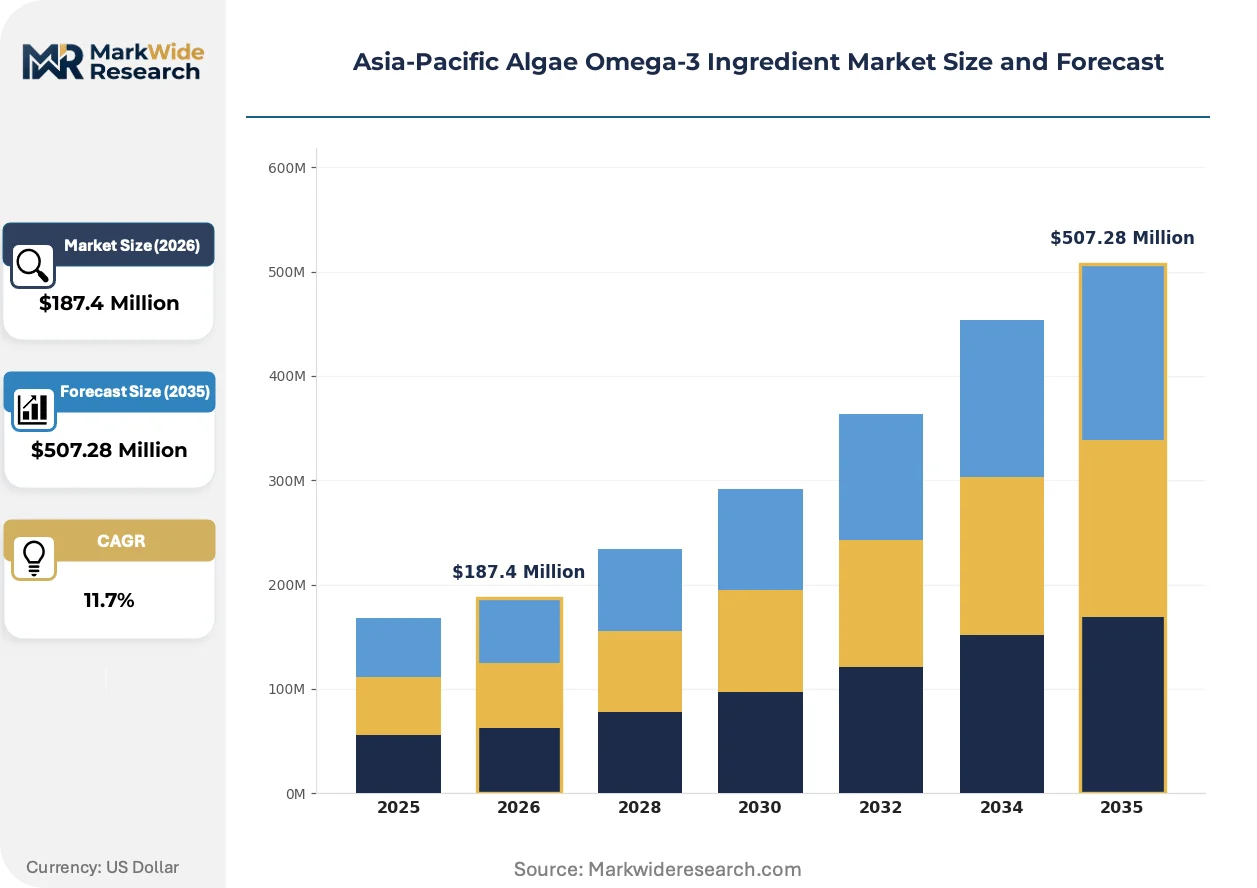
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Capsules, Emulsions End User: Food & Beverage, Dietary Supplements, Pharmaceuticals, Animal Feed Grade: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade Form: Liquid, Solid, Gel, Paste |
| Companies Covered | BASF SE, Nordic Naturals Inc, Archer Daniels Midland Company, SIMRIS ALG AB, Qponics Limited, DSM Nutritional Products, Xiamen Huison Biotech Co Ltd, Beijing Gingko Group Co. Ltd., Corbion NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Algae Omega-3 Ingredient Market Strategic Shifts
Controlled fermentation technology is displacing open-pond cultivation across high-value applications, while regulatory fragmentation between national pharmacopeial standards forces suppliers to maintain parallel compliance architectures.
Precision fermentation using metabolically engineered oleaginous yeast strains is converging with traditional microalgae cultivation, enabling hybrid production systems that combine the strain stability of heterotrophic platforms with the lipid profile diversity of phototrophic sources. Australian contract manufacturers are piloting these integrated bioreactor configurations for pharmaceutical-grade DHA output. The structural consequence is a compression of minimum efficient scale thresholds, allowing mid-cap regional suppliers to achieve cost parity with legacy pond operators.
China's SAMR is tightening contaminant screening thresholds for algae-derived novel food ingredients, mirroring EFSA's evolving specifications for 3-MCPD esters and glycidyl esters in refined oils. This regulatory convergence is forcing extraction technology upgrades across Fujian and Shandong processing facilities. Infant formula ingredient suppliers are responding by investing in molecular distillation and supercritical CO2 purification capacity ahead of anticipated 2025 enforcement windows.
Direct procurement relationships between finished brands and fermentation operators are displacing traditional ingredient distributor networks across Southeast Asia. Dietary supplement manufacturers in Thailand and Vietnam are establishing volume-commitment contracts with Chinese cultivation facilities, bypassing Singapore-based trading houses that historically controlled regional supply allocation. This channel restructuring is most visible in Australia's nutraceutical contract manufacturing corridor, where brands now specify strain provenance and batch analytics in master service agreements.
Asia-Pacific Algae Omega-3 Ingredient Market Segmentation
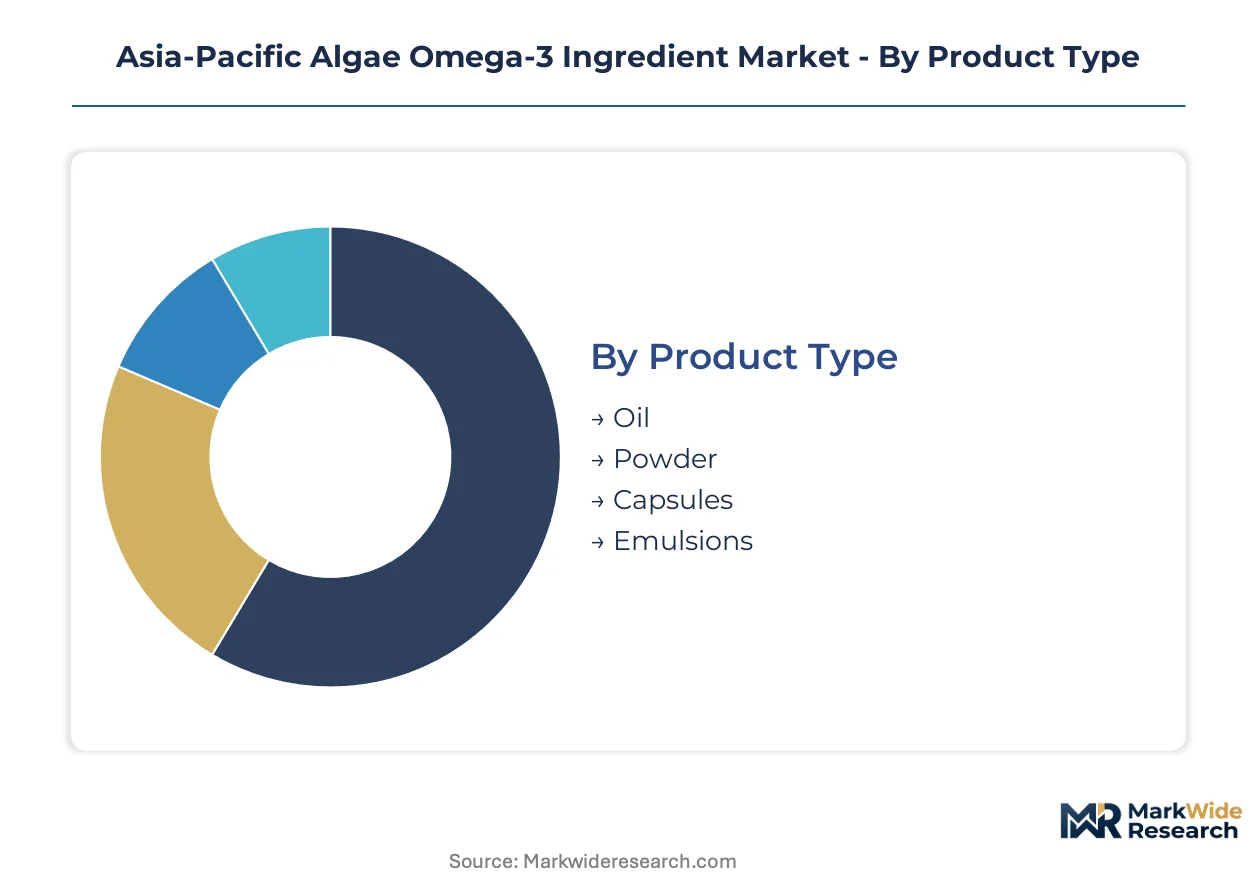
Segmentation in the Asia-Pacific algae omega-3 market reveals how purity thresholds, application requirements, and formulation constraints fragment procurement behavior across infant formula manufacturers, sports nutrition brands, and pharmaceutical compounders.
Product Type:
Buyers differentiate primarily by bioavailability requirements and processing compatibility with their finished goods manufacturing lines.
- Oil:Concentrated lipid extracts containing 15-50% DHA by weight serve as the baseline input for softgel encapsulation and functional food fortification across Australian nutraceutical contract manufacturers. Demand concentrates in China's infant formula sector where SAMR-mandated novel food registrations favor established oil suppliers with batch-traceable documentation.
- Powder:Microencapsulated formats with dispersion-stable matrices penetrate protein premix and instant beverage applications across Southeast Asian functional food processors. Thailand and Vietnam sports nutrition manufacturers specify powder forms for clean-label omega-3 fortification where oil integration would compromise texture.
- Capsules:Pre-formed softgel and hard-shell delivery systems reduce in-house processing burden for smaller dietary supplement brands lacking encapsulation capacity.
- Emulsions:Aqueous-dispersible lipid droplets enable beverage fortification and medical nutrition applications requiring homogenous suspension stability.
Oil leads volumes today; powder is gaining share fastest across the Asia-Pacific formulation landscape.
End User:
Application-specific regulatory pathways and margin structures determine supplier prioritization across buyer categories.
- Dietary Supplements:Capsule and softgel finished goods dominate procurement from Southeast Asian contract manufacturers seeking flexible dosing formats for diverse consumer segments. India's FSSAI notification pathways for health supplements are opening volume commitments with Mumbai and Hyderabad testing laboratories.
- Food & Beverage:Infant formula fortification commands stringent purity benchmarks under China's tightening GB standards, while sports nutrition applications favor dispersion-stable powder formats. Fujian province cultivation facilities direct output toward food-grade specifications exceeding baseline contaminant thresholds.
- Pharmaceuticals:Batch-level DHA verification and 18-month certification timelines restrict supply to fermentation-capable producers with pharmaceutical-grade purification capacity.
- Animal Feed:Cost-sensitive aquaculture and pet nutrition applications absorb lower-purity streams from open-pond cultivation operations.
Dietary supplements anchor current procurement volumes; food and beverage applications are expanding most quickly.
Grade:
Certification intensity and analytical documentation requirements stratify pricing and supplier qualification barriers.
- Pharmaceutical Grade:Batch-level DHA verification and contaminant screening protocols exceeding food-grade thresholds command premium positioning in Australia's TGA-regulated complementary medicine channels. Australia's nutraceutical contract manufacturing corridor specifies pharmaceutical-grade certification in master service agreements.
- Food Grade:Novel food ingredient registrations under China's SAMR filter subscale suppliers and reward batch-traceable producers with preferred status among infant formula manufacturers.
- Feed Grade:Lower analytical burden suits aquaculture and pet nutrition applications where cost minimization outweighs documentation intensity.
- Industrial Grade:Technical applications in cosmetics and biochemical feedstocks tolerate broader specification ranges.
Food grade dominates transaction volumes; pharmaceutical grade commands the steepest margin premiums.
Form:
Physical state determines handling infrastructure requirements and integration compatibility with downstream processing equipment.
- Liquid:Bulk oil formats require temperature-controlled logistics and stainless-steel handling systems prevalent among large-scale softgel manufacturers.
- Solid:Powder and granule forms enable dry-blending operations across Southeast Asian functional food processors lacking liquid dosing capabilities.
- Gel:Semi-solid matrices suit specific encapsulation technologies and controlled-release formulations.
- Paste:High-viscosity concentrates serve niche applications in medical nutrition and veterinary formulations.
Liquid forms maintain volume leadership; solid formats are climbing fastest in powder-centric nutrition applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algae omega-3 cultivation first achieved industrial scale in Japan during the 1980s, with phototrophic raceway systems later migrating to China's coastal provinces as fermentation technology matured. Today's Asia-Pacific landscape distributes production across heterotrophic bioreactor facilities and open-pond operations serving distinct end-use specifications.
China
Infant formula manufacturers in Shanghai and Beijing drive concentrated demand for SAMR-registered DHA oils. GB standards for novel food ingredients are tightening purity benchmarks for 3-MCPD esters ahead of 2025 enforcement windows. Fujian province cultivation facilities direct output toward food-grade specifications exceeding baseline contaminant thresholds.
Australia
TGA-regulated complementary medicine channels command pharmaceutical-grade certification for batch-verified DHA oils. Nutraceutical contract manufacturers in Sydney and Melbourne specify strain provenance and batch analytics in master service agreements. Direct procurement relationships are displacing traditional Singapore-based trading houses.
India
FSSAI notification pathways for health supplements are opening volume commitments with Mumbai and Hyderabad testing laboratories. Dietary supplement manufacturers seek flexible dosing formats for diverse consumer segments across Maharashtra and Karnataka. CDSCO joint oversight of import purity standards creates multi-layered compliance architecture.
Thailand
Sports nutrition powder applications penetrate protein premix operations seeking clean-label omega-3 fortification. Functional food processors specify dispersion-stable microencapsulated formats where oil integration would compromise texture. ASEAN harmonization momentum is reducing redundant registration burdens for novel food safety assessments.
Vietnam
Volume-commitment contracts with Chinese cultivation facilities are bypassing historical distributor networks. Cost-sensitive buyers periodically switch toward marine sources when Peruvian anchovy catch recoveries collapse omega-3 price spreads. Emerging mutual recognition frameworks are reshaping regional supply allocation patterns.
Asia-Pacific Algae Omega-3 Ingredient Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade certification commanding 18-month validation cycles that filter subscale suppliers. The vendor base distributes across fermentation-capable producers with heterotrophic platforms and phototrophic pond operators serving feed-grade applications. Three archetypes dominate: global nutrition conglomerates with strain licensing control, mid-cap regional specialists with backward integration into cultivation, and contract manufacturing service providers with TGA certification pipelines. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as batch-traceable documentation becomes a non-negotiable procurement criterion.
Within the global nutrition tier, DSM Nutritional Products and BASF SE exemplify multinational players with pharmaceutical-grade certification pipelines. Xiamen Huison Biotech Co Ltd occupies a position among China-based fermentation specialists with cost-competitive cultivation scale across Fujian province. These three anchors illustrate how proprietary strain access and regulatory documentation capabilities are concentrating preferred supplier status among infant formula and nutraceutical manufacturers.
| Leading Market Players |
|---|
| BASF SE |
| Nordic Naturals Inc |
| Archer Daniels Midland Company |
| SIMRIS ALG AB |
| Qponics Limited |
| DSM Nutritional Products |
| Xiamen Huison Biotech Co Ltd |
| Beijing Gingko Group Co. Ltd. |
| Corbion NV |
| Others |
Value Chain & Pricing Dynamics
China's SAMR-mandated novel food ingredient registrations for algae-derived DHA oils are forcing infant formula manufacturers toward batch-traceable suppliers with documented fermentation capability, compressing the qualified supplier base and amplifying pricing power for certification-holding incumbents across Fujian and Jiangsu province manufacturing clusters.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and feed grades separates premium-margin batch-verified oils from commodity-grade pond extracts. Certification intensity and analytical documentation requirements drive price differentiation, with TGA-compliant pharmaceutical-grade products commanding substantial premiums over SAMR-registered food-grade alternatives. Cost compression in standard food-grade tiers is intensifying as glucose and yeast extract input costs fluctuate with Brazilian sugarcane harvest cycles. Feed-grade aquaculture applications exhibit highest price sensitivity, while pharmaceutical compounders in Australia's TGA-regulated channels demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from Australian nutraceutical contract manufacturers are mandating multi-supplier qualification across Chinese fermentation facilities and alternative cultivation sites. Geographic supply concentration centers on China, with Fujian and Hainan provinces anchoring phototrophic raceway operations and Guangdong bioreactor clusters serving heterotrophic platforms. Raw material dependencies draw from Brazilian sugarcane-derived glucose, yeast extract from global fermentation supply bases, and specialized Schizochytrium strain licenses from three dominant technology licensors. Single-source vulnerability around proprietary high-DHA strains creates structural risk. Distribution runs through direct procurement relationships displacing Singapore-based trading houses, with volume-commitment contracts penetrating Thailand and Vietnam dietary supplement manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's tightening GB standards for 3-MCPD esters ahead of 2025 enforcement windows accelerating demand for molecular distillation and supercritical CO2 purification capacity.
For Market Incumbents: To counter heterotrophic feedstock volatility compressing margins during Q2-Q3 procurement windows, deepen backward integration into glucose supply arrangements and expand pharmaceutical-grade certification pipelines through Australia's TGA complementary medicine channels. Capacity addition in Fujian province fermentation facilities reinforces cost positioning against phototrophic pond operators. For New Entrants and Emerging Players: Begin with India's FSSAI health supplement notification pathways, where analytical partnerships with Mumbai and Hyderabad testing laboratories create first-mover positioning in an underpenetrated regulatory window. Thailand and Vietnam sports nutrition powder applications offer the most penetrable segment, with clean-label omega-3 fortification demand outpacing local dispersion-stable microencapsulation supply. A go-to-market angle anchored to ASEAN harmonization momentum reduces redundant registration burdens across emerging mutual recognition frameworks. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap regional specialists possessing backward integration into heterotrophic cultivation and existing SAMR novel food registrations, as batch-traceable documentation becomes non-negotiable procurement criteria. Long-term viability over a five-to-ten-year window favors fermentation-capable producers with strain licensing relationships and pharmaceutical-grade purification capacity. The signal to watch is divergence between national pharmacopeial specifications and ASEAN harmonization progress, which would materially shift competitive positioning for multi-country suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Pipeline | TGA compliance enables premium positioning in Australia's complementary medicine channels. |
| Backward Integration into Strain Licensing | Proprietary Schizochytrium access reduces dependency on three global technology licensors. |
| Direct Procurement Relationship Establishment | Bypassing Singapore trading houses captures margin from Southeast Asian dietary supplement manufacturers. |
| Dispersion-Stable Microencapsulation Capacity | Thailand and Vietnam sports nutrition processors specify powder formats for protein premix integration. |
| ASEAN Harmonization Participation | Mutual recognition frameworks reduce redundant registration costs across Thailand, Vietnam, and Indonesia. |
Study Parameters
Multiple input streams — primary interviews with fermentation operations directors, infant formula procurement managers, and regulatory affairs specialists at SAMR and TGA; secondary validation through customs trade data, SEC filings of listed nutrition conglomerates, and pharmacopeial specification databases; plus bottom-up and top-down triangulation — were reconciled to construct market estimates across the Asia-Pacific algae omega-3 landscape.
Data-stream reconciliation applied analytical frameworks modeling grade tier, end-use application, formulation format, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions, with inputs including SAMR registration timelines, TGA certification cycle durations, and heterotrophic cultivation yield improvements from metabolically engineered strain development.
Caveats apply where regulatory enforcement intensity around 3-MCPD esters, Peruvian anchovy catch recoveries triggering fish oil price arbitrage, or strain licensing concentration among three global technology licensors could materially shift the outlook. Deviation in China's GB standard implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Paraffin Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Estolides Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Triisostearyl Citrate Market