
 Night Vision Goggles Market | 2026-2036
Night Vision Goggles Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Goggles Market Analysis
Gallium arsenide photocathodes is rebalancing cost-performance tradeoffs in Gen III night vision devices. L3Harris leverages captive semiconductor foundry capacity to secure GaAs wafer supply for military contracts. Elbit Systems anchors its position through vertical integration into tube manufacturing and helmet display systems. ATN competes aggressively in the civilian digital night vision tier with price-accessible sensor packages.
Night vision goggles are electro-optical devices that amplify ambient near-infrared light through vacuum tube image intensifiers or solid-state digital sensors, typically operating at wavelengths between 600 and 900 nanometers with resolution measured in line pairs per millimeter. Their primary purpose is to enable human visual perception in environments below 0.001 lux where unaided sight fails. Goggle form factors dominate military helmet-mounted applications where hands-free operation and peripheral field-of-view exceed 40 degrees prove essential, while thermal imaging technology commands premium positioning in law enforcement search and rescue scenarios where obscurant penetration matters more than target recognition range. Fusion technology represents the fastest-expanding segment as multi-spectral blending of intensified and thermal channels migrates from special operations to mainstream tactical units.
US ITAR regulations restrict image intensifier tube exports and mandate domestic provenance for military-grade devices, compressing supplier pools and elevating compliance costs. The EU AI Act and CE marking under the MDR framework impose emerging conformity requirements on sensor systems with embedded processing, affecting import pathways for non-European manufacturers. Stakeholders must monitor gallium supply chain security and ITAR jurisdiction rulings as photocathode materials face dual-use classification pressures.
Market Dynamics
Gallium arsenide photocathode supply concentration and US ITAR domestic sourcing mandates are restructuring competitive access to military-grade image intensifier tubes, compressing supplier pools while elevating compliance barriers for non-captive producers.
Growth Catalysts
- US ITAR domestic provenance rules:Mandates for US-origin image intensifier tubes in military contracts are accelerating foundry investments and reshoring photocathode production capacity.
- Special Operations Command modernization:Helmet-mounted goggle refresh cycles across NATO special forces units are driving volume procurement of fusion-capable devices.
- Homeland security border surveillance:US Customs and Border Protection upgrades to multi-spectral observation posts are expanding commercial demand for intensified thermal fusion systems.
Market Restraints
- GaAs wafer supply concentration:Limited semiconductor foundry capacity for gallium arsenide substrates creates bottlenecks for Gen III photocathode manufacturing.
- ITAR export control friction:Restrictions on image intensifier tube transfers compress addressable markets for US-based manufacturers seeking allied nation sales.
- Digital sensor substitution pressure:Solid-state CMOS-based night vision alternatives threaten vacuum tube technologies in price-sensitive law enforcement segments.
Strategic Opportunities
- Emerging EU MDR conformity pathways:CE marking requirements for sensor systems with embedded processing create first-mover advantages for compliant manufacturers in European tactical markets.
- Civilian aviation augmented vision:FAA certification progress for helicopter pilot helmet-mounted displays opens new non-military volume channels.
- Multi-spectral fusion convergence:Blending intensified near-infrared with thermal long-wave channels enables premium positioning in search and rescue applications.
Industry Challenges
- ITAR compliance timeline compression:Jurisdiction rulings on photocathode dual-use classifications delay contract awards and require specialized legal expertise.
- Legacy system integration friction:Helmet display interface standardization gaps between NATO member forces complicate multinational procurement alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Goggles Market |
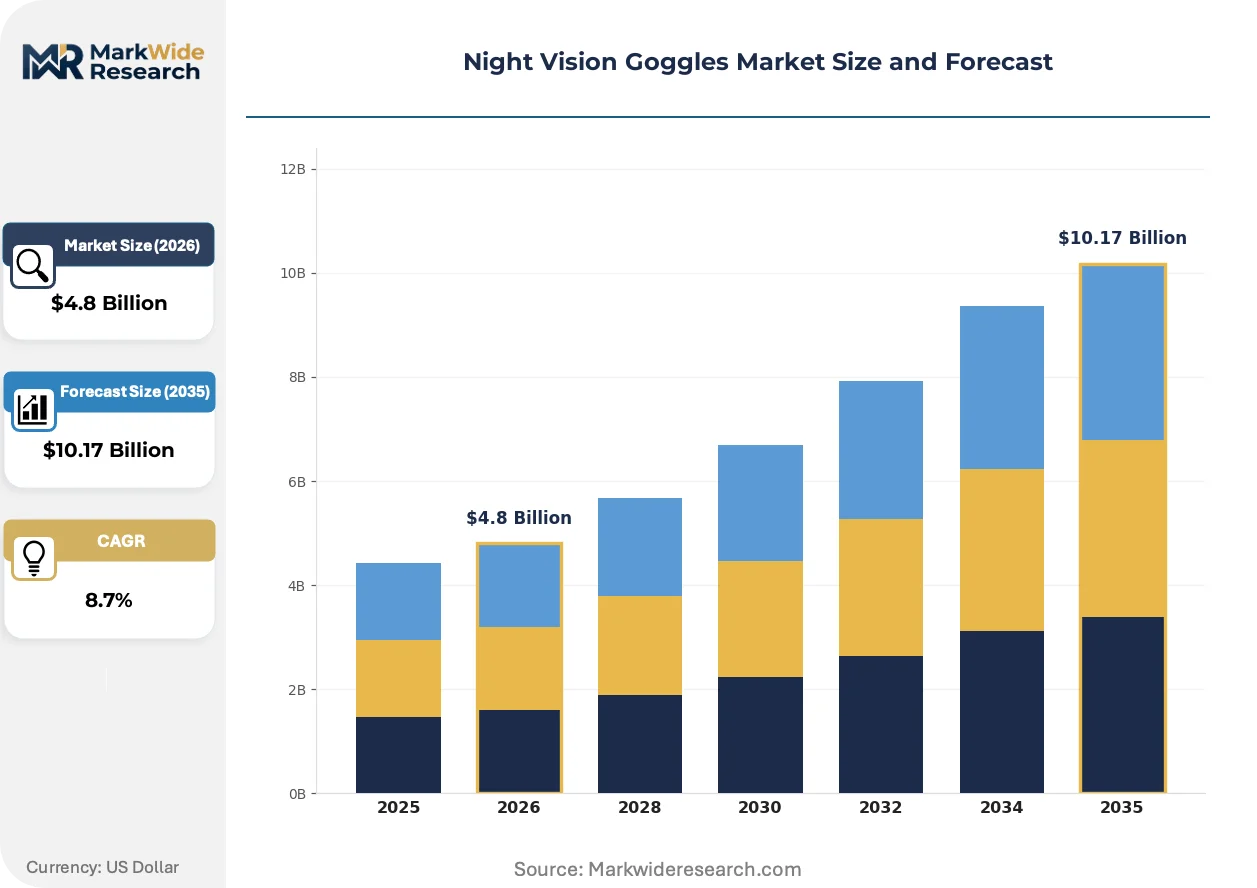
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binoculars, Monoculars, Goggles, Scopes Technology: Image Intensification, Thermal Imaging, Digital Night Vision, Fusion Technology End User: Military, Law Enforcement, Wildlife Observation, Sports & Recreation Application: Surveillance, Search & Rescue, Hunting, Tactical Operations |
| Companies Covered | L3Harris, Elbit Systems, ATN, Raytheon Technologies, Physical Sciences Inc, SRI International, BAE Systems, FLIR Systems, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Goggles Market Emerging Trajectories
Fusion architecture adoption is redistributing competitive advantage from pure-play intensifier tube specialists toward multi-spectral system integrators with software-defined blending capabilities.
Digital night vision sensor technology is decentralizing manufacturing entry barriers by reducing reliance on vacuum tube foundries and enabling fabless design models. Commercial security integrators and hunting optics brands are adopting CMOS-based systems at accelerating rates. This sensor transition is decentralizing supplier power away from legacy photocathode producers toward semiconductor packaging houses.
EU AI Act algorithmic transparency requirements are imposing new conformity burdens on night vision devices with embedded target recognition or image enhancement processing. Manufacturers must document training data provenance and decision logic for CE marking under MDR sensor system classifications. European tactical procurement offices are prioritizing compliant vendors, reshaping competitive access for non-European suppliers.
Specialized distributor networks for law enforcement and hunting channels are displacing traditional defense contractor sales structures in commercial night vision. Direct-to-consumer digital brands are capturing volume through online tactical equipment retailers, compressing traditional two-tier distribution margins. This channel fragmentation is most visible in the United States, where civilian digital night vision purchases bypass legacy defense procurement frameworks.
Night Vision Goggles Market Segmentation
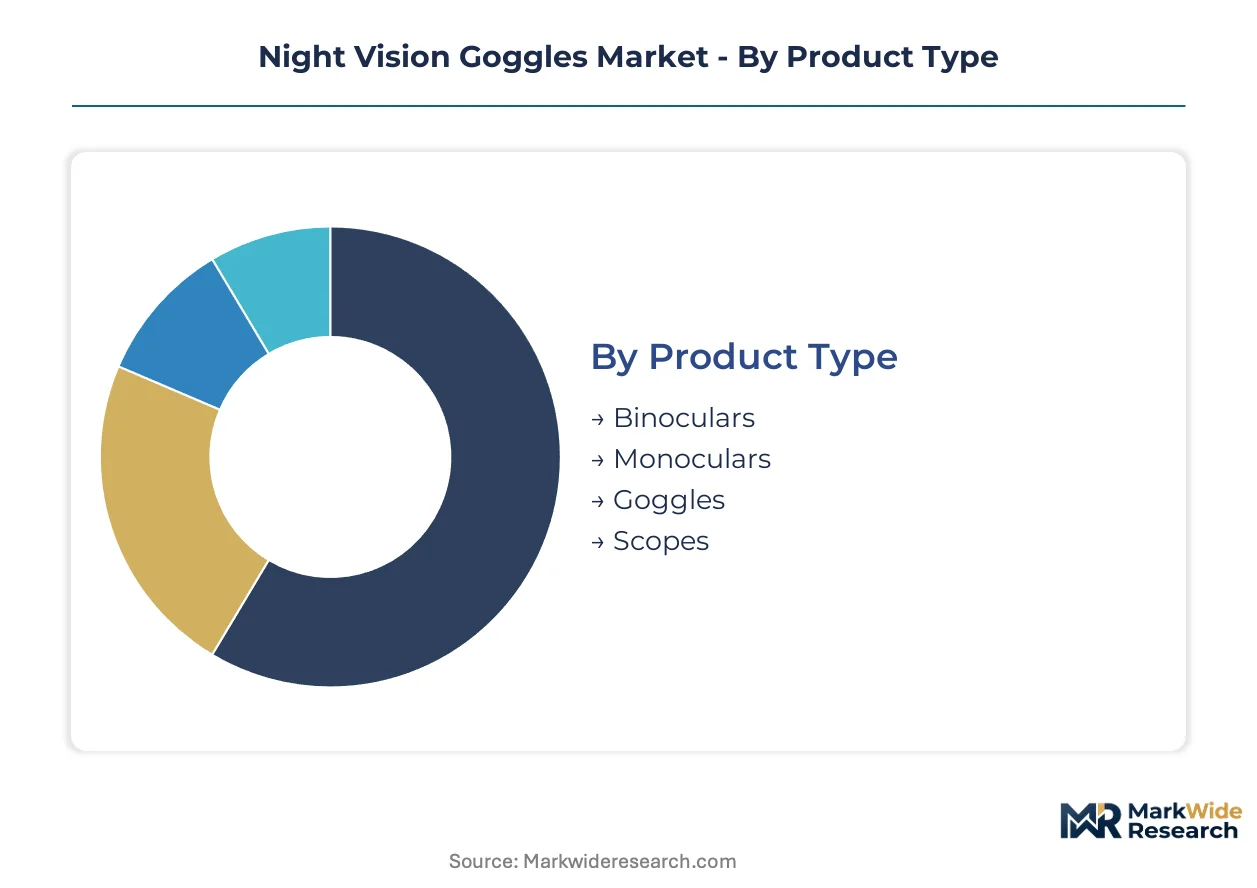
Helmet-mounted refresh cycles and multi-spectral fusion adoption create divergent upgrade pathways across product categories. Procurement officers segment budgets by operational tempo, distinguishing between high-duty tactical deployments and intermittent civilian use.
Product Type:
Goggle form factors dominate Special Operations Command modernization programs where hands-free operation proves mission-critical.
- Goggles:Helmet-mounted systems with 40-degree plus peripheral field-of-view anchor NATO special forces procurement. US Customs and Border Protection multi-spectral observation post upgrades are expanding commercial fusion goggle placements.
- Binoculars:Dual-tube configurations deliver depth perception for surveillance teams requiring extended observation periods. Wildlife research stations in Kenya and Tanzania favor these units for nocturnal species monitoring.
- Monoculars:Single-ocular devices reduce weight for dismounted infantry patrols.
- Scopes:Weapon-mounted systems serve designated marksman roles in law enforcement tactical units.
Volume placements concentrate in Goggles; the faster expansion belongs to Binoculars.
Technology:
Cost-performance tradeoffs between vacuum tube heritage and solid-state disruption reshape procurement specifications across defense and commercial channels.
- Fusion Technology:Multi-spectral blending of intensified near-infrared with thermal long-wave channels enables obscurant penetration beyond pure image intensification. US SOCOM and allied NATO special operations units are standardizing fusion architectures for target recognition in degraded visual environments.
- Image Intensification:Gen III vacuum tube devices with gallium arsenide photocathodes retain dominance in military contracts requiring sub-0.001 lux performance. ITAR domestic sourcing mandates compress supplier pools to L3Harris and Elbit Systems captive foundries.
- Thermal Imaging:Uncooled microbolometer sensors command premium positioning in search and rescue where smoke and fog penetration matters.
- Digital Night Vision:CMOS-based solid-state alternatives threaten tube technologies in price-sensitive law enforcement segments.
Procurement volume clusters in Image Intensification; Fusion Technology is climbing the fastest.
End User:
Customer type determines certification requirements, with ITAR jurisdiction creating impermeable boundaries between military-grade and commercial channels.
- Military:Helmet-mounted goggle refresh cycles across NATO member states drive volume demand for ITAR-compliant Gen III tubes. US Special Operations Command modernization programs specify fusion-capable devices with standardized helmet display interfaces.
- Law Enforcement:Search and rescue units and tactical response teams prioritize thermal and fusion systems for urban operations. Budget constraints accelerate digital night vision substitution in municipal police departments.
- Wildlife Observation:Research institutions and conservation NGOs favor digital and Gen II+ intensified systems for cost-managed field deployment.
- Sports & Recreation:Hunting optics brands and civilian aviation pilots drive direct-to-consumer digital night vision volume through online tactical retailers.
Military contracts capture the largest placement volumes; Sports & Recreation is gaining share fastest.
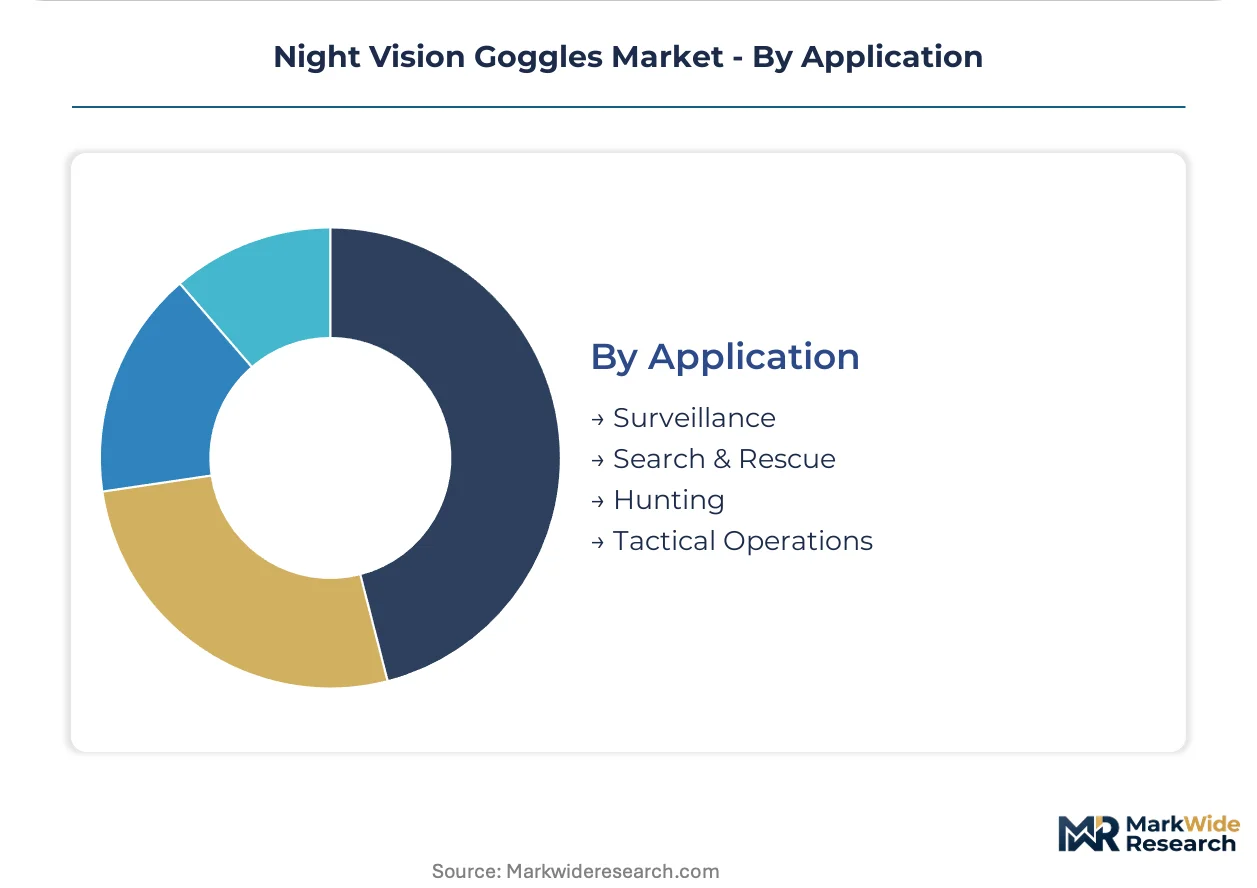
Application:
Operational scenario dictates sensor specification, separating continuous surveillance from intermittent target engagement requirements.
- Tactical Operations:Close-quarters battle and dismounted patrol missions require helmet-mounted goggles with rapid light-adaptive protection. NATO standardization gaps in helmet display interfaces complicate multinational procurement alignment.
- Surveillance:Border observation posts and perimeter security installations favor binocular and scope configurations for sustained monitoring. US Customs and Border Protection multi-spectral upgrades are intensifying demand for intensified-thermal fusion.
- Search & Rescue:Thermal imaging dominates urban fire rescue and wilderness recovery where obscurant penetration outweighs target recognition range.
- Hunting:Digital night vision scopes and monoculars serve recreational hunters through price-accessible CMOS sensor packages.
Surveillance applications hold the deepest placement base; Search & Rescue is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement programs concentrate approximately half of worldwide military-grade night vision demand, with Special Operations Command modernization cycles and Customs and Border Protection surveillance upgrades driving volume placement. ITAR domestic sourcing mandates reshape supplier access across allied nations. Procurement officers in NATO member states navigate certification fragmentation while seeking helmet display interface standardization.
United States
US Special Operations Command helmet-mounted goggle refresh cycles and Customs and Border Protection multi-spectral observation post upgrades anchor regional demand. ITAR regulations restrict image intensifier tube exports and mandate domestic provenance for military contracts, compressing supplier pools to captive foundries. Huntsville, Alabama and Dallas-Fort Worth, Texas host concentrated defense electronics manufacturing clusters serving these programs.
Germany
Bundeswehr special forces procurement and federal police tactical unit modernization drive fusion-capable device demand. KBA vehicle equipment standards and EU AI Act algorithmic transparency requirements impose conformity burdens on sensor systems with embedded processing. Bavaria's Munich-Stuttgart corridor anchors precision optics and electro-optical subsystem manufacturing for NATO supply chains.
United Kingdom
Ministry of Defence helmet-mounted display programs and counter-terrorism unit equipment refresh cycles sustain procurement volume. UK Export Control Organisation dual-use licensing requirements parallel ITAR restrictions on image intensifier technology transfers. Greater Manchester and Bristol aerospace clusters concentrate night vision integration capabilities for domestic and allied military contracts.
Israel
Israel Defense Forces urban warfare doctrine and border surveillance system upgrades sustain continuous tactical equipment procurement. Ministry of Defense export licensing requirements govern technology transfer for electro-optical systems with multi-spectral capabilities. Tel Aviv metropolitan area and Haifa defense technology corridor host vertically integrated night vision manufacturing and helmet display system integration.
France
Direction Générale de l'Armement special operations equipment programs and Gendarmerie nationale tactical response unit modernization drive fusion goggle adoption. ANSM/CNIL data governance frameworks and EU MDR CE marking requirements affect sensor system import pathways. Paris-Saclay and Toulouse aerospace clusters concentrate electro-optical research and helmet-mounted display engineering capabilities.
Night Vision Goggles Market Vendor Landscape
Backward integration into photocathode manufacturing dominates the current landscape as suppliers secure captive gallium arsenide wafer capacity. The vendor base concentrates around three tiers: vertically integrated defense primes with foundry ownership, mid-scale system integrators sourcing tubes under license, and fabless digital sensor specialists competing on price-accessibility. Two competitive moves define positioning: strategic partnerships bridging tube supply gaps, and portfolio diversification into multi-spectral fusion architectures.
Within the integrated-prime tier, L3Harris and Elbit Systems exemplify foundry-captive positioning through semiconductor manufacturing ownership. ATN occupies a position at the fabless-commercial vector, representing price-accessible digital night vision specialization. These three anchors illustrate the structural split between ITAR-compliant military supply and civilian market accessibility.
| Leading Market Players |
|---|
| L3Harris |
| Elbit Systems |
| ATN |
| Raytheon Technologies |
| Physical Sciences Inc |
| SRI International |
| BAE Systems |
| FLIR Systems |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
US Special Operations Command fusion-goggle procurement specifications are compressing supplier margins for non-captive tube manufacturers while rewarding foundry-integrated primes with pricing power on multi-spectral contracts.
Pricing Analysis
Volume procurement concentrates in ITAR-compliant Gen III tubes where L3Harris and Elbit Systems command premium positioning; digital CMOS alternatives compete on price-accessibility in law enforcement channels. Price differentiation rests on certification grade—military contracts carry ITAR domestic-provenance premiums while civilian digital devices compete on sensor-package cost. Cost compression in the law enforcement tier is intensifying because municipal budget constraints accelerate CMOS substitution. Wildlife observation and hunting segments exhibit highest price sensitivity; NATO special forces procurement shows lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
US ITAR domestic-sourcing mandates and EU MDR conformity requirements are forcing photocathode reshoring and dual-use classification reviews that fragment supplier access across military and commercial channels. Manufacturing gravity centers on the United States, Israel, and Germany where captive GaAs foundries and precision optics clusters anchor production. Raw material dependencies include gallium arsenide wafers, rare-earth phosphor compounds, and microbolometer vanadium oxide substrates. Single-source vulnerability concentrates in GaAs semiconductor foundry capacity where limited qualified suppliers create photocathode bottlenecks. Distribution runs through specialized defense contractors for military channels and direct-to-consumer online retailers for civilian digital segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around foundry-captive primes as ITAR compliance costs and GaAs supply concentration force smaller tube assemblers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into GaAs wafer production or secure long-term foundry offtake agreements to lock in tube supply for SOCOM fusion contracts. Invest in EU MDR algorithmic-transparency documentation to capture first-mover positioning in European tactical procurement before CE marking gates close to non-compliant vendors. Digital CMOS substitution in law enforcement represents the primary margin threat requiring portfolio diversification into multi-spectral fusion architectures. For New Entrants and Emerging Players: Capture civilian aviation augmented-vision certification progress as FAA helicopter pilot helmet-display pathways open non-military volume channels underserved by defense primes. Target price-accessible digital night vision for hunting and recreational markets where direct-to-consumer distribution bypasses legacy procurement frameworks. Partner with established semiconductor packaging houses to circumvent vacuum-tube foundry barriers and accelerate CMOS-based product development. For Investors and Strategic Acquirers: The window for entry favors mid-scale system integrators with tube-sourcing licenses and software-defined fusion capabilities that larger primes may acquire to fill technology gaps. Long-term viability rests on positioning ahead of NATO helmet-display interface standardization and EU AI Act enforcement waves. Watch GaAs wafer supply announcements and ITAR jurisdiction rulings on photocathode dual-use classifications as inflection indicators for contract award velocity and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaAs Foundry Capacity | Captive wafer supply secures ITAR-compliant tube production for SOCOM fusion contracts. |
| EU MDR CE Marking Pathway Investment | Algorithmic-transparency documentation opens European tactical procurement to compliant vendors. |
| Multi-Spectral Fusion Architecture Development | Software-defined blending capabilities shift competitive advantage from tube specialists to system integrators. |
| Direct-to-Consumer Digital Channel Launch | Online tactical retailer partnerships capture hunting and recreational volume outside defense procurement. |
| FAA Certification Partnership for Aviation Displays | Helmet-mounted augmented-vision approval creates new non-military volume channel for goggle manufacturers. |
Methodological Framework
Document review covered ITAR jurisdiction rulings, EU MDR technical documentation requirements, and GaAs semiconductor trade data, complemented by interviews with defense procurement officers at NATO special operations commands, electro-optical subsystem engineers at prime contractors, gallium arsenide foundry operations managers, and law enforcement equipment procurement leads. Secondary validation drew from SEC 10-K filings of listed defense electronics firms, US Customs and Border Protection budget justifications, and FAA certification progress databases. Bottom-up demand modeling triangulated against top-down military expenditure allocations.
Cross-referencing historical procurement cycle patterns with expert panel input on SOCOM modernization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, technology architecture, end-user certification tier, and regional regulatory cluster. CAGR derivation incorporated volume placement trajectories for helmet-mounted refresh cycles, fusion adoption rates in special operations units, and digital substitution elasticities in municipal law enforcement. Industry-specific forecast inputs included ITAR domestic-content compliance thresholds and EU AI Act enforcement phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GaAs supply chain disruptions, ITAR jurisdiction reinterpretations, and CMOS sensor performance breakthroughs. The analysis reflects documented assumptions on NATO standardization progress and regulatory enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Road Safety Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Life Jacket Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Child Leash Market
Personal Safety
Global Fall Protection Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Concealable Vest Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Fall Detection System Market
Personal Safety
Child Safety Seat Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Global Self Defense Products Market