
 Global Coworking Space Management Software Market | 2026-2036
Global Coworking Space Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coworking Space Management Software Market Foresight
Buyer concentration is shifting as enterprise branch networks replace freelancers as the dominant purchasing segment for coworking management platforms. OfficeRnD Limited leverages deep API integration capabilities to anchor its position among mid-market operators. Satellite Deskworks LLC competes through specialized resource scheduling tools designed for hybrid workplace configurations. Cobot differentiates via streamlined billing and invoicing workflows that reduce administrative overhead for independent space operators.
Coworking space management software constitutes an integrated technology stack that automates desk allocation, membership billing, visitor check-in, and real-time occupancy tracking through IoT sensor feeds and calendar system synchronization. The primary commercial purpose centers on maximizing revenue per square foot while minimizing manual administrative labor across multi-location flexible office portfolios. Cloud-based deployment leads the architecture mix as operators prioritize remote accessibility and reduced IT infrastructure burden, while data analytics represents the fastest-growing solution type as owners seek predictive occupancy modeling. Resource scheduling commands concentrated margin pools where enterprise clients negotiate premium-tier service level agreements.
The EU AI Act and GDPR shape product development trajectories for vendors serving European operators by mandating algorithmic transparency in automated space allocation and strict visitor data retention protocols. The FCC's broadband infrastructure standards in the United States indirectly influence platform performance requirements as reliable connectivity underpins real-time desk availability systems. Stakeholders must monitor how OSHA's evolving indoor air quality guidelines integrate with occupancy management dashboards to determine whether environmental sensor fusion becomes a table-stakes feature or premium differentiator.
Market Dynamics
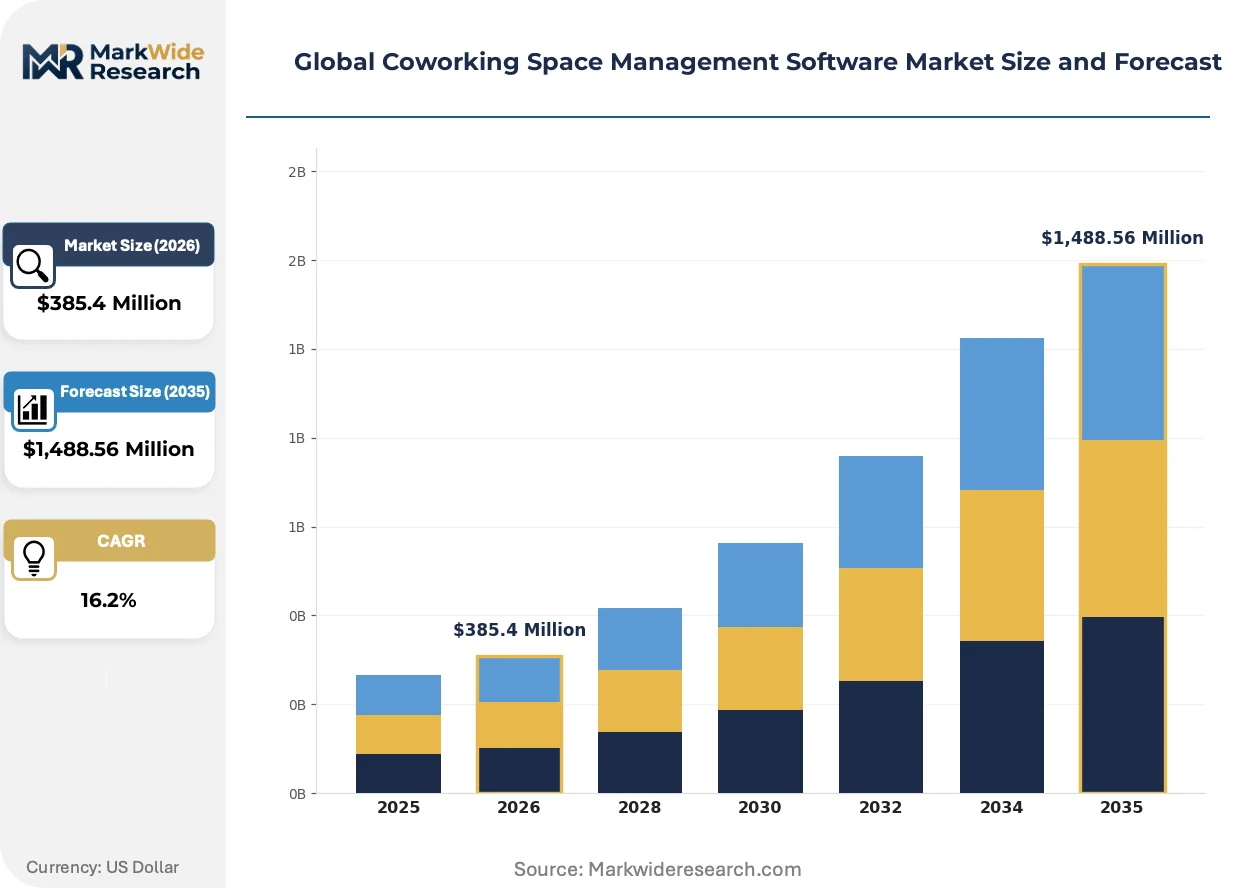
Enterprise branch networks now dominate purchasing decisions as hybrid work policies harden into permanent operational frameworks. This shift compresses sales cycles for vendors while elevating API integration and multi-location orchestration capabilities into primary selection criteria.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European operators face algorithmic transparency requirements for automated space allocation, driving replacement of legacy systems with auditable cloud architectures.
- IoT sensor fusion for real-time occupancy:Desk availability dashboards now integrate environmental monitoring, creating bundled value propositions that justify premium pricing tiers.
- India's flexible office infrastructure buildout:Domestic operators in Bengaluru, Mumbai, and Hyderabad are digitizing manual booking systems to manage rapid portfolio expansion.
Market Restraints
- Cloud dependency and connectivity fragility:FCC broadband infrastructure gaps in secondary US markets degrade real-time synchronization between sensors and central platforms.
- Input cost volatility in IoT hardware:Semiconductor supply concentration in East Asian foundries creates procurement uncertainty for sensor deployment at scale.
- Data retention protocol fragmentation:Divergent national privacy frameworks force vendors to maintain parallel codebases, inflating development overhead.
Strategic Opportunities
- Germany's Mittelstand manufacturing hubs:Mid-sized industrial clusters in Stuttgart and Munich lack dedicated flexible workspace management, presenting greenfield deployment potential.
- Environmental sensor convergence with HVAC:OSHA indoor air quality guideline evolution creates demand for integrated dashboards that fuse occupancy, ventilation, and health metrics.
- Outcome-based space utilization contracts:Enterprise clients in the United States now negotiate performance-linked pricing tied to measured productivity per square foot.
Industry Challenges
- Legacy calendar system integration complexity:Enterprise IT departments resist API overhauls, forcing vendors to maintain brittle connectors to Microsoft Exchange and Google Workspace.
- Specialized DevOps talent scarcity:Multi-tenant cloud architecture expertise remains concentrated in San Francisco, London, and Berlin, constraining vendor expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coworking Space Management Software Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,488.56 Million |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Booking Management, Billing & Invoicing, Resource Scheduling, Visitor Management, Communication Tools, Data Analytics Application: Space Utilization Optimization, Membership Management, Event Coordination, Resource Allocation, Payment Processing, Customer Support Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Platform, Mobile Application, API Integration End User Type: Startups, Freelancers, Business Incubators, Remote Teams, Enterprise Branches, Independent Professionals |
| Companies Covered | Cobot, Satellite Deskworks LLC, OfficeRnD Limited, LiquidSpace Inc., Skedda Pty. Ltd., Nexudus Ltd., Yardi Kube Inc., Optix, OfficeSpace Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coworking Space Management Software Market Shifts & Advancements
Software architecture decisions now precede physical space design as operators prioritize data infrastructure over aesthetic fit-out. This inversion elevates vendors with embedded analytics capabilities into strategic partnership roles.
API-first modular platforms is overtaking monolithic legacy suites in competitive evaluations. Enterprise branch networks in the United States and Germany now mandate microservices architectures that permit selective component replacement without system-wide overhaul. This technical preference compresses margins for vendors locked into rigid codebase structures while rewarding those with documented integration ecosystems.
REACH chemical safety protocols and RoHS electronics standards in Europe now extend to IoT sensor procurement specifications. Coworking operators in Germany and France face supplier due diligence obligations that disqualify non-compliant hardware vendors. This regulatory layer adds compliance overhead to sensor deployment programs while creating certification moats for established equipment manufacturers.
Consolidated vendor relationships are displacing fragmented point-solution stacks among multi-location operators. Mid-market portfolio managers in India and the United States now prioritize single-platform coverage over best-of-breed feature depth. This procurement compression threatens specialized scheduling and billing vendors unless they embed into broader platform ecosystems through partnership or acquisition.
Global Coworking Space Management Software Market Segmentation
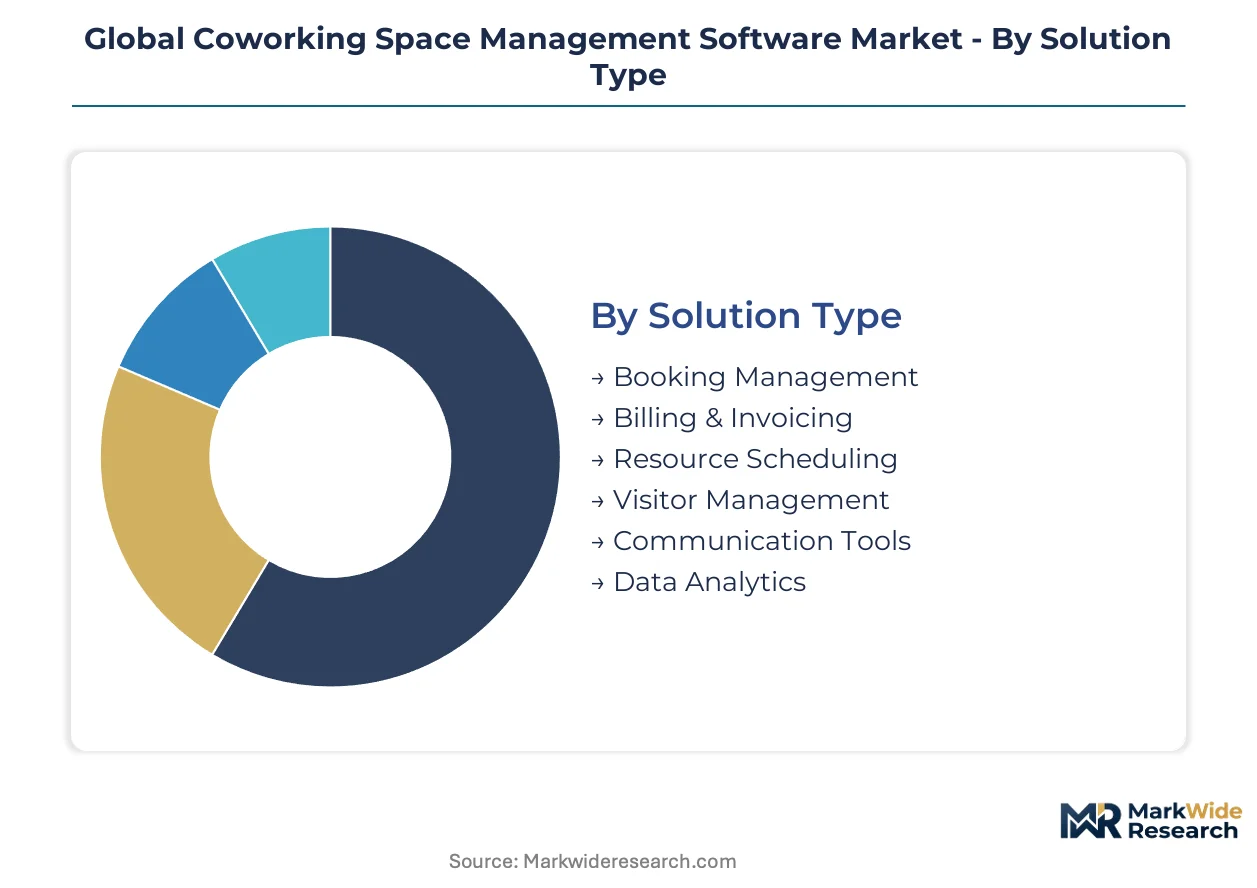
Segmentation in coworking space management software reveals how procurement priorities diverge across operator scale and technical sophistication. Compliance requirements from GDPR and the EU AI Act create certification friction that reshapes competitive positioning within each category.
Solution Type:
REACH chemical safety protocols and RoHS electronics standards in Europe now extend to IoT sensor procurement tied to several solution categories, elevating vendor due diligence obligations.
- Booking Management:Core desk and meeting room reservation engines synchronize with calendar systems through API connectors. Demand concentrates among enterprise branch networks in Germany and the United States as hybrid work policies harden into permanent frameworks.
- Billing & Invoicing:Automated membership fee processing and usage-based charging modules reduce administrative overhead for independent operators. Growth accelerates in India's Bengaluru and Mumbai markets where domestic operators digitize manual systems during rapid portfolio expansion.
- Resource Scheduling:Equipment and amenity allocation tools command premium pricing tiers where enterprise clients negotiate service level agreements.
- Visitor Management:Check-in workflows and access control integration face strict data retention protocols under GDPR.
- Communication Tools:Member messaging and community features differentiate platforms for freelancer-heavy locations.
- Data Analytics:Predictive occupancy modeling and revenue-per-square-foot dashboards represent the fastest-growing solution type as owners seek operational intelligence.
Leading the category by volume: Booking Management. Growing fastest: Data Analytics.
Application:
Application segments map directly to operator business models, with revenue concentration determining which workflows receive platform investment priority.
- Space Utilization Optimization:Real-time occupancy tracking through IoT sensor fusion maximizes revenue per square foot across multi-location portfolios. Enterprise clients in the United States now negotiate outcome-based contracts tied to measured productivity per square foot.
- Membership Management:Onboarding, tier configuration, and renewal automation anchor retention strategies for mid-market operators. Stuttgart and Munich manufacturing hubs present greenfield deployment potential as Mittelstand firms adopt flexible workspace models.
- Event Coordination:Workshop and networking session booking modules serve community-building objectives.
- Resource Allocation:Shared equipment and meeting room distribution balances availability across user segments.
- Payment Processing:Multi-currency and multi-gateway support addresses cross-border operator requirements.
- Customer Support:Ticket routing and knowledge base integration reduces staff overhead for independent professionals.
Revenue leadership: Space Utilization Optimization. Steepest expansion trajectory: Membership Management.
Deployment:
Deployment architecture decisions precede physical space design as operators prioritize data infrastructure over aesthetic fit-out.
- Cloud-Based:Remote accessibility and reduced IT infrastructure burden dominate architecture selection for multi-location operators. GDPR and EU AI Act compliance mandates drive replacement of legacy systems with auditable cloud architectures across European markets.
- On-Premise:Data sovereignty requirements and legacy IT governance retain relevance for financial services tenants in Frankfurt and Singapore.
- Hybrid:Selective local processing with cloud backup addresses connectivity fragility in secondary US markets where FCC broadband infrastructure gaps degrade real-time synchronization.
- SaaS Platform:Subscription pricing aligns with operator cash flow patterns during expansion phases.
- Mobile Application:Member-facing apps for desk booking and community access differentiate consumer-grade offerings.
- API Integration:Microservices architectures permit selective component replacement without system-wide overhaul, now mandated by enterprise branch networks in Germany and the United States.
Architecture preference leader: Cloud-Based. Fastest adoption climb: API Integration.
End User Type:
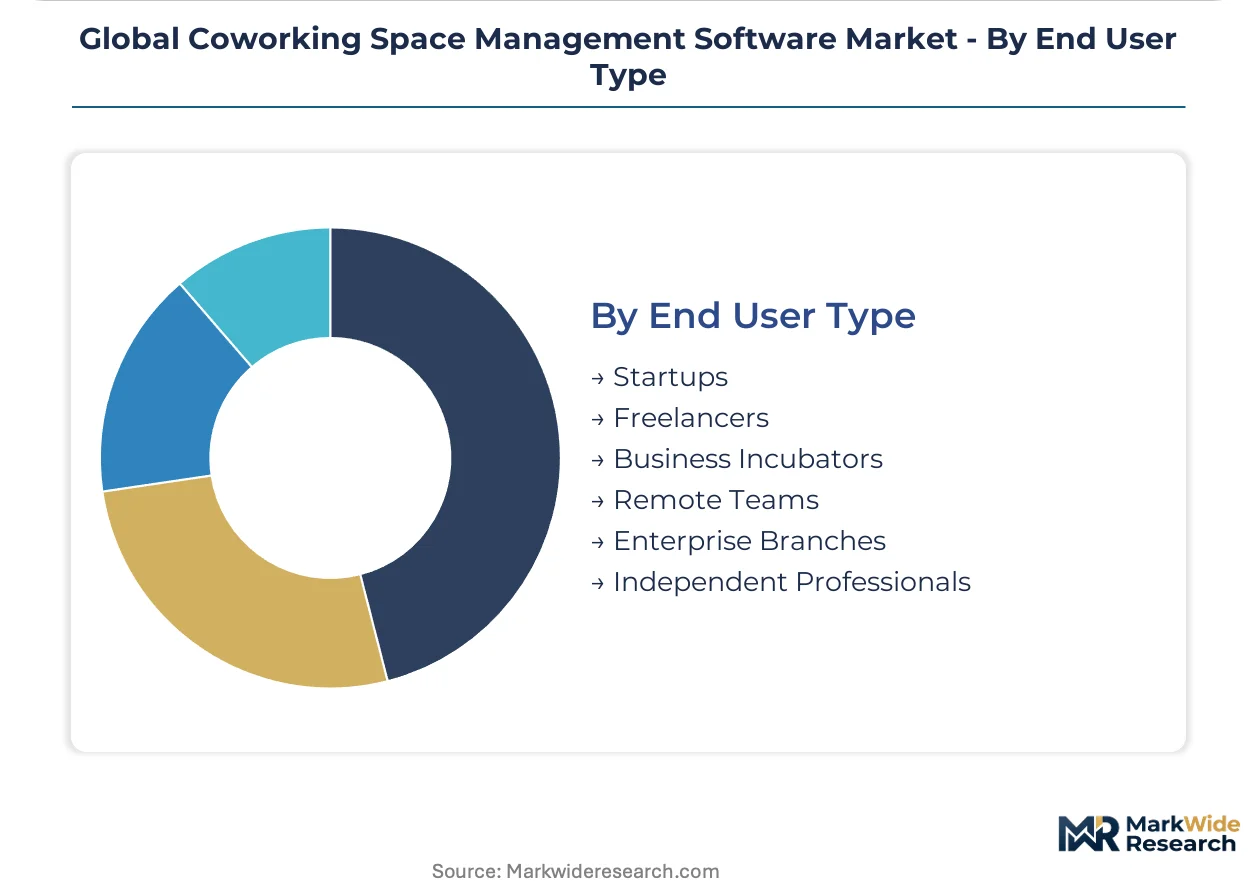
Purchasing concentration has shifted dramatically as enterprise branch networks displace freelancers as the dominant segment.
- Enterprise Branches:Corporate satellite offices and hybrid work hubs demand multi-location orchestration capabilities and premium service level agreements. Procurement compresses sales cycles while elevating API integration into primary selection criteria for vendors.
- Startups:Growth-stage companies prioritize scalable tier transitions and investor reporting integrations. Hyderabad's technology corridor drives regional demand as domestic operators build flexible office infrastructure.
- Freelancers:Individual professionals seek community features and flexible membership terms.
- Business Incubators:Program-based cohort management requires specialized application tracking.
- Remote Teams:Distributed company pods need coordination tools across dispersed locations.
- Independent Professionals:Solo practitioners balance cost sensitivity with professional address requirements.
Volume concentration: Enterprise Branches. Fastest segment expansion: Startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise branch networks in the United States, Germany, and India now concentrate procurement activity as hybrid work policies harden into permanent operational frameworks. FCC broadband infrastructure standards and GDPR compliance mandates reshape platform requirements across these core markets.
United States
Enterprise branch networks dominate software procurement as Fortune 500 firms consolidate satellite office management under unified platforms. FCC broadband infrastructure standards in secondary markets degrade real-time sensor synchronization, forcing hybrid deployment architectures. Greater Boston and Pacific Northwest technology corridors anchor domestic demand concentration.
Germany
Mittelstand manufacturing clusters in Stuttgart and Munich present greenfield deployment potential as mid-sized industrial firms adopt flexible workspace models. GDPR and EU AI Act compliance mandates drive replacement of legacy systems with auditable cloud architectures. REACH chemical safety protocols now extend to IoT sensor procurement specifications.
India
Domestic operators in Bengaluru, Mumbai, and Hyderabad digitize manual booking systems to manage rapid flexible office portfolio expansion. BIS standards and RBI payment processing guidelines shape platform feature requirements. Hyderabad's technology corridor drives regional demand concentration among growth-stage companies.
United Kingdom
London's financial services tenants retain data sovereignty requirements that sustain on-premise deployment relevance alongside cloud migration. FCA operational resilience guidelines intersect with workspace management platform reliability standards. Southeast England technology clusters anchor domestic procurement volume.
Japan
Tokyo-based enterprise branch networks demand multi-location orchestration capabilities with strict data localization compliance. METI digital transformation incentives accelerate replacement of legacy facility management systems. Kansai manufacturing hubs present emerging adoption potential as hybrid work policies penetrate industrial sectors.
Global Coworking Space Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue API-first modular architectures and embedded analytics capabilities. The vendor base stratifies across three maturity tiers: legacy suite providers with monolithic codebases, mid-market specialists with documented integration ecosystems, and cloud-native entrants with microservices foundations. Two dominant competitive moves define current positioning: strategic partnerships with IoT sensor manufacturers and geographic expansion through localized compliance certification.
Among platform specialists, Cobot exemplifies the streamlined billing archetype for independent operators, while OfficeRnD Limited occupies a position within the mid-market integration tier. Satellite Deskworks LLC represents the specialized resource scheduling segment designed for hybrid workplace configurations. These three anchors illustrate how competitive differentiation concentrates around workflow depth rather than horizontal feature breadth.
| Leading Market Players |
|---|
| Cobot |
| Satellite Deskworks LLC |
| OfficeRnD Limited |
| LiquidSpace Inc. |
| Skedda Pty. Ltd. |
| Nexudus Ltd. |
| Yardi Kube Inc. |
| Optix |
| OfficeSpace Software Inc. |
| Others |
Supply & Pricing Matrix
Semiconductor costs in East Asian foundries cascade through IoT sensor procurement tiers, compressing margins for hardware-dependent deployment packages while elevating pure-software subscription premiums across enterprise branch networks in the United States and Germany.
Pricing Analysis
Volume concentrates in mid-tier SaaS subscriptions serving independent operators, while margin pools accrue to premium API-integration tiers negotiated by enterprise clients with multi-location orchestration requirements. Price differentiation separates GDPR-certified cloud architectures from standard deployments, with EU AI Act compliance commanding tier premiums. Cost compression in sensor hardware bundles is intensifying because semiconductor supply concentration creates procurement uncertainty. Independent professionals and small operators exhibit highest price sensitivity, while Fortune 500 branch networks prioritize integration depth over per-seat cost.
Supply Chain Analysis
Reverse-logistics flows for IoT sensor refurbishment remain underdeveloped, forcing operators into premature hardware replacement cycles that inflate total deployment costs. Supply concentrates in Taiwan, South Korea, and China for semiconductor components, with Germany and the United States anchoring cloud infrastructure provisioning. Raw material dependencies span silicon wafers, rare earth elements for sensor magnetics, and lithium-ion cells for edge devices. Single-source vulnerability in East Asian foundries represents the dominant structural risk. Distribution runs through direct vendor partnerships for enterprise accounts and channel aggregators serving mid-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue captive control over IoT sensor supply to secure margin capture and deployment reliability.
For Market Incumbents: To counter API-first modular entrants, deepen backward integration into sensor hardware certification programs aligned with REACH and RoHS protocols, while consolidating channel control through exclusive distribution partnerships with Germany's Mittelstand manufacturing hubs. For New Entrants and Emerging Players: Capture greenfield deployment potential in Stuttgart and Munich industrial clusters where legacy facility management systems lack flexible workspace digitization, leveraging microservices architectures as the primary go-to-market angle against monolithic incumbent suites. For Investors and Strategic Acquirers: Enterprise branch networks negotiating outcome-based utilization contracts is the leading indicator that performance-linked pricing models will reshape vendor economics. Long-term viability favors cloud-native platforms with embedded analytics capabilities and documented integration ecosystems. Acquisition targets should display API-first architectures and European compliance certification. Practitioners should monitor OSHA indoor air quality guideline evolution for early signals of environmental sensor fusion becoming table-stakes functionality.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Partnership | Secures REACH-compliant hardware supply for European operators facing procurement due diligence obligations. |
| API Ecosystem Expansion | Enables selective component replacement demanded by enterprise branch networks in Germany and the United States. |
| GDPR Certification Investment | Creates algorithmic transparency moats against legacy vendors unable to retrofit auditable cloud architectures. |
| Geographic Expansion | Captures India's Bengaluru and Hyderabad buildout as domestic operators digitize manual booking systems. |
| Embedded Analytics Development | Positions vendors as strategic partners as software architecture decisions precede physical space design. |
Research Methodology
Document review covered SEC filings from platform vendors, EU regulatory submissions under GDPR and AI Act frameworks, and IoT hardware certification databases, complemented by interviews with coworking space operators, enterprise facility managers, and integration specialists. Secondary validation drew from FCC broadband infrastructure reports, BIS standards documentation, and OSHA guideline evolution tracking. Bottom-up deployment estimates triangulated against top-down market sizing across solution type and deployment model segments.
Cross-referencing historical adoption curves with panel input from CTOs and IT procurement officers anchored growth rate derivation across the projection horizon. Segmentation modeling incorporated deployment architecture, operator scale tier, integration complexity level, vertical industry focus, and regional regulatory cluster. Forecast inputs included enterprise branch network expansion timelines, hybrid work policy permanence indicators, and semiconductor supply availability assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC broadband infrastructure deployment pace in secondary US markets and EU AI Act enforcement intensity. Forecasts reflect documented assumptions regarding IoT sensor cost trajectories and enterprise software procurement cycle normalization. Practitioners should monitor OSHA indoor air quality guideline finalization and REACH chemical safety protocol expansion for early signals of compliance-driven replacement demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Tenant Billing Software Market
Software & Services
North America Deck Design Software Market
Software & Services
Test Automation Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Global Claims Processing Software Market
Software & Services
Attendance Management Software Market
Software & Services
House Cleaning App Market
Software & Services
Global Diagram Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Airline Route Profitability Software Market
Software & Services
India Sports Management Software Market
Software & Services
Warranty Management Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Point of Sale (Pos) Software Market