
 Rubber Molding Market | 2026-2036
Rubber Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Molding Market Outlook
Southeast Asian compounders is repositioning capacity toward high-consistency silicone and fluoroelastomer grades to serve EV thermal management needs. Continental AG leverages vertical integration from rubber compounding through finished seal production to sustain margin capture across the value chain. Freudenberg Group anchors its competitive position through dedicated R&D centers in Weinheim that specialize in material science for extreme-temperature applications. Sumitomo Riko Company Limited dominates acoustic control component supply to Japanese and Korean OEM transplant factories in North America.
Rubber molding encompasses the shaping of elastomeric compounds—natural rubber with polyisoprene content exceeding 90%, synthetic variants including EPDM and NBR, and thermoplastic elastomers with Shore A hardness ranging from 30 to 90—through heated cavity processes to produce dimensionally stable, elastic components. Injection molding leads production value due to cycle time efficiency and flash reduction, while transfer molding retains importance for bulky precision parts where material flow control determines dimensional tolerance. Compression molding occupies mature, cost-sensitive segments such as industrial gaskets where tooling simplicity outweighs throughput requirements. Silicone formulations command premium positioning in medical device and food-contact applications where biocompatibility certifications create margin pools.
The EPA regulates volatile organic compound emissions from rubber curing operations under NESHAP standards, while REACH restricts phthalate plasticizers and certain accelerator chemicals in compounds sold into European end-use markets. OSHA mandates specific exposure limits for nitrosamine byproducts during vulcanization, shaping workplace investment and process chemistry choices at compounders across the United States. Stakeholders must monitor evolving battery electric vehicle platform architectures, as thermal interface specifications and reduced vibration profiles will redefine elastomer performance requirements and qualification protocols.
Market Dynamics
Automotive electrification is forcing rubber molders to redesign elastomer formulations for battery thermal management systems, compressing traditional NVH component margins while opening high-value niches in coolant seals and interface gaskets.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon blowing agents accelerates adoption of water-blown EPDM foams in HVAC sealing applications across European building stock renovation.
- Medical device reshoring:FDA domestic manufacturing incentives for critical care consumables pull liquid silicone injection capacity back to US contract manufacturers from Asian suppliers.
- Silicone rubber chemistry:Advances in platinum-catalyzed addition cure systems enable thinner-walled, higher-tear-strength components for minimally invasive surgical instruments.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions from leaf disease outbreaks transmit directly to compounder feedstock costs with limited hedging instruments available.
- Per- and polyfluoroalkyl substance liability:REACH restrictions on PFAS-containing fluoroelastomers force premature obsolescence of existing seal designs in chemical processing equipment.
- Tooling lead times:Mold fabrication capacity concentrates in Chinese and German precision machining clusters, extending qualification cycles for new automotive platform launches.
Strategic Opportunities
- India automotive component PLI scheme:Production-linked incentives for advanced automotive technology parts attract greenfield molding investments serving Maruti Suzuki and Hyundai Motor India export programs.
- Closed-loop recycling:Devulcanization technology convergence with pyrolysis enables reclaimed carbon black and oil recovery from end-of-life tires for reintegration into new compound formulations.
- Digital direct-to-molder platforms:Online quoting and design-for-manufacturability tools disintermediate traditional distributor networks for small-batch industrial gasket procurement.
Industry Challenges
- Compound formulation expertise:Retiring polymer chemists at specialty compounders leave gaps in custom rheology design for extreme-temperature aerospace specifications.
- Multi-standard certification burdens:Simultaneous FDA 21 CFR Part 177.2600, EU MDR, and ISO 13485 compliance for medical-grade silicone extends product launch timelines by 14-18 months.
- Legacy ERP integration:Real-time production monitoring systems face interoperability friction with decades-old MRP platforms at mid-tier family-owned molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Molding Market |
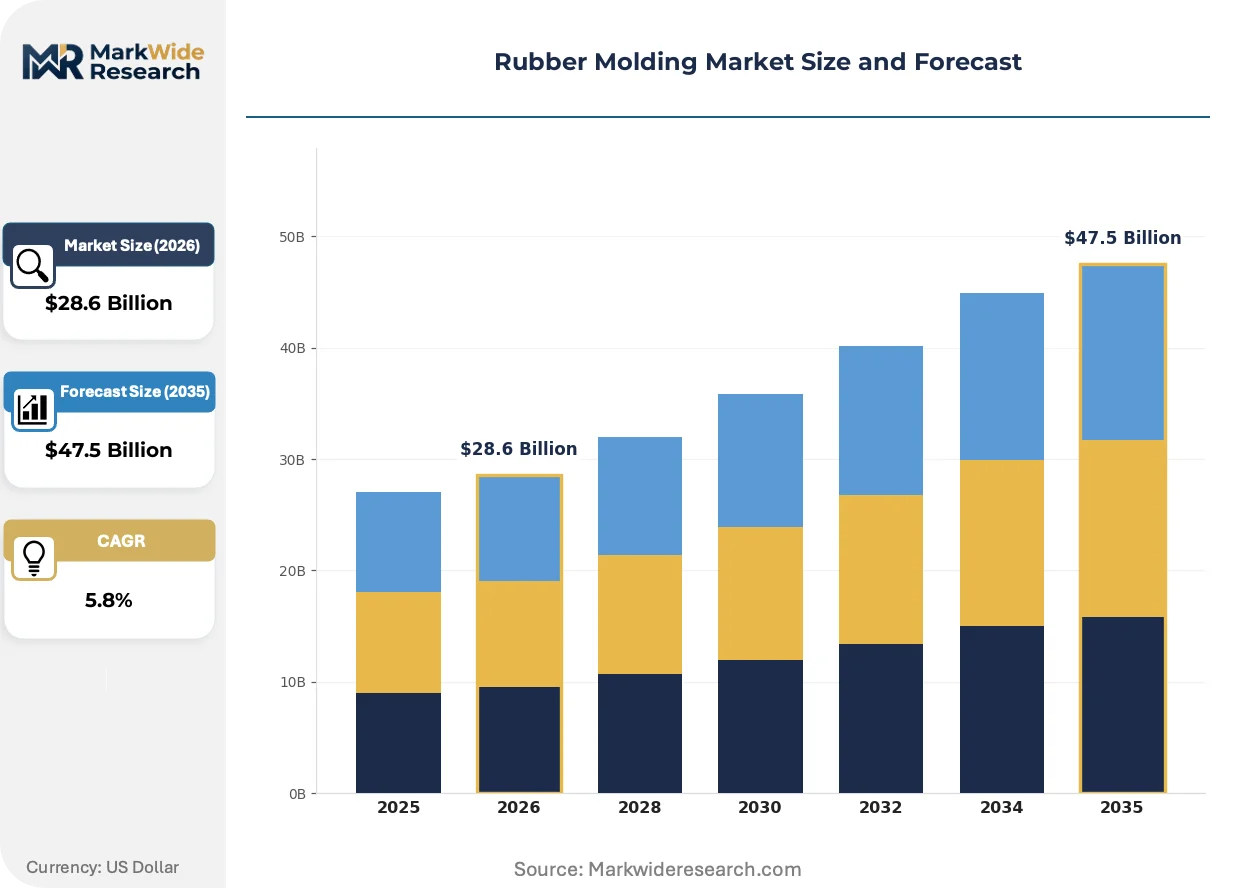
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Compression Molding, Transfer Molding, Blow Molding End User: Automotive, Aerospace, Consumer Goods, Medical Devices Material: Natural Rubber, Synthetic Rubber, Thermoplastic Elastomers, Silicone Application: Seals, Gaskets, Hoses, Custom Parts |
| Companies Covered | Continental AG, Freudenberg Group, Sumitomo Riko Company Limited, Trelleborg AB, NOK Corporation, Hutchinson SA, Toyoda Gosei Co Ltd, Cooper Standard, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Molding Market Strategic Shifts
Process digitization and material science breakthroughs are compressing development cycles while regulatory chemistry restrictions force fundamental reformulation of established product lines across end-use verticals.
Collaborative robotic demolding and vision-based quality inspection is automating final part handling in high-cavity injection cells, with tier-one automotive suppliers deploying these systems at scale in Stuttgart and Wolfsburg corridor plants. The technology compresses labor cost differentials between Western European and Eastern European production locations. Toolmakers in Germany are retrofitting existing presses with adaptive cavity pressure sensors to enable closed-loop process control without full equipment replacement.
REACH Annex XVII restrictions on microplastic-containing abrasives in rubber processing compounds are forcing molders to switch to water-based mold release agents and ceramic blasting media for surface preparation. The regulation affects precision seal manufacturers serving semiconductor fabrication equipment most severely. Japanese compounders are accelerating bio-based fatty acid ester development to preempt similar restrictions under METI chemical management frameworks.
Automotive OEMs are consolidating supplier panels and demanding systems-level sealing solutions rather than discrete component procurement, compressing the number of qualified molders per platform. This behavior shift concentrates volume with vertically integrated compounder-molders capable of in-house material development and finite element analysis validation. Korean battery manufacturers are extending this consolidation pattern to thermal interface material suppliers for their European gigafactory investments.
Rubber Molding Market Segmentation
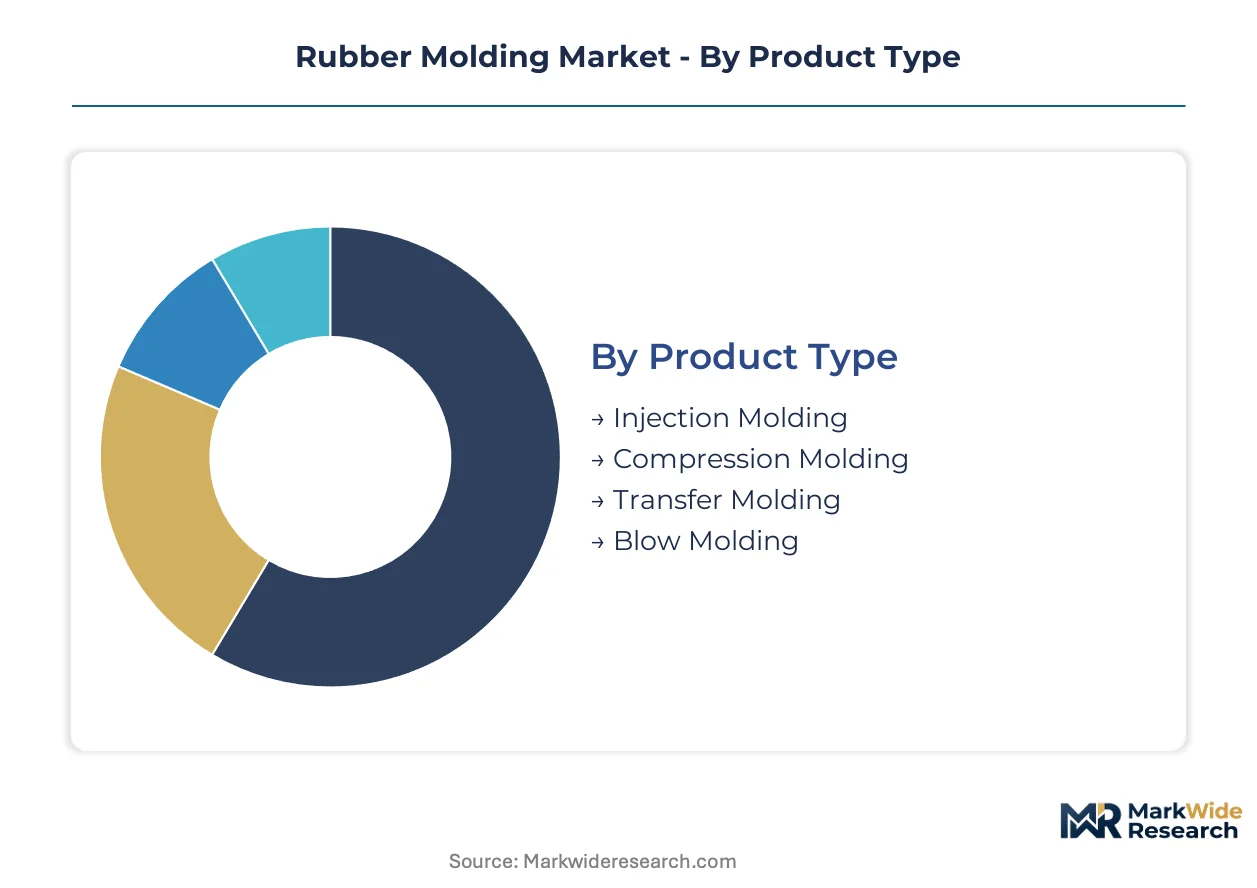
Segmentation in rubber molding reflects divergent certification burdens, tooling economics, and thermal performance thresholds. Each dimension—process technology, end-use vertical, material chemistry, and component function—carries distinct regulatory gatekeepers and margin architectures that shape supplier specialization.
Product Type:
Certification intensity varies sharply across molding technologies: medical-grade liquid silicone injection demands FDA 21 CFR Part 177.2600 validation, while industrial compression molding operates under lighter ISO 9001 quality frameworks. Aerospace transfer molding adds AS9100 and NADCAP surface treatment accreditations.
- Injection Molding:Heated barrel systems force elastomer compounds into precision cavities under controlled pressure and temperature profiles. Cycle times under 60 seconds suit high-volume automotive seal production in Stuttgart corridor plants, though mold complexity drives capital intensity.
- Compression Molding:Pre-weighed charges placed directly into heated open cavities suit bulky industrial gaskets where tooling simplicity outweighs throughput. German mid-tier molders retain this process for REACH-compliant EPDM building stock renovation components.
- Transfer Molding:Plunger-fed material flow enables intricate geometries for aerospace firewall seals and electrical connector boots. The process dominates extreme-temperature applications requiring perfluoroelastomer grades.
- Blow Molding:Parison-based expansion creates hollow elastomer profiles for HVAC ducting and expansion joints. Limited adoption outside fluid handling infrastructure reflects material waste rates and dimensional tolerance challenges.
Injection molding sits at the top of the volume ranking, with transfer molding climbing the fastest on aerospace electrification demand.
End User:
Customer-type concentration determines pricing power and contract duration, with automotive platforms demanding systems-level partnerships while medical device procurement fragments across specialized contract manufacturers.
- Automotive:OEM consolidation around Stuttgart and Wolfsburg production corridors concentrates volume with vertically integrated compounder-molders capable of in-house FEA validation. Battery thermal management specifications are displacing traditional NVH component margins.
- Aerospace:AS9100 and NADCAP certifications create 18-24 month qualification cycles that lock incumbent suppliers into airframe programs. Silicone and fluorocarbon formulations dominate engine seals and cabin pressure systems.
- Consumer Goods:Appliance gaskets, sporting equipment grips, and footwear components operate on shorter design cycles with lower regulatory barriers. Price sensitivity drives procurement toward Asian compounders.
- Medical Devices:FDA 21 CFR Part 177.2600, EU MDR, and ISO 13485 simultaneous compliance extends launch timelines. Liquid silicone injection for minimally invasive surgical instruments commands premium positioning.
Automotive captures the dominant revenue share, with medical devices expanding most quickly on reshoring incentives.
Material:
Material selection locks in downstream certification pathways: platinum-catalyzed silicone chemistry enables thinner-walled surgical components, while natural rubber compounds face phytosanitary documentation for EU import.
- Natural Rubber:Polyisoprene content exceeding 90% delivers superior resilience for tire and vibration isolation applications. Thai and Indonesian supply disruptions from leaf disease outbreaks transmit directly to compounder feedstock costs.
- Synthetic Rubber:EPDM and NBR variants dominate automotive coolant seals and fuel system components. REACH phthalate restrictions and accelerator chemical bans force continuous reformulation.
- Thermoplastic Elastomers:Shore A hardness ranging from 30 to 90 enables overmolding with rigid substrates for consumer electronics and appliance interfaces. Recyclability appeals to closed-loop manufacturing mandates.
- Silicone:Platinum-catalyzed addition cure systems achieve biocompatibility certifications for food-contact and medical applications. High-consistency grades serve EV thermal management in Southeast Asian compounder investments.
Synthetic rubber leads by tonnage, with silicone gaining share fastest on electrification thermal specifications.
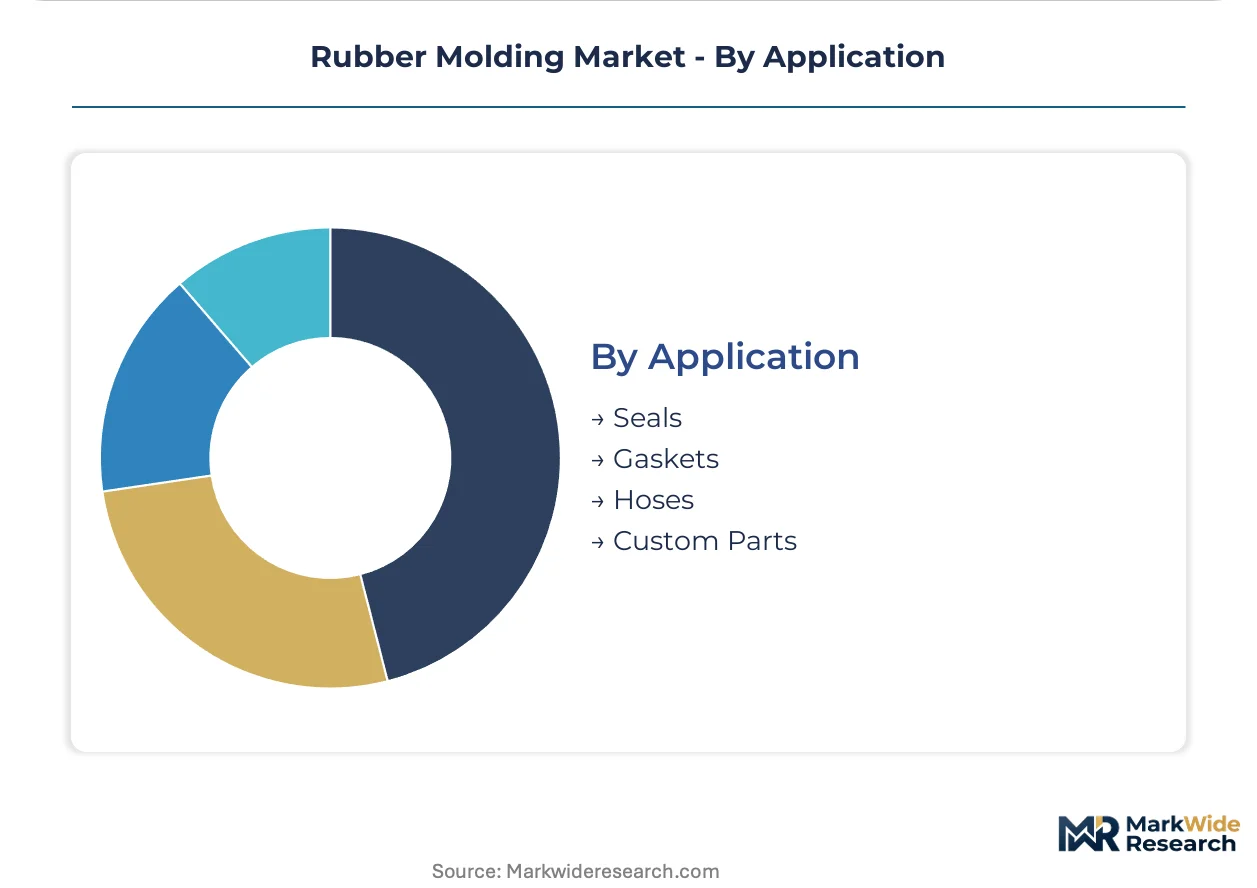
Application:
Functional purpose determines performance thresholds: dynamic seals face wear and compression set requirements, while static gaskets prioritize chemical resistance and dimensional stability under bolt load.
- Seals:Dynamic and static configurations for fluid retention across rotating shafts and flange joints. Automotive electrification is forcing redesign for battery coolant circuits and reduced vibration profiles.
- Gaskets:Compression-set resistant profiles for flange sealing in chemical processing and building HVAC. EU F-Gas Regulation accelerates water-blown EPDM foam adoption.
- Hoses:Reinforced elastomer tubes for fluid and air conveyance in automotive, agriculture, and construction equipment. Multi-layer constructions with textile or wire reinforcement dominate pressure ratings.
- Custom Parts:Application-specific geometries for acoustic control, vibration isolation, and electrical insulation. Sumitomo Riko anchors supply to Japanese and Korean OEM transplant factories in North America.
Seals command the largest volume position, with custom parts ascending fastest on systems-level procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as compounders migrate capacity toward jurisdictions with lower compliance costs for REACH-equivalent chemistry restrictions. German molders absorb premium certification burdens to retain automotive OEM proximity, while Southeast Asian facilities capture EV thermal management volume with streamlined environmental permitting.
Germany
Stuttgart and Wolfsburg production corridors concentrate Tier 1 supplier ecosystems serving BMW, Mercedes-Benz, and Volkswagen electrification programs. EU F-Gas Regulation compliance costs for water-blown EPDM formulations compress margins for independent molders lacking captive compounding. Freudenberg Group anchors material science R&D in Weinheim, specializing in extreme-temperature elastomer specifications for aerospace and powertrain applications.
United States
FDA domestic manufacturing incentives for critical care consumables pull liquid silicone injection capacity back from Asian contract manufacturers. EPA NESHAP standards for volatile organic compound emissions from rubber curing operations shape capital investment decisions at Ohio and Michigan automotive belt suppliers. Cooper Standard and Dana Incorporated maintain compounding-to-finished-part vertical integration across Midwest production networks.
China
MIIT dual carbon goals accelerate pyrolysis-based devulcanization pilot plants for reclaimed carbon black recovery from end-of-life tires. Yangtze River Delta molders serve BYD, NIO, and Tesla Shanghai with high-consistency silicone grades for battery thermal interface materials. Tooling fabrication capacity concentrates in Suzhou and Ningbo precision machining clusters, extending qualification cycles for European automotive platform launches.
Japan
METI chemical management frameworks preempt REACH-style restrictions on microplastic-containing rubber processing compounds. Kanto region suppliers anchor acoustic control component production for Toyota, Honda, and Nissan hybrid platform programs. Sumitomo Riko Company Limited dominates supply to Japanese and Korean OEM transplant factories across North American manufacturing corridors.
India
Production-linked incentive schemes for advanced automotive technology parts attract greenfield molding investments serving Maruti Suzuki and Hyundai Motor India export programs. BIS certification requirements for automotive elastomer specifications create qualification barriers for unorganized sector compounders. Tamil Nadu and Haryana industrial corridors concentrate capacity for coolant seal and vibration isolation component supply to domestic OEMs.
Rubber Molding Market Competitive Environment
German producers anchor one tier; Japanese specialists hold another through acoustic control and precision seal expertise. The vendor base fragments across three tiers: vertically integrated compounder-molders with captive material science capabilities, process-focused contract manufacturers serving medical and aerospace certification requirements, and regional specialists capturing building stock renovation volume under EU F-Gas Regulation compliance windows. Consolidation pressure intensifies as automotive OEMs demand systems-level sealing solutions rather than discrete component procurement. Capacity expansion and strategic partnerships represent the dominant competitive moves, with Korean battery manufacturers extending supplier consolidation patterns to thermal interface material vendors for European gigafactory investments.
Within the vertically integrated tier, Continental AG exemplifies backward integration from rubber compounding through finished seal production to sustain margin capture across the value chain. Among precision seal specialists, Trelleborg AB and NOK Corporation occupy positions defined by extreme-temperature material science capabilities and AS9100 aerospace certification portfolios. Hutchinson SA and Toyoda Gosei Co Ltd represent divergent geographic anchoring strategies—French and Japanese respectively—while serving overlapping automotive electrification thermal management requirements. These named entities function as archetype anchors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Continental AG |
| Freudenberg Group |
| Sumitomo Riko Company Limited |
| Trelleborg AB |
| NOK Corporation |
| Hutchinson SA |
| Toyoda Gosei Co Ltd |
| Cooper Standard |
| Dana Incorporated |
| Others |
Value Chain & Pricing Dynamics
Natural rubber futures on the Tokyo Commodity Exchange cascade through compounder feedstock costs into three distinct pricing tiers for molded elastomer components. Thai and Indonesian supply disruptions from leaf disease outbreaks transmit volatility directly to automotive seal pricing, while silicone grades command premium positioning through platinum-catalyzed chemistry certifications.
Pricing Analysis
Distributor margins of 15-25 percent separate standard EPDM gaskets from medical-grade liquid silicone delivered direct-to-OEM under long-term offtake contracts. Price differentiation hinges on FDA 21 CFR Part 177.2600 certification tier and volume scale, with automotive platforms leveraging systems-level procurement to compress component-level margins. Cost compression in industrial compression molding intensifies because REACH-compliant reformulation raises compound costs. Building stock renovation contractors exhibit highest price sensitivity, while aerospace OEMs absorb premium fluoroelastomer pricing for AS9100-qualified firewall seals.
Supply Chain Analysis
AS9100 and NADCAP qualification gating concentrates aerospace-grade supply among German, Japanese, and US molders with captive metrology capabilities. Raw material dependencies draw from Thai natural rubber plantations, German precision tooling clusters in Stuttgart, and Chinese Yangtze River Delta silicone monomer production. Single-source vulnerability runs through Suzhou mold fabrication capacity, where extended lead times delay European automotive platform launches. Distribution runs through Tier 1 supplier consolidation around Wolfsburg and Stuttgart corridors, with direct-to-molder digital platforms disintermediating traditional industrial gasket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phasedown of hydrofluorocarbon blowing agents is accelerating water-blown EPDM foam demand across European building stock renovation.
For Market Incumbents: Deploy backward integration into captive rubber compounding to defend margin capture against emerging Asian compounders repositioning toward high-consistency silicone grades. Accelerate Weinheim-style R&D center investment in extreme-temperature material science to lock in aerospace qualification cycles. Consolidate systems-level sealing partnerships as automotive OEMs reduce supplier panels per electrification platform. For New Entrants and Emerging Players: Devulcanization technology convergence with pyrolysis offers entry into closed-loop recycling for reclaimed carbon black recovery, a white-space target where incumbent compounders lack scale. Target India's automotive component PLI scheme corridors in Tamil Nadu and Haryana for greenfield molding investments serving Maruti Suzuki export programs. Lead with digital direct-to-molder platforms featuring design-for-manufacturability tools to disintermediate traditional distributor networks in small-batch industrial gasket procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated compounder-molders possessing in-house FEA validation and captive material science capabilities. Long-term viability favors suppliers anchored to battery electric vehicle thermal interface specifications rather than legacy NVH component exposure. Watch Korean battery manufacturer supplier consolidation patterns at European gigafactory investments as the inflection signal for thermal management material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding | Continental AG sustains margin capture across rubber formulation through finished seal production. |
| Devulcanization Technology Scale-Up | Pyrolysis-based reclaimed carbon black recovery enables circular feedstock for EPDM compounds. |
| AS9100 Certification Investment | NADCAP surface treatment accreditation locks suppliers into 18-24 month aerospace qualification cycles. |
| Digital Direct-to-Molder Platform Launch | Online quoting tools disintermediate traditional distributor networks for small-batch gasket procurement. |
| High-Consistency Silicone Capacity Addition | Southeast Asian compounders serve EV thermal management specifications for battery interface materials. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 automotive procurement officers, rubber compounder plant managers, aerospace seal qualification engineers, and medical device contract manufacturing executives with secondary validation. Customs data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed suppliers, and EPA NESHAP compliance disclosures anchored volume estimates. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validated projections across injection, compression, and transfer molding process technologies.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-electrification demand inflection patterns. Segmentation modeling spanned process technology, end-use vertical, material chemistry grade, and component function dimensions across the analysis window. CAGRs derived from elastic demand modeling for automotive content per vehicle, medical device reshoring incentives, and REACH regulatory compliance cost pass-through assumptions.
The model holds under stable natural rubber supply from Thai and Indonesian plantations; deviation in leaf disease outbreak severity or EU F-Gas Regulation enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Global Chloroprene Rubber Market
Rubber
Gum Rosin Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Isoprene Rubber Market
Rubber
Rubber Splicing Tape Market
Rubber
Nitrile Elastomers Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Snap on Rubber Stopper Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Plastomers Market
Rubber
Liquid Polybutadiene Market
Rubber
Polybutadiene Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Europe Silicone Rubber Market