
 Labor Management System in Retail Market | 2026-2036
Labor Management System in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Labor Management System in Retail Market Foresight
The divergence between premium workforce intelligence suites and commodity scheduling tools is hardening. Enterprise-grade platforms now embed AI-driven demand forecasting and real-time labor optimization, while basic tier offerings compete primarily on per-seat pricing. Yoobic leverages mobile-native task management to dominate European grocery and big-box deployments. Tulip sustains technology leadership by anchoring its platform to clienteling and assisted-selling workflows that require tight associate-task coordination. Deputy competes aggressively on speed-to-implement for mid-market specialty retail chains.
A labor management system in retail is an integrated software platform that automates workforce scheduling, time capture, task allocation, and compliance tracking across distributed store networks, typically processing real-time sales data feeds to generate labor-to-demand matching algorithms. Its primary commercial purpose is to minimize labor cost overruns while ensuring regulatory adherence to break rules, minor-hour restrictions, and predictive-scheduling mandates. Cloud-based deployment now leads adoption curves, though hybrid architectures retain share among retailers with legacy ERP entanglements. Mobile technology is accelerating fastest as floor associates gain self-service shift-swap and communication tools. The scheduling solution category captures the deepest margin pools because recurring optimization logic creates stickier renewal economics than transactional time-clock modules.
The US Department of Labor's overtime rule revisions and state-level predictive-scheduling laws in California, New York, and Oregon shape product roadmaps by mandating automated advance-notice and premium-pay calculations. The EU AI Act and GDPR impose algorithmic transparency requirements on European deployments of automated scheduling systems that profile worker availability patterns. Retailers must monitor how emerging AI disclosure obligations interact with workforce analytics investments.
Market Dynamics
Cloud migration is compressing deployment cycles for workforce optimization platforms while predictive-scheduling mandates in multiple states force algorithmic transparency upgrades. Specialty retailers now demand real-time labor-to-demand matching that legacy on-premise systems cannot deliver.
Growth Catalysts
- Predictive-Scheduling Mandates:Oregon and New York laws require automated advance-notice calculations, compelling retailers to replace spreadsheet-based scheduling with compliant platforms.
- Mobile-First Architectures:Floor associates at big-box chains now expect self-service shift-swapping and task notifications through native smartphone applications.
- AI-Driven Demand Forecasting:Integration of machine learning models with point-of-sale data feeds enables dynamic labor allocation during promotional events and seasonal spikes.
Market Restraints
- Legacy ERP Entanglements:Hybrid deployment requirements slow cloud migration for retailers with deeply integrated on-premise payroll and inventory systems.
- GDPR Algorithmic Transparency:The EU AI Act imposes disclosure obligations on automated scheduling systems that profile worker availability patterns, increasing compliance costs.
- Substitution by Native Workforce Modules:Large enterprise resource planning vendors bundle basic scheduling tools, pressuring standalone platform pricing.
Strategic Opportunities
- Task-Clienteling Convergence:Assisted-selling workflows that coordinate associate activities with customer engagement data represent an underdeveloped application layer.
- Mid-Market Speed-to-Implement:Specialty retail chains with fifty to two hundred locations seek rapid deployment without extensive IT overhead.
- State-Level Overtime Rule Revisions:The US Department of Labor's evolving overtime thresholds create recurring demand for automated premium-pay calculation engines.
Industry Challenges
- Integration Complexity with Time-Clock Hardware:Biometric and RFID-based attendance terminals require proprietary middleware that fragments vendor ecosystems.
- Data Science Talent Scarcity:Retailers lack internal expertise to tune demand-forecasting models, creating dependency on vendor professional services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labor Management System in Retail Market |
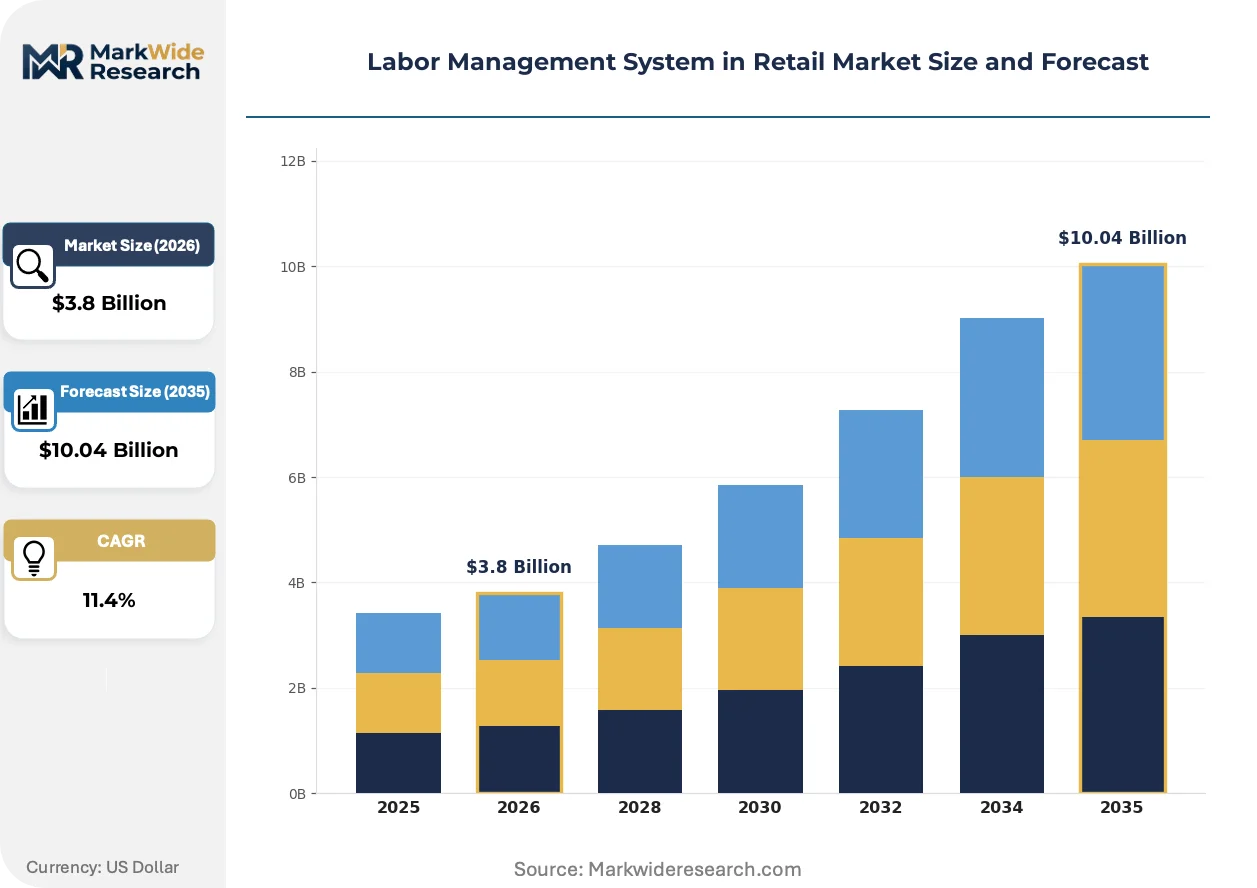
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premise, Hybrid, Mobile Deployment: Public Cloud, Private Cloud, SaaS, Self-Hosted End User: Supermarkets, Department Stores, Specialty Retailers, E-Commerce Solution: Scheduling, Time and Attendance, Performance Management, Compliance |
| Companies Covered | Yoobic, Tulip, Workjam, Deputy, Workforce.com, Rallyware, Zipline, TimeForge, Axonify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labor Management System in Retail Market Shifts & Advancements
Workforce intelligence platforms are embedding generative AI for natural-language schedule queries while regulatory pressure accelerates algorithmic audit capabilities. These shifts are compressing the gap between enterprise-grade optimization and mid-market accessibility.
Generative AI interfaces are rewriting how store managers interact with scheduling systems. District managers at grocery chains now query labor forecasts through conversational prompts rather than static dashboards. This capability is compressing the training burden for seasonal supervisor rotations and expanding platform adoption among non-technical users.
The EU AI Act's risk-classification framework for employment-related algorithms is forcing disclosure of automated decision logic. European deployments must now document how scheduling systems weight worker availability against business demand. Retailers operating across Germany, France, and the Netherlands are consolidating vendor selection around platforms with built-in audit trails.
Subscription pricing for optimization modules is displacing perpetual licensing for basic time-capture functions. Mid-market specialty chains now expect consumption-based fees tied to scheduled labor hours rather than fixed seat counts. This shift is most visible in California, where predictive-scheduling compliance costs make outcome-based vendor relationships preferable to capital-intensive purchases.
Labor Management System in Retail Market Segmentation
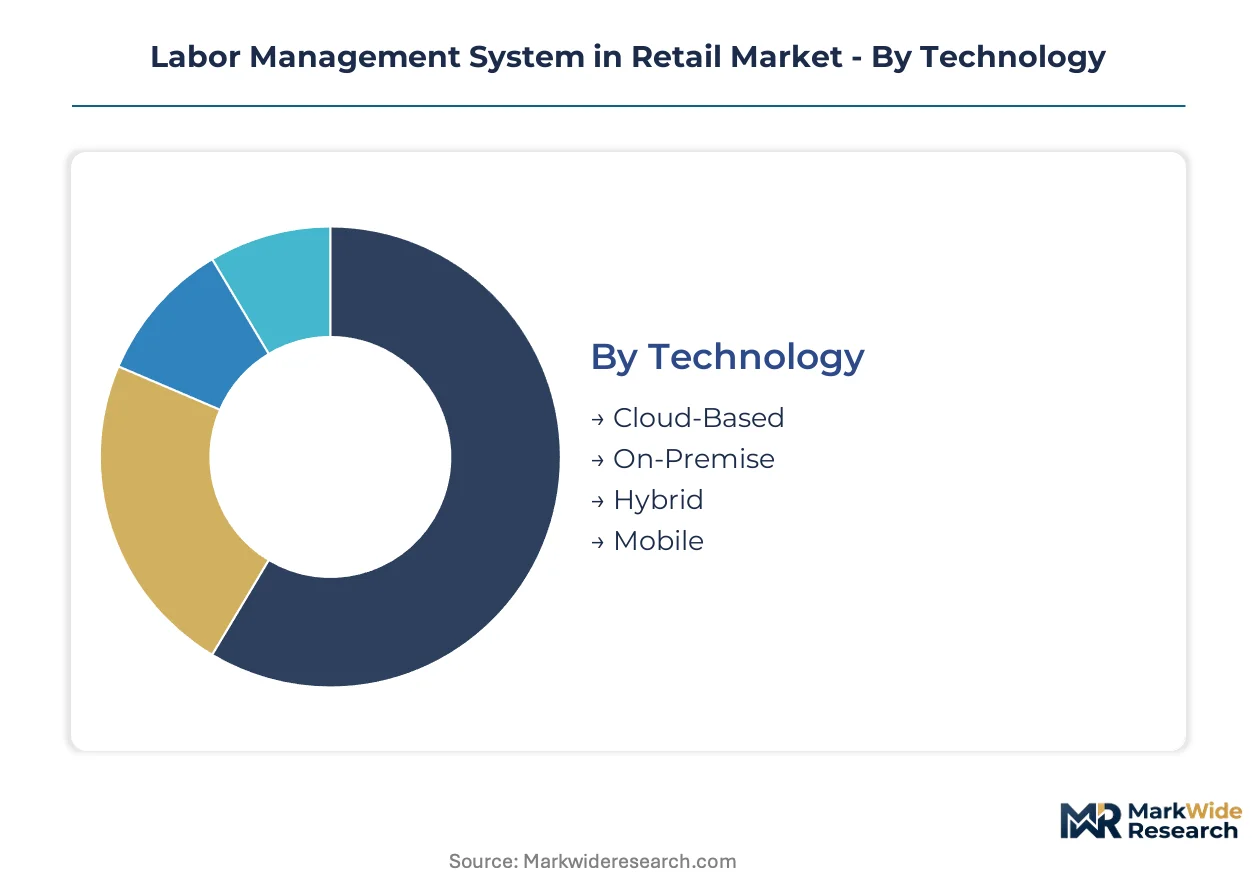
Labor management platforms serve heterogeneous retail environments with divergent IT maturity, regulatory exposure, and workforce scale. Segmentation reveals where capital deployment concentrates and which configurations deliver measurable labor cost compression.
Technology:
Cloud-based architectures demand the lowest upfront capital outlay, while on-premise installations require substantial server infrastructure and dedicated IT staffing.
- Cloud-Based:Multi-tenant SaaS platforms eliminate hardware procurement and accelerate deployment cycles for distributed store networks. Specialty retailers in California and New York prioritize this model to satisfy predictive-scheduling mandates without capital-intensive infrastructure.
- On-Premise:Single-tenant installations running on retailer-owned servers retain favor among large grocery chains with legacy ERP entanglements and stringent data residency requirements. These deployments absorb significant IT labor for patch management and security hardening.
- Hybrid:Split architectures route sensitive payroll data through on-premise gateways while pushing scheduling logic to cloud instances. Mid-market department stores adopt this compromise to balance compliance control with mobile accessibility.
- Mobile:Native smartphone applications for shift swapping and task management require minimal backend investment but demand continuous UX refinement. Big-box chains in the United States deploy these most aggressively for floor associate engagement.
Cloud-based systems absorb the bulk of installed capacity; mobile is expanding most quickly.
Deployment:
Operational control preferences segment retailers between fully managed SaaS and infrastructure-retaining self-hosted models.
- Public Cloud:Shared infrastructure pools deliver elastic scaling during seasonal demand spikes without capacity planning overhead. E-commerce fulfillment networks leverage this model for warehouse labor surges tied to promotional calendars.
- Private Cloud:Dedicated single-tenant environments isolate scheduling data from co-tenant security risks. European supermarkets facing GDPR algorithmic transparency mandates favor this deployment for audit trail isolation.
- SaaS:Subscription consumption models convert capital expenditure to operational spending with automatic feature updates. Specialty retail chains with fifty to two hundred locations select this path to minimize IT overhead.
- Self-Hosted:Complete infrastructure ownership permits deep customization of labor optimization algorithms. Large department store holding companies retain this model to preserve competitive differentiation in workforce analytics.
SaaS deployments command the largest share of new implementations; private cloud is climbing the fastest among compliance-sensitive European operators.
End User:
Workforce scale and scheduling complexity create divergent functional requirements across retail formats.
- Supermarkets:High-volume, high-frequency scheduling environments with unionized workforces and strict break-rule enforcement. Chains across Germany and France invest heavily in automated compliance engines to manage variable shift lengths.
- Department Stores:Complex multi-department staffing with seasonal volume swings and commission-based selling roles. These retailers prioritize clienteling-integrated task management to coordinate associate activities with customer engagement.
- Specialty Retailers:Smaller format footprints with fluctuating foot traffic and lean management structures. Oregon and California specialty chains drive demand for rapid-deployment platforms with minimal configuration.
- E-Commerce:Warehouse-centric labor optimization focused on pick productivity and fulfillment SLA adherence. These operations emphasize real-time labor-to-demand matching during promotional events.
Supermarkets maintain the deepest installed base; specialty retailers are gaining share fastest as cloud migration accelerates.
Solution:
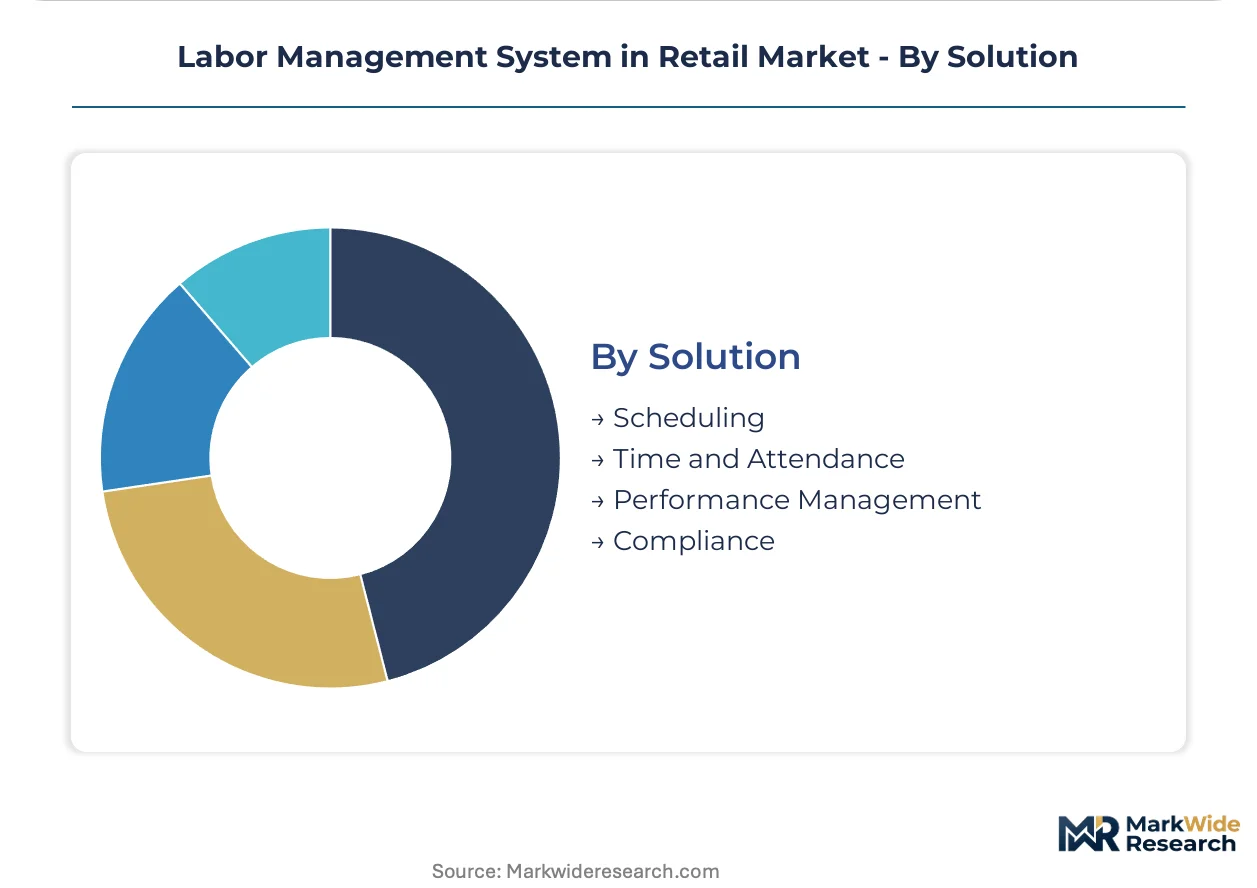
Functional modules vary in margin contribution and renewal stickiness, with optimization logic commanding premium pricing over transactional capture.
- Scheduling:AI-driven demand forecasting and automated labor-to-demand matching form the core optimization layer. This module generates the stickiest renewal economics through continuous algorithmic refinement.
- Time and Attendance:Biometric and RFID-based clock-in systems with payroll integration. Hardware fragmentation and middleware complexity create implementation friction for multi-vendor environments.
- Performance Management:Associate productivity tracking and goal-setting workflows. These tools expand platform value beyond cost control into revenue-enablement for assisted-selling formats.
- Compliance:Automated calculation engines for overtime, predictive-scheduling premiums, and minor-hour restrictions. State-level regulatory divergence in the United States drives recurring demand for rules-engine updates.
Scheduling solutions capture the deepest margin pools; compliance modules are expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors workforce technology development, with specialized vendors clustering around Silicon Valley's enterprise software corridor and cloud infrastructure providers.
United States
Specialty retailers in Oregon and New York drive platform adoption to satisfy predictive-scheduling mandates requiring automated advance-notice calculations. The US Department of Labor's overtime rule revisions compel investment in premium-pay calculation engines. California's Bay Area concentrates vendor headquarters and early-deployment grocery chains testing AI-driven demand forecasting.
Germany
Supermarket operators across Bavaria and North Rhine-Westphalia prioritize automated compliance engines for unionized workforces with variable shift lengths. The EU AI Act imposes algorithmic transparency requirements on automated scheduling systems profiling worker availability. Frankfurt's retail technology cluster hosts integration specialists connecting workforce platforms to legacy ERP systems.
France
Department stores in Île-de-France invest in clienteling-integrated task management to coordinate associate activities with customer engagement data. GDPR mandates disclosure obligations on workforce analytics investments. Paris-based retail groups pilot private-cloud deployments to isolate scheduling data for audit trail compliance.
United Kingdom
Mid-market specialty chains across Greater London and the Midlands seek rapid-deployment SaaS platforms with minimal IT overhead. The country's national labor regulator enforces working-time regulations requiring automated break-rule enforcement. Manchester's retail technology corridor attracts vendors targeting fifty-to-two-hundred-location deployments.
Japan
Big-box chains in the Kanto region deploy mobile-native applications for floor associate shift-swapping and task notifications. METI guidelines shape workforce digitization incentives for retail productivity improvement. Tokyo's omni-channel retail clusters drive integration between warehouse labor optimization and store scheduling systems.
Labor Management System in Retail Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithmic sophistication and compliance automation depth. The vendor base stratifies into three tiers: enterprise-grade platforms embedding AI-driven demand forecasting, mid-market speed-to-implement specialists, and mobile-first task management providers. Strategic moves concentrate on M&A for predictive analytics capabilities and geographic expansion through cloud-native distribution.
Within the mobile-native tier, Yoobic and Workjam exemplify European grocery and big-box deployment specialists. Deputy occupies a position among mid-market speed-to-implement providers targeting specialty retail chains. Tulip anchors the clienteling-integrated segment where assisted-selling workflows demand tight associate-task coordination.
| Leading Market Players |
|---|
| Yoobic |
| Tulip |
| Workjam |
| Deputy |
| Workforce.com |
| Rallyware |
| Zipline |
| TimeForge |
| Axonify |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up workforce software specialists have consolidated scheduling and time-tracking vendors across California and New York, compressing pricing discipline while extending cloud infrastructure commitments that lock in recurring revenue streams.
Pricing Analysis
Value-based pricing anchored to labor-hour outcomes now dominates California deployments, where predictive-scheduling compliance costs make per-seat models untenable. Three-tier pricing structure across premium AI-optimization, standard SaaS, and economy time-capture levels reflects algorithmic sophistication gaps. Cost compression in the economy tier is intensifying because ERP vendors bundle basic scheduling modules at marginal cost. Mid-market specialty retailers exhibit highest price sensitivity; enterprise grocery chains prioritize compliance automation over per-seat economics.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Ireland, and Germany, with latency-sensitive workforce data routing through edge nodes near retail headquarters. Software development draws from Indian engineering services, U.S. machine-learning talent pools, and Eastern European QA specialists. Single-source vulnerability in biometric time-clock hardware creates fragmentation risk for multi-vendor deployments. Distribution runs through direct SaaS provisioning and value-added reseller networks serving mid-market chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around AI-optimization capabilities, with predictive-scheduling regulatory complexity forcing standalone time-clock vendors toward acquisition or exit.
For Market Incumbents:To counter ERP vendor bundling, deepen algorithmic moats through acquisition of demand-forecasting specialists and anchor platform stickiness in compliance engine subscriptions. Vertical integration into biometric hardware middleware reduces integration friction for grocery chain deployments.
For New Entrants and Emerging Players:Mid-market specialty retailers in Oregon and New York represent the most penetrable buyer archetype, underserved by enterprise-grade complexity and economy-tier limitations. Rapid-deployment SaaS with mobile-native shift-swapping captures share from legacy on-premise installations. Channel partnerships with regional payroll providers accelerate speed-to-revenue without direct enterprise sales overhead.
For Investors and Strategic Acquirers:EU AI Act enforcement actions against opaque scheduling algorithms are the leading indicator that audit-trail capabilities will determine platform viability across European deployments. Long-term positioning favors vendors with built-in algorithmic transparency documentation. Acquisition targets should demonstrate GDPR-compliant workforce analytics with existing supermarket deployments in Germany or France. Watch for state-level predictive-scheduling expansion beyond Oregon, New York, and California as the signal for accelerated compliance-driven replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Demand-Forecasting Specialist | Machine-learning talent scarcity makes pre-trained labor optimization models irreplaceable. |
| Biometric Hardware Middleware Integration | Proprietary time-clock connectivity reduces implementation friction for unionized grocery chains. |
| EU Algorithmic Audit Trail Development | GDPR and EU AI Act disclosure mandates now gate European supermarket procurement decisions. |
| Mobile-Native Task Management Launch | Floor associate self-service tools differentiate platforms for big-box workforce engagement. |
| Mid-Market Speed-to-Implement Program | Fifty-to-two-hundred-location specialty retailers prioritize deployment velocity over feature depth. |
Research Methodology
Document review covered SEC filings from workforce software vendors, EU regulatory guidance on algorithmic transparency, and state labor department predictive-scheduling enforcement records, complemented by interviews with retail workforce technology directors, grocery chain operations executives, specialty retail franchise operators, and compliance officers at multi-state employers. Secondary validation drew from OSHA workplace safety data, U.S. Department of Labor overtime rule dockets, and cloud infrastructure provider service region disclosures. Bottom-up deployment estimates triangulated against top-down software spending benchmarks across the analysis window.
Installed base projections and revenue estimates were generated through modeling of deployment model, retailer size tier, vertical format, and geographic regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated point-of-sale data integration penetration rates and mobile application adoption curves specific to floor associate workforce demographics.
Revisions become necessary when federal overtime threshold adjustments, new state predictive-scheduling enactments, or EU AI Act enforcement precedents materialize outside modeled assumptions. Forecasts reflect documented scenario parameters and stated elasticity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Service Mesh Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
G2P Systems Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Global Application Container Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Data Governance Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Digital Pen Market