
 Artificial Intelligence HPC Cloud Market | 2026-2036
Artificial Intelligence HPC Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence HPC Cloud Market Insights
Cloud service provider channel access is narrowing as hyperscalers consolidate GPU allocation contracts with preferred enterprise customers. Amazon Web Services Inc. leverages its custom Trainium and Inferentia silicon to reduce NVIDIA dependency in training pipelines. Microsoft Corp. anchors its competitive position through deep Azure integration with OpenAI model serving infrastructure. Google Cloud differentiates via its TPU v5p pods and competitive pricing for large-scale transformer training workloads.
Artificial Intelligence HPC Cloud denotes distributed computing environments delivering petaflop-scale tensor operations through virtualized GPU clusters, Infiniband interconnects, and containerized orchestration platforms for iterative model optimization. These systems execute mixed-precision matrix multiplication at scale to compress training timelines for billion-parameter neural architectures across federated data estates. Public cloud deployment leads absolute spending as burst-capacity economics outweigh private infrastructure capital commitments for most enterprise AI programs. Healthcare end users represent the fastest-expanding consumption vertical as FDA-regulated diagnostic algorithms require elastic validation compute. Deep learning technology segments command premium pricing due to sparse attention mechanisms and multimodal fusion workloads that saturate memory bandwidth.
FDA scrutiny of AI-enabled medical devices shapes validation requirements for cloud-hosted training environments, while the EU AI Act imposes conformity assessment obligations on providers of general-purpose AI models above computational thresholds. NIST AI Risk Management Framework guidance increasingly filters into federal procurement standards for cloud-based AI services. Stakeholders must monitor evolving export control classifications on advanced GPU clusters and preemptively architect multi-region compliance strategies before jurisdictional fragmentation hardens operational constraints.
Market Dynamics
GPU allocation scarcity is restructuring competitive access across cloud providers, as hyperscalers prioritize enterprise contracts with committed spend thresholds over on-demand provisioning for research institutions and mid-market firms.
Growth Catalysts
- EU AI Act Conformity Requirements:High-risk automated decision systems mandate documented training provenance, driving pharmaceutical and financial services firms toward compliant cloud environments with audit-ready infrastructure.
- Molecular Simulation Workloads:Drug discovery pipelines at biotechnology firms now require petaflop-scale tensor operations for protein folding prediction, compressing timelines from years to months.
- Northern Virginia Cluster Density:Hyperscaler data center concentration in Loudoun County delivers sub-millisecond latency to East Coast enterprise headquarters, anchoring financial services and defense contractor adoption.
Market Restraints
- NVIDIA Supply Concentration:Advanced GPU fabrication depends on TSMC's N4 process node, creating single-source vulnerability for training clusters requiring H100 or Blackwell architectures.
- Export Control Friction:US Bureau of Industry and Security licensing restrictions on A100 and H100 shipments to China fragment global deployment strategies and complicate multi-region architectures.
- Memory Bandwidth Saturation:Sparse attention mechanisms in transformer models exceed HBM3e throughput limits, forcing batch size reductions that extend training timelines.
Strategic Opportunities
- India PLI Scheme for Semiconductor Design:Production-linked incentives for AI chip development are attracting hyperscaler R&D centers to Bangalore and Hyderabad, creating captive silicon alternatives to NVIDIA dependency.
- Federated Learning Architectures:Privacy-preserving distributed training across hospital networks without data centralization opens regulated healthcare deployments previously blocked by HIPAA constraints.
- Neuromorphic-Quantum Convergence:Early-stage integration of photonic co-processors with conventional GPU clusters promises order-of-magnitude efficiency gains for optimization workloads in logistics and materials science.
Industry Challenges
- Distributed Systems Engineering Talent:Shortage of engineers proficient in Infiniband topology optimization and NCCL collective communication tuning extends cluster deployment timelines.
- FDA Validation Documentation:Cloud-hosted training environments for diagnostic algorithms require 21 CFR Part 11 compliant audit trails, forcing infrastructure re-architecture mid-deployment.
- Legacy On-Premise Integration:Enterprises with sunk capital in private HPC clusters face friction migrating hybrid workloads due to incompatible job schedulers and identity management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence HPC Cloud Market |
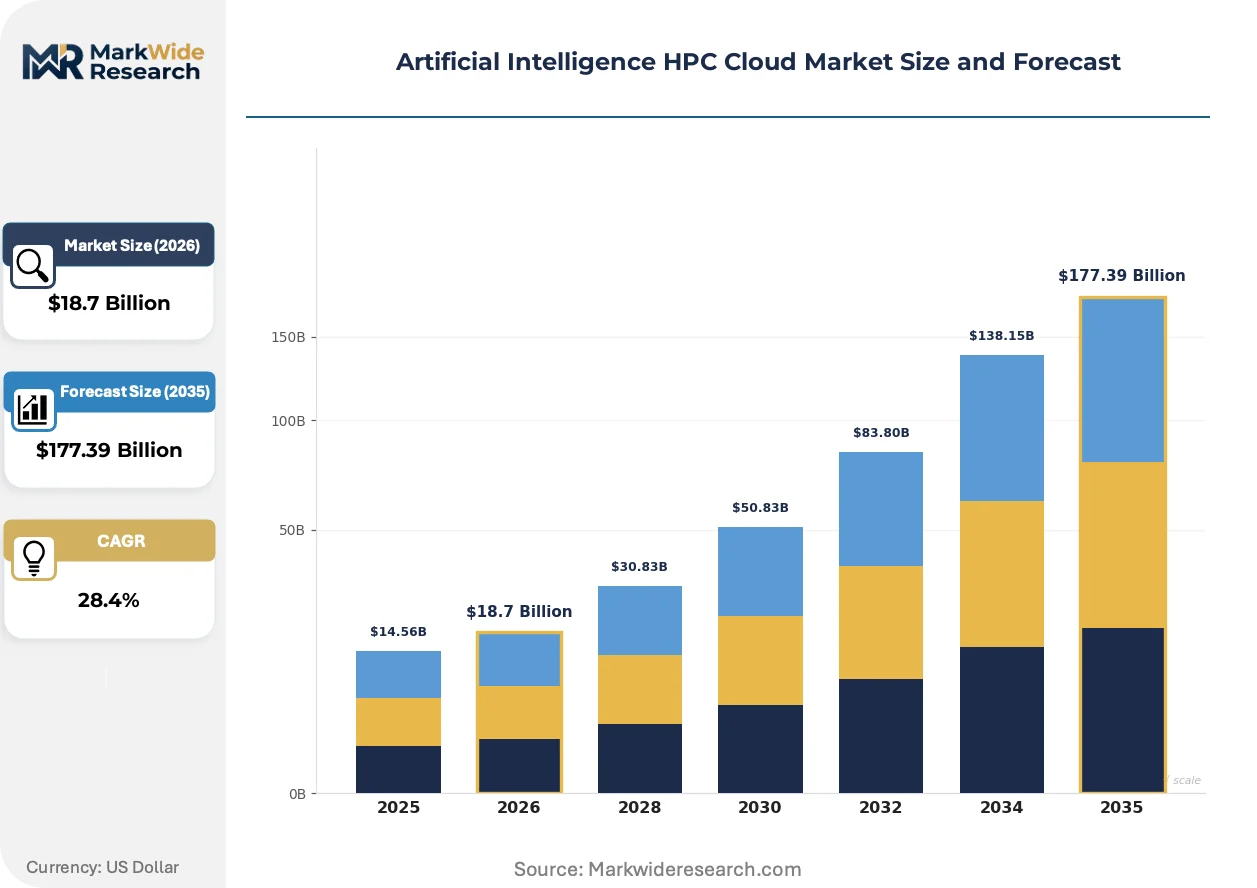
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Healthcare, Financial Services, Retail, Manufacturing Solution: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service Technology: Deep Learning, Machine Learning, Natural Language Processing, Computer Vision |
| Companies Covered | Amazon Web Services Inc., Microsoft Corp., Google Cloud, NVIDIA Corp., Intel Corp., Hewlett Packard Enterprise Co., International Business Machines Corp., Dell Technologies Inc., Advanced Micro Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence HPC Cloud Market Trends and Innovations
Computational architectures are fragmenting as custom silicon, optical interconnects, and software-defined orchestration layers compete to displace homogeneous GPU clusters as the dominant training paradigm.
Custom AI accelerators from cloud providers are hybridizing the training stack. AWS Trainium2 and Google TPU v5p pods execute mixed-precision matrix operations at competitive throughput while reducing NVIDIA silicon dependency. Pharmaceutical firms and autonomous vehicle developers now split workloads across multiple accelerator types based on model architecture, compressing unit economics for billion-parameter training runs.
The EU AI Act's computational threshold triggers are reshaping provider obligations. General-purpose models trained above specified FLOP levels face conformity assessment requirements before market deployment. Cloud providers serving European healthcare and financial services customers are pre-emptively implementing model cards, dataset documentation, and red-teaming protocols to avoid service suspension.
Consumption-based pricing models are displacing reserved instance commitments for experimental AI workloads. Research institutions and startups now favor spot-preemptible GPU capacity with checkpoint-restart orchestration over long-term contracts. This shift concentrates in the United States where hyperscaler spot market liquidity exceeds European or Asian alternatives, creating geographic arbitrage in compute procurement strategies.
Artificial Intelligence HPC Cloud Market Segmentation
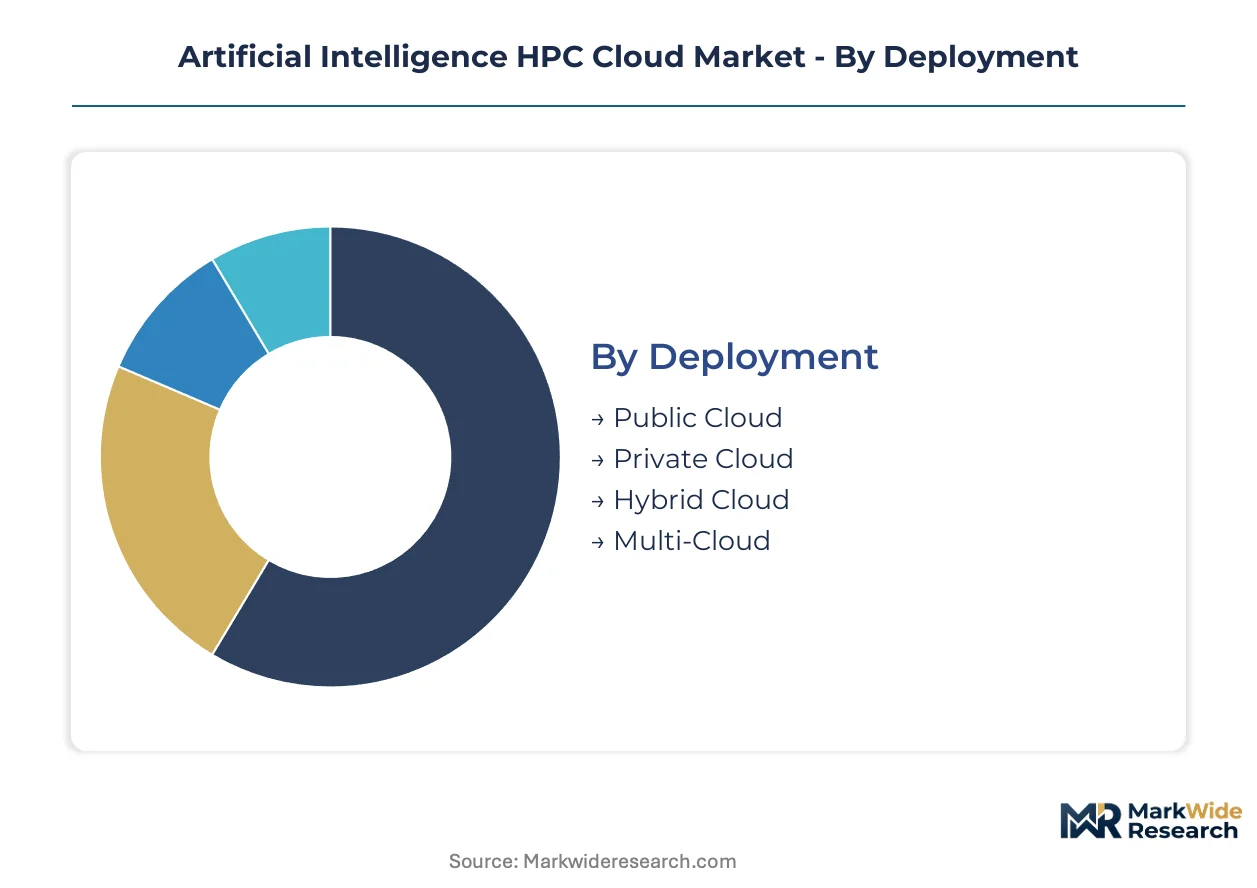
Segmentation in the AI HPC Cloud market reveals how workload economics, regulatory exposure, and infrastructure maturity fragment purchasing behavior across enterprise tiers. Deployment models diverge sharply between burst-capacity researchers and compliance-bound pharmaceutical validators, while technology choices map directly to memory bandwidth requirements and silicon availability.
Deployment:
Cost tier determines access priority as GPU scarcity forces hyperscalers to ration capacity through contract structures rather than spot pricing alone.
- Public Cloud:Virtualized GPU clusters deliver petaflop-scale tensor operations through on-demand or reserved instance models. Pharmaceutical firms in Northern Virginia leverage burst capacity for molecular simulation pipelines, though FDA validation requirements increasingly demand documented training provenance that public environments struggle to provide.
- Private Cloud:Dedicated infrastructure isolates workloads for HIPAA-regulated healthcare deployments and export-controlled defense contractors. Financial services firms in Oregon data clusters favor private deployments for algorithmic trading models where latency consistency outweighs elasticity premiums.
- Hybrid Cloud:Split architectures anchor baseline training in private environments while bursting validation workloads to public capacity. Manufacturing quality-control systems use hybrid models to balance sensitive inspection data against seasonal demand spikes.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and Google Cloud mitigate single-provider GPU allocation risk. Retail recommendation engines deploy multi-cloud strategies to circumvent vendor lock-in during silicon supply disruptions.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
End User:
Application-specific compliance burdens reshape infrastructure procurement, with FDA and EU AI Act obligations creating divergent technical requirements across verticals.
- Healthcare:Diagnostic algorithm training demands 21 CFR Part 11 compliant audit trails and elastic validation compute for FDA submissions. Hospital networks in the United States concentrate consumption around federated learning architectures that preserve HIPAA boundaries.
- Financial Services:Real-time risk modeling and algorithmic trading drive sub-millisecond latency requirements. Northern Virginia proximity to hyperscaler clusters anchors East Coast bank adoption, though EU AI Act conformity assessments complicate European deployment.
- Retail:Recommendation engines and demand forecasting utilize spot-preemptible capacity with checkpoint-restart orchestration. Seasonal elasticity needs favor consumption-based pricing over reserved commitments.
- Manufacturing:Computer vision quality inspection and predictive maintenance workloads split between edge inference and cloud training. Supply chain optimization models increasingly demand neuromorphic-quantum convergence pilots.
Healthcare commands premium pricing per FLOP. Retail is gaining share fastest through spot market arbitrage.
Solution:
Customer type and internal engineering maturity determine abstraction layer preferences, with enterprises trading control for deployment velocity.
- Infrastructure as a Service:Bare-metal GPU access with Infiniband interconnects serves autonomous vehicle developers and biotechnology firms requiring NCCL tuning flexibility for billion-parameter models.
- Platform as a Service:Containerized orchestration with pre-configured ML pipelines accelerates time-to-model for mid-market firms lacking distributed systems engineering talent.
- Software as a Service:Fully managed model serving abstracts infrastructure entirely, appealing to healthcare institutions prioritizing FDA validation documentation over architectural control.
- Function as a Service:Event-driven inference scaling matches intermittent workloads like retail fraud detection, though cold-start latency limits adoption in real-time financial applications.
Infrastructure as a Service holds installed capacity. Platform as a Service is rotating up the share rankings.
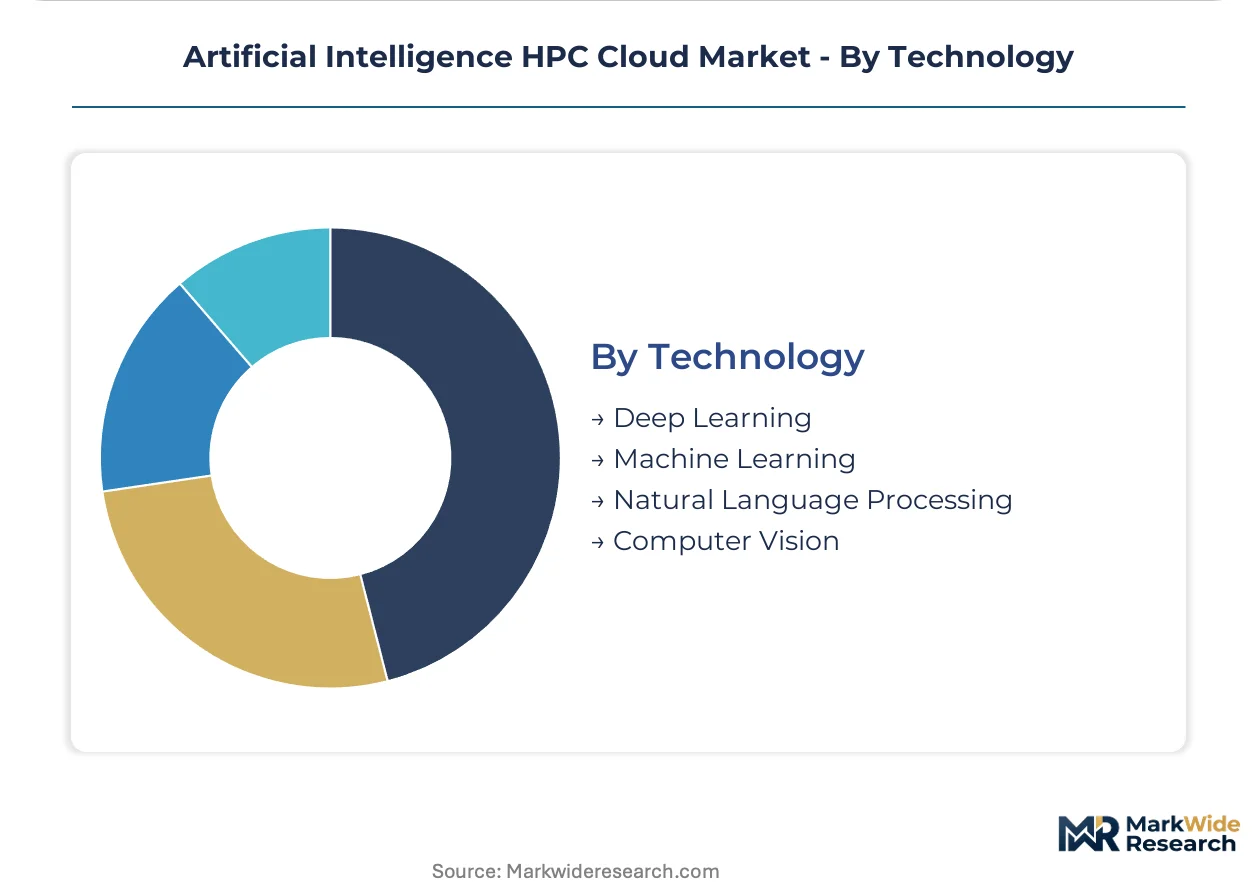
Technology:
Volume and memory bandwidth saturation dictate accelerator selection, with sparse attention mechanisms forcing batch size reductions that extend training timelines.
- Deep Learning:Transformer architectures with multimodal fusion workloads saturate HBM3e throughput and command premium pricing. Protein folding prediction at biotechnology firms exemplifies the petaflop-scale requirements defining this segment.
- Machine Learning:Traditional gradient-boosted and random forest models execute efficiently on CPU-GPU hybrid clusters with lower memory bandwidth demands. Manufacturing predictive maintenance relies on these approaches for cost-effective retraining cycles.
- Natural Language Processing:Large language model fine-tuning concentrates in TPU v5p pods and Trainium2 instances as cloud providers push custom silicon alternatives to NVIDIA dependency.
- Computer Vision:Convolutional and vision transformer workloads split training across cloud clusters while pushing inference to edge devices. Retail visual search and manufacturing defect detection drive diverging latency requirements.
Deep Learning holds installed capacity. Natural Language Processing is climbing the fastest as foundation model adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dulles Technology Corridor's fiber-dense infrastructure underwrites United States dominance in AI HPC Cloud capacity, with sub-millisecond latency to hyperscaler clusters anchoring financial services and defense contractor demand. This concentration shapes procurement patterns across enterprise tiers.
United States
Pharmaceutical firms and autonomous vehicle developers drive petaflop-scale consumption in Northern Virginia and Oregon data clusters. FDA scrutiny of AI-enabled medical devices forces 21 CFR Part 11 compliant audit trails for cloud-hosted training environments. Loudoun County hosts the densest concentration of hyperscaler GPU capacity globally, with Microsoft Corp. and Amazon Web Services Inc. operating contiguous facilities.
Germany
Automotive OEMs and industrial machinery manufacturers demand elastic compute for generative design and simulation workloads. The EU AI Act imposes conformity assessment obligations on general-purpose AI models above computational thresholds, redirecting pharmaceutical validation spend toward documented training provenance. Frankfurt's DE-CIX interconnect anchors Central European data gravity for latency-sensitive financial modeling.
China
Domestic cloud providers accelerate custom silicon development as US Bureau of Industry and Security restrictions fragment NVIDIA supply access. The national pharmaceutical regulator tightens validation requirements for AI diagnostic algorithms deployed in hospital networks. Beijing-Tianjin-Hebei corridor concentrates government-funded training clusters for large language model development.
India
Production-linked incentives for semiconductor design attract hyperscaler R&D centers to Bangalore and Hyderabad, creating captive silicon alternatives. The central bank's digital payment infrastructure demands real-time fraud detection compute that scales elastically during festival-season transaction spikes. Telangana's AI City project anchors domestic cloud capacity expansion for regulated financial services workloads.
United Kingdom
London's algorithmic trading ecosystem demands sub-millisecond proximity to hyperscaler clusters for real-time risk modeling. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit AI device validation with FDA precedent, easing transatlantic pharmaceutical deployment. Slough's data center corridor concentrates financial services consumption alongside emerging biotechnology firms.
Artificial Intelligence HPC Cloud Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the silicon layer. Hyperscalers consolidate GPU allocation contracts with preferred enterprise customers, narrowing channel access for mid-market firms and research institutions. Three archetypes dominate: cloud-native platform operators, custom silicon designers, and legacy infrastructure vendors pivoting toward AI-optimized stacks. Competitive moves concentrate on strategic partnerships for model serving infrastructure and geographic capacity expansion to circumvent export control friction.
Within the hyperscaler tier, Amazon Web Services Inc., Microsoft Corp., and Google Cloud occupy positions defined by custom accelerator strategies and deep enterprise integration. AWS leverages Trainium and Inferentia silicon to reduce NVIDIA dependency in training pipelines. Microsoft anchors its competitive position through Azure integration with OpenAI model serving infrastructure. Google Cloud differentiates via TPU v5p pods and competitive pricing for transformer training workloads.
| Leading Market Players |
|---|
| Amazon Web Services Inc. |
| Microsoft Corp. |
| Google Cloud |
| NVIDIA Corp. |
| Intel Corp. |
| Hewlett Packard Enterprise Co. |
| International Business Machines Corp. |
| Dell Technologies Inc. |
| Advanced Micro Devices Inc. |
| Others |
Pricing and Supply Chain Analysis
Loudoun County's hyperscaler cluster concentration in Northern Virginia concentrates GPU allocation power among AWS, Microsoft, and Google, enabling committed-spend contract structures that marginalize on-demand pricing for research institutions and mid-market firms. This geographic supply gravity translates directly into tiered access economics where pharmaceutical validators with FDA documentation requirements absorb premium elasticity costs unavailable to academic workloads.
Pricing Analysis
Three-tier pricing structure across premium reserved instances, standard committed-use contracts, and economy spot-preemptible capacity dominates procurement. Price differentiation rests on audit-trail certification grade for FDA-regulated healthcare workloads and volume scale for autonomous vehicle developers. Cost compression in spot-tier capacity is intensifying because hyperscaler spot market liquidity concentrates in United States regions, creating geographic arbitrage. Research institutions exhibit highest price sensitivity; defense contractors with export-controlled workloads show lowest sensitivity due to compliance-driven private deployment mandates.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for advanced GPU clusters. Fabrication concentrates in Taiwan through TSMC's N4 process node, with assembly and testing distributed across Malaysia and Vietnam. Raw material dependencies span HBM3e memory stacks from South Korea, CoWoS packaging substrates from Taiwan, and rare earth elements for magnetics from China. Single-source vulnerability in TSMC's leading-edge node feeds NVIDIA H100 and Blackwell allocation scarcity. Distribution runs through hyperscaler direct-enterprise contracts rather than channel partners, compressing mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI HPC Cloud market rewards organizations commanding scarce distributed systems engineering talent capable of Infiniband topology optimization and NCCL collective communication tuning. Infrastructure procurement decisions increasingly hinge on documented training provenance capabilities rather than raw compute economics alone.
For Market Incumbents: Harden GPU allocation contracts with multi-year committed spend thresholds to preempt custom silicon alternatives from eroding NVIDIA-dependent training margins. Anchor defensive positioning through preemptive EU AI Act conformity assessment infrastructure for pharmaceutical and financial services verticals. Expand captive silicon design partnerships in India to reduce TSMC single-source exposure.
For New Entrants and Emerging Players: India's Telangana AI City and domestic cloud capacity expansion represent underpenetrated infrastructure deployment opportunities. Target federated learning architectures for hospital networks blocked by HIPAA constraints from centralized data estates. Pursue neuromorphic-quantum convergence pilots for logistics optimization workloads as a differentiated entry vector.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom accelerator designers with hyperscaler captive demand over homogeneous GPU cluster operators. Long-term viability concentrates in firms with backward integration into semiconductor design or forward integration into model serving infrastructure. Watch FDA validation documentation automation capabilities as inflection signal for healthcare vertical capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development Partnership | AWS Trainium2 and Google TPU v5p pods reduce NVIDIA dependency in billion-parameter training pipelines. |
| EU AI Act Conformity Infrastructure | Documented training provenance and model cards preempt service suspension for European healthcare deployments. |
| Multi-Region GPU Allocation Architecture | Orchestrated workloads across AWS, Azure, and Google Cloud mitigate single-provider silicon supply disruptions. |
| Federated Learning Platform Deployment | Privacy-preserving distributed training opens HIPAA-regulated hospital networks previously blocked from cloud centralization. |
| Neuromorphic-Quantum Convergence Pilot | Photonic co-processor integration with GPU clusters promises efficiency gains for logistics optimization workloads. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, FDA 510(k) submission databases, and EU AI Act regulatory filings. Interviews with cloud infrastructure procurement officers, distributed systems engineers at biotechnology firms, regulatory affairs leads at medical device manufacturers, and GPU supply chain sourcing managers inform qualitative assessments. Secondary validation draws from SEC 10-K infrastructure investment disclosures, TSMC earnings call commentary on advanced packaging capacity, and hyperscaler spot market pricing datasets. Bottom-up workload modeling triangulates against top-down market sizing across deployment modes and end-user verticals.
Forecast inputs span public cloud reserved instance commitments, private cloud dedicated infrastructure deployments, hybrid burst-capacity utilization patterns, and multi-cloud orchestration adoption curves. Segmentation dimensions include deployment model, end-user vertical, solution abstraction layer, and accelerator technology type. CAGRs derive from elasticity coefficient modeling against pharmaceutical molecular simulation pipeline expansion and autonomous vehicle training cluster demand. Industry-specific inputs incorporate FDA validation timeline compression effects and EU AI Act computational threshold triggers.
The forecast holds incumbent behavior within observed patterns; aggressive custom silicon deployment by cloud-native operators or sudden TSMC capacity expansion would shift outcomes beyond modeled bounds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Global AI in Social Media Market