
 Life Sciences BPO Market | 2026-2036
Life Sciences BPO Market Size, Share, and Industry Trends Forecast 2026-2036
Life Sciences BPO Market Intelligence
Advanced analytics platforms are broadening the economic viability of decentralized clinical trials by reducing site infrastructure costs and patient dropout rates. IQVIA leverages its real-world evidence databases to anchor large-scale observational studies across multiple therapeutic areas. Thermo Fisher Scientific (PPD) sustains global laboratory networks that support biomarker-driven trial designs. Charles River Laboratories specializes in preclinical safety assessment, occupying a critical position before human-phase outsourcing begins.
Life Sciences BPO encompasses the externalized execution of pharmaceutical research, regulatory compliance, and pharmacovigilance functions through specialized service providers operating under formal quality agreements and Good Clinical Practice protocols. These arrangements transfer operational risk from sponsor companies to vendors while maintaining FDA, EMA, and ICH standards across data integrity, patient safety reporting, and audit trails. Clinical Research services command the largest revenue share within the service type dimension, though Pharmacovigilance is expanding fastest as biologics portfolios thicken post-market surveillance obligations. The delivery model dimension shows Hybrid structures gaining preference as sponsors balance cost arbitrage from offshore locations against regulatory inspectorate expectations for domestic data handling.
FDA's risk-based monitoring guidance and EMA's Clinical Trial Regulation reshape vendor qualification requirements, forcing BPO providers to demonstrate integrated quality management systems across geographically dispersed operations. India's CDSCO and Germany's BfArM impose additional country-specific documentation standards that filter market entry for mid-tier competitors. Stakeholders must evaluate vendor resilience against evolving data localization mandates and inspectorate travel patterns before committing to long-term outsourcing partnerships.
Market Dynamics
Cloud-based data platforms and AI-driven patient recruitment tools are compressing clinical trial timelines, forcing BPO providers to restructure delivery models around real-time data flows and decentralized site networks.
Growth Catalysts
- EMA Clinical Trial Regulation:The harmonized submission portal and streamlined assessment procedures accelerate multi-country study activation across EU member states.
- Biologics portfolio expansion:Complex protein therapeutics and gene therapies require specialized manufacturing and post-market surveillance capabilities that sponsors externalize to qualified vendors.
- India's CDSCO fast-track pathways:Accelerated approval mechanisms for orphan drugs and breakthrough therapies attract sponsor investment in local contract research infrastructure.
Market Restraints
- Data localization mandates:Germany's BfArM and other European inspectorates increasingly require primary data storage within national borders, fragmenting cloud architectures.
- Specialized talent scarcity:Clinical data scientists and regulatory affairs specialists command premium compensation, inflating vendor operating costs.
- Legacy system integration:Sponsor ERP and clinical trial management systems resist API connectivity with vendor platforms, delaying study startup.
Strategic Opportunities
- Cell and gene therapy manufacturing:Viral vector production and cryogenic logistics represent white-space services where few vendors possess validated capabilities.
- Real-world evidence generation:FDA's guidance on RWE for regulatory decision-making creates demand for observational study design and claims database analytics.
- Decentralized trial infrastructure:Direct-to-patient drug shipment and home nursing networks enable geographic expansion into underserved recruitment pools.
Industry Challenges
- Cross-border data transfer compliance:GDPR adequacy decisions and EU-US Data Privacy Framework uncertainties complicate multi-continental study execution.
- Quality management system harmonization:Vendors must maintain simultaneous ISO 14155, ICH E6(R2), and country-specific GCP certifications across dispersed operational sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Sciences BPO Market |
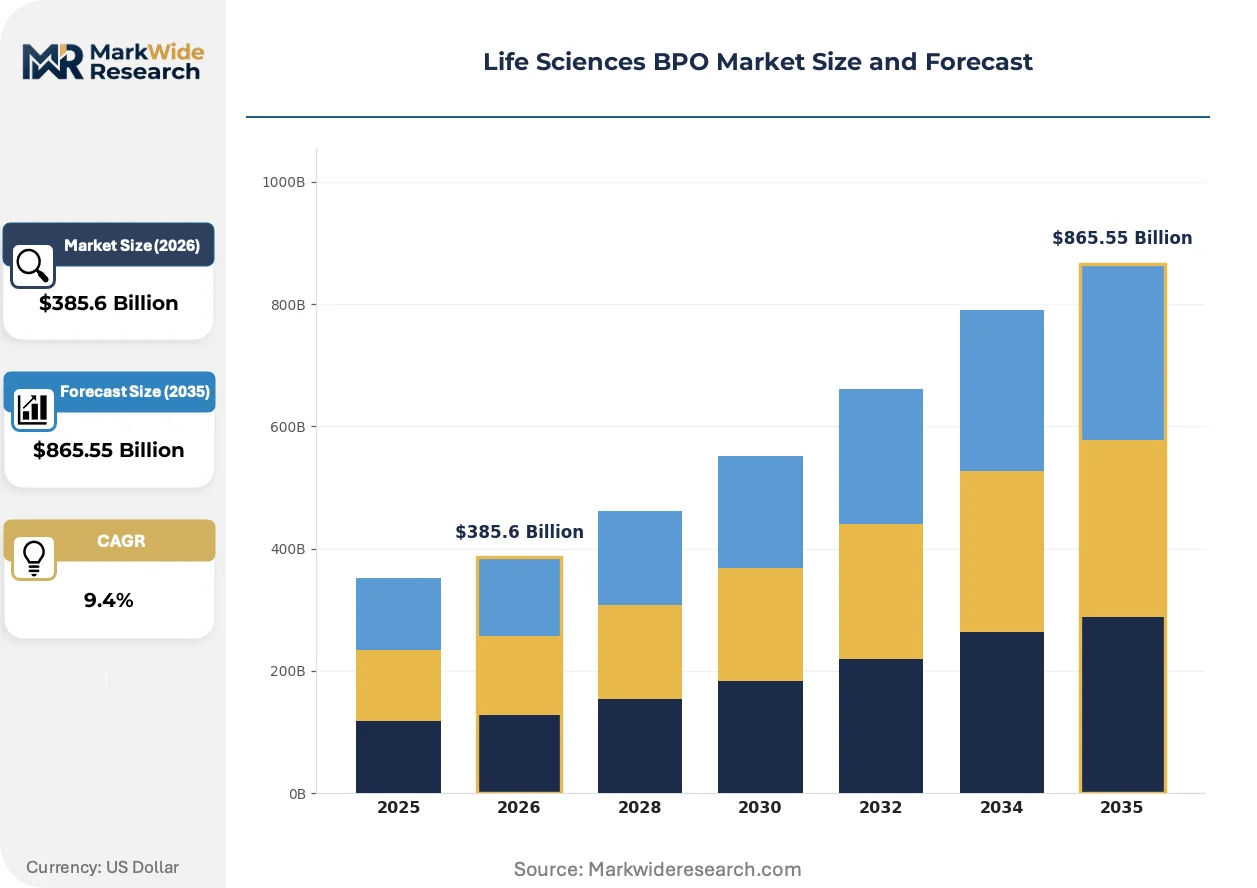
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $865.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Research, Pharmacovigilance, Regulatory Affairs, Data Management Application: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Delivery Model: Onshore, Offshore, Nearshore, Hybrid End User: Healthcare Providers, Research Laboratories, Academic Institutions, Government Agencies |
| Companies Covered | Thermo Fisher Scientific (PPD), Syneos Health, IQVIA, Cognizant Technology Solutions, Charles River Laboratories, Parexel International Corporation, ICON plc, Lonza Group, Labcorp Drug Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Sciences BPO Market Strategic Shifts & Innovations
Artificial intelligence and distributed computing architectures are reconfiguring how clinical data flows between sponsors, sites, and regulators. These technologies compress decision cycles while introducing new validation requirements.
Modular eClinical platforms are modularizing the technology stack that underpins trial execution. Mid-sized biopharmaceutical sponsors are adopting component-based systems at accelerating pace. This architecture is modularizing vendor relationships, enabling sponsors to swap specialized modules for data capture, randomization, or safety reporting without full platform replacement.
REACH and EU AI Act provisions are imposing algorithmic transparency requirements on clinical decision-support tools. Automated patient eligibility screening and adverse event detection systems now require documented training data provenance and performance validation. European sponsor organizations are establishing AI governance committees to pre-qualify vendor algorithms before regulatory submission.
Site-less trial models are displacing traditional investigative site networks in specific therapeutic areas. Oncology and rare disease studies increasingly combine telemedicine, wearable sensors, and local laboratory partnerships. This pattern concentrates in the United States where regulatory flexibility and patient mobility enable geographic dispersion that would face operational barriers in more centralized healthcare systems.
Life Sciences BPO Market Segmentation
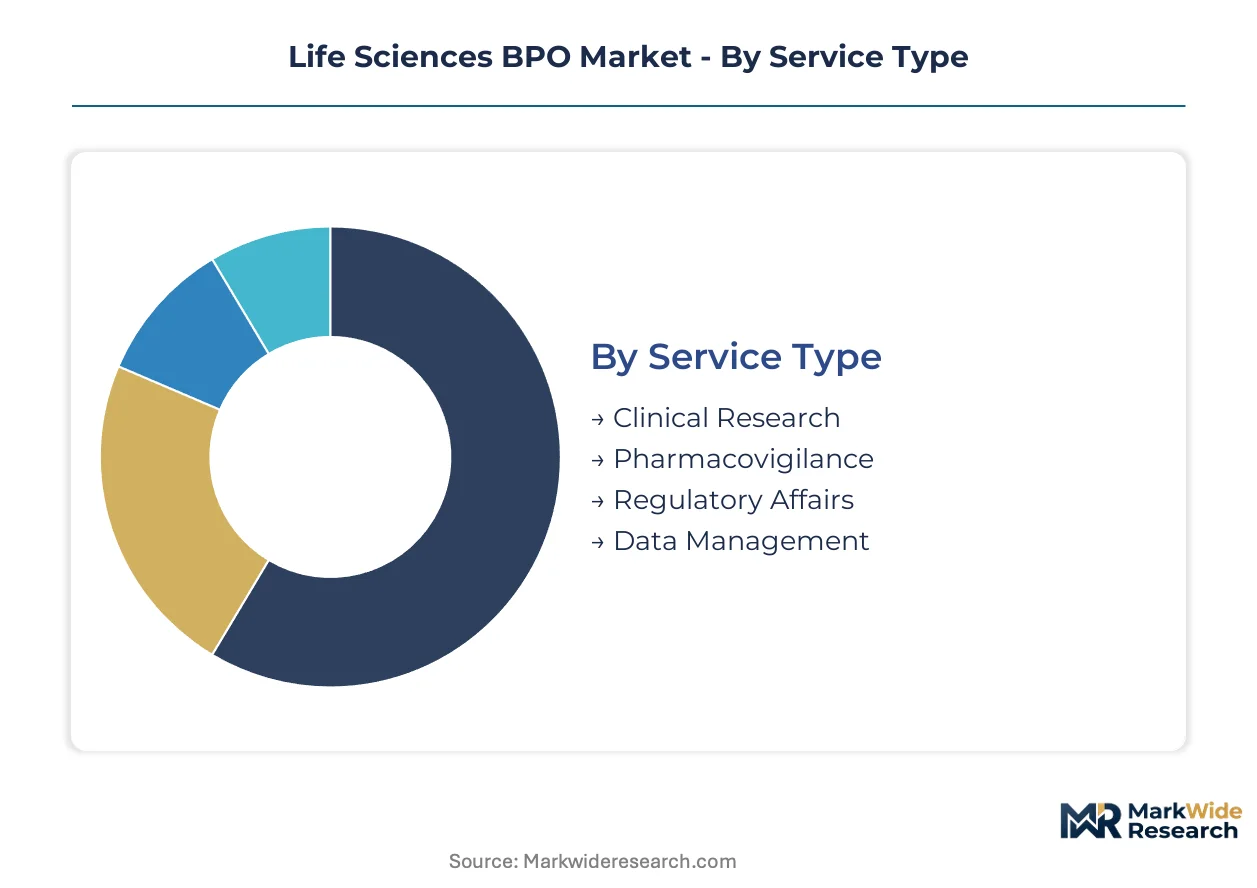
Life Sciences BPO segmentation reveals how capital deployment and regulatory risk tolerance shape vendor selection. Sponsors match service complexity to delivery geography based on inspectorate proximity and data sovereignty requirements.
Service Type:
Capital intensity varies sharply across service categories, with laboratory infrastructure and specialized talent pools demanding the heaviest upfront investment.
- Clinical Research:Encompasses protocol design, site management, and patient monitoring through Phase I-IV studies. Demand concentrates in the United States and Germany where FDA and EMA inspectorate presence ensures audit-ready documentation standards. Sponsors externalize to vendors with established investigator networks and integrated quality management systems.
- Pharmacovigilance:Post-market safety surveillance, signal detection, and regulatory reporting for adverse events. Biotechnology firms in India drive expansion as CDSCO strengthens post-approval monitoring mandates for biologics. Case processing volumes scale with therapeutic portfolio complexity.
- Regulatory Affairs:Submission preparation, agency correspondence, and compliance documentation across jurisdictions.
- Data Management:EDC build, database validation, and statistical programming for clinical datasets.
Most installed capacity flows through Clinical Research. Expansion is steepest in Pharmacovigilance.
Application:
Customer archetypes differ in outsourcing maturity, with research institutions favoring modular engagements and pharmaceutical companies pursuing integrated partnerships.
- Pharmaceutical Companies:Large and mid-cap sponsors externalizing entire trial portfolios or functional service provider arrangements. United States-based sponsors dominate contract value, driven by FDA's risk-based monitoring guidance and compressed development timelines for competitive therapeutic categories.
- Biotechnology Firms:Venture-backed and publicly traded developers lacking internal infrastructure for global trials. Germany's dense cluster of immuno-oncology startups sources specialized pharmacovigilance and regulatory writing capabilities from qualified vendors.
- Research Institutions:Academic medical centers and independent research institutes conducting investigator-initiated studies.
- Contract Research Organizations:BPO providers themselves subcontracting specialized functions to niche vendors.
Pharmaceutical Companies anchor current revenue. Biotechnology Firms are expanding most quickly.
Delivery Model:
Geographic configuration of service delivery determines labor arbitrage potential against regulatory inspection accessibility.
- Hybrid:Combines onshore regulatory-facing functions with offshore data processing and back-office operations. Sponsors in the United States and India favor this structure to balance FDA inspectorate expectations against cost efficiency in Bangalore and Hyderabad delivery centers.
- Offshore:Full-service delivery from lower-cost jurisdictions with established clinical research infrastructure. India's CDSCO-aligned vendors capture substantial share through English-language capability and therapeutic area specialization.
- Onshore:Domestic delivery maintaining direct inspectorate access for high-risk or complex trials.
- Nearshore:Regional delivery from adjacent time zones to enable real-time collaboration without transcontinental coordination.
Hybrid structures command the dominant share. Offshore delivery is gaining share fastest.
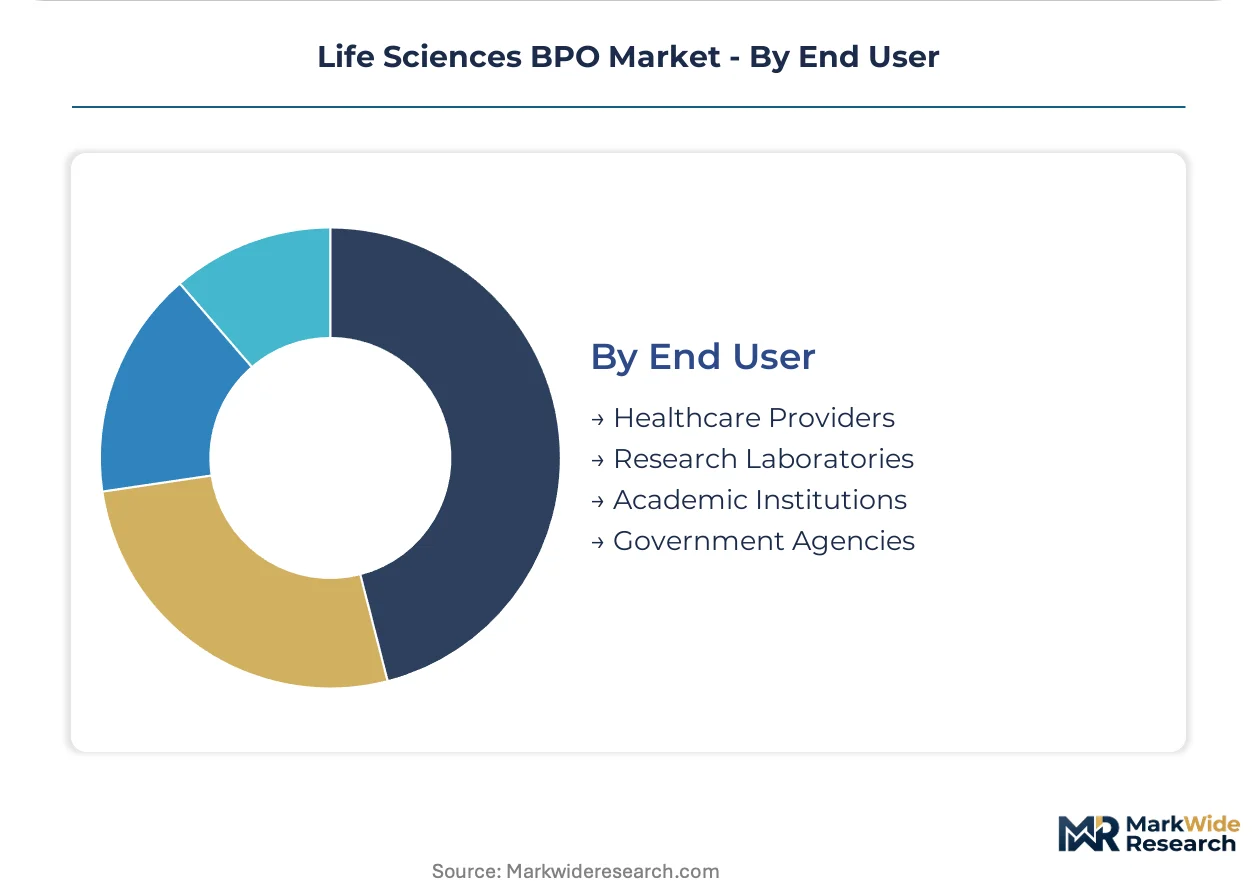
End User:
Institutional purchasing patterns reflect funding source stability and regulatory accountability requirements.
- Healthcare Providers:Hospital systems and integrated delivery networks participating as investigative sites or sponsors of pragmatic trials. United States academic medical centers leverage existing patient populations for recruitment-intensive studies in rare diseases.
- Research Laboratories:Dedicated clinical research facilities and central laboratories requiring specialized biospecimen handling and biomarker analysis capabilities.
- Academic Institutions:Universities and medical schools with federal funding obligations and publication-driven timelines.
- Government Agencies:National health institutes and regulatory bodies commissioning post-market surveillance or comparative effectiveness research.
Healthcare Providers represent the largest addressable base. Research Laboratories show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors global demand for clinical research outsourcing, with pharmaceutical sponsors and contract research organizations clustering around FDA headquarters and academic medical centers. Regional differentiation reflects regulatory proximity, talent density, and data infrastructure maturity across major pharmaceutical markets.
United States
Biopharmaceutical sponsors in Massachusetts and North Carolina drive demand for Phase I-IV trial execution and pharmacovigilance services. FDA's risk-based monitoring guidance and breakthrough therapy designation programs compress development timelines, forcing vendors to maintain domestic data centers and investigator networks. The Research Triangle Park and San Francisco Bay Area concentrate specialized clinical data science talent and early-stage biotechnology firms lacking internal infrastructure.
Germany
Berlin and Munich host dense clusters of immuno-oncology startups and mid-cap pharmaceutical companies externalizing regulatory affairs and safety surveillance functions. BfArM's data localization requirements and EMA's Clinical Trial Regulation harmonization create compliance complexity that favors established vendors with integrated quality management systems. The Heidelberg-Mannheim bioregion anchors academic-industry partnerships for real-world evidence generation.
India
Bangalore and Hyderabad delivery centers capture substantial clinical data management and pharmacovigilance case processing volume from US and European sponsors. CDSCO's fast-track approval pathways for orphan drugs and strengthened post-market surveillance mandates for biologics expand local contract research infrastructure. English-language capability and therapeutic area specialization in oncology and infectious diseases differentiate Indian vendors.
United Kingdom
London and Cambridge concentrate regulatory consulting and medical writing capabilities serving EMA-aligned submission strategies despite post-Brexit operational separation. MHRA's recognition of FDA inspections and streamlined clinical trial authorization procedures sustain vendor investment in UK-based regulatory affairs functions. The Oxford-AstraZeneca manufacturing partnership demonstrates integrated biologics development and commercialization capacity.
Switzerland
Basel and Zurich anchor specialized capabilities in cell and gene therapy manufacturing and viral vector production that few vendors possess globally. Swissmedic's alignment with ICH standards and proximity to European pharmaceutical headquarters attract quality-intensive outsourcing relationships. The country's concentrated biotechnology and diagnostics industrial base generates demand for niche preclinical and analytical services.
Life Sciences BPO Market Key Industry Players
Global majors compete with regional champions across service breadth and therapeutic specialization, producing a tiered structure where scale-driven players anchor high-volume clinical research against boutique vendors capturing premium cell therapy manufacturing. Three archetypes dominate: integrated platform providers spanning discovery through commercialization, functional service specialists delivering discrete pharmacovigilance or regulatory modules, and emerging cell therapy manufacturing pure-plays. Competitive intensity centers on M&A consolidation for geographic expansion and strategic partnerships for technology access rather than price-based rivalry.
Within the integrated platform tier, Thermo Fisher Scientific (PPD) and IQVIA exemplify scale-driven positioning through global laboratory networks and real-world evidence databases. Charles River Laboratories occupies a specialized position in preclinical safety assessment before human-phase outsourcing begins. These three companies anchor the competitive landscape through differentiated infrastructure investments that mid-tier competitors cannot replicate without substantial capital deployment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific (PPD) |
| Syneos Health |
| IQVIA |
| Cognizant Technology Solutions |
| Charles River Laboratories |
| Parexel International Corporation |
| ICON plc |
| Lonza Group |
| Labcorp Drug Development |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up clinical research specialists anchor supply concentration across the United States and India, translating portfolio scale into pricing discipline that resists commoditization in pharmacovigilance and regulatory affairs modules. Their acquisition-driven expansion creates captive delivery center networks that compress unit economics while sustaining premium positioning for FDA-facing functions.
Pricing Analysis
Input-cost pass-through from specialized clinical data scientists and regulatory affairs specialists flows into project-based and functional service provider arrangements, with premium tiers commanding price differentiation through ICH E6(R2) certification and integrated quality management systems. Three-tier pricing structure across premium, standard, and economy levels separates sponsors demanding domestic inspectorate proximity from those accepting offshore data processing. Pricing pressure stems from mid-tier competitors in Bangalore and Hyderabad capturing share through English-language capability and therapeutic area specialization in oncology. Biotechnology firms exhibit highest price sensitivity due to venture-backed funding constraints, while large pharmaceutical companies prioritize audit-readiness over unit cost.
Supply Chain Analysis
Specialized talent supply rests on educational pipelines in the United States, India, and Germany, with clinical data scientists and biomarker analysts forming the critical input layer alongside cloud infrastructure and modular eClinical software licenses. Vendor networks draw from investigator site partnerships, central laboratory facilities, and decentralized trial technology providers to assemble service delivery. Single-source vulnerability concentrates in viral vector production and cryogenic logistics for cell and gene therapy manufacturing, where few vendors possess validated capabilities. Distribution runs through direct enterprise sales to pharmaceutical sponsors and biotechnology firms, with hybrid delivery models combining onshore regulatory-facing functions and offshore data processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Life Sciences BPO market functions as a stable compounder anchored by biologics portfolio expansion and thickening post-market surveillance obligations that sustain recurring revenue streams across economic cycles.
For Market Incumbents: Lock in investigator network exclusivity through long-term site partnership agreements and deepen backward integration into proprietary real-world evidence databases to offset emerging competition from AI-native patient recruitment platforms. Prioritize certification investment in cell and gene therapy manufacturing capabilities before capacity scarcity inflates asset valuations. Channel control through integrated quality management systems spanning FDA, EMA, and CDSCO jurisdictions defends margin position against regional champions. For New Entrants and Emerging Players: The price-point gap between premium integrated platform providers and economy-tier offshore data processors creates white-space opportunity in pharmacovigilance case processing for mid-cap biotechnology firms and modular eClinical components for academic medical centers. Target India's CDSCO-aligned orphan drug fast-track pathway and Germany's immuno-oncology startup cluster as the most penetrable geographies. A direct-to-patient decentralized trial infrastructure play enables geographic expansion into underserved recruitment pools without replicating established site networks. For Investors and Strategic Acquirers: Valuations sit cheapest among functional service specialists with pharmacovigilance or regulatory writing capabilities that lack global laboratory networks or real-world evidence assets. The five-to-ten year viability window favors acquisition targets possessing validated cell therapy manufacturing infrastructure or AI-driven patient eligibility screening algorithms pre-qualified under EU AI Act provisions. Watch FDA risk-based monitoring guidance evolution and EMA Clinical Trial Regulation implementation pace as inflection indicators for vendor qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Investment | EMA Clinical Trial Regulation harmonization accelerates multi-country study activation across EU member states. |
| Manufacturing Scale-Up in Cell Therapy | Viral vector production and cryogenic logistics capabilities capture scarce premium positioning in biologics outsourcing. |
| Platform Integration of AI Tools | REACH and EU AI Act algorithmic transparency requirements demand documented training data provenance for clinical decision-support systems. |
| Strategic Partnership for Real-World Evidence | FDA guidance on RWE for regulatory decision-making creates demand for observational study design and claims database analytics. |
| Geographic Expansion via Decentralized Infrastructure | Direct-to-patient drug shipment and home nursing networks enable recruitment in rare disease populations beyond traditional site networks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up service-type and delivery model sizing triangulated against top-down pharmaceutical R&D spending and outsourcing penetration assumptions.
Segment-weighting approaches distributed value across clinical research, pharmacovigilance, regulatory affairs, and data management service types, with additional stratification by hybrid, offshore, onshore, and nearshore delivery models across the projection horizon. CAGRs derived from sponsor outsourcing budget growth, biologics pipeline expansion, and inspectorate travel pattern recovery assumptions. Treatment line and regional regulatory cluster dimensions refined forecast granularity.
Caveats apply where data localization mandates, GDPR adequacy decisions, or EU-US Data Privacy Framework uncertainties could materially shift the outlook for multi-continental study execution. Forecasts reflect assumptions regarding CDSCO fast-track pathway utilization and EMA Clinical Trial Regulation adoption velocity. A small set of named triggers—cross-border data transfer compliance evolution, specialized talent compensation inflation, and legacy system API connectivity breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market