
 DTC Pet Food Market | 2026-2036
DTC Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
DTC Pet Food Market Intelligence
The substitution of grain-based fillers with human-grade meats and novel proteins is restructuring product economics across the direct-to-consumer pet food landscape. This shift increases ingredient costs but supports premium pricing and stronger brand loyalty. The Farmers Dog Inc. leverages a subscription model built entirely around fresh, customized meals. Nom Nom Now differentiates with portion-controlled, vet-formulated recipes, while Sundays for Dogs Inc. offers an air-dried alternative to traditional kibble.
Direct-to-consumer pet food involves manufacturers selling products directly to households, bypassing traditional retail intermediaries like pet stores or supermarkets. This model relies on proprietary e-commerce platforms and sophisticated subscription management software to manage logistics and customer relationships. Within product types, raw food and grain-free formulations are challenging the market share of conventional dry food. Subscription services represent the fastest-growing distribution channel, creating predictable, recurring revenue streams for vendors.
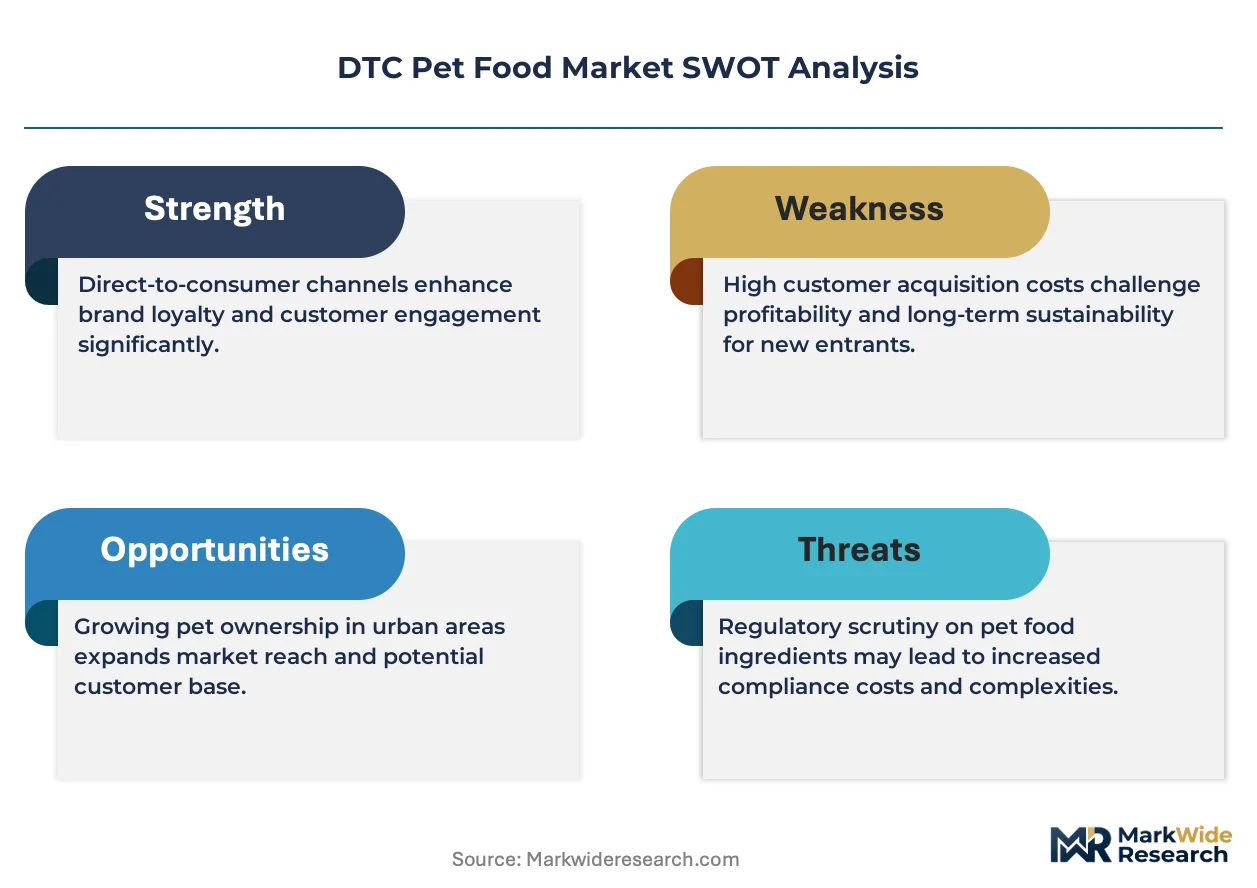
Regulatory frameworks from bodies like the FDA in the United States and standards overseen by the EFSA in Europe dictate pet food safety, labeling, and marketing claims. These agencies' guidelines on ingredient sourcing and nutritional adequacy directly shape product development and market access. Success for DTC brands now depends on mastering the complexities of temperature-controlled logistics while managing escalating digital customer acquisition costs.
Market Dynamics
The structural shift toward pet humanization is the central force shaping the direct-to-consumer pet food market. This trend manifests as owner demand for ingredient transparency and personalized nutrition plans, compelling brands to re-engineer supply chains around fresh, human-grade inputs and sophisticated cold-chain logistics.
Growth Catalysts
- Cold-Chain Logistics Expansion:Advances in refrigerated packaging and last-mile delivery networks enable the reliable distribution of temperature-sensitive fresh and raw pet foods, unlocking market access beyond dense urban centers.
- Pet Humanization Trend:A growing population of pet owners, particularly millennials, view pets as family members and are willing to invest in premium, health-focused products that mirror their own dietary values.
- Ingredient Transparency Standards:Guidelines from bodies like the FDA and AAFCO in the United States on labeling and nutritional claims build consumer trust, allowing premium brands to differentiate on ingredient quality.
Market Restraints
- Elevated Input Costs:The use of human-grade meats, novel proteins, and organic vegetables significantly increases raw material costs compared to traditional grain-based kibble, pressuring profit margins.
- Logistical Complexity:Managing a national temperature-controlled supply chain for perishable goods is capital-intensive and presents a significant barrier to entry, limiting scalability for smaller brands.
- Regulatory Scrutiny:Raw and fresh food formulations face heightened food safety scrutiny from regulators like the FDA, requiring costly pathogen testing and specialized processing like high-pressure pasteurization.
Strategic Opportunities
- Geographic Expansion in Europe:Markets like the United Kingdom and Germany, with high pet ownership and strong e-commerce penetration, represent significant growth opportunities for DTC subscription models.
- Specialized Diet Formulations:There is unmet demand for DTC options targeting specific health conditions, such as hypoallergenic, low-glycemic, or renal support diets, creating white space for specialized brands.
- Veterinary Channel Partnerships:Collaborating with veterinary clinics to offer vet-formulated, prescription-based meal plans can serve as a powerful customer acquisition channel and add a layer of medical credibility.
Industry Challenges
- Rising Customer Acquisition Costs:Escalating competition for online advertising space on major digital platforms is increasing the cost to acquire new subscribers, challenging the economic model of many DTC brands.
- Supply Chain Volatility:Sourcing a consistent supply of high-quality fresh ingredients is subject to price fluctuations and availability issues, creating operational challenges in production planning and cost management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DTC Pet Food Market |
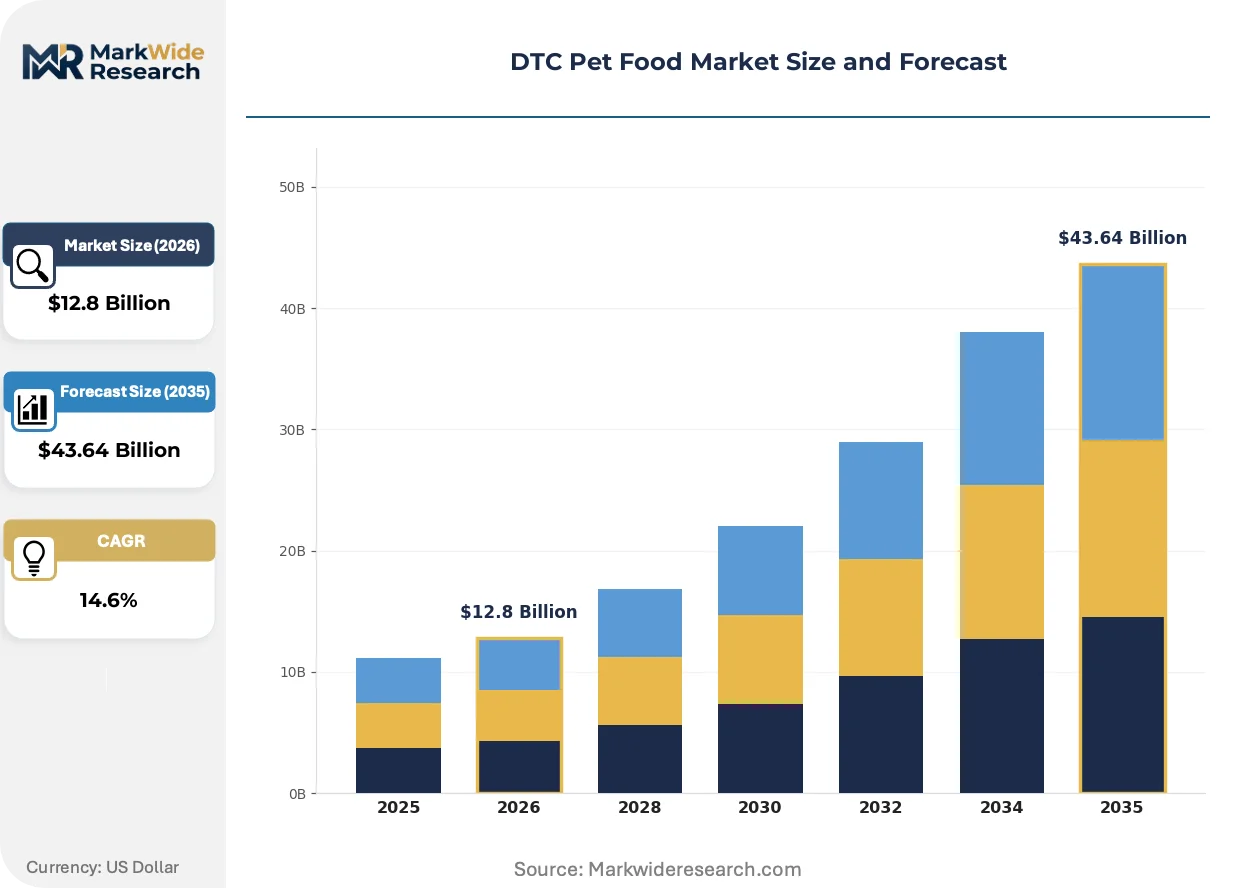
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Organic, Vegetarian Customer Type: Dog Owners, Cat Owners, Mixed Pet Owners, Rescue Organizations Distribution Channel: Online Store, Subscription Service, Direct Sales, Mobile App |
| Companies Covered | Primal Pet Group, Dog World, The Farmers Dog Inc., General Mills, Kitty Up, Nom Nom Now, Bramble, Inc., Diamond Pet Foods Inc., Sundays for Dogs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DTC Pet Food Market Strategic Shifts & Innovations
The convergence of food science, data analytics, and e-commerce is redefining product formulation and delivery in the pet food sector. Personalization at scale, enabled by digital platforms, allows for customized meal plans that cater to individual pet health needs, moving the market beyond one-size-fits-all products.
Subscription management software automates recurring billing, order customization, and logistics coordination for DTC pet food brands. Dog and cat owners are rapidly adopting these platforms for the convenience of scheduled, customized deliveries that eliminate trips to the store. This technology is decentralizing the pet food supply chain, allowing new brands to bypass traditional retail gatekeepers and build direct, data-rich customer relationships.
Regulatory bodies are increasing their focus on the safety and labeling of non-traditional pet foods. In the United States, the FDA's Food Safety Modernization Act (FSMA) imposes stricter preventative controls on manufacturers, including those producing raw and fresh formats. The raw food segment is most affected, prompting investment in technologies like high-pressure processing (HPP) to ensure microbial safety without using heat.
A significant behavioral shift is occurring as consumers prioritize convenience and consistency, moving from ad-hoc retail purchases to automated subscription services. This recurring revenue model is disrupting traditional pet store and supermarket channels by fostering direct brand loyalty and providing predictable demand forecasts. This trend is most visible among urban pet owners in North America and Western Europe who value time savings and product personalization.
DTC Pet Food Market Segmentation
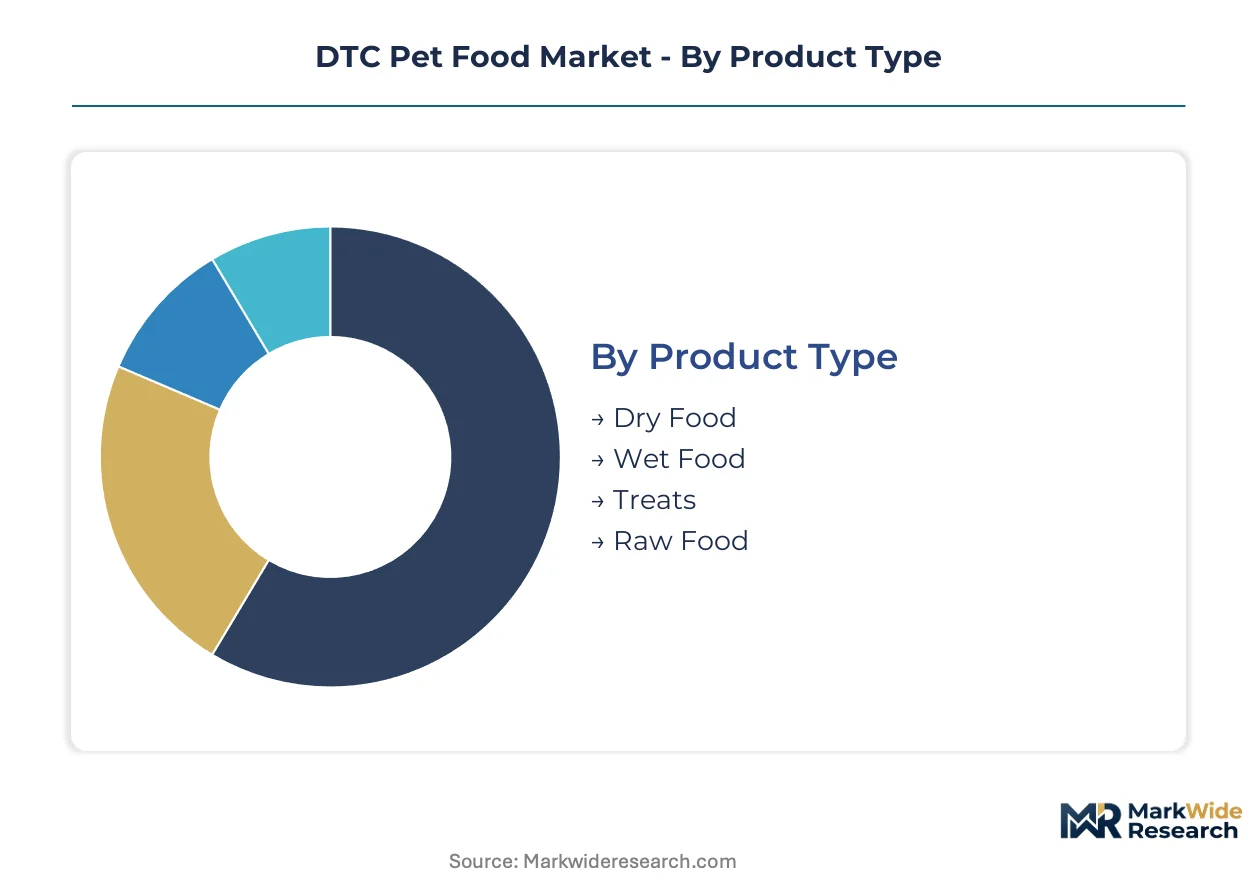
Market segmentation in DTC pet food illuminates distinct consumer needs and product preferences. This analysis identifies key categories shaping product development and distribution strategies. Understanding these segments allows brands to tailor offerings and marketing efforts effectively across diverse pet owner demographics.
Product Type:
The upgrade cycle for pet food products often begins with owners seeking healthier alternatives to traditional options.
- Raw Food:These products consist of uncooked meat, organs, and bones, often supplemented with fruits and vegetables. Demand concentrates among health-conscious pet owners in the United States seeking biologically appropriate diets for their animals.
- Wet Food:Characterized by high moisture content and often presented in cans or pouches, wet food offers enhanced palatability and hydration. Pet owners in Europe often prefer wet formulations for smaller breeds and cats due to perceived quality and moisture benefits.
- Dry Food:This segment includes traditional kibble, offering convenience and a longer shelf life. Dry food remains a foundational product for many pet owners due to its ease of storage and cost-effectiveness.
- Treats:These are supplementary food items used for training, rewards, or occasional indulgence. Treats cater to owner desires for positive reinforcement and pet enjoyment.
Dry Food sits at the top of the volume ranking, with Raw Food climbing the fastest.
Ingredient Type:
Pet owners increasingly base purchasing decisions on specific ingredient types, reflecting their own dietary values and pet health concerns.
- Grain-Free:These formulations exclude common grains like corn, wheat, and soy, often replacing them with alternative carbohydrates or proteins. Pet owners in the United States frequently choose grain-free options due to perceived allergen sensitivities in their animals.
- Organic:Certified organic ingredients, free from pesticides, hormones, and artificial additives, define this premium segment. Demand for organic pet food is significant among holistic pet care advocates, particularly in countries like Germany.
- Meat-Based:Products primarily composed of animal proteins like chicken, beef, or fish form the traditional core of pet nutrition. These formulations appeal to the natural carnivorous diets of dogs and cats, ensuring palatability and essential nutrient intake.
- Vegetarian:These diets utilize plant-based proteins to meet nutritional requirements, appealing to owners with ethical or specific dietary preferences. Vegetarian options cater to a niche but growing segment of the market.
The diversity of ingredient types reflects a fragmented market driven by specialized pet health needs and owner philosophies.
Customer Type:
Targeting specific customer types allows DTC brands to develop tailored product lines and marketing messages that resonate with distinct pet owner demographics.
- Dog Owners:This segment represents the largest customer base, characterized by diverse needs ranging from puppy growth to senior support. Dog owners in the United States increasingly seek personalized nutrition plans for their companions.
- Cat Owners:Cat owners prioritize specific dietary needs, including high protein content and palatability, crucial for obligate carnivores. Wet food preferences are particularly strong among cat owners in the United Kingdom.
- Mixed Pet Owners:These customers own both dogs and cats, often seeking convenient, multi-species solutions from a single brand. Mixed pet owners value ease of ordering and consistent brand experience.
- Rescue Organizations:These entities purchase pet food in bulk, often requiring cost-effective, nutritionally complete options for a variety of animals. Rescue organizations represent a significant institutional buyer segment.
Dog Owners command the largest market share, while Cat Owners represent a segment with distinct and growing product preferences.
Distribution Channel:
The evolution of distribution channels defines the direct-to-consumer model, emphasizing convenience and direct customer engagement.
- Subscription Service:This model provides recurring, automated deliveries of pet food, often with customizable meal plans. Subscription services are favored by convenience-seeking pet owners across North America, ensuring consistent supply.
- Online Store:Proprietary e-commerce platforms allow customers to make one-time or recurring purchases directly from the brand. Online stores serve as primary touchpoints for initial product trials and access to broader product ranges.
- Direct Sales:This channel involves direct interaction between brand representatives and customers, often through events or personalized consultations. Direct sales are common for niche or highly specialized products requiring detailed explanation.
- Mobile App:Dedicated applications facilitate ordering, subscription management, and loyalty program engagement directly from a smartphone. Mobile apps enhance convenience and integrate brand services into daily customer routines.
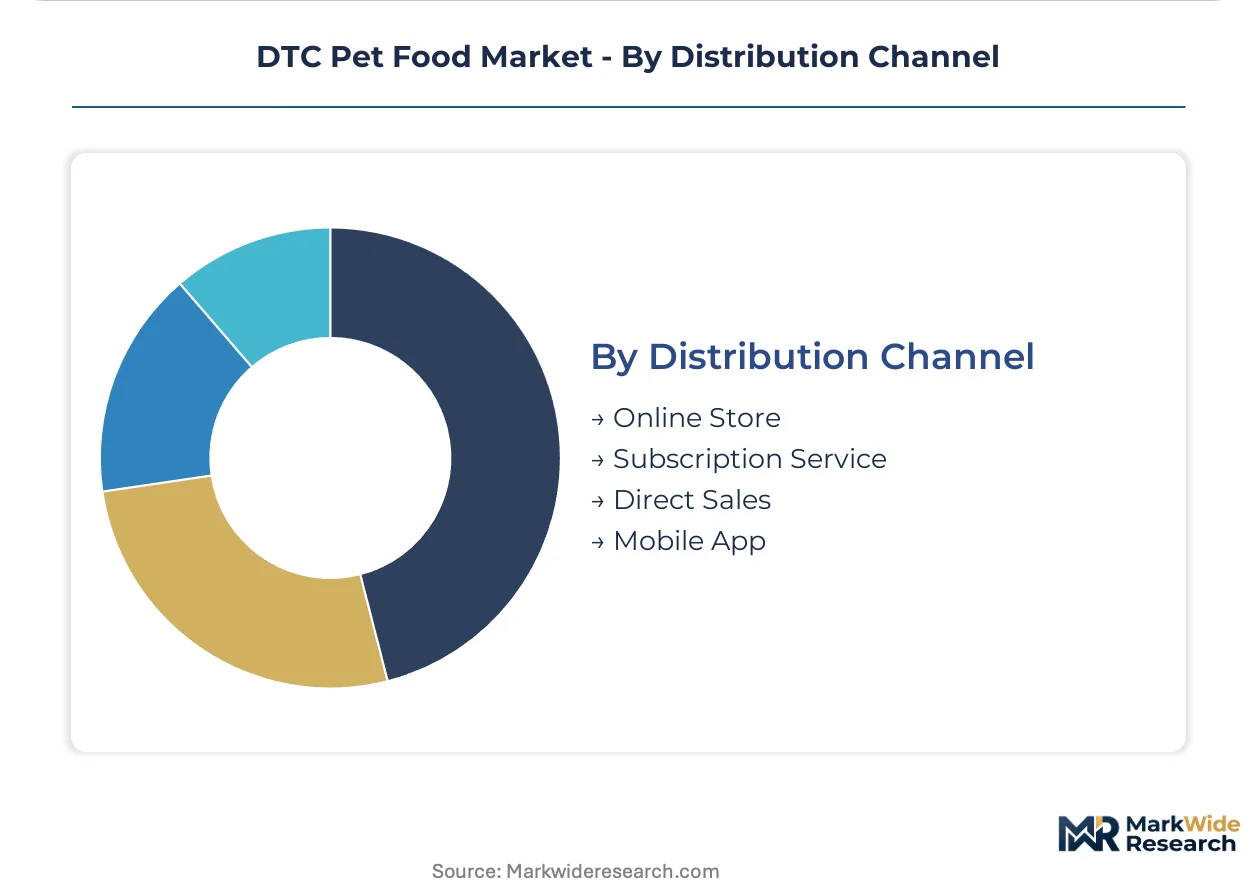
Subscription Service represents the fastest-growing distribution channel, transforming how pet owners acquire their products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cities like New York and Los Angeles anchor significant demand for direct-to-consumer pet food, driven by affluent pet owners prioritizing health and convenience. This market expansion is supported by advanced cold-chain logistics and a strong e-commerce infrastructure. Regulatory bodies like the FDA and AAFCO provide frameworks for ingredient transparency and nutritional adequacy, fostering consumer trust in premium offerings.
United States
Pet humanization and a preference for personalized nutrition plans drive demand among dog owners in the United States. The Food Safety Modernization Act (FSMA) imposes stricter preventative controls on pet food manufacturers, particularly for raw and fresh formats. Urban centers such as San Francisco and Seattle show high concentrations of subscription-based DTC pet food consumption.
United Kingdom
High pet ownership and strong e-commerce penetration characterize the United Kingdom market, where wet food preferences are strong among cat owners. The Veterinary Medicines Directorate (VMD) regulates pet food safety and labeling, ensuring compliance with nutritional standards. London and Manchester are key hubs for online pet food subscriptions and specialized diet formulations.
Germany
Demand for organic and premium pet food is significant in Germany, supported by holistic pet care advocates. The European Food Safety Authority (EFSA) sets stringent guidelines for ingredient sourcing and nutritional claims across the European Union. Munich and Berlin demonstrate robust adoption of subscription models for fresh and organic pet food products.
Japan
An aging pet population and a cultural emphasis on pet well-being fuel demand for high-quality, health-focused pet food in Japan. The Ministry of Agriculture, Forestry and Fisheries (MAFF) regulates pet food safety and labeling standards. Tokyo and Osaka exhibit strong consumer interest in specialized diets and convenient online delivery services.
Australia
Pet owners in Australia increasingly seek grain-free and raw food options for their animals, mirroring human dietary trends. The Australian Pesticides and Veterinary Medicines Authority (APVMA) oversees pet food ingredient safety and product claims. Sydney and Melbourne are key markets for DTC pet food brands leveraging subscription-based delivery models.
DTC Pet Food Market Key Industry Players
Global majors compete with regional champions across product innovation and supply chain efficiency within the direct-to-consumer pet food market. The market structure exhibits a blend of established industry giants and agile specialized startups. Strategic archetypes include large diversified food companies, niche fresh food providers, and technology-driven subscription platforms. Dominant competitive moves involve portfolio diversification and aggressive digital customer acquisition.
Niche fresh food providers like The Farmers Dog Inc. and Nom Nom Now exemplify the specialized DTC segment, focusing on customized, human-grade meal plans delivered directly to consumers. General Mills, a global major, also participates in the pet food market, leveraging its extensive distribution networks and brand recognition. These companies anchor different ends of the market, from highly personalized subscription services to broader consumer packaged goods offerings, reflecting diverse approaches to pet nutrition.
| Leading Market Players |
|---|
| Primal Pet Group |
| Dog World |
| The Farmers Dog Inc. |
| General Mills |
| Kitty Up |
| Nom Nom Now |
| Bramble, Inc. |
| Diamond Pet Foods Inc. |
| Sundays for Dogs Inc. |
| Others |
Cost & Logistics Intelligence
The USDA's meat price index directly influences DTC pet food production costs, cascading through supply chains into premium pricing tiers for human-grade formulations. This cost structure differentiates specialized brands from traditional kibble producers.
Pricing Analysis
Elevated input costs for human-grade meats and novel proteins pass directly to consumers through subscription models. Price differentiation stems from customization levels and brand premium, reflecting ingredient quality and vet-formulated recipes. Pricing pressure stems from rising raw material expenses, pushing average selling prices upward. Rescue organizations exhibit the highest price sensitivity, while dog owners seeking personalized nutrition show lower price elasticity.
Supply Chain Analysis
Managing failed deliveries and quality control issues constitutes the primary reverse logistics challenge for perishable DTC pet food. Ingredient supply concentrates in the United States and Europe, drawing from human-grade meats, novel proteins, and organic vegetables. Commodity price volatility represents a structural risk, impacting cost predictability for manufacturers. Distribution runs through direct-to-consumer subscription services, emphasizing cold-chain reliability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DTC pet food market operates as a stable compounder, driven by the sustained pet humanization trend. Recurring revenue models further underpin predictable, continuous growth for vendors.
For Market Incumbents: Deploy portfolio diversification to integrate specialized fresh food options, countering agile DTC startups. Incumbents should invest in cold-chain logistics technology, enhancing reach beyond dense urban centers. Certification investment for human-grade ingredients builds consumer trust against emerging competitors. Broadening distribution channels through strategic partnerships with veterinary clinics also strengthens market presence.
For New Entrants and Emerging Players: Launch specialized diet formulations via subscription models, targeting specific health conditions like allergies or renal support. The United Kingdom and Germany represent penetrable geographic white spaces for these offerings. Partnerships with veterinary channels provide a credible go-to-market angle, leveraging medical endorsement. Focus on data analytics to personalize meal plans and optimize customer acquisition costs.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche fresh food providers demonstrating scalable cold-chain logistics and strong subscriber retention. These acquisition targets possess robust proprietary e-commerce platforms and unique ingredient sourcing. Long-term viability hinges on sustained consumer willingness to pay premiums for pet health. Practitioners should monitor digital customer acquisition costs for early signals of market saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cold-Chain Logistics Network | Enables reliable distribution of perishable fresh foods to broader US and European markets. |
| Develop Specialized Diet Formulations | Addresses unmet demand for hypoallergenic or renal support diets, serving distinct pet owner needs. |
| Form Veterinary Channel Partnerships | Leverages medical credibility for customer acquisition and introduces vet-formulated meal plans. |
| Invest in High-Pressure Processing (HPP) | Ensures microbial safety for raw food products, meeting FDA and EFSA regulatory scrutiny. |
| Optimize Digital Customer Acquisition | Reduces escalating marketing expenses, improving economic models for DTC subscription brands. |
Research Approach
Direct dialogue with pet food manufacturers, DTC platform providers, veterinarians, and pet owners grounded the primary research. This included in-depth interviews with industry executives and supply chain managers. Secondary validation drew from FDA guidelines, EFSA standards, AAFCO publications, and e-commerce platform data. Bottom-up and top-down triangulation ensured robust market size and forecast accuracy.
The quantitative model produced detailed market volume and value projections across the analysis window. Segmentation dimensions modeled included product type, ingredient type, customer type, and distribution channel. Compound annual growth rates were derived from historical data analysis and future trend extrapolation. Pet ownership demographics and cold-chain logistics capacity served as key industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts. Forecasts reflect assumptions documented through extensive research. Practitioners should monitor digital customer acquisition costs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Pen Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
South America Dog Food Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Dog Float Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market