
 Global Aerospace Helmet Mounted Display Market | 2026-2036
Global Aerospace Helmet Mounted Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Helmet Mounted Display Market Foresight
The capability gap between vertically integrated primes and component-dependent suppliers is rotating competitive advantage toward firms with captive optical manufacturing. Collins Aerospace leverages in-house waveguide fabrication to control delivery timelines for fixed-wing programs. Elbit Systems sustains technology leadership through specialized helmet-integrated night vision architectures. Thales Group anchors European supply chains with sovereign production lines in France.
Aerospace helmet mounted displays fuse optical projection engines with precision head-tracking sensors to present flight, targeting, and sensor data within a pilot's natural field of view, typically operating at luminance levels exceeding 2000 foot-lamberts for daylight readability. These systems serve primarily to reduce cockpit scan workload and shorten decision loops in high-G combat maneuvers. Fully integrated helmet systems dominate military procurement by embedding oxygen masks, communications, and countermeasure controls into a single airframe-connected platform. Waveguide technology represents the fastest-expanding segment as manufacturers replace refractive optics with thinner, lighter combiner elements that reduce neck strain during extended missions.
The FAA certifies civil variants under Part 25 avionics standards while the EMA's MDR framework governs European military medical-device-adjacent eye safety requirements, and Israel's MOD testing protocols set ballistic impact benchmarks that shape global durability specifications. Compliance with these overlapping regimes extends development cycles but creates barriers that favor established primes with dedicated certification teams. Stakeholders must monitor how the EU AI Act's emerging transparency requirements for autonomous decision aids could reshape software architectures in next-generation helmet systems.
Market Dynamics
Waveguide fabrication is consolidating competitive advantage among suppliers with captive optical manufacturing, compressing delivery timelines and reshaping procurement patterns across fixed-wing and rotary programs.
Growth Catalysts
- FAA Part 25 Certification Momentum:Updated avionics standards for head-worn displays are accelerating product validation cycles and expanding addressable market for civil aviation variants.
- Next-Generation Fighter Procurement:Military aviation programs in the United States are expanding helmet-mounted display procurement for advanced tactical aircraft platforms.
- Israeli MOD Ballistic Testing:Israel's Ministry of Defense testing protocols set global durability benchmarks that shape international product specifications and create export-ready certification pathways.
Market Restraints
- Waveguide Input Concentration:Precision optical substrate supply concentrates among Japanese and German specialty glass manufacturers, creating vulnerability to geographic disruption.
- EMA MDR Compliance Friction:European medical-device-adjacent eye safety requirements extend development cycles and favor established primes with dedicated certification teams.
- Refractive Optics Obsolescence Risk:Traditional helmet display architectures face substitution pressure as waveguide technology achieves cost parity at scale.
Strategic Opportunities
- Indian Defense Modernization:India's PLI scheme for aerospace components creates localized assembly incentives for helmet system integrators seeking offset-compliant production.
- EU AI Act Transparency Mandates:Emerging requirements for autonomous decision aids in next-generation helmet systems create first-mover advantage for software architecture redesign.
- Unmanned Wingman Integration:Convergence of helmet-mounted displays with loyal wingman drone control interfaces opens new application vertical beyond manned cockpits.
Industry Challenges
- Precision Optics Talent Scarcity:Waveguide design and nanofabrication expertise concentrates among a narrow cohort of specialists, constraining workforce scaling.
- Multi-Regime Certification Overlap:Simultaneous compliance with FAA civil standards, EMA medical requirements, and Israeli ballistic protocols fragments testing resources.
- Legacy Platform Retrofit Complexity:Integration with existing avionics buses and power architectures in fielded aircraft fleets demands costly customization engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Helmet Mounted Display Market |
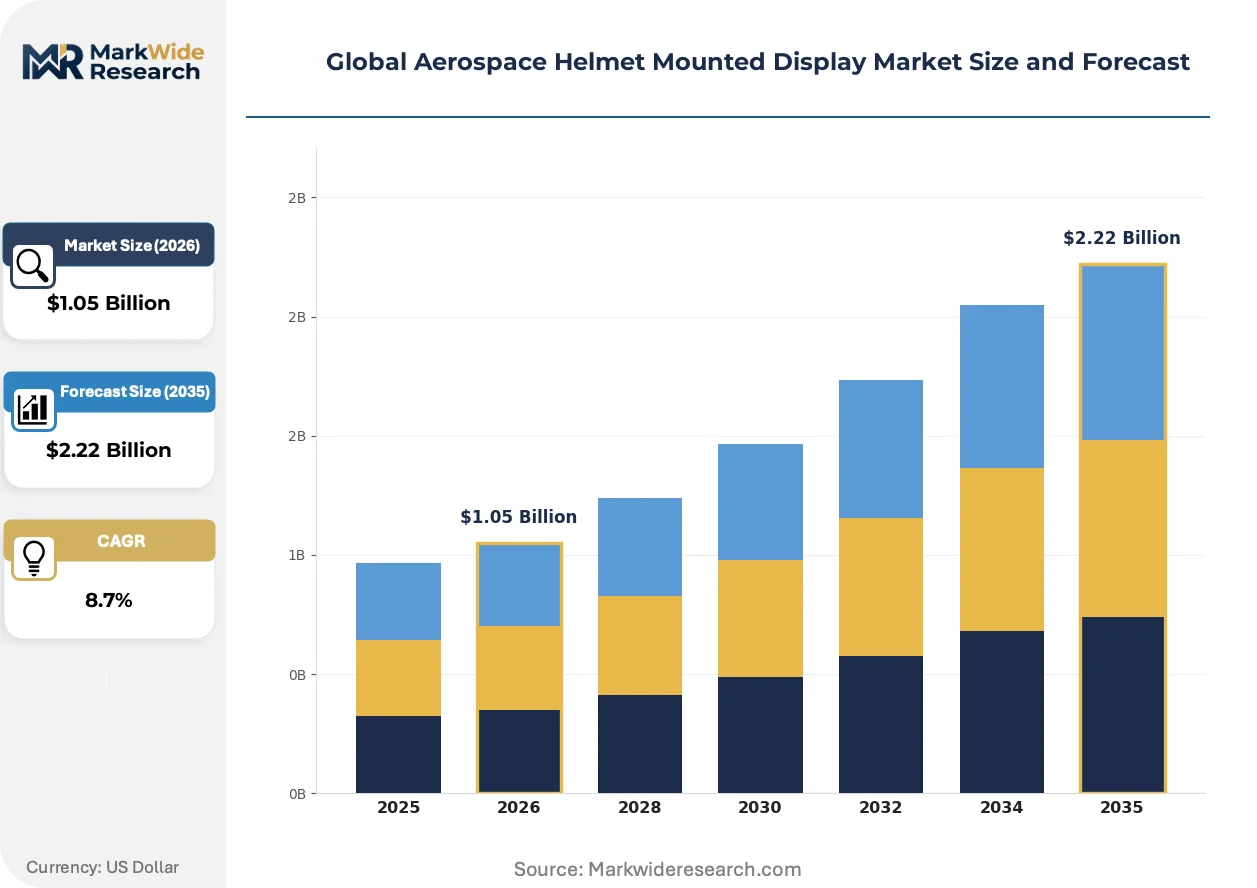
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Helmet Mounted Display, Fully Integrated, Hybrid, Standalone Technology: LCD, OLED, Waveguide, Microdisplay, Virtual Reticle Application: Military Aviation, Space Missions, Unmanned Aerial Vehicles Control, Flight Training End User: Fighter Pilots, Astronauts, UAV Operators, Flight Instructors |
| Companies Covered | Collins Aerospace, Honeywell Aerospace, BAE Systems, Leonardo, Saab, Elbit Systems, L3Harris Technologies, General Dynamics, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Helmet Mounted Display Market Shifts & Advancements
Optical engine miniaturization and sovereign production mandates are converging to reshape competitive positioning across military and civil aviation procurement channels.
Diffractive waveguide combiners are fragmenting traditional refractive optical supply chains by enabling thinner, lighter projection engines that reduce pilot neck strain during extended missions. Fighter program offices in the United States and France are specifying waveguide-based architectures for next-generation helmet contracts. The technology is fragmenting established supplier relationships as primes with in-house waveguide fabrication capture margin previously allocated to external optical houses.
The EU AI Act's emerging transparency requirements for autonomous decision aids are forcing software architecture redesigns in helmet-integrated targeting systems. Manufacturers must now embed explainability layers into symbology generation algorithms that previously operated as black-box neural networks. European military procurement offices are inserting AI Act compliance clauses into helmet system RFPs ahead of formal mandate deadlines.
Defense ministries are consolidating helmet system procurement under platform-centric contracting rather than discrete avionics line items, compressing vendor negotiation cycles and favoring integrated system suppliers. The United States Air Force's Next Generation Air Dominance program exemplifies this bundling approach. France's DGA has adopted similar consolidated sourcing for Rafale F4 standard upgrades.
Global Aerospace Helmet Mounted Display Market Segmentation
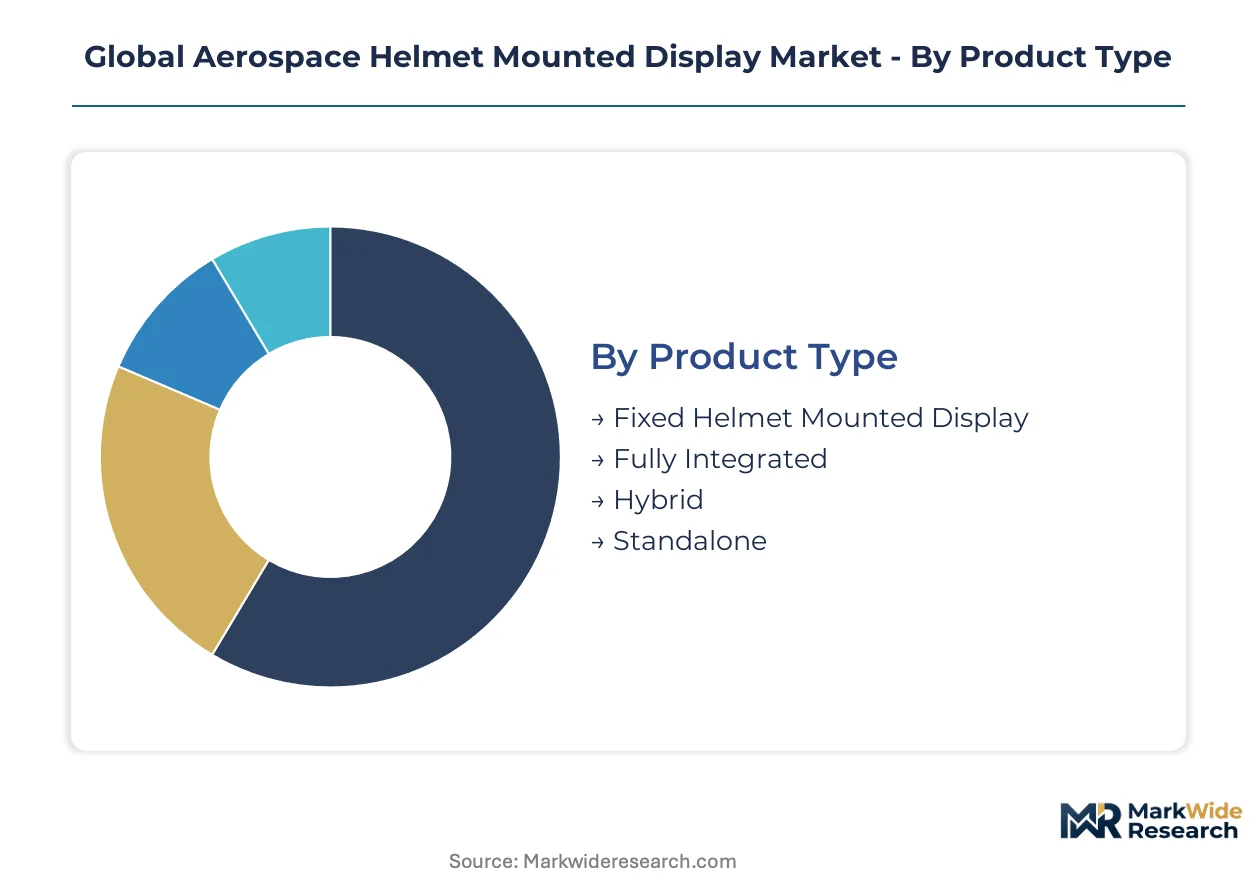
Segmentation in aerospace helmet mounted displays reveals how procurement patterns concentrate around platform integration depth and optical technology maturity. Understanding these divides exposes where certification burdens and manufacturing scale create sustainable margin pools for suppliers.
Product Type:
Premium margins concentrate in architectures that embed multiple aircraft systems into unified platforms, while commoditization pressures squeeze standalone display units lacking airframe integration.
- Fully Integrated:These systems fuse oxygen delivery, communications, countermeasure controls, and display projection into a single helmet platform connected directly to aircraft avionics buses. Fighter programs in the United States and France specify this architecture exclusively for next-generation tactical aircraft, with procurement bundling under platform-centric contracts compressing vendor negotiations.
- Fixed Helmet Mounted Display:Permanently mounted display units with rigid optical paths serve legacy rotary-wing platforms where helmet interchangeability is less critical. Demand clusters in military helicopter modernization budgets across Israel and France, constrained by retrofit complexity with existing avionics architectures.
- Hybrid:Modular designs allowing partial system upgrades without full platform replacement address budget-constrained operators seeking incremental capability insertion.
- Standalone:Discrete display units without integrated aircraft interfaces target flight training and civil aviation applications where FAA Part 25 certification drives specification requirements.
The dominant share belongs to Fully Integrated systems, while Hybrid configurations are closing the gap fastest as operators balance capability against modernization budget constraints.
Technology:
Volume leadership currently rests with mature flat-panel technologies, though fabrication scale and supply concentration are shifting competitive advantage toward specialized optical architectures.
- Waveguide:Diffractive combiner elements replace bulky refractive optics with sub-millimeter glass substrates that project symbology across expanded eyeboxes. Fighter program offices in the United States and France now mandate waveguide architectures for new helmet contracts, with in-house fabrication capability determining supplier selection.
- LCD:Liquid crystal microdisplays with LED backlighting deliver proven reliability for civil aviation and training applications where cost sensitivity outweighs performance optimization.
- OLED:Organic light-emitting diode microdisplays offer superior contrast ratios and faster refresh rates for night vision integration, though limited supplier concentration constrains procurement scale.
- Microdisplay:Silicon-backed reflective and transmissive panels serve as image sources for optical relay systems in mid-tier military platforms.
- Virtual Reticle:Laser-based reticle projection systems persist in specialized targeting applications requiring extreme brightness for daylight acquisition.
Waveguide technology commands the steepest expansion trajectory as weight reduction specifications harden across NATO procurement channels, while LCD retains volume leadership in civil-certified variants.
Application:
Customer concentration and procurement authority fragmentation create divergent margin structures across mission environments, with manned combat aviation offering the deepest contract values.
- Military Aviation:Tactical aircraft programs drive specification standards through integrated platform procurement, with helmet systems evaluated as mission-critical avionics rather than discrete accessories.
- Unmanned Aerial Vehicles Control:Ground-based operator stations are adopting helmet-mounted displays for immersive sensor payload management, opening vertical expansion beyond traditional cockpit applications.
- Flight Training:Civil and military training organizations specify lower-cost variants with reduced environmental hardening, prioritizing FAA certification pathway clarity over combat durability.
- Space Missions:Extravehicular activity helmets incorporate specialized displays for suit telemetry and robotic arm control, with NASA and ESA procurement volumes constrained by mission frequency.
Military Aviation maintains the dominant procurement value, while UAV Control applications are expanding most quickly as loyal wingman programs proliferate.
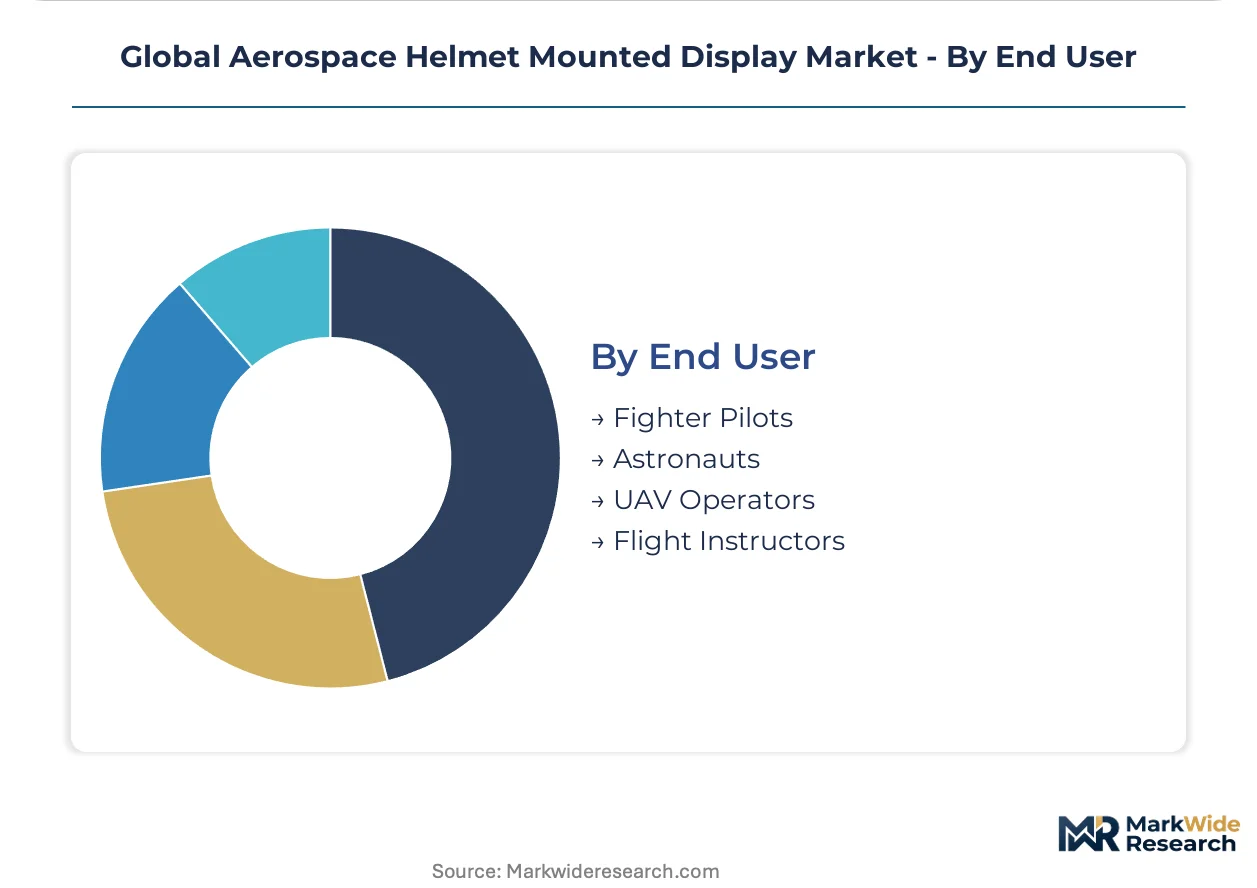
End User:
User physiology and mission duration requirements segment demand across G-force tolerance, helmet mass sensitivity, and information density needs.
- Fighter Pilots:High-G maneuvering demands drive neck strain minimization as a primary specification, with waveguide weight reduction directly addressing mission endurance limitations.
- UAV Operators:Ground-based control environments eliminate aerodynamic loading constraints, permitting heavier optical systems with expanded field-of-view for multi-vehicle supervision.
- Flight Instructors:Training scenarios require rapid reconfiguration between student and instructor display modes, favoring modular architectures with simplified maintenance protocols.
- Astronauts:Pressurized suit integration and microgravity operation impose unique center-of-mass and visibility requirements distinct from atmospheric flight profiles.
Fighter Pilots represent the largest addressable user base, while UAV Operators are gaining share fastest as autonomous wingman deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement channels. Israeli and French defense buyers prioritize performance over unit cost, while Indian and Japanese operators face tighter budget constraints that favor modular upgrade paths.
United States
The Air Force's Next Generation Air Dominance program drives integrated helmet procurement under platform-centric contracts. FAA Part 25 certification pathways for civil variants are accelerating validation timelines. Collins Aerospace maintains captive waveguide fabrication in Iowa, compressing delivery schedules for fixed-wing programs.
France
DGA consolidated sourcing for Rafale F4 standard upgrades bundles helmet systems with airframe procurement. EMA MDR compliance for eye safety requirements extends development cycles but favors established primes with dedicated certification teams. Thales Group anchors sovereign production lines in the Provence-Alpes-Côte d'Azur region.
Israel
Ministry of Defense ballistic testing protocols set global durability benchmarks that shape international export specifications. Elbit Systems sustains technology leadership through specialized helmet-integrated night vision architectures. Tel Aviv-area defense clusters concentrate precision optics talent for waveguide nanofabrication.
India
PLI scheme incentives for aerospace components create localized assembly opportunities for offset-compliant production. DGFT import substitution policies are redirecting procurement toward domestic integrators. Bengaluru and Hyderabad emerging as maintenance and limited manufacturing hubs for helmet system components.
Japan
METI defense industrial base programs are expanding domestic helmet display capabilities for F-X fighter integration. JIS standards for avionics interoperability constrain foreign supplier participation. Nagoya-area aerospace clusters developing precision optical substrate partnerships with German and Japanese specialty glass manufacturers.
Global Aerospace Helmet Mounted Display Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. The market structure concentrates around vertically integrated primes with captive optical manufacturing and specialized component suppliers dependent on external substrate sources. Three archetypes dominate: waveguide-integrated system houses, refractive optics legacy providers, and software-defined symbology specialists. Competitive moves center on backward integration into precision glass fabrication and strategic partnerships for AI-enabled targeting algorithms.
Among US-based defense primes, Collins Aerospace and L3Harris Technologies exemplify the integrated system house archetype with in-house optical manufacturing capabilities. Elbit Systems represents the specialized technology leader position, anchoring Israeli supply chains with sovereign production expertise. Thales Group occupies the European anchor role, leveraging French industrial policy support for platform-centric procurement dominance.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell Aerospace |
| BAE Systems |
| Leonardo |
| Saab |
| Elbit Systems |
| L3Harris Technologies |
| General Dynamics |
| Thales Group |
| Others |
Supply & Pricing Matrix
Platform-centric procurement contracts with multi-year helmet system bundles lock in supply access for primes while freezing price visibility for component-dependent suppliers across United States and French fighter programs. This contract structure concentrates pricing power among vertically integrated houses with captive waveguide fabrication while fragmenting margin pools for optical substrate importers facing Japanese and German supply bottlenecks.
Pricing Analysis
After-market service and spares revenue drives lifetime value for helmet system suppliers, with multi-year logistics support contracts often exceeding initial hardware unit economics. Three-tier pricing structure across fully integrated, hybrid, and standalone configurations separates platform-grade systems from training variants. Pricing pressure stems from waveguide cost compression as captive fabrication scales, squeezing refractive optics legacy providers. Flight training organizations exhibit highest price sensitivity, while Israeli and French defense procurement offices prioritize ballistic performance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for precision optical substrates sourced from Japanese and German specialty glass manufacturers. Waveguide nanofabrication draws from concentrated feedstock in Japan and Germany, with diffractive combiner elements resting on photoresist and rare-earth dopant supply chains. Single-source vulnerability permeates high-index glass substrate procurement, where Schott AG and Hoya Corporation anchor global capacity. Distribution runs through defense prime direct-to-military channels and civil aviation OEM tier-one supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in aerospace helmet mounted displays centers on airframe-helmet integration bundling, where interoperability standards for loyal wingman control interfaces are reshaping vendor lock-in dynamics across NATO procurement channels.
For Market Incumbents: Fortify captive waveguide fabrication capacity in Iowa and Provence-Alpes-Côte d'Azur to defend against refractive optics substitution pressure. Deepen backward integration into precision glass substrate supply through strategic partnerships with Japanese and German specialty manufacturers, securing inventory buffers against geographic disruption. For New Entrants and Emerging Players: Differentiate on UAV ground control station displays, where loyal wingman operator stations remain underpenetrated by legacy cockpit-focused suppliers. Target Indian defense modernization through PLI scheme-compliant assembly partnerships in Bengaluru and Hyderabad, leveraging offset requirements to bypass prime-dominated platform contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated system houses with multi-year logistics support contracts, offering superior cash flow predictability over component suppliers exposed to program cancellation risk. Waveguide nanofabrication specialists with Israeli or French sovereign production credentials represent priority acquisition archetypes. Monitor EU AI Act compliance clause insertion into European military RFPs as signal for software architecture inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Glass Fabrication | Captive waveguide substrate production compresses delivery timelines for United States Air Force Next Generation Air Dominance contracts. |
| AI-Act Compliance Software Architecture Redesign | Explainability layer embedding secures European military procurement eligibility ahead of formal mandate deadlines. |
| Localized Assembly Partnership in India | PLI scheme qualification opens offset-compliant production for domestic integrators seeking Rafale and Tejas program participation. |
| UAV Ground Control Display Development | Loyal wingman operator station integration expands addressable market beyond manned cockpit applications. |
| Multi-Regime Certification Team Expansion | Dedicated FAA Part 25, EMA MDR, and Israeli MOD compliance capabilities accelerate product validation cycles. |
Research Methodology
Cross-validation between primary interviews with fighter program procurement officers, helmet system engineering directors, and precision optics manufacturing executives and secondary validation against FAA certification databases, EMA MDR filings, and Israeli MOD testing protocol documentation anchors the qualitative findings. Bottom-up triangulation from component-level bill-of-materials analysis and top-down reconciliation against defense budget appropriation schedules ensures methodological consistency.
Sensitivity analysis across waveguide adoption rate scenarios, fighter platform procurement delays, and civil aviation certification timeline variations informs the analytical framework. Segmentation dimensions modeled include product integration depth, optical technology architecture, application environment, and end-user physiology requirements. CAGRs derive from platform delivery schedules, helmet system content-per-aircraft assumptions, and replacement cycle frequency inputs across military and civil aviation fleets.
Decision-makers should treat outputs as directional under sustained defense modernization budget trajectories and waveguide cost parity assumptions; material deviation in either vector would warrant model refresh. Forecasts reflect these base conditions without contingency for program cancellation or supply chain disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market