
 Aircraft Cockpit Systems Market | 2026-2036
Aircraft Cockpit Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cockpit Systems Market Outlook
OEM-direct procurement channels is rewriting how avionics suppliers reach fleet operators, bypassing traditional aftermarket distributors for integrated cockpit suites. Thales Group leverages its flight management systems portfolio to anchor long-term contracts with Airbus and regional jet programs. Honeywell International Inc. competes through end-to-end cockpit integration spanning displays, controls, and connectivity layers. Garmin Ltd specializes in the business aviation and general aviation tiers, where retrofit cycles run shorter and owner-operator decision-making dominates purchasing.
Aircraft cockpit systems comprise the integrated avionics, flight instruments, navigation displays, and control interfaces that enable pilots to command, monitor, and communicate during all flight phases, typically incorporating multi-function displays with 10-15 inch diagonal formats and ARINC 429/664 data buses for subsystem interoperability. Glass cockpit technology leads the technology dimension as analog systems face obsolescence across commercial and military fleets, while fly-by-wire architectures gain share in new military platforms and regional aircraft redesigns. Civil aviation commands the largest end-user segment by installed base, though military aviation generates higher unit margins due to hardened specifications and classified interface requirements.
FAA NextGen mandates and EASA CS-25 airworthiness standards shape product roadmaps by requiring ADS-B Out, LPV approach capability, and synthetic vision upgrades across certified transport aircraft. China's CAAC harmonization with ICAO standards and its domestic GB avionics certification framework create parallel compliance pathways for suppliers serving COMAC programs. Stakeholders must monitor regulatory divergence between FAA, EASA, and CAAC interface standards as these bodies advance incompatible data-link and cybersecurity specifications that could fragment cockpit architecture choices.
Market Dynamics
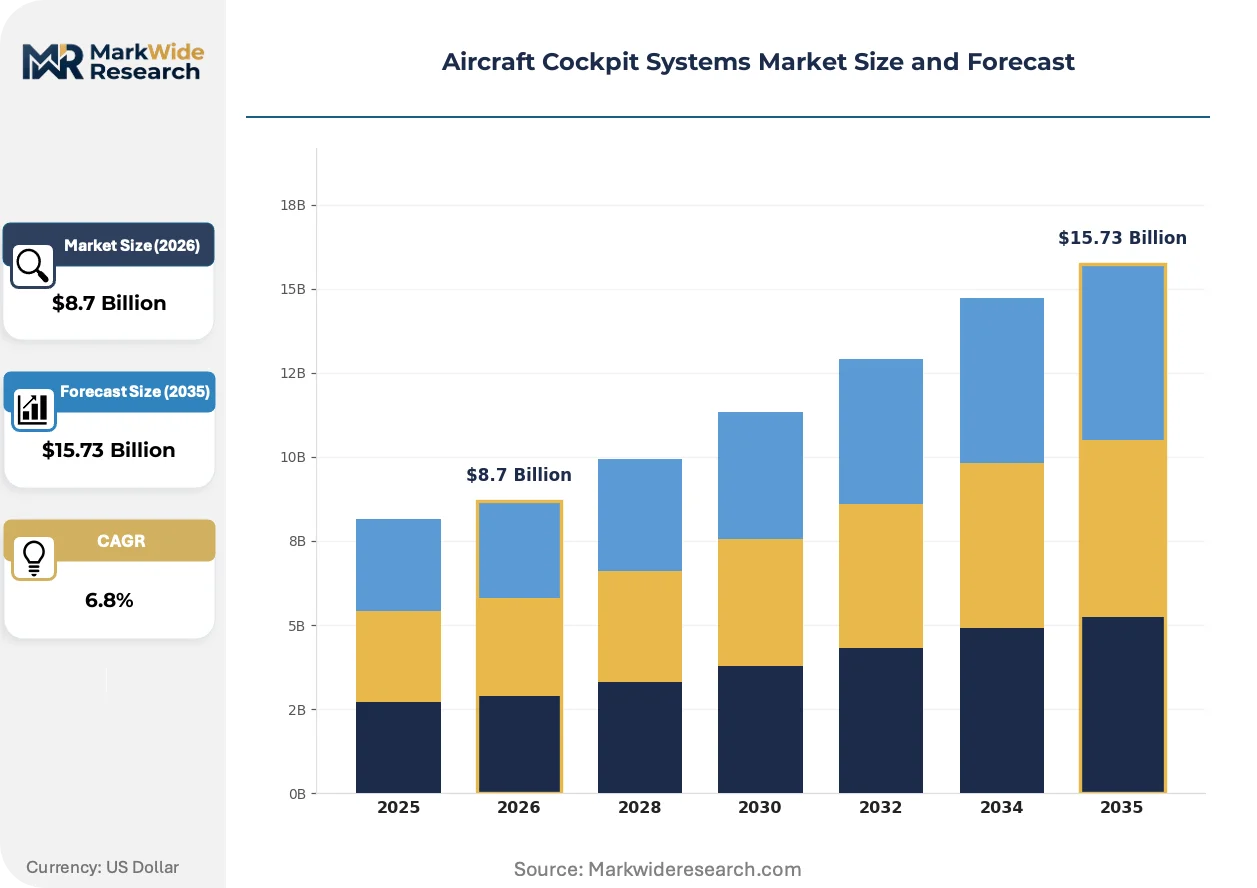
Fleet modernization mandates from FAA NextGen and EASA CS-25 certification updates are forcing accelerated retrofit cycles across aging narrow-body aircraft, compressing supplier lead times and reshaping procurement relationships between avionics vendors and airline operators.
Growth Catalysts
- FAA NextGen Mandates:ADS-B Out and LPV approach capability requirements are compelling airlines to upgrade flight management systems and navigation displays across certified transport fleets.
- Glass Cockpit Technology:Analog instrument obsolescence is driving replacement demand as multi-function displays with ARINC 429/664 data buses become standard for subsystem interoperability.
- China:CAAC harmonization with ICAO standards and domestic GB avionics certification frameworks are creating parallel compliance pathways for suppliers serving COMAC programs.
Market Restraints
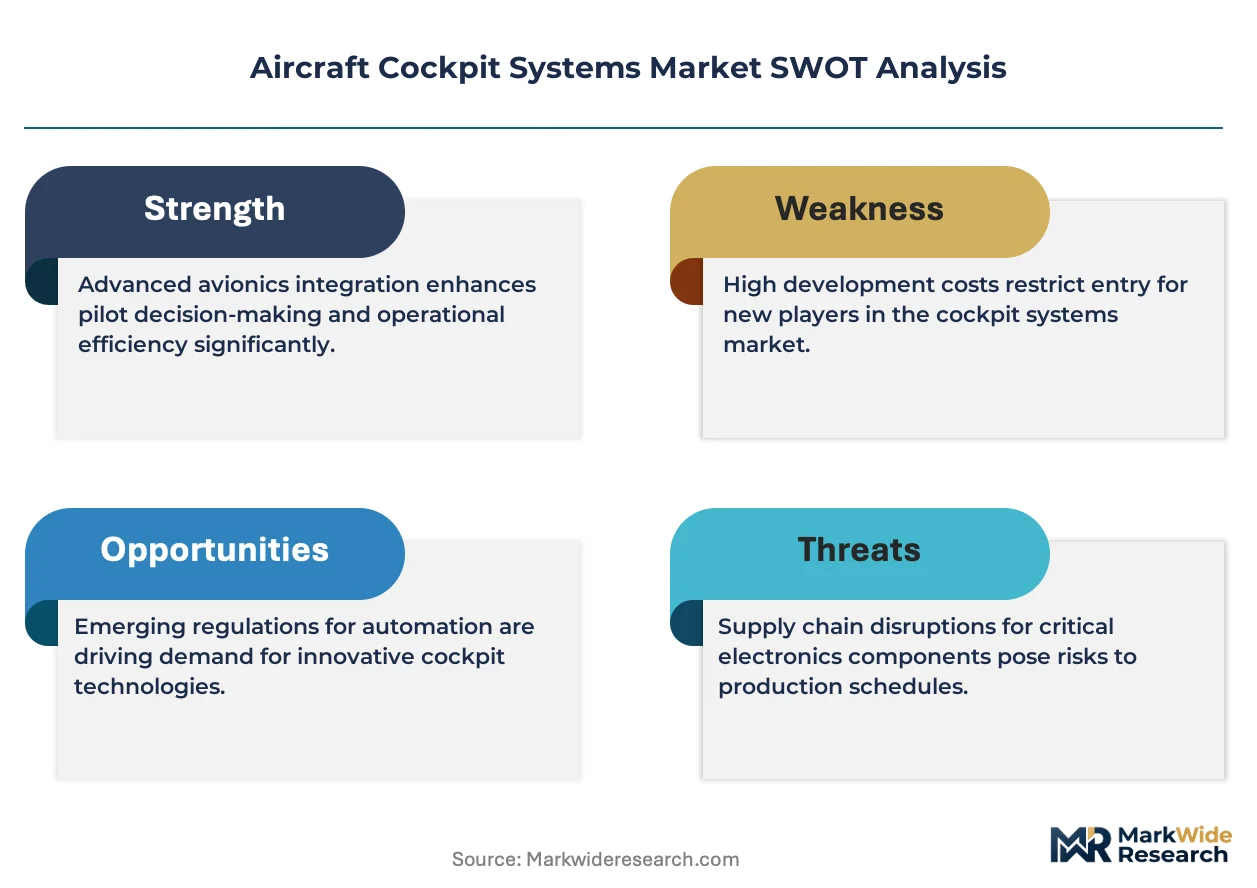
- Supply Concentration Risk:Specialized semiconductor foundries for aviation-grade components concentrate in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- Technical Limitation:Synthetic vision system certification requires extensive flight testing that extends product qualification timelines beyond typical commercial development cycles.
- Regulatory Friction:Divergent cybersecurity specifications between FAA, EASA, and CAAC are fragmenting cockpit architecture choices and forcing redundant engineering investments.
Strategic Opportunities
- Business Aviation Retrofit:Owner-operator decision-making in general aviation enables shorter sales cycles and higher-margin integrated cockpit suite deployments.
- Fly-by-Wire Convergence:Military platform hardened specifications are migrating into regional aircraft redesigns, opening dual-use technology licensing pathways.
- EASA CS-25 Updates:Certification pathway accelerations for synthetic vision and connectivity layers create first-mover advantages for compliant suppliers.
Industry Challenges
- Certification Timeline Compression:FAA and EASA parallel validation processes demand dedicated regulatory affairs teams with jurisdiction-specific expertise.
- Legacy System Integration:ARINC 429 backward compatibility requirements complicate ARINC 664 Ethernet migration in mixed-generation fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cockpit Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Management Systems, Display Units, Control Systems, Monitoring Systems Technology: Glass Cockpit, Analog Systems, Fly-by-Wire, Digital Flight Control End User: Civil Aviation, Military Aviation, Business Aviation, General Aviation Application: Commercial Flights, Cargo Operations, Private Flights, Training |
| Companies Covered | Thales Group, Northrop Grumman Corporation, Honeywell International Inc., Avidyne Corporation, Aspen Avionics Inc., Collins Aerospace, Elbit Systems, Continental AG, Garmin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cockpit Systems Market Strategic Shifts
Aviation human-machine interfaces are undergoing fundamental redesign as touch-sensitive controls, voice recognition, and predictive alerting systems replace mechanical switches and static instrument panels.
Synthetic vision systems (SVS) are hybridizing sensor fusion architectures that combine terrain databases, weather radar, and traffic collision avoidance into unified pilot displays. Regional airlines and cargo operators are adopting SVS for low-visibility operations at secondary airports. This convergence is compressing the capability gap between premium wide-body suites and narrow-body retrofit offerings.
EASA CS-25 airworthiness standards now mandate cybersecurity risk assessments for all new cockpit system certifications, extending to supply chain software provenance documentation. Manufacturers must demonstrate threat modeling across embedded operating systems and data-link protocols. European operators are responding by consolidating vendor relationships with suppliers holding dual FAA-EASA validation credentials.
Airline technical procurement teams are consolidating avionics purchasing under fleet lifecycle management contracts rather than transactional component orders. Long-term service agreements now bundle hardware, software updates, and regulatory compliance monitoring. This restructuring is most pronounced among United States network carriers managing mixed Airbus-Boeing fleets under unified technical operations divisions.
Aircraft Cockpit Systems Market Segmentation
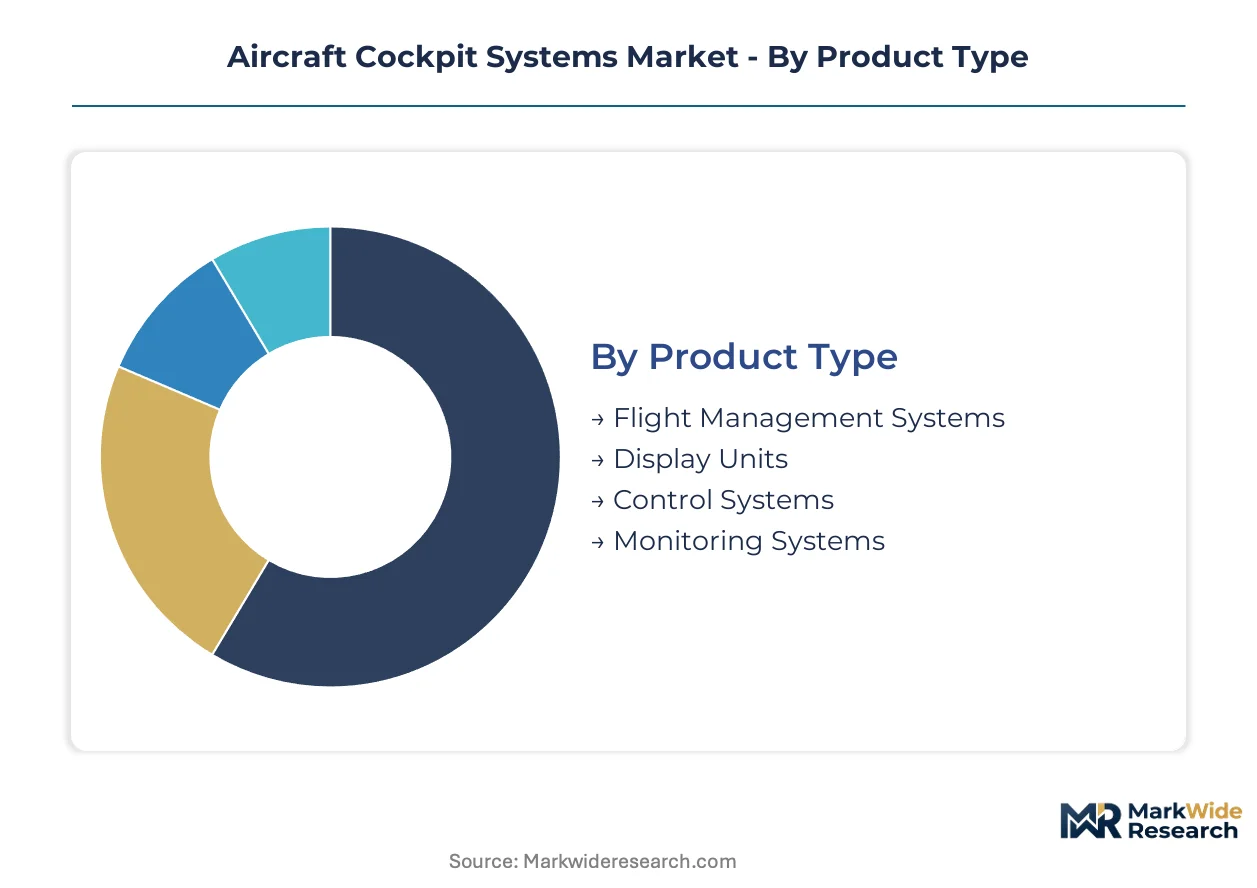
Cockpit system procurement patterns diverge sharply across aircraft categories, with retrofit cycles in general aviation running one-third the duration of commercial transport mandates. Understanding these rhythm differences enables suppliers to align inventory and certification resources against predictable replacement waves.
Product Type:
Replacement velocity varies from 18-month display refresh cycles to decade-long flight management system overhauls, creating tiered revenue recognition profiles for avionics vendors.
- Flight Management Systems:Core navigation computers processing waypoint sequencing, performance optimization, and ADS-B compliance data. Airlines in the United States prioritize FMS upgrades to meet FAA NextGen mandates ahead of equipage deadlines. Flight Management Systems anchors the volume base while Display Units gains share at the steepest rate.
- Display Units:Multi-function LCD and OLED panels ranging from 10-inch standby instruments to 15-inch primary flight displays with synthetic vision overlays. Retrofit demand concentrates in Germany as Lufthansa Technik drives narrow-body modernization programs for European operators.
- Control Systems:Side-stick, yoke, and throttle quadrant interfaces with haptic feedback and mode annunciation.
- Monitoring Systems:Engine indication and crew alerting computers consolidating subsystem health data.
Control Systems and Monitoring Systems follow longer procurement cycles tied to airframe heavy maintenance intervals.
Technology:
Architecture choices determine margin structure, with hardened military specifications commanding 40-60% premiums over commercial equivalents while analog legacy support generates recurring service revenue.
- Glass Cockpit:Integrated electronic flight instrument systems replacing mechanical gauges with reconfigurable multi-function displays. China's COMAC C919 and ARJ21 programs in Shanghai and Xi'an specify domestic GB-certified glass suites, creating parallel certification pathways alongside FAA-EASA validation.
- Analog Systems:Electromechanical attitude indicators, altimeters, and airspeed indicators retained in vintage aircraft and cost-sensitive training fleets.
- Fly-by-Wire:Digital flight control computers translating pilot inputs into surface actuator commands without mechanical linkages. Military platforms in the United States and France drive hardened specification development that migrates into regional aircraft redesigns.
- Digital Flight Control:Augmented stability systems with envelope protection and autothrottle integration.
Glass Cockpit dominates installed base value while Fly-by-Wire climbs the fastest as military-derived architectures penetrate commercial applications.
End User:
Customer concentration shapes contract structure, with airline fleet managers demanding lifecycle service bundles versus owner-operators purchasing discrete component upgrades.
- Civil Aviation:Scheduled airlines and cargo operators managing mixed Airbus-Boeing fleets under unified technical operations divisions. Network carriers in the United States consolidate avionics purchasing under decade-long agreements bundling hardware, software updates, and regulatory compliance monitoring.
- Military Aviation:Defense agencies requiring classified interface specifications, cybersecurity hardening, and MIL-STD-1553 data bus compatibility. Higher unit margins reflect extended qualification timelines and proprietary encryption modules.
- Business Aviation:Corporate flight departments and fractional ownership programs with shorter decision chains and premium feature willingness.
- General Aviation:Owner-operated piston and light turbine aircraft with experimental category installation flexibility.
Civil Aviation generates the largest absolute revenue pool while Business Aviation offers the most attractive margin profile per installation.
Application:
Operational intensity dictates equipment duty cycles, with cargo freighters accumulating flight hours at 2.5x the rate of passenger equivalents and accelerating wear-out replacement schedules.
- Commercial Flights:Scheduled passenger operations subject to EASA CS-25 and FAA Part 25 certification requirements for transport category aircraft. European operators respond to cybersecurity risk assessment mandates by consolidating vendor relationships with dual FAA-EASA validated suppliers.
- Cargo Operations:Dedicated freighter and converted passenger-to-cargo fleets operating high-utilization routes with minimal ground time. United Parcel Service and FedEx hub operations in Louisville and Memphis drive demand for synthetic vision systems enabling low-visibility approaches at secondary airports.
- Private Flights:Non-scheduled charter and personal transportation with owner-operator purchasing authority.
- Training:Flight schools and university aviation programs operating standardized fleets with high student touch rates.
Commercial Flights represents the deepest retrofit backlog while Cargo Operations shows the steepest expansion trajectory as e-commerce fulfillment networks expand dedicated freighter capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA NextGen mandates in the United States are compelling airlines to accelerate flight management system upgrades ahead of equipage deadlines, while EASA CS-25 cybersecurity requirements in Europe are reshaping supplier validation priorities.
United States
Network carriers operating mixed Airbus-Boeing fleets are consolidating avionics purchasing under decade-long lifecycle management contracts. FAA Part 25 certification requirements for ADS-B Out and LPV approach capability are driving synthetic vision system retrofits across aging narrow-body aircraft. Seattle and Wichita clusters host major OEM engineering centers where flight control integration testing occurs.
Germany
Lufthansa Technik is spearheading narrow-body modernization programs that concentrate display unit demand from European operators. EASA CS-25 airworthiness standards mandating cybersecurity risk assessments are forcing supply chain software provenance documentation. Hamburg and Munich industrial corridors house avionics integration facilities serving COMAC and Airbus programs simultaneously.
China
COMAC C919 and ARJ21 programs in Shanghai and Xi'an are specifying domestic GB-certified glass cockpit suites alongside FAA-EASA validation pathways. CAAC harmonization with ICAO standards is creating parallel compliance frameworks for suppliers serving indigenous aircraft production. Chengdu and Xi'an defense-industrial complexes are migrating hardened military flight control architectures into regional commercial applications.
France
Thales Group leverages its flight management systems portfolio to anchor long-term contracts with Airbus assembly lines in Toulouse. EASA regulatory leadership on synthetic vision certification is compressing product qualification timelines for compliant suppliers. Paris-Saclay aerospace cluster coordinates dual-use technology transfer between military platform development and regional aircraft redesigns.
United Kingdom
Collins Aerospace and BAE Systems operations in southern England are supporting military aviation programs requiring classified interface specifications and MIL-STD-1553 compatibility. CAA alignment with EASA post-Brexit is maintaining regulatory continuity for suppliers serving European airline technical procurement teams. Bristol and Farnborough corridors concentrate avionics R&D investment focused on connectivity layer integration.
Aircraft Cockpit Systems Market Competitive Environment
On the supply side, the industry is consolidating around integrated cockpit suite providers capable of delivering end-to-end hardware-software bundles under long-term service agreements. Tier-one suppliers anchor procurement relationships with OEM direct channels, while specialized avionics vendors occupy retrofit and aftermarket niches. Two strategic archetypes dominate: full-stack integrators spanning displays, controls, and connectivity layers; and focused specialists leveraging shorter decision chains in business aviation. Competitive intensity manifests through technology licensing partnerships and regulatory validation credential accumulation.
Among transatlantic defense-avionics conglomerates, Northrop Grumman Corporation and Collins Aerospace exemplify the hardened-specification tier where military platform requirements generate premium unit margins. Garmin Ltd occupies a distinct position within the owner-operator segment, where retrofit cycles compress and purchasing authority concentrates in individual decision-makers. Thales Group anchors the European supplier vector through flight management system portfolios tied to Airbus production lines.
| Leading Market Players |
|---|
| Thales Group |
| Northrop Grumman Corporation |
| Honeywell International Inc. |
| Avidyne Corporation |
| Aspen Avionics Inc. |
| Collins Aerospace |
| Elbit Systems |
| Continental AG |
| Garmin Ltd |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwan and South Korea for aviation-grade semiconductors determines both pricing tier spreads and supply chain shape across cockpit system manufacturing. FAA and EASA cybersecurity mandates compress supplier margins while fragmenting certification pathways, forcing tiered pricing structures that separate hardened military specifications from commercial equivalents.
Pricing Analysis
Certification level creates the primary spread between FAA-EASA dual-validated suppliers and single-jurisdiction vendors. Three-tier pricing structure separates military-grade hardened systems, commercial transport validated suites, and general aviation retrofit bundles. Pricing pressure stems from airline fleet managers consolidating purchasing under decade-long lifecycle contracts that bundle hardware, software updates, and regulatory compliance monitoring. Owner-operators in business aviation show lowest price sensitivity due to compressed decision chains and premium feature willingness.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for cockpit system manufacturers. Specialized semiconductor foundries concentrate in Taiwan, South Korea, and Japan, drawing from rare earth processing facilities in China and precision optics suppliers in Germany. Single-source vulnerability persists for ARINC 664 Ethernet switch components and synthetic vision graphics processors. Distribution runs through OEM direct channels for new aircraft programs and certified repair stations for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet modernization cycles are accelerating as FAA NextGen equipage deadlines compress retrofit windows, positioning the market at early-cycle expansion. Airlines are consolidating vendor relationships under unified technical operations divisions that favor integrated suite providers with dual regulatory validation.
For Market Incumbents: Build regulatory validation moats by securing parallel FAA-EASA certification credentials ahead of cybersecurity mandate divergence. Consolidate channel control through exclusive lifecycle management contracts with network carriers operating mixed Airbus-Boeing fleets. Anchor procurement relationships by embedding flight management system upgrades within heavy maintenance intervals at Lufthansa Technik and similar MRO providers. For New Entrants and Emerging Players: Pursue white-space opportunities in business aviation retrofit segments where owner-operator decision chains compress sales cycles. Target general aviation experimental category installations as the most penetrable entry point before pursuing certified transport aircraft validation. Differentiate through synthetic vision system specialization for regional airlines operating at secondary airports with low-visibility approach requirements. For Investors and Strategic Acquirers: The market sits at a regulatory-driven replacement phase that favors dual-use technology licensors with military-derived commercial applications. Long-term viability hinges on suppliers capable of navigating divergent FAA-EASA-CAAC cybersecurity specifications without redundant engineering investment. Monitor CAAC harmonization progress with ICAO standards as the signal indicating inflection toward indigenous Chinese aircraft program participation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual FAA-EASA Certification Investment | European operators consolidate vendor relationships with suppliers holding dual validation credentials under CS-25 cybersecurity mandates. |
| Synthetic Vision System Specialization | Regional airlines adopt SVS for low-visibility operations at secondary airports, compressing capability gaps between wide-body and narrow-body suites. |
| Military-Derived Technology Licensing | Hardened fly-by-wire specifications from United States and French defense programs migrate into regional aircraft redesigns. |
| Lifecycle Management Contracting | United States network carriers bundle hardware, software updates, and regulatory compliance monitoring under unified technical operations divisions. |
| CAAC Parallel Validation Pathway | Suppliers serving COMAC C919 and ARJ21 programs in Shanghai and Xi'an navigate domestic GB certification alongside FAA-EASA validation. |
Study Parameters
Operator-level perspectives from airline fleet managers, MRO technical directors, avionics procurement officers, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from FAA ADS-B equipage databases, EASA certification bulletins, COMAC program disclosures, and airline technical operations filings. Bottom-up triangulation across product type, technology architecture, and end-user segment informed volume estimates, while top-down cross-checks against OEM delivery schedules and fleet age profiles anchored value projections.
Scenario-bracketing framed analytical development across the projection horizon, modeling demand under baseline regulatory compliance and accelerated cybersecurity mandate scenarios. Segmentation dimensions included product type, technology architecture, end-user category, and application intensity, with regional regulatory cluster as the aviation-specific overlay. CAGRs derived from fitted growth curves against historical retrofit cycle patterns, incorporating fleet age distributions and mandate deadline proximity as industry-specific forecast inputs.
Sensitivities concentrate around CAAC regulatory divergence from ICAO standards, semiconductor supply disruption from Taiwan Strait tensions, and airline bankruptcy cycles that compress retrofit spending. Forecasts reflect documented assumptions regarding mandate deadline adherence and OEM delivery schedule realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market