
 Glass Cockpit for Aerospace Market | 2026-2036
Glass Cockpit for Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Cockpit for Aerospace Market Analysis
OEM-direct and MRO distribution channels is rewriting how avionics suppliers reach fleet operators. Honeywell International Inc. leverages its integrated flight deck portfolio to dominate retrofit contracts for narrow-body aircraft. Thales Group sustains technology leadership through synthetic vision and head-up display systems for military and commercial platforms. Garmin Ltd. competes aggressively in general aviation with certified integrated avionics suites that lower entry barriers for piston and turboprop operators.
Glass cockpit systems integrate electronic flight instrument displays, digital avionics processors, and software-driven human-machine interfaces that replace traditional electromechanical gauges. These systems process sensor inputs through ARINC 429 and Ethernet avionics data buses, presenting consolidated flight, navigation, and engine information on multi-function LCD or OLED panels to reduce pilot workload and enhance situational awareness. Synthetic vision system technology leads investment as terrain and obstacle rendering capabilities become standard for Part 25 transport category aircraft. Military aviation end-user demand accelerates fastest as defense ministries mandate networked battlefield digitization and helmet-mounted cueing integration. Display units within the component segment anchor margin pools due to stringent certification requirements and multi-layer supply constraints.
FAA, EASA, and ICAO standards govern glass cockpit certification through DO-178C software assurance, DO-254 hardware integrity, and minimum performance specifications for electronic flight displays. These frameworks shape demand by mandating terrain awareness, traffic collision avoidance, and required navigation performance capabilities that drive fleet-wide retrofit cycles. Stakeholders must monitor harmonization gaps between FAA NextGen and EASA SESAR implementation timelines that could fragment certification pathways and alter supplier competitive dynamics.
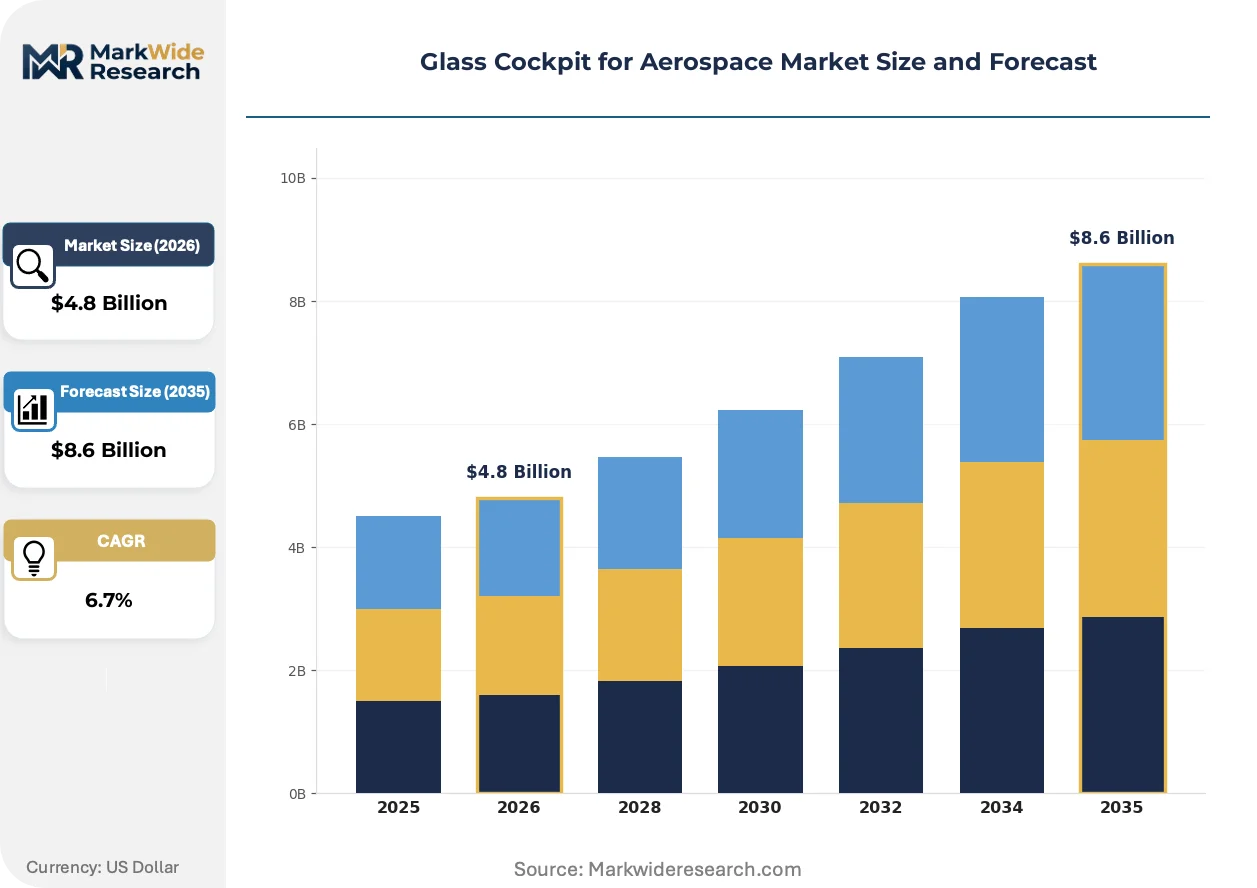
Market Dynamics
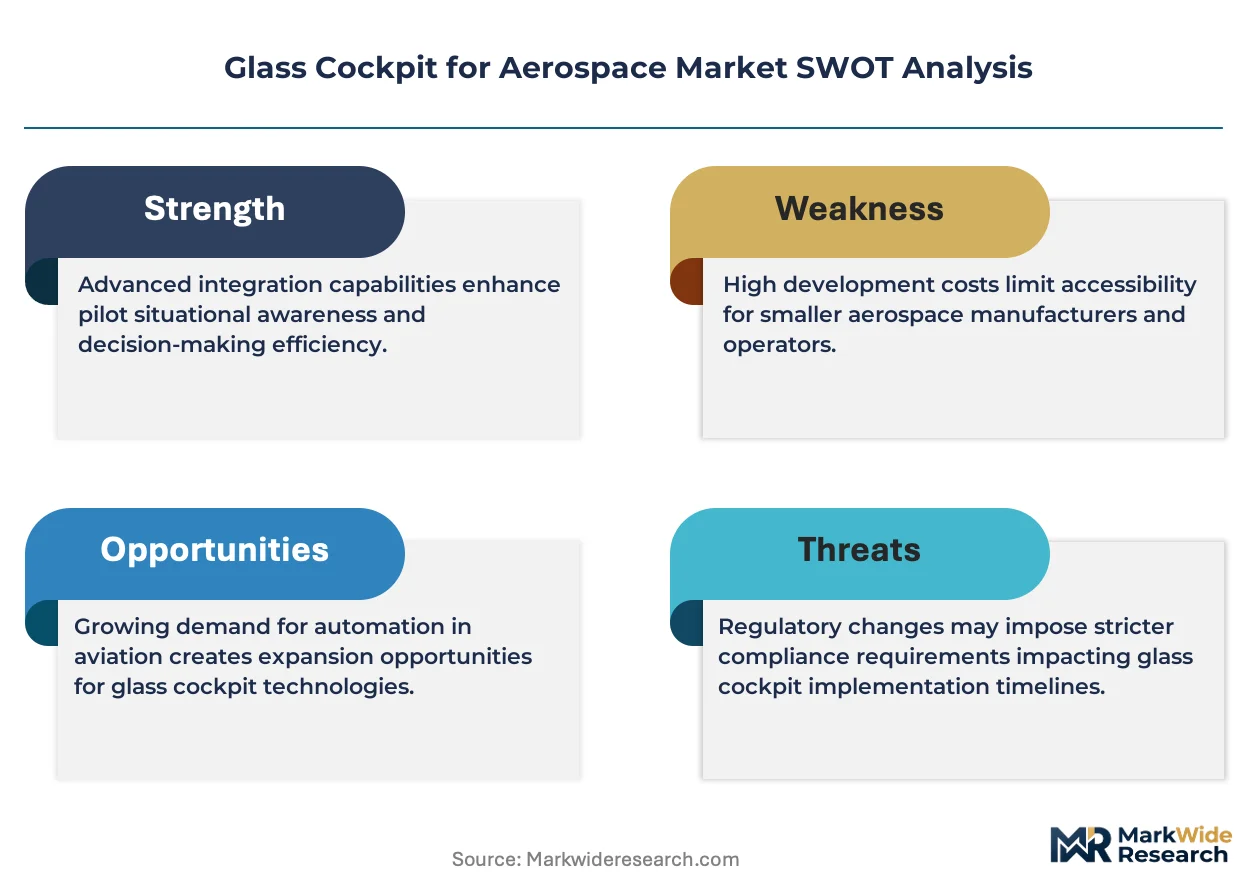
FAA NextGen mandates and EASA cockpit modernization directives are compressing retrofit timelines for aging commercial fleets, forcing operators to accelerate electronic flight display upgrades ahead of regulatory deadlines.
Growth Catalysts
- DO-178C Software Assurance Mandates:FAA certification requirements for terrain awareness and traffic collision avoidance systems are mandating fleet-wide glass cockpit retrofits for Part 25 transport category aircraft.
- Helmet-Mounted Cueing Integration:Military aviation end-users are driving demand for networked battlefield digitization that requires advanced synthetic vision and head-up display systems.
- LCD/OLED Panel Manufacturing Concentration:Display technology advances in South Korea and Taiwan are lowering unit costs for multi-function electronic flight instrument systems.
Market Restraints
- ARINC 429 to Ethernet Migration Costs:Legacy aircraft wiring infrastructure requires expensive airframe modifications to support modern avionics data bus architectures.
- Multi-Layer Display Supply Constraints:Stringent aerospace certification requirements limit qualified suppliers for sunlight-readable LCD and OLED panels to a concentrated tier-one base.
- Electromechanical Gauge Spare Parts:MRO operators maintain inventories of analog instruments, creating substitution friction for full glass cockpit conversions.
Strategic Opportunities
- General Aviation Piston Aircraft:Garmin's certified integrated avionics suites have created accessible retrofit pathways for owner-operated turboprop fleets previously priced out of glass cockpit upgrades.
- FAA-EASA Harmonization Gaps:Fragmented certification timelines between NextGen and SESAR implementation create arbitrage opportunities for suppliers with dual-approval capabilities.
- Synthetic Vision + Head-Up Display Convergence:Terrain and obstacle rendering technologies are merging with augmented reality flight path guidance to create next-generation human-machine interfaces.
Industry Challenges
- DO-254 Hardware Integrity Certification:Digital avionics processors require extensive verification cycles that extend product development timelines and strain engineering talent pools.
- Legacy Analog System Integration:Hybrid cockpit configurations demand specialized interface units to bridge electromechanical sensors with modern electronic flight displays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Cockpit for Aerospace Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LCD, LED, OLED, Synthetic Vision System End User: Commercial Airlines, Military Aviation, General Aviation, Business Jets Application: Flight Navigation, Instrumentation, Cockpit Display, Situational Awareness Component: Display Units, Control Systems, Sensors, Software |
| Companies Covered | Thales Group, United Technologies Corporation, Honeywell International Inc., Universal Avionics Systems, BAE Systems, Garmin Ltd., Elbit Systems Ltd., The Boeing Company, Rockwell Collins (Collins Aerospace), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Cockpit for Aerospace Market Emerging Trajectories
Software-defined avionics architectures are displacing hardware-centric designs, enabling continuous flight deck upgrades through over-the-air updates rather than physical component replacement.
Synthetic vision system technology is rendering obsolete traditional attitude indicator reliance on clear-day visual meteorological conditions. Regional airlines operating in mountainous terrain are adopting terrain-rendering capabilities at accelerated rates. This technology is compressing the operational advantage gap between experienced and novice flight crews.
EASA's SESAR deployment timeline is diverging from FAA NextGen implementation schedules, creating dual-certification burdens for suppliers seeking transatlantic market access. European operators face accelerated mandates for required navigation performance capabilities that exceed current US equipage deadlines. Military procurement offices in Germany and France are prioritizing helmet-mounted cueing systems that exceed civilian certification frameworks.
Airline procurement departments are unbundling avionics upgrades from airframe purchase agreements, creating direct supplier relationships previously intermediated by OEMs. Low-cost carriers in Southeast Asia are negotiating retrofit contracts independent of Boeing and Airbus delivery schedules. This pattern concentrates in Indonesia and Vietnam where fleet expansion outpaces factory-new glass cockpit availability.
Glass Cockpit for Aerospace Market Segmentation
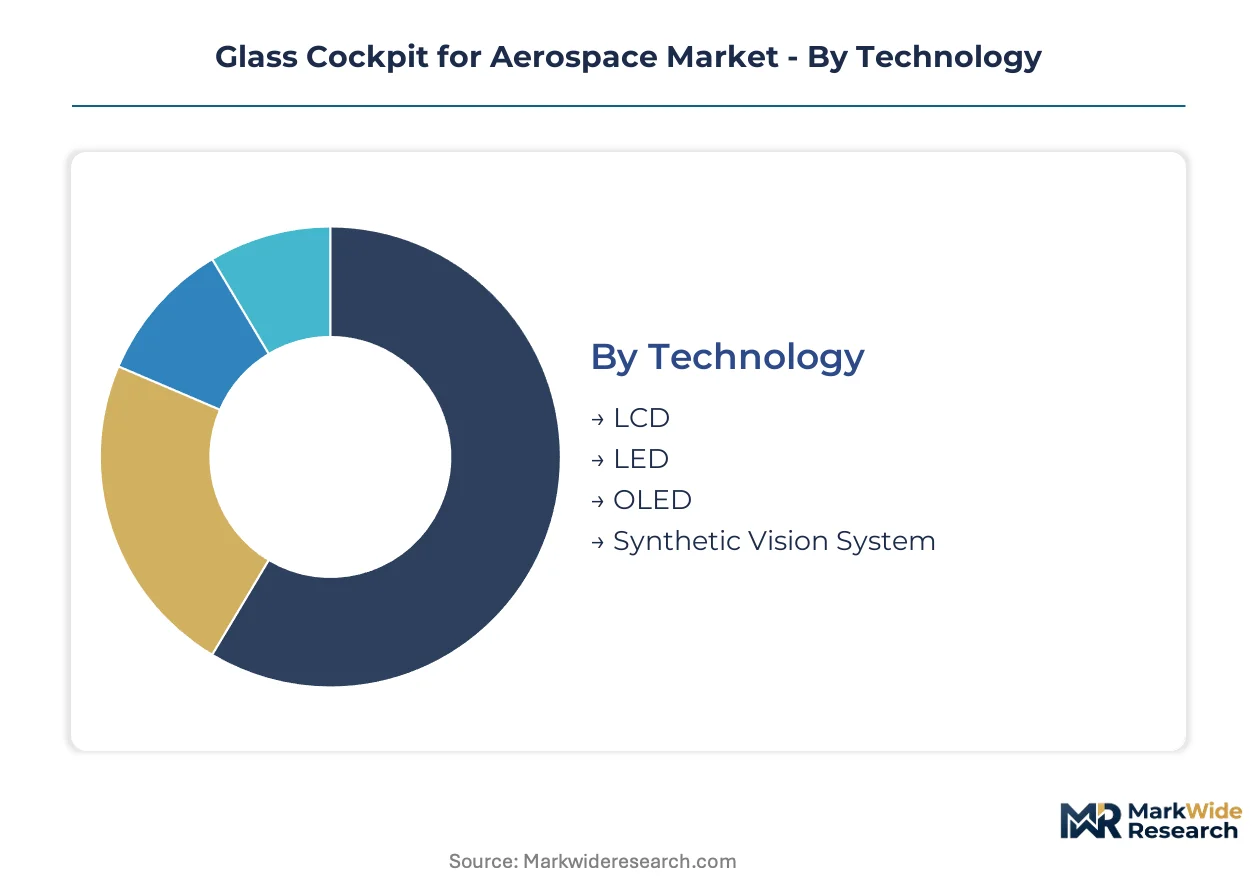
Glass cockpit segmentation reveals how display technology, end-user requirements, and application complexity create distinct margin pools and certification pathways. Component hierarchy and end-user procurement patterns determine supplier competitive positioning across retrofit and OEM channels.
Technology:
Cost tier stratification separates legacy display technologies from emerging synthetic vision capabilities that command premium positioning.
- LCD:Dominates commercial transport retrofits with mature manufacturing economics and established FAA certification pathways. Narrow-body fleet operators in the United States specify LCD-based flight displays for cost-controlled modernization programs under NextGen mandates.
- Synthetic Vision System:Renders terrain, obstacles, and flight path guidance through computer-generated imagery independent of visual meteorological conditions. Regional airlines operating in mountainous terrain across Colorado and Utah adopt these systems at accelerated rates to compress operational advantage gaps between flight crews.
- LED:Offers improved luminance efficiency for sunlight-readable cockpit environments with reduced power draw versus legacy alternatives.
- OLED:Enables thinner form factors and wider viewing angles for next-generation integrated flight deck architectures.
LCD holds installed capacity. Synthetic Vision System is rotating up the share rankings.
End User:
Application maturity varies sharply across customer types, with military procurement cycles and commercial retrofit timelines creating divergent demand patterns.
- Commercial Airlines:Drive volume through narrow-body retrofit programs as FAA NextGen equipage deadlines compress upgrade timelines. Fleet operators negotiate direct supplier relationships unbundled from OEM purchase agreements, particularly among low-cost carriers in Southeast Asia.
- Military Aviation:Demands networked battlefield digitization with helmet-mounted cueing integration exceeding civilian certification frameworks. Defense ministries in Germany and France prioritize synthetic vision and head-up display convergence for combat aircraft platforms.
- General Aviation:Owner-operated turboprop fleets access glass cockpit upgrades through certified integrated avionics suites that lower entry barriers previously excluding this segment.
- Business Jets:Specify premium display configurations with augmented reality flight path guidance and custom human-machine interface designs.
Commercial Airlines anchor current procurement volume. Military Aviation is expanding most quickly as defense digitization mandates accelerate.
Application:
Functional criticality determines certification burden and supplier qualification requirements across flight deck domains.
- Flight Navigation:Integrates GPS, inertial reference, and required navigation performance data through ARINC 429 and Ethernet avionics buses. EASA SESAR deployment timelines diverge from FAA NextGen schedules, creating dual-certification burdens for suppliers seeking transatlantic market access.
- Situational Awareness:Consolidates traffic collision avoidance, terrain awareness, and weather radar inputs through software-defined architectures enabling over-the-air updates. This application is gaining share fastest as regulatory mandates expand beyond basic flight instrumentation.
- Instrumentation:Replaces electromechanical attitude, altitude, and airspeed indicators with electronic flight instrument systems.
- Cockpit Display:Encompasses multi-function LCD and OLED panels presenting consolidated engine, system, and flight management information.
Flight Navigation holds installed capacity. Situational Awareness is climbing the fastest as terrain and traffic integration becomes standard.
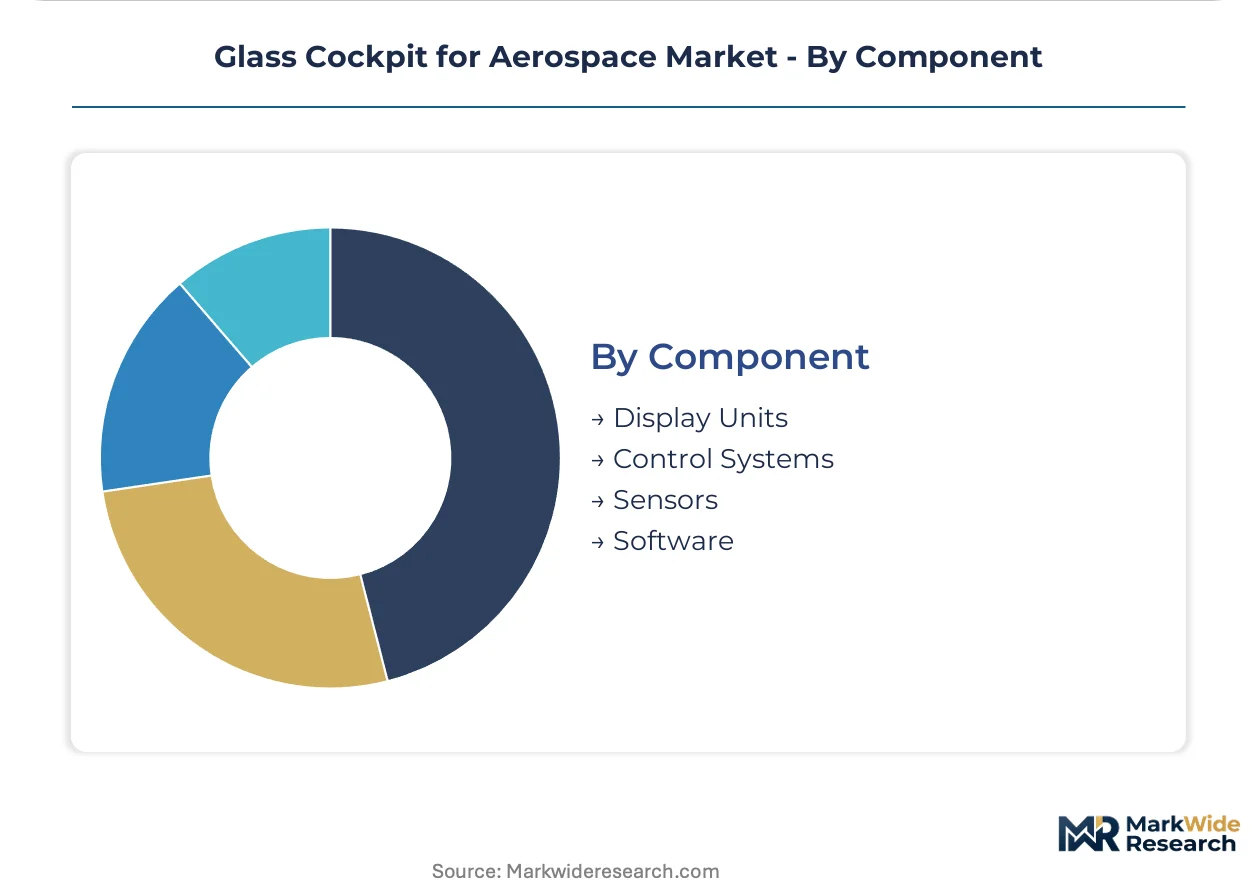
Component:
Supply concentration and margin distribution concentrate in display hardware due to multi-layer certification constraints and qualified supplier scarcity.
- Display Units:Sunlight-readable LCD and OLED panels face stringent aerospace certification requirements limiting qualified suppliers to concentrated tier-one bases in South Korea and Taiwan. These units anchor margin pools within the component segment.
- Software:DO-178C assurance mandates for terrain awareness and traffic collision avoidance systems extend development timelines and strain engineering talent pools. Digital avionics processors require continuous verification cycles that differentiate competitive offerings.
- Control Systems:Interface units bridge legacy electromechanical sensors with modern electronic flight displays in hybrid cockpit configurations.
- Sensors:Provide air data, attitude, and heading reference inputs processed through integrated avionics architectures.
Display Units hold installed capacity. Software is rotating up the share rankings as software-defined architectures displace hardware-centric designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FAA NextGen mandates compress retrofit timelines, while European operators navigate fragmented EASA SESAR deadlines that dilute supplier leverage.
United States
Commercial airlines dominate procurement volume through narrow-body fleet modernization programs. FAA NextGen equipage requirements for terrain awareness and traffic collision avoidance systems mandate electronic flight display upgrades ahead of regulatory deadlines. Seattle and Wichita anchor production clusters where major OEMs and tier-one avionics suppliers concentrate R&D investment.
Germany
Military aviation procurement drives fastest expansion as defense ministries prioritize networked battlefield digitization. EASA SESAR deployment timelines diverge from FAA schedules, creating dual-certification burdens for suppliers seeking transatlantic market access. Munich and Hamburg host concentrated aerospace engineering talent pools developing helmet-mounted cueing integration systems.
France
Synthetic vision and head-up display convergence attracts premium positioning for combat aircraft platforms. Military procurement offices prioritize capabilities exceeding civilian certification frameworks established by EASA. Toulouse anchors commercial aviation clusters where airframe OEMs intermediate traditional supplier relationships.
United Kingdom
BAE Systems and defense contractors sustain demand for advanced human-machine interface technologies. CAA alignment with EASA standards shapes certification pathways for electronic flight instrument systems. Bristol and Farnborough concentrate avionics engineering capabilities serving both military and commercial end-users.
Japan
Industrial electronics manufacturing supplies multi-layer display components to qualified tier-one bases. METI standards govern avionics hardware integrity alongside international DO-254 certification requirements. Nagoya and Tokyo host precision manufacturing clusters producing sunlight-readable LCD and OLED panels.
Glass Cockpit for Aerospace Market Vendor Landscape
Integrated flight deck specialists and component-focused suppliers split the market between retrofit program dominance and technology module leadership. Consolidation concentrates around five to seven entities with end-to-end certification capabilities. Diversified conglomerates with aerospace divisions compete against pure-play avionics houses. Strategic moves center on M&A for regulatory approval portfolios and strategic partnerships for synthetic vision technology licensing.
Among diversified technology conglomerates, Honeywell International Inc. and Thales Group exemplify the integrated-systems archetype spanning commercial and military platforms. Garmin Ltd. occupies a distinct position within the accessible-retrofit tier, lowering entry barriers for owner-operated turboprop fleets. Elbit Systems Ltd. and BAE Systems anchor the defense-specialist segment where helmet-mounted cueing and networked battlefield requirements exceed civilian frameworks.
| Leading Market Players |
|---|
| Thales Group |
| United Technologies Corporation |
| Honeywell International Inc. |
| Universal Avionics Systems |
| BAE Systems |
| Garmin Ltd. |
| Elbit Systems Ltd. |
| The Boeing Company |
| Rockwell Collins (Collins Aerospace) |
| Others |
Supply Flow & Price Mechanics
Undercapacity in South Korean and Taiwanese OLED panel fabrication is tightening supply availability for multi-function flight displays and elevating pricing leverage for qualified tier-one suppliers serving FAA-mandated retrofit programs. This utilization dynamic compresses margins for avionics integrators while concentrating margin capture upstream in display manufacturing.
Pricing Analysis
The customization-premium spread separates standard LCD-based electronic flight instrument systems from synthetic vision configurations with terrain-rendering capabilities. Project-based pricing dominates, with DO-178C certification grade and after-sales service bundling as primary price differentiation drivers. Cost compression in narrow-body commercial retrofits is intensifying because low-cost carriers in Southeast Asia negotiate direct supplier contracts unbundled from OEM purchase agreements. General aviation owner-operators exhibit highest price sensitivity, while military procurement offices in Germany and France demonstrate lowest sensitivity due to helmet-mounted cueing integration requirements.
Supply Chain Analysis
Contract-manufacturing concentration in South Korea, Taiwan, and Japan holds capacity for sunlight-readable LCD and OLED aerospace-qualified panels. The supply chain draws from indium tin oxide substrates, aerospace-grade backlight assemblies, and ARINC 429-to-Ethernet interface chipsets as critical inputs. Single-source vulnerability in qualified display panel suppliers creates structural risk given FAA and EASA certification barriers that limit alternative qualification pathways. Distribution runs through OEM-direct channels and independent MRO retrofit networks serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as airline procurement departments unbundle avionics upgrades from airframe purchase agreements, creating direct supplier niches previously intermediated by Boeing and Airbus.
For Market Incumbents: Harden certification portfolio breadth across FAA NextGen and EASA SESAR dual-approval pathways to capture arbitrage from fragmented implementation timelines. Consolidate control over display unit supply through backward integration into OLED panel sourcing or captive supply agreements with South Korean and Taiwanese manufacturers. Synthetic vision technology licensing from emerging specialists poses substitution threat requiring defensive patent positioning. For New Entrants and Emerging Players: Build out certified integrated avionics suites targeting owner-operated turboprop fleets in general aviation, the most penetrable segment given Garmin's demonstrated pathway for lowering entry barriers. Focus initial go-to-market on direct-to-operator digital sales channels bypassing traditional OEM intermediation, mirroring low-cost carrier procurement patterns in Indonesia and Vietnam. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across software-defined avionics architectures as continuous DO-178C verification cycles replace discrete hardware development. Long-term viability favors acquisition targets with established dual-approval regulatory portfolios spanning FAA and EASA frameworks. Watch for inflection in airline unbundling rates as indicator of direct supplier channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Portfolio Buildout | Captures arbitrage from divergent FAA NextGen and EASA SESAR implementation timelines. |
| Synthetic Vision Technology Licensing | Accelerates terrain-rendering capability deployment for regional airlines in mountainous terrain. |
| Direct-to-Operator Channel Expansion | Bypasses OEM intermediation to serve unbundled procurement patterns among low-cost carriers. |
| Backward Integration into Display Manufacturing | Secures supply of sunlight-readable OLED panels from concentrated South Korean and Taiwanese sources. |
| Software-Defined Architecture Migration | Enables over-the-air flight deck updates displacing physical component replacement cycles. |
Methodological Framework
Operator-level perspectives from fleet maintenance directors, avionics procurement managers, MRO facility operators, and regulatory certification engineers anchored the qualitative base. Primary interviews combined with secondary validation from FAA airworthiness directives, EASA certification databases, ARINC standards documentation, and OEM delivery schedules. Bottom-up triangulation across retrofit program pipelines and top-down reconciliation against fleet age demographics established volume estimates.
Scenario-bracketing framed projections across regulatory implementation timelines, technology adoption curves, and supply chain constraint scenarios. The analytical framework modeled technology, end user, application, and component segmentation dimensions over the projection horizon. CAGRs derived from fitted growth curves against equipage mandate deadlines and fleet replacement cycles, with synthetic vision penetration rates and software-defined architecture adoption as industry-specific forecast inputs.
Stress conditions across FAA-EASA harmonization gaps, display panel supply disruptions, and military procurement priority shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory deadline adherence and supplier qualification timelines. Quarterly review of airline unbundling rates, dual-approval certification filings, and South Korean-Taiwanese display manufacturing utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market