
 Cockpit Module Market | 2026-2036
Cockpit Module Market Size, Share, and Industry Trends Forecast 2026-2036
Cockpit Module Market Analysis
Software-defined vehicle architecture is reshaping cockpit module development from discrete hardware assemblies into continuously upgradable digital platforms. Visteon Corporation leverages its domain controller expertise to consolidate instrument cluster and infotainment functions onto single silicon. Panasonic Holdings Corporation anchors high-resolution display supply for premium OEM programs across multiple continents. Continental AG competes through its integrated software stack that spans operating systems to human-machine interface layers.
A cockpit module constitutes the driver-facing assembly combining instrument clusters, center stack interfaces, head-up displays, and associated control electronics into a unified operating environment, typically integrating multiple display surfaces with processing units capable of rendering real-time vehicle data, navigation, and multimedia content at resolutions exceeding 4K while meeting automotive temperature cycling standards from minus forty to eighty-five degrees Celsius. Digital cockpit configurations command the dominant share of engineering investment as OEMs eliminate mechanical gauges entirely. Head-up display adoption accelerates fastest among technology segments as augmented reality overlays migrate from luxury to mass-market vehicle platforms. Center stack modules retain mature margin pools but face pressure from voice recognition and artificial intelligence interfaces that reduce physical button counts and redistribute value toward software licensing.
NHTSA distraction guidelines, Euro NCAP assessment protocols, and ECE R79 steering equipment regulations collectively mandate eye-glance time limits and haptic feedback standards that dictate cockpit module interface architecture. OEMs must certify systems against these overlapping frameworks before securing type approval for vehicle programs. Stakeholders should monitor how artificial intelligence integration clauses in emerging regulatory drafts reshape liability allocation between module suppliers and vehicle manufacturers.
Market Dynamics
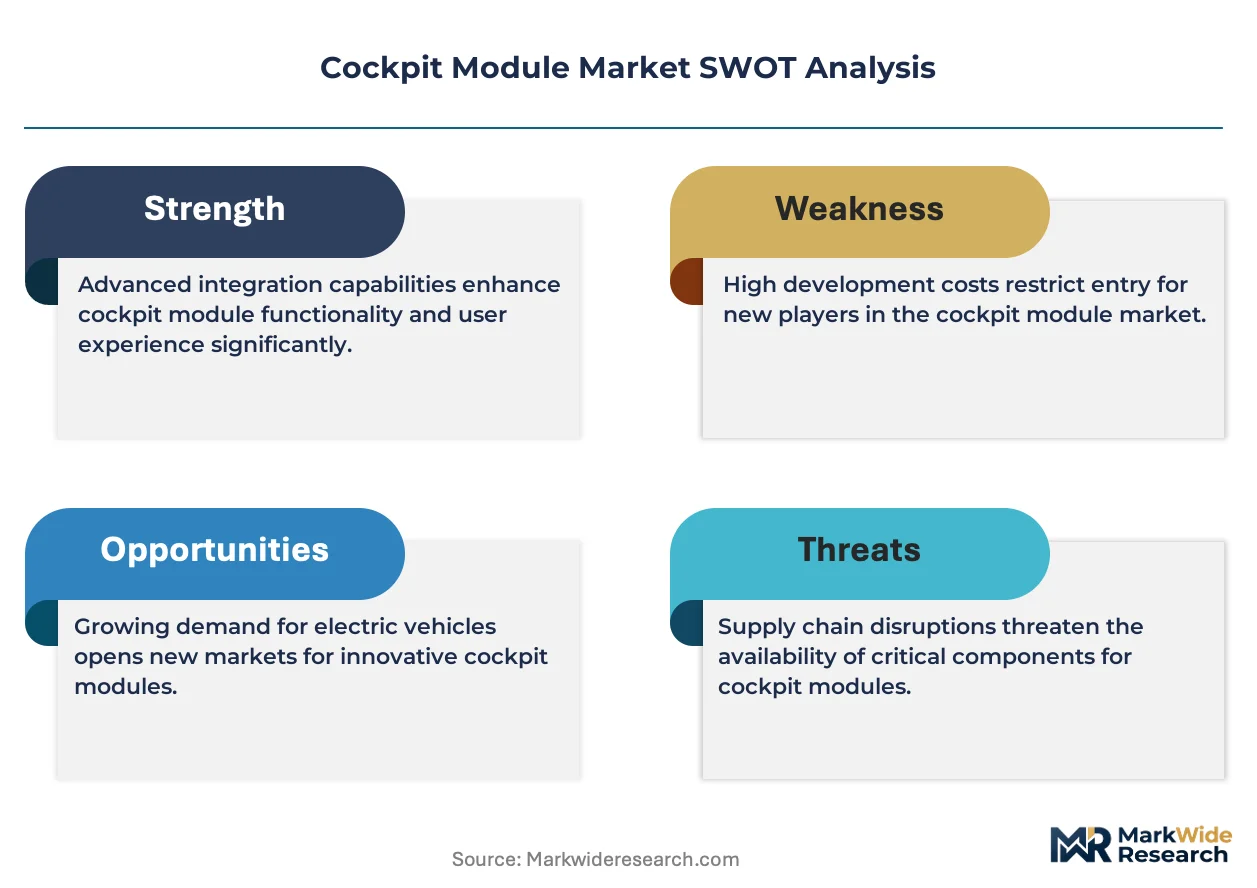
Software-defined vehicle architecture is compressing hardware refresh cycles from seven years to eighteen months, forcing tier-one suppliers to restructure engineering teams around continuous integration pipelines rather than discrete program launches.
Growth Catalysts
- EU AI Act compliance requirements:Mandates for explainable human-machine interfaces are accelerating investment in contextual awareness algorithms that reduce driver cognitive load during complex maneuvers.
- Electric vehicle platform proliferation:Battery-electric architectures eliminate mechanical gauge clusters entirely, creating mandatory upgrade paths to fully digital cockpit configurations across all price tiers.
- Head-up display optical waveguide maturation:Advances in holographic combiner technology from Germany and Japan are collapsing cost curves for augmented reality projection surfaces.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance system SoC fabrication depends on a single Taiwanese foundry node, creating vulnerability to geopolitical disruption or capacity constraints.
- Automotive-grade OLED yield limitations:Temperature cycling requirements from minus forty to eighty-five degrees Celsius restrict viable display suppliers to three qualified panel manufacturers.
- ECE R79 steering interface certification:Haptic feedback latency thresholds add fourteen to eighteen months to type-approval timelines for integrated cockpit-steering systems.
Strategic Opportunities
- India domestic production incentives:PLI scheme subsidies for automotive electronics manufacturing are attracting module assembly investments to serve emerging OEM engineering centers in Chennai and Pune.
- Over-the-air monetization infrastructure:Subscription-enabled feature activation creates recurring revenue streams from hardware already deployed in vehicle fleets.
- Biometric driver identification convergence:Integration of iris recognition with seat-position memory and climate preferences enables personalized cockpit environments without manual profile selection.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among a limited pool of specialists, inflating compensation and extending hiring timelines.
- Legacy CAN bus integration complexity:New domain controllers must maintain backward compatibility with decade-old vehicle networks while delivering real-time 4K rendering performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cockpit Module Market |
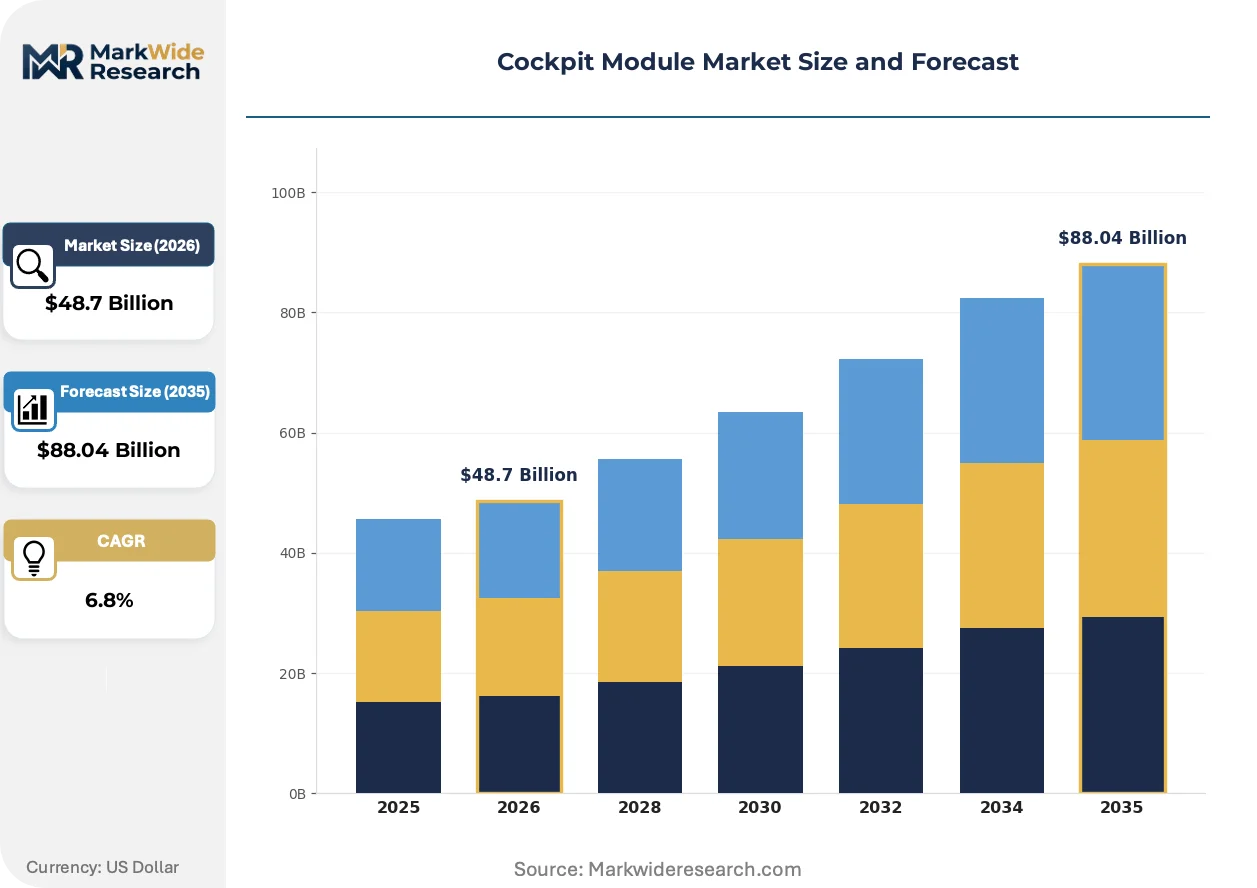
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Cockpit, Instrument Cluster, Head-Up Display, Center Stack Technology: Display Technology, Touchscreen, Voice Recognition, Artificial Intelligence End User: OEMs, Aftermarket Providers, Fleet Operators, Automotive Manufacturers Installation: Integrated, Standalone, Modular, Retrofit |
| Companies Covered | Visteon Corporation, Panasonic Holdings Corporation, Robert Bosch GmbH, Alps Alpine Co., Ltd., Samsung Electronics, Continental AG, Hyundai Mobis, Magna International, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cockpit Module Market Emerging Trajectories
Active matrix organic light-emitting diode technology is penetrating instrument cluster applications previously reserved for thin-film transistor liquid crystal displays, driven by contrast ratio requirements for augmented reality readiness.
Micro-LED backlighting is rendering obsolete edge-lit liquid crystal display architectures in premium vehicle programs. Mercedes-Benz and BMW have committed to miniaturized chip-on-board configurations for their flagship electric sedans launching in 2026. The technology enables localized dimming zones exceeding ten thousand segments, compressing power consumption by forty percent while eliminating halo artifacts around instrument needles.
NHTSA updated distraction guidelines now mandate eye-glance time limits of two seconds for secondary tasks, forcing interface designers to consolidate multi-step menu navigation into single-gesture controls. Tier-one suppliers are restructuring human-machine interaction teams around cognitive load testing protocols. German OEMs have accelerated adoption of predictive touch surfaces that activate functions before finger contact to comply with the reduced interaction windows.
Fleet procurement departments are consolidating cockpit module sourcing under single-supplier frameworks that bundle hardware, software licensing, and over-the-air update infrastructure. Rental and ride-hail operators in the United States are leading this consolidation, prioritizing standardized interfaces that reduce driver training costs across mixed-vehicle fleets. The shift displaces traditional multi-vendor component sourcing that separated display procurement from computing hardware.
Cockpit Module Market Segmentation
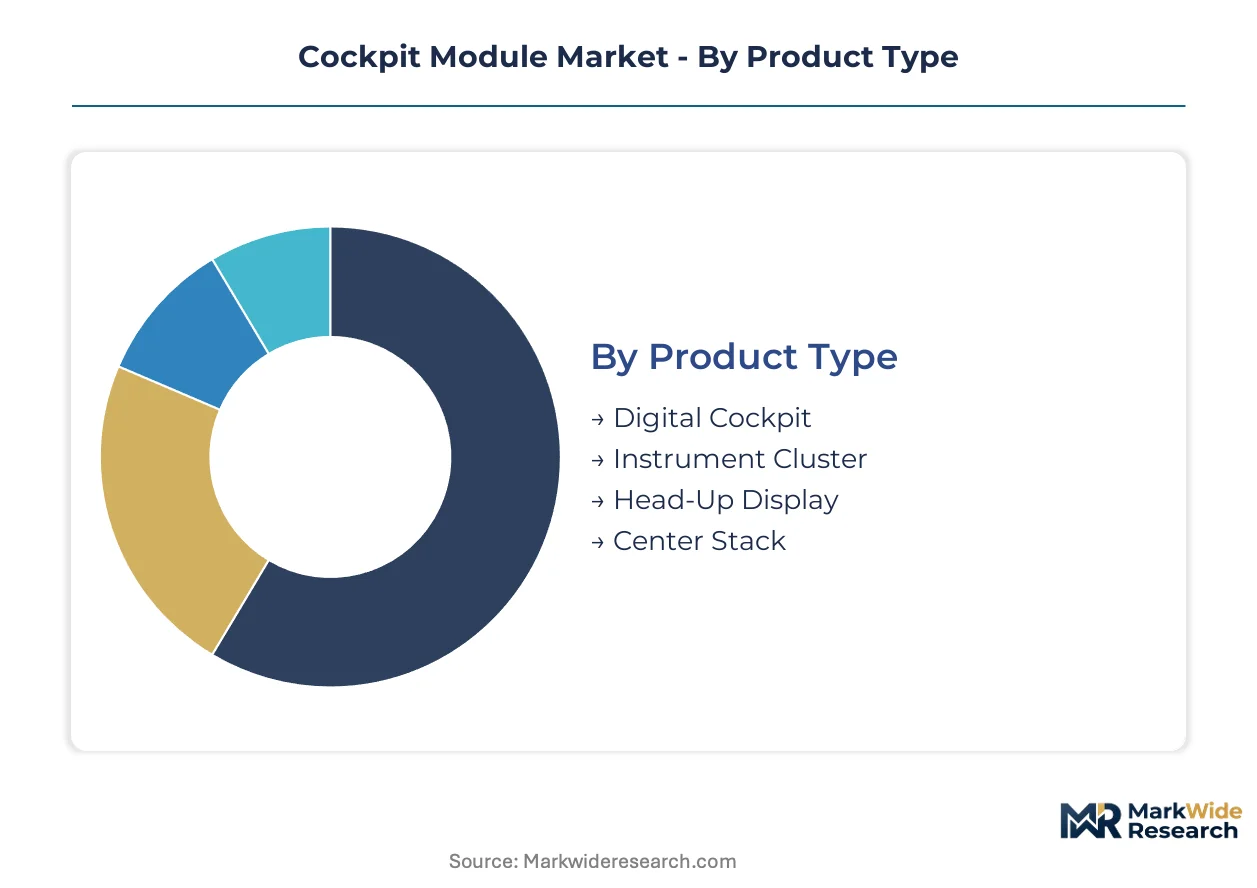
Cockpit module procurement patterns diverge sharply between vehicle programs requiring continuous software support and those with fixed lifecycle specifications. Segmentation reveals how supplier economics shift across hardware-only transactions versus recurring service engagements.
Product Type:
After-sales service intensity varies dramatically across cockpit configurations, with software-enabled systems demanding multi-year update commitments while mechanical assemblies require minimal ongoing support.
- Digital Cockpit:Unified display architecture consolidating instrument clusters, infotainment, and climate controls onto single-domain controllers with over-the-air update capability. Demand concentrates among German and US electric vehicle platforms where Mercedes-Benz and Tesla have eliminated physical gauges entirely; regulatory pressure from NHTSA eye-glance time limits accelerates interface consolidation.
- Head-Up Display:Windshield-projection systems rendering vehicle speed, navigation, and augmented reality overlays within driver line-of-sight. Japanese OEMs in Toyota City and German engineering centers in Stuttgart are driving waveguide cost reduction; EU AI Act explainability mandates favor contextual awareness algorithms that reduce cognitive load.
- Instrument Cluster:Driver-facing information displays transitioning from analog gauges to thin-film transistor and active matrix organic light-emitting diode configurations. Legacy internal combustion vehicle programs in Detroit retain this as standard equipment.
- Center Stack:Center-console-mounted interfaces housing infotainment, climate, and secondary vehicle controls. Volume production persists in mass-market segments though physical button counts decline under voice recognition displacement.
Digital Cockpit holds the largest share; momentum sits with Head-Up Display.
Technology:
Cost tier stratification separates premium sensor fusion architectures from commodity display controllers, with mid-range solutions capturing fleet standardization contracts.
- Display Technology:Thin-film transistor liquid crystal, active matrix organic light-emitting diode, and emerging micro-LED backlighting systems rendering instrument and infotainment content. Automotive-grade organic light-emitting diode yield limitations restrict qualified suppliers to Korean and Japanese panel manufacturers serving Stuttgart and Munich flagship programs.
- Artificial Intelligence:Contextual awareness algorithms predicting driver intent and automating interface responses. EU AI Act compliance requirements are accelerating investment among German tier-one suppliers seeking explainable human-machine interface certification.
- Touchscreen:Capacitive and resistive surface technologies enabling direct manual input. NHTSA two-second eye-glance limits are forcing consolidation of multi-step navigation into single-gesture controls.
- Voice Recognition:Natural language processing systems executing commands without visual distraction. Fleet operators in the United States prioritize standardized voice interfaces across mixed-vehicle procurement.
Display Technology commands current procurement volumes; Artificial Intelligence is climbing the fastest.
End User:
Customer type determines contract structure, with fleet operators demanding unified sourcing frameworks while aftermarket channels fragment across installation networks.
- OEMs:Original equipment manufacturers integrating cockpit modules during vehicle assembly. Engineering co-location with tier-one suppliers in Germany, Japan, and the United States dominates development resource allocation.
- Fleet Operators:Rental and ride-hail procurement departments consolidating sourcing under single-supplier bundles. US-based operators lead this shift to reduce driver training costs across mixed fleets.
- Automotive Manufacturers:Captive production divisions assembling modules for affiliated vehicle brands. Integration complexity with legacy controller area network bus architectures extends type-approval timelines.
- Aftermarket Providers:Independent distributors serving vehicle modification and repair channels. Retrofit certification requirements vary by national type-approval frameworks.
OEMs retain dominant procurement volume; Fleet Operators are gaining share fastest.
Installation:
Supply concentration favors integrated architectures where domain controller consolidation reduces wiring harness complexity and assembly labor.
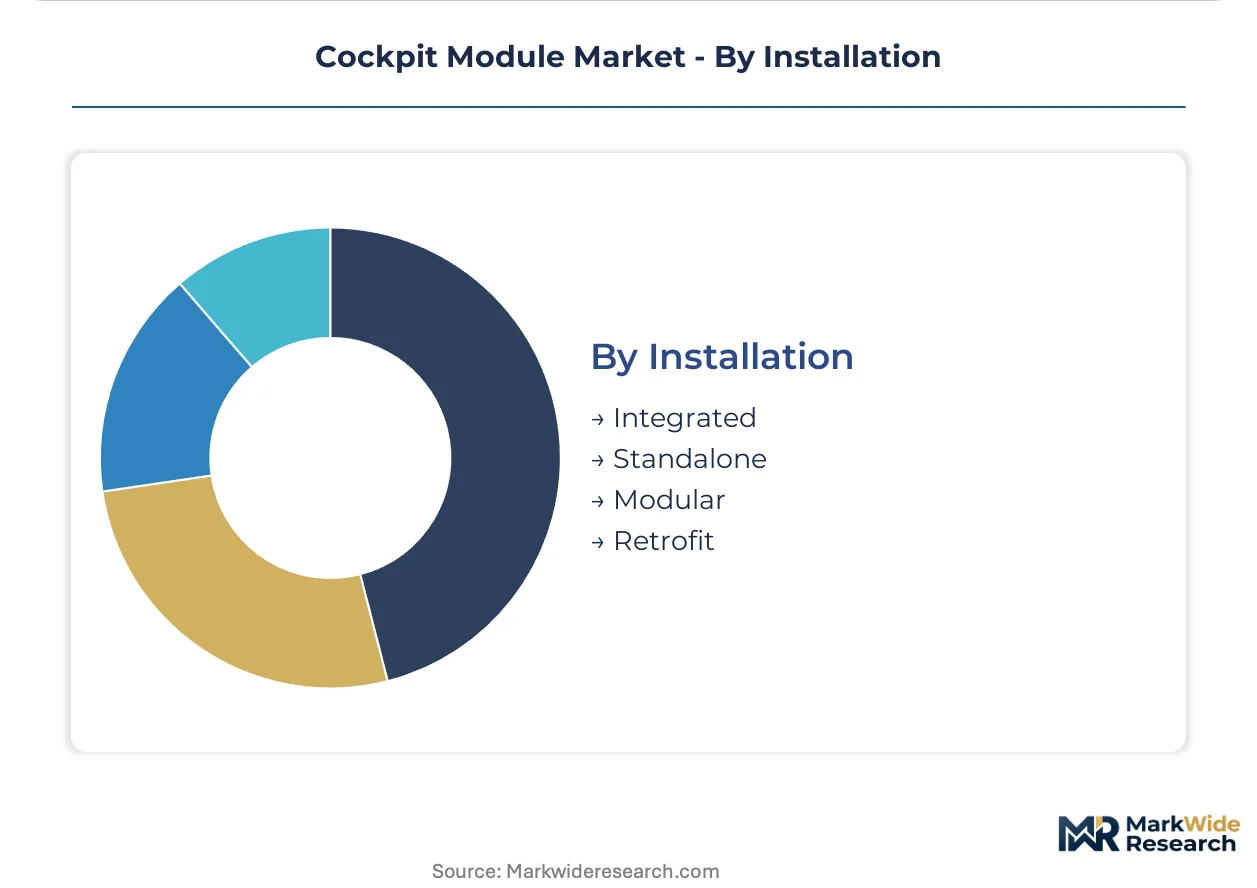
- Integrated:Cockpit modules factory-installed as unified assemblies with consolidated computing and display hardware. Electric vehicle platform proliferation in Germany and California is mandating this configuration across all price tiers.
- Modular:Separable display and controller units enabling tiered feature packaging. Japanese OEMs utilize this architecture to differentiate trim levels without complete hardware redesign.
- Standalone:Discrete component replacement addressing individual failure modes. Aftermarket channels in the United States maintain inventory for legacy vehicle support.
- Retrofit:Post-assembly installation upgrading older vehicles with digital interfaces. India's domestic production incentives are attracting module assembly investments serving Chennai and Pune engineering centers.
Integrated configurations dominate engineering investment; Modular approaches retain flexibility advantages in multi-trim programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports cockpit module engineering services and domain controller hardware to premium OEM assembly plants across the United States and China. Japanese suppliers ship head-up display optical waveguides to German and US engineering centers. South Korean panel manufacturers supply automotive-grade OLED substrates to Stuttgart and Munich flagship programs.
United States
NHTSA eye-glance time limits of two seconds for secondary tasks are forcing interface consolidation into single-gesture controls. The IRA domestic content provisions are accelerating local assembly investments for electric vehicle platforms. Michigan and California engineering clusters in Detroit and Silicon Valley are co-locating tier-one supplier development teams with OEM headquarters.
Germany
EU AI Act explainability mandates for human-machine interfaces are accelerating investment in contextual awareness algorithms. ECE R79 steering equipment regulations dictate haptic feedback latency thresholds that extend type-approval timelines. Stuttgart and Munich engineering centers are driving waveguide cost reduction for augmented reality head-up displays.
Japan
Toyota City engineering clusters are advancing holographic combiner technology for mass-market augmented reality projection surfaces. METI technology roadmaps support domestic display panel manufacturing for automotive applications. Alps Alpine and Denso engineering facilities in Nagoya and Tokyo are consolidating instrument cluster and infotainment functions onto single-domain controllers.
China
Dual carbon goals are mandating fully digital cockpit configurations across battery-electric vehicle platforms at all price tiers. MIIT standards for intelligent connected vehicles are tightening integration requirements for domain controller architectures. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou are attracting module assembly investments for both domestic OEMs and export programs.
India
PLI scheme subsidies for automotive electronics manufacturing are attracting module assembly investments to serve emerging OEM engineering centers. BIS certification requirements for automotive components are structuring supplier qualification timelines. Chennai and Pune industrial corridors are developing captive production capacity for integrated cockpit configurations serving domestic and export markets.
Cockpit Module Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates around domain controller consolidation capabilities and display supply security, with premium-tier procurement favoring integrated software-hardware bundles. Three archetypes dominate: silicon-to-system integrators owning full stack control, display panel specialists supplying high-resolution substrates, and domain controller architects consolidating multiple cockpit functions. Competitive moves center on backward integration into semiconductor sourcing and strategic partnerships for over-the-air update infrastructure.
Among German-based integrators, Continental AG and Robert Bosch GmbH exemplify the full-stack archetype spanning operating systems to human-machine interface layers. Visteon Corporation represents the domain controller consolidation model, leveraging silicon expertise to merge instrument cluster and infotainment functions. Panasonic Holdings Corporation anchors the display supply tier, occupying a position across multiple continental premium OEM programs.
| Leading Market Players |
|---|
| Visteon Corporation |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| Alps Alpine Co., Ltd. |
| Samsung Electronics |
| Continental AG |
| Hyundai Mobis |
| Magna International |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry concentration for advanced driver-assistance system SoC fabrication concentrates margin capture upstream, forcing tier-one suppliers to absorb cost volatility while OEMs negotiate fixed-price multi-year contracts for domain controller hardware.
Pricing Analysis
Next-generation micro-LED backlighting commands substantial premiums over edge-lit liquid crystal configurations, while prior-generation thin-film transistor panels face commoditization pressure. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from fleet procurement consolidation demanding bundled hardware-software-service contracts. Mass-market OEMs exhibit highest price sensitivity; luxury German marques prioritize performance specifications over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for display panel sourcing. Taiwan, South Korea, and Japan anchor semiconductor fabrication and optical component supply. Automotive-grade OLED substrates and holographic waveguides represent critical input dependencies. Single-source vulnerability concentrates in Taiwanese foundry nodes for domain controller silicon. Distribution runs through tier-one supplier engineering co-location with OEM headquarters in Germany, Japan, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architecture is compressing hardware refresh cycles from seven years to eighteen months, creating a high-growth disruption window where regulatory mandates from NHTSA and the EU AI Act accelerate technology turnover.
For Market Incumbents: Harden supply security through backward integration into semiconductor sourcing and captive production of automotive-grade OLED panels. ISO 26262 ASIL-D certification expertise scarcity threatens engineering capacity expansion timelines. Domain controller consolidation capabilities must expand to match electric vehicle platform proliferation across all price tiers. For New Entrants and Emerging Players: Build out aftermarket retrofit capabilities serving India's Chennai and Pune engineering centers where PLI scheme subsidies reduce capital barriers. Fleet operator procurement consolidation in the United States represents the most penetrable demand segment. Voice recognition and artificial intelligence interface licensing offers a software-centric go-to-market angle avoiding capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Capital is best deployed toward domain controller architects with demonstrated software-hardware integration capabilities and established OEM co-location relationships. The five-to-ten year viability window favors suppliers positioned for over-the-air monetization infrastructure deployment. Watch for artificial intelligence integration clauses in emerging regulatory drafts as the signal indicating liability allocation shifts between module suppliers and vehicle manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Consolidates instrument cluster and infotainment functions onto single silicon platforms for continuous upgradeability. |
| Battery Supply Agreement | Secures domain controller allocation for electric vehicle platforms eliminating mechanical gauge clusters entirely. |
| Geographic Manufacturing Footprint | Establishes module assembly in India to serve PLI-subsidized domestic production and export programs. |
| Platform Standardization | Reduces driver training costs for US fleet operators consolidating mixed-vehicle procurement under single-supplier frameworks. |
| Charging Infrastructure Partnership | Integrates cockpit modules with vehicle-to-grid communication interfaces for energy management display overlays. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations specialists and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive electronics suppliers, and NHTSA regulatory dockets. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators established volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from installed base evolution and technology substitution curves incorporating electric vehicle platform proliferation rates and regulatory mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon-to-system integrators pursuing full-stack control would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Cockpit Display Market