
 Cockpit Display Market | 2026-2036
Cockpit Display Market Size, Share, and Industry Trends Forecast 2026-2036
Cockpit Display Market Analysis
South Korea is reconfiguring regional supply dynamics through concentrated LCD and OLED panel capacity expansion for aerospace-qualified displays. Garmin Ltd leverages vertical integration from sensor modules to fully integrated flight decks, sustaining its position in general and commercial aviation retrofit markets. Thales Group anchors European defense and civil programs through sovereign manufacturing lines in France, while Collins Aerospace competes on integrated avionics architectures that span displays, processors, and software stacks.
A cockpit display comprises an electronic visual interface presenting flight, navigation, engine, and systems data to flight crew, typically built around active-matrix LCD or OLED panels with luminance exceeding 1000 cd/m² for sunlight readability and operating temperatures from -40°C to +70°C. Its primary purpose replaces electromechanical instruments with consolidated, reconfigurable information surfaces that reduce pilot workload and enable advanced functions like synthetic vision. Multifunction displays now dominate new installations by consolidating previously separate instruments into configurable screen zones, while OLED technology captures the fastest expansion trajectory due to superior contrast ratios and reduced power draw critical for extended missions. Commercial aviation generates the largest revenue pool among end users, though military aviation commands premium pricing through hardened specifications and security requirements.
FAA Technical Standard Orders govern display optical performance and environmental qualification for US-certified aircraft, while EASA CS-AWF and EU AI Act provisions increasingly shape human-machine interface requirements for European-registered fleets. China's NMPA and MIIT enforce local certification pathways that condition market access for foreign suppliers serving indigenous commercial programs. Stakeholders must monitor divergence between FAA and EASA certification timelines for synthetic vision standards, as asynchronous adoption could fragment product development roadmaps and qualification investments.
Market Dynamics
The transition from cathode-ray tube to solid-state glass cockpit configurations constitutes the dominant structural force, as FAA mandates for synthetic vision and terrain awareness systems compel fleet-wide display upgrades across commercial and defense aviation platforms.
Growth Catalysts
- FAA Certification Mandates:Synthetic vision system requirements under FAA Technical Standard Orders are accelerating replacement cycles for legacy cockpit instrumentation in US-registered commercial fleets.
- OLED Panel Technology:Superior contrast ratios and reduced power consumption in active-matrix OLED configurations are displacing LCD dominance in extended-duration military missions.
- South Korean Display Capacity:Concentrated aerospace-qualified LCD and OLED manufacturing expansion in Gumi and Tangjeong clusters is compressing lead times for avionics integrators.
Market Restraints
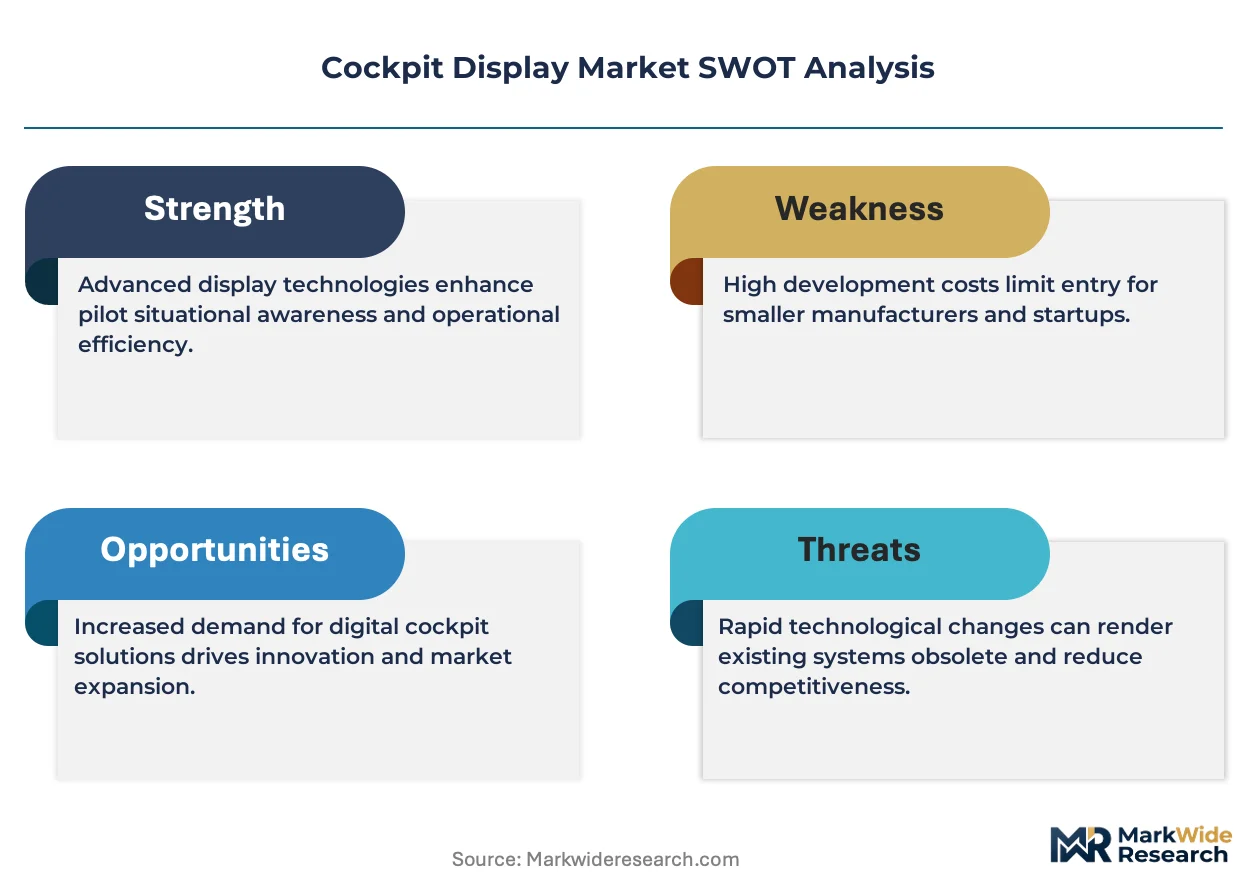
- Indium Supply Concentration:Indium tin oxide deposition for transparent conductive layers faces price volatility tied to Chinese smelter output and geopolitical trade friction.
- Dual Certification Burden:Asynchronous FAA and EASA synthetic vision standard timelines are fragmenting product development roadmaps and duplicating qualification investments.
- MicroLED Manufacturing Yields:Sub-50% yields in gallium nitride epitaxy for microLED emitters are constraining volume scaling for next-generation head-up display applications.
Strategic Opportunities
- Urban Air Mobility:Electric vertical take-off and landing platforms require compact, high-brightness displays for congested airspace navigation in emerging metropolitan networks.
- EU AI Act Compliance:Human-machine interface transparency requirements for European-registered fleets are creating specification premiums for explainable flight deck architectures.
- Retrofit Channel Expansion:Independent maintenance, repair, and overhaul facilities are capturing display upgrade volumes outside OEM-controlled service networks.
Industry Challenges
- EMI Certification Bottlenecks:DO-160G Section 21 conducted susceptibility testing for high-speed digital video interfaces is extending qualification timelines by 8-14 months for new display designs.
- Legacy ARINC 429 Integration:Analog-era data bus architectures in aging Boeing 737NG and Airbus A320ceo fleets require costly protocol bridge hardware for modern display connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cockpit Display Market |
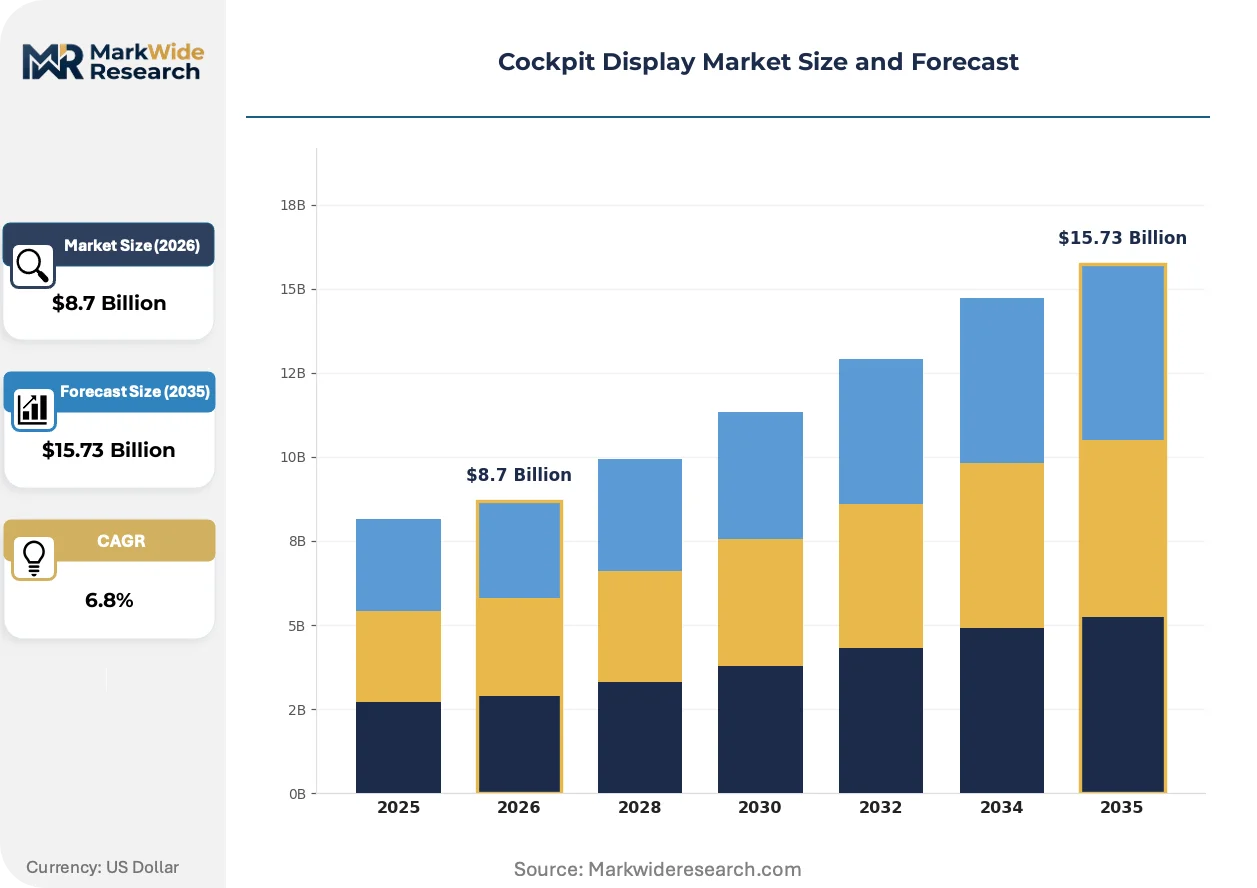
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
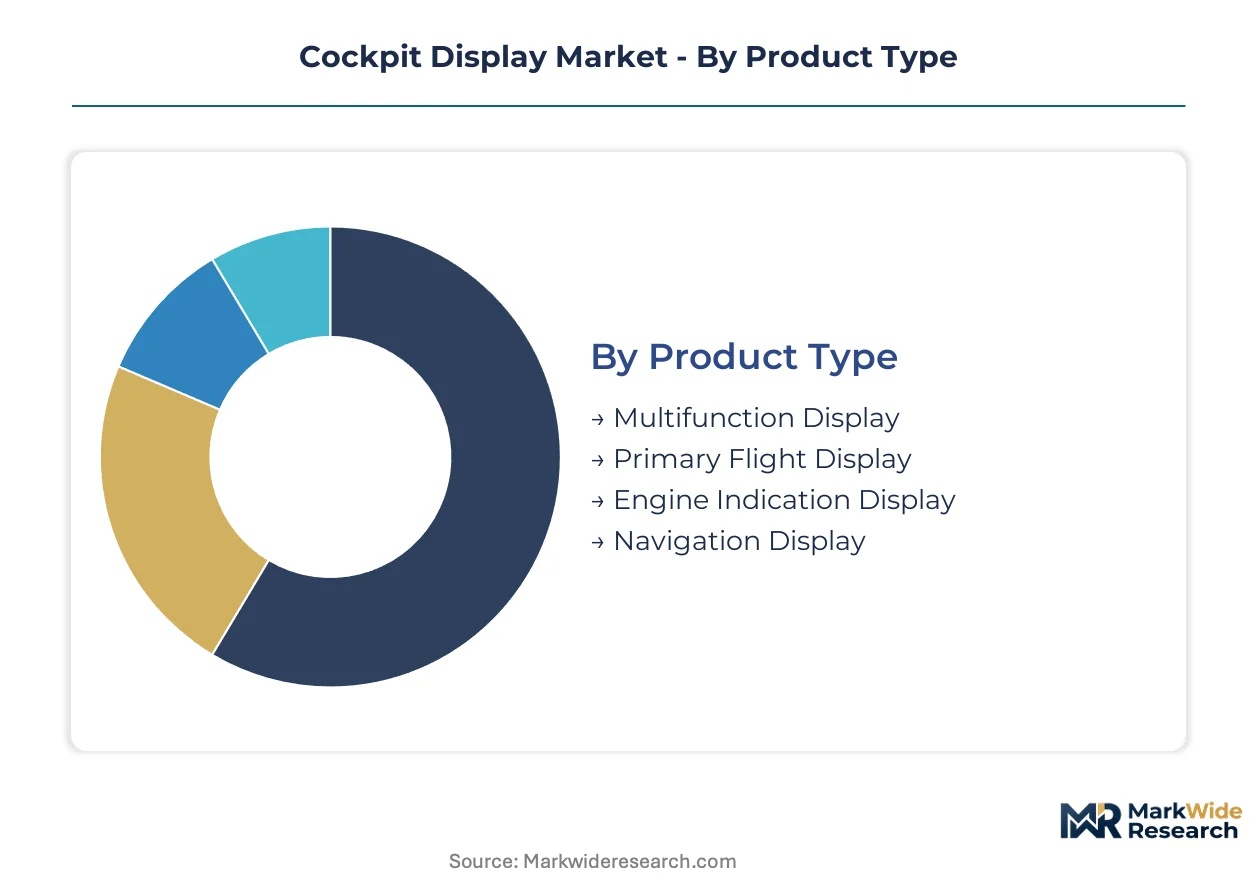
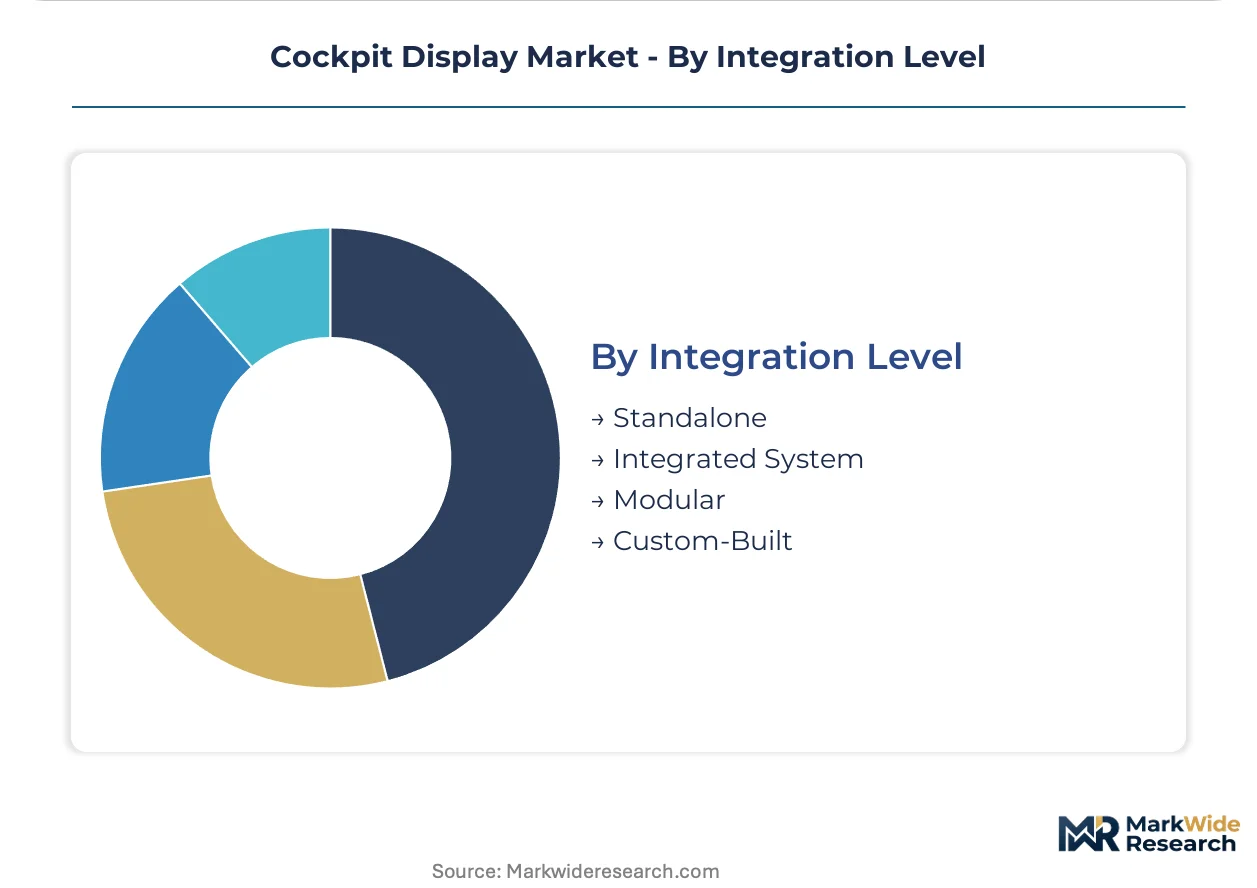
| Segmentation | Product Type: Multifunction Display, Primary Flight Display, Engine Indication Display, Navigation Display Technology: LCD, OLED, LED, Projection End User: Commercial Aviation, Military Aviation, General Aviation, Space Exploration Integration Level: Standalone, Integrated System, Modular, Custom-Built |
| Companies Covered | Garmin Ltd, Thales Group, Collins Aerospace, Innolux Corporation, AU Optronics Corp, Continental AG, Elbit Systems, Japan Display Inc, Honeywell Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cockpit Display Market Emerging Trajectories
Display architecture consolidation and regulatory harmonization pressures are compressing traditional supplier margins while opening white space for vertically integrated flight deck providers. Three developments are reshaping competitive positioning.
OLED technology is collapsing the distinction between day and night vision-optimized displays through self-emissive pixel control that eliminates backlight bleed. Military avionics programs in the United States and NATO member states are adopting multi-spectral compatible OLED configurations for helmet-mounted cueing systems. This convergence is compressing the addressable market for legacy AMLCD suppliers dependent on dual-mode backlight architectures.
EASA CS-AWF airworthiness framework revisions are mandating human factors validation for reconfigurable display formats in European commercial operations. The regulation requires empirical evidence that pilot workload does not increase during automated mode transitions. Flight deck integrators serving Lufthansa, Air France-KLM, and International Airlines Group are front-loading cognitive engineering investments to secure type certificate amendments.
Airline technical procurement departments are unbundling display hardware from integrated avionics suites, selecting panel suppliers independently of flight management system vendors. This disintermediation is visible most acutely in Southeast Asian low-cost carrier fleets, where Cebu Pacific and VietJet Air are sourcing sunlight-readable LCDs through direct OEM relationships rather than through Collins Aerospace or Thales system bundles.
Cockpit Display Market Segmentation
Cockpit display procurement patterns diverge sharply across aircraft categories, certification tiers, and technology readiness levels. Understanding these fault lines clarifies where specification premiums concentrate and where commoditization pressures dominate.
Product Type:
Flight deck configurations range from consolidated multifunction surfaces to dedicated single-purpose instruments, with integration depth dictating hardware margins and software recurring revenue.
- Multifunction Display:Consolidated screen zones replace previously separate instruments through reconfigurable pixel arrays, enabling synthetic vision and terrain overlays on demand. Commercial aviation fleets in the United States and European Union drive procurement volumes as FAA and EASA mandates compel glass cockpit retrofits.
- Primary Flight Display:Attitude, altitude, and airspeed data render on sunlight-readable panels exceeding 1000 cd/m² luminance, with dual-redundant architectures required for Part 25 certification. Military aviation programs specify hardened variants with night-vision goggle compatibility and electromagnetic pulse resilience.
- Engine Indication Display:Powerplant parameters consolidate on dedicated surfaces in legacy aircraft lacking full glass integration.
- Navigation Display:Moving-map symbology and flight plan depiction concentrate demand in regional jet and business aviation retrofits.
Established volume favors multifunction configurations; emerging adoption favors dedicated primary flight displays in urban air mobility platforms.
Technology:
Panel chemistry determines power budgets, thermal envelopes, and viewing angle performance across mission profiles from short-haul commercial to extended-duration military sorties.
- LCD:Active-matrix liquid crystal configurations with LED backlighting dominate installed base economics, leveraging mature supply chains in South Korean manufacturing clusters. Sunlight readability requirements in general aviation and commercial retrofit channels sustain demand despite OLED encroachment.
- OLED:Self-emissive organic diode architectures eliminate backlight bleed entirely, delivering superior contrast ratios critical for helmet-mounted cueing and night operations. NATO military avionics programs and extended-range unmanned platforms represent the steepest expansion trajectory.
- LED:Direct-view emissive tiles address niche applications in large-format head-up display projection engines.
- Projection:Micro-mirror and laser-phosphor systems persist in head-up display applications where combiner optics require distant virtual image formation.
Cost-sensitive procurement favors LCD; performance-optimized specifications favor OLED.
End User:
Customer archetypes span regulated commercial operators, sovereign defense procurement, owner-flown general aviation, and emerging space launch segments with divergent certification burdens.
- Commercial Aviation:Part 121 carriers and regional operators generate the largest absolute revenue pool, with fleet-wide retrofit cycles triggered by FAA airworthiness directives and EASA CS-AWF amendments. Synthetic vision mandates and terrain awareness requirements tighten display performance specifications progressively.
- Military Aviation:Hardened specifications for electromagnetic interference resilience, secure data handling, and multi-spectral compatibility command substantial price premiums. United States Department of Defense and NATO member state procurement concentrates in sovereign manufacturing lines.
- General Aviation:Experimental and light-sport categories drive demand for portable and panel-mount displays outside Part 25 certification pathways.
- Space Exploration:Crewed capsule and launch vehicle applications require vacuum-compatible packaging and radiation-hardened electronics.
Volume concentration favors commercial aviation; margin capture favors military specifications.
Integration Level:
System architecture choices determine supplier bargaining power, with unbundling trends reshaping traditional avionics suite economics.
- Integrated System:Displays, processors, and software stacks from single vendors reduce interface complexity and streamline certification. Collins Aerospace and Thales Group anchor European and North American procurement through bundled flight deck offerings.
- Modular:Open architecture standards enable panel substitution independent of flight management system vendors. Southeast Asian low-cost carriers exploit this flexibility to source sunlight-readable displays through direct OEM relationships.
- Standalone:Single-function instruments persist in legacy aircraft with analog-era wiring harnesses.
- Custom-Built:Bespoke configurations address unique mission requirements in special-mission military platforms and experimental space vehicles.
OEM channel control favors integrated systems; aftermarket price pressure favors modular architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Technical Standard Orders anchor procurement cycles in the United States, where synthetic vision mandates and terrain awareness requirements drive fleet-wide display upgrades across commercial and defense aviation platforms.
United States
Major airframers and defense integrators concentrate demand for next-generation avionics suites. FAA certification mandates for synthetic vision systems tighten display performance specifications progressively. Wichita, Kansas and the Dallas-Fort Worth corridor host dense clusters of avionics integration facilities serving retrofit markets.
France
Sovereign manufacturing lines anchor European defense and civil programs through vertically integrated production. EASA CS-AWF airworthiness framework revisions mandate human factors validation for reconfigurable display formats. The Toulouse aerospace cluster sustains specialized supply chains for flight deck certification.
South Korea
Concentrated LCD and OLED panel capacity expansion reconfigures regional supply dynamics for aerospace-qualified displays. The country's national industrial regulator enforces local certification pathways conditioning market access. Gumi and Tangjeong manufacturing clusters compress lead times for avionics integrators.
China
Indigenous commercial programs drive demand for cockpit displays through state-backed aircraft development initiatives. NMPA and MIIT enforce local certification pathways that condition market access for foreign suppliers. The Yangtze River Delta concentrates panel manufacturing investment for aviation-grade specifications.
Germany
Lufthansa Group technical procurement departments front-load cognitive engineering investments for EASA type certificate amendments. EU AI Act provisions shape human-machine interface requirements for European-registered fleets. Bavaria hosts specialized engineering centers for flight deck architecture development.
Cockpit Display Market Vendor Landscape
Vertically integrated flight deck providers and specialized panel manufacturers split the market along certification depth and manufacturing scale. The vendor base concentrates in sovereign defense procurement channels and commercial aviation retrofit networks. Three archetypes dominate: avionics suite integrators controlling end-to-end flight deck architectures, display panel specialists supplying sunlight-readable and night-vision-compatible configurations, and sensor-to-screen vertically integrated providers capturing general aviation retrofit volumes. Competitive moves center on backward integration into aerospace-qualified panel manufacturing and strategic partnerships with urban air mobility platform developers.
Among avionics suite integrators, Thales Group and Collins Aerospace exemplify the bundled flight deck architecture archetype, while Garmin Ltd occupies a position within the sensor-to-screen vertical integration tier. These three anchors represent contrasting geographic origins and organizational structures: Thales Group as a French société anonyme, Collins Aerospace as a US-incorporated subsidiary structure, and Garmin Ltd as a Swiss-registered public limited company with operational headquarters in the United States.
| Leading Market Players |
|---|
| Garmin Ltd |
| Thales Group |
| Collins Aerospace |
| Innolux Corporation |
| AU Optronics Corp |
| Continental AG |
| Elbit Systems |
| Japan Display Inc |
| Honeywell Aerospace |
| Others |
Supply Flow & Price Mechanics
Indium supply concentration from Chinese smelter output determines both pricing tier spreads and supply chain shape in cockpit display manufacturing, compressing margins for transparent conductive layer deposition while forcing tiered procurement strategies across military and commercial aviation end users.
Pricing Analysis
North American procurement commands substantial premiums over Southeast Asian retrofit channels due to FAA certification burdens and synthetic vision mandate compliance. Three-tier pricing structure across military-grade hardened specifications, commercial Part 25 certified configurations, and general aviation portable units reflects certification depth and volume scale. Price differentiation stems from electromagnetic interference resilience requirements and night-vision goggle compatibility testing. Cost compression in general aviation LCD retrofits is intensifying because independent MRO facilities bypass OEM-controlled service networks.
Supply Chain Analysis
Extended payment terms from South Korean panel manufacturers compress working capital cycles for avionics integrators sourcing aerospace-qualified OLED substrates. Gumi and Tangjeong manufacturing clusters in South Korea, combined with Yangtze River Delta capacity in China and Toulouse-area sovereign lines in France, concentrate display panel supply. Indium tin oxide deposition draws from Chinese smelter output, gallium nitride epitaxy for microLED emitters rests on limited foundry capacity, and ARINC 429 protocol bridge hardware hinges on specialized semiconductor packaging. Single-source vulnerability in indium supply creates tariff exposure downstream. Distribution runs through OEM-authorized service networks and independent MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against emerging microLED head-up display architectures that threaten to displace established LCD and OLED panel suppliers in next-generation military avionics programs.
For Market Incumbents: Entrench synthetic vision certification leadership through accelerated FAA Technical Standard Order compliance investments that lock out unqualified competitors. Secure captive supply of aerospace-qualified OLED substrates through backward integration into South Korean manufacturing clusters or exclusive offtake agreements with Gumi and Tangjeong facilities. Consolidate position in integrated flight deck architectures before urban air mobility platforms fragment procurement into modular panel sourcing. For New Entrants and Emerging Players: Establish a beachhead in urban air mobility display segments where compact, high-brightness requirements favor specialized suppliers over bundled avionics suite incumbents. Target Southeast Asian low-cost carrier retrofit channels where Cebu Pacific and VietJet Air procurement patterns demonstrate openness to direct OEM relationships outside Collins Aerospace or Thales system bundles. Pursue EU AI Act compliance specialization as a go-to-market angle for European-registered fleet human-machine interface transparency requirements. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors vertically integrated sensor-to-screen providers over pure panel manufacturers. Long-term viability across the analysis window rests on securing positions in extended-range unmanned platforms and NATO military avionics programs where OLED specifications command durable premiums. Target acquisition archetypes include aerospace-qualified OLED substrate specialists with existing DO-160G Section 21 EMI certification and established South Korean supply relationships. Monitor asynchronous FAA and EASA synthetic vision standard adoption as the inflection indicator for qualification investment fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OLED Substrate Manufacturing | Captures margin from South Korean Gumi and Tangjeong supply clusters while compressing lead times for avionics integrators. |
| FAA Synthetic Vision Certification Acceleration | Locks out unqualified competitors as Technical Standard Order mandates tighten display performance specifications progressively. |
| Urban Air Mobility Platform Partnership | Positions suppliers for electric vertical take-off and landing display volumes in emerging metropolitan airspace networks. |
| EU AI Act Compliance Engineering Investment | Captures specification premiums from Lufthansa Group and Air France-KLM cognitive engineering requirements for EASA type certificate amendments. |
| Independent MRO Channel Expansion | Bypasses OEM-controlled service networks to capture general aviation and regional jet retrofit volumes outside bundled avionics suites. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with avionics integration engineers, flight deck procurement managers at Part 121 carriers, FAA certification specialists, and military program officers; and secondary validation against FAA Technical Standard Order filings, EASA CS-AWF amendment documentation, SEC 10-K disclosures from listed avionics suppliers, and customs records for aerospace-qualified panel imports. Bottom-up triangulation across segment-level procurement volumes and top-down reconciliation against fleet retrofit cycle data anchored the market sizing framework.
Forecast inputs considered aircraft delivery schedules, regulatory mandate effective dates, and technology substitution curves across the projection horizon. Segmentation dimensions modeled include display technology chemistry, integration architecture depth, end-user certification tier, and regional regulatory cluster. CAGRs were derived from fitted adoption curves for synthetic vision system penetration and OLED technology displacement rates. Industry-specific inputs encompassed DO-160G qualification timeline data and ARINC 429 protocol bridge hardware attachment rates in legacy fleet retrofits.
Stress conditions across indium price volatility, FAA-EASA standard timeline divergence, and microLED manufacturing yield recovery were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet upgrade cycle timing and regulatory enforcement intensity. Macroeconomic contraction, tariff escalation, or breakthrough microLED yield improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market