
 Aircraft Glareshield Lighting Market | 2026-2036
Aircraft Glareshield Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Glareshield Lighting Market Outlook
Multi-source procurement for cockpit illumination subsystems is realigning supplier relationships across the aerospace lighting value chain. Collins Aerospace leverages its integrated avionics platforms to bundle glareshield solutions with flight-deck upgrades. Honeywell International Inc. sustains dominance in adaptive dimming architectures through captive semiconductor sourcing. Diehl Stiftung anchors European supply with specialized manufacturing for both commercial and military cockpit programs.
Aircraft glareshield lighting denotes the integrated illumination systems installed on the instrument panel brow, typically employing LEDs with color temperatures between 2700K and 6500K and dimming ratios exceeding 1000:1 to preserve pilot night vision and reduce cognitive load during critical flight phases. LED product types occupy the majority of new-build installations given their luminous efficacy and mean-time-between-failure advantages over halogen and xenon alternatives. Smart control technology segments are expanding fastest, driven by integration with central aircraft maintenance systems and programmable scene presets for diverse operational conditions.
FAA Technical Standard Orders and EASA Certification Specifications govern photometric performance, electromagnetic interference, and environmental qualification for cockpit lighting equipment, creating compliance barriers for non-certified suppliers. The EU AI Act and emerging MEE efficiency directives in China are beginning to shape design requirements for intelligent, sensor-driven illumination systems. Stakeholders must monitor evolving night-vision goggle compatibility standards and decide whether to internalize spectral testing capabilities or rely on qualified third-party laboratories.
Market Dynamics
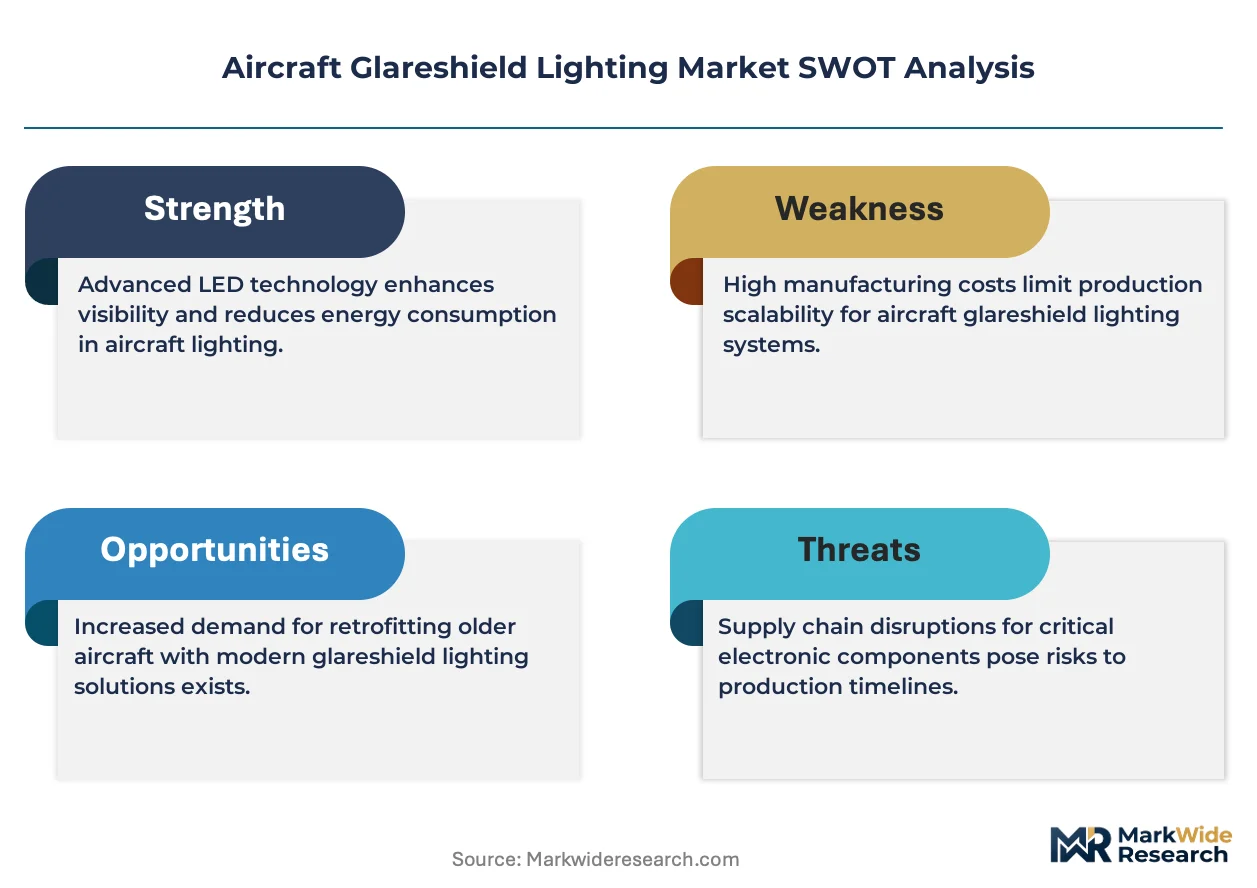
LED spectral engineering is compressing supplier margins while elevating performance thresholds, forcing incumbents to internalize semiconductor packaging and optical testing capabilities that previously resided with tier-two vendors.
Growth Catalysts
- FAA TSO-C113 certification mandates:Night-vision goggle compatibility requirements for Part 121 operators are accelerating replacement cycles across narrow-body retrofits.
- Silicon carbide substrates:Wider bandgap semiconductors enable higher switching frequencies in dimming controllers, reducing electromagnetic interference signatures below 100 kHz thresholds.
- United States manufacturing concentration:Proximity to Boeing and Gulfstream final assembly lines in Washington and Georgia reduces logistics costs for integrated cockpit upgrades.
Market Restraints
- Indium gallium nitride epitaxy costs:Blue LED die fabrication requires specialized metal-organic chemical vapor deposition reactors with 18-month lead times.
- Single-source phosphor supply:Cerium-doped yttrium aluminum garnet conversion materials concentrate with Japanese chemical processors, creating input vulnerability.
- EASA CS-25 electromagnetic compatibility testing:Extended qualification timelines for spectral flicker below 0.5% at 100 Hz delay platform certification by 8-14 months.
Strategic Opportunities
- Urban air mobility cockpits:Electric vertical take-off aircraft require compact, low-power illumination architectures absent in traditional transport categories.
- EU AI Act algorithmic transparency:Adaptive lighting systems with embedded machine vision for pilot gaze tracking gain preferential market access under emerging conformity assessment frameworks.
- Direct airline procurement channels:Delta, United, and American Airlines are consolidating subsystem purchasing through integrated flight-deck retrofit contracts, bypassing traditional OEM intermediaries.
Industry Challenges
- Optical metrology talent scarcity:Spectroradiometer operation and goniophotometer calibration require specialized technicians with photometric laboratory experience.
- Legacy 28VDC architecture integration:New solid-state drivers must interface with electromechanical dimming rheostats installed on pre-2010 airframes without airworthiness directive triggers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Glareshield Lighting Market |
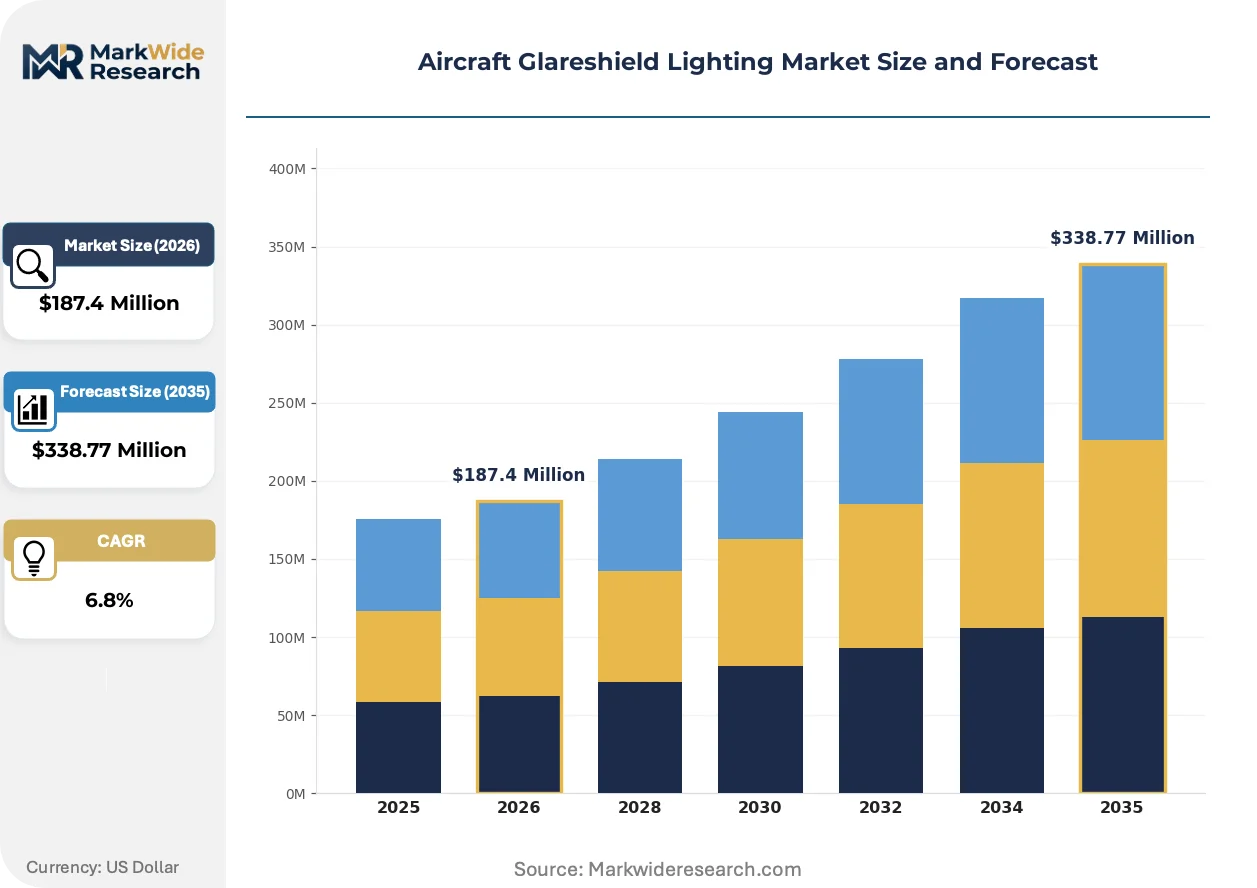
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Xenon, Halogen Technology: Direct Lighting, Indirect Lighting, Adaptive Lighting, Smart Control Installation: New Build, Retrofit, Upgrades, Maintenance End User: Commercial Aviation, Military Aviation, Private Jets, Helicopters |
| Companies Covered | Honeywell International Inc., Collins Aerospace, BAE Systems, Astronics Corporation, Cobham, STG Aerospace, Diehl Stiftung, Thales, Whelen Aerospace Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Glareshield Lighting Market Strategic Shifts
Spectral tunability and predictive maintenance integration are redefining how cockpit illumination systems interface with broader avionics architectures and airline operational technology stacks.
Multi-channel LED drivers with independent wavelength control are unifying red, green, and blue die outputs into single optical assemblies. Regional carriers and cargo operators are adopting these architectures for 737-800 and A320ceo retrofits at accelerating rates. This consolidation is unifying previously separate incandescent and electroluminescent supply chains into unified solid-state platforms.
EASA Certification Specification 25.812 and FAA AC 25-7C are tightening photobiological safety limits for blue-rich spectral outputs above 450 nanometers. Manufacturers must now submit extended retinal hazard analysis documentation alongside traditional electromagnetic qualification. European OEMs and their supply bases are responding by accelerating amber-dominant spectral recipes that reduce circadian disruption metrics.
Airlines are consolidating subsystem procurement through flight-deck modernization contracts rather than discrete component purchasing. Maintenance, repair, and overhaul facilities are displacing traditional distribution channels for line-replaceable unit sourcing. This concentration is most visible in United States-based carriers with captive engineering organizations capable of specifying integrated illumination-avionics packages.
Aircraft Glareshield Lighting Market Segmentation
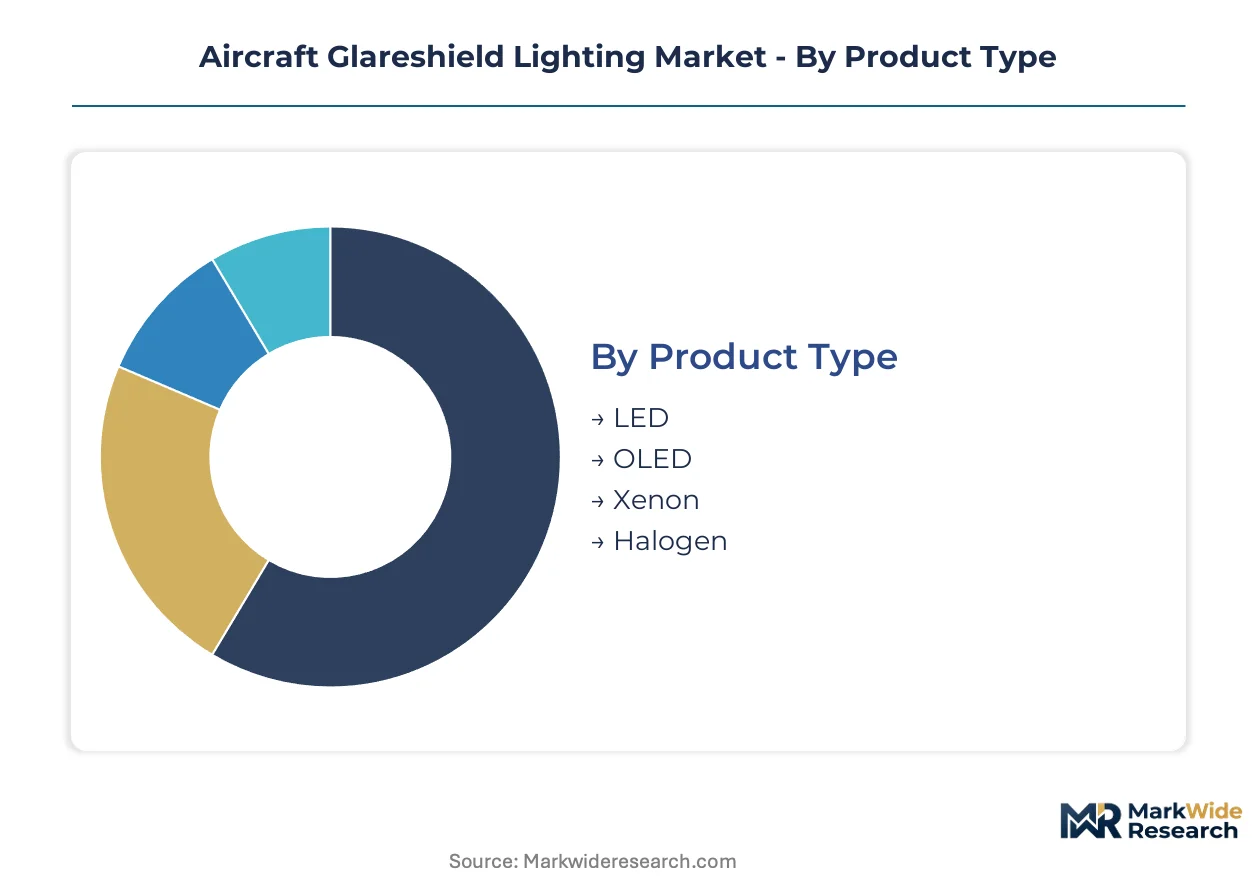
Glareshield lighting configurations diverge sharply between integrated cockpit architectures and standalone retrofits, with procurement patterns tracking fleet modernization cycles rather than uniform platform adoption. LED spectral engineering and adaptive dimming intelligence now sit at the center of vendor differentiation across every segment tier.
Product Type:
Integration depth varies dramatically: LED and OLED segments embed directly into glass-cockpit avionics suites, while xenon and halogen remain predominantly standalone replacements for legacy electromechanical systems.
- LED:Multi-die assemblies with independent red-green-blue channels achieve color temperatures from 2700K to 6500K and dimming ratios exceeding 1000:1. Demand concentrates in United States-based narrow-body retrofits where FAA TSO-C113 certification mandates night-vision goggle compatibility, compressing replacement timelines for Part 121 operators.
- OLED:Thin-film organic emissive layers deliver uniform surface illumination without secondary optics, enabling curved glareshield geometries in Gulfstream and Bombardier business jet programs. European OEMs are accelerating amber-dominant spectral recipes to meet EASA photobiological safety limits for blue-rich outputs above 450 nanometers.
- Xenon:High-intensity discharge architectures persist in select military transport categories where electromagnetic pulse hardening requirements exceed solid-state reliability margins.
- Halogen:Tungsten-halogen incandescence retains minimal footprint in pre-2010 airframes requiring 28VDC electromechanical dimming rheostat compatibility without airworthiness directive triggers.
Volume placements concentrate in LED; the faster expansion belongs to OLED.
Technology:
Cost stratification separates commodity illumination from intelligent systems, with adaptive and smart control architectures commanding premium positioning through predictive maintenance integration.
- Direct Lighting:Point-source LED arrays with dedicated collimating lenses provide task-specific instrument panel illumination. Commercial aviation fleets in the United States specify these architectures for 737-800 and A320ceo flight-deck modernizations where procurement runs through integrated retrofit contracts.
- Indirect Lighting:Edge-lit light-guide plates distribute uniform luminance across glareshield surfaces without visible point sources. Private jet completion centers in Georgia and Washington state favor these configurations for cabin aesthetic integration.
- Adaptive Lighting:Sensor-driven spectral tuning responds to ambient cockpit conditions and pilot gaze tracking. The EU AI Act algorithmic transparency requirements are reshaping competitive positioning for European market access.
- Smart Control:Embedded diagnostics and programmable scene presets interface with central aircraft maintenance systems. Military aviation programs are concentrating procurement here for reduced logistics burden in deployed operations.
Revenue concentrates in adaptive architectures; smart control is gaining share fastest.
Installation:
Customer type dictates channel structure: airline engineering organizations bypass OEM intermediaries for retrofit bundles, while new build flows through tier-one avionics integrators.
- New Build:Factory-installed illumination systems ship as integrated cockpit modules from Collins Aerospace and Honeywell production lines in Iowa and Arizona.
- Retrofit:Line-replaceable unit upgrades for in-service fleets concentrate in United States-based MRO facilities with captive engineering capabilities.
- Upgrades:Mid-life avionics refreshes bundle glareshield lighting with display and flight management system replacements.
- Maintenance:Spare part procurement for failed units runs through airline inventory pools rather than traditional distribution channels.
Procurement volume clusters in new build; retrofit is climbing the fastest.
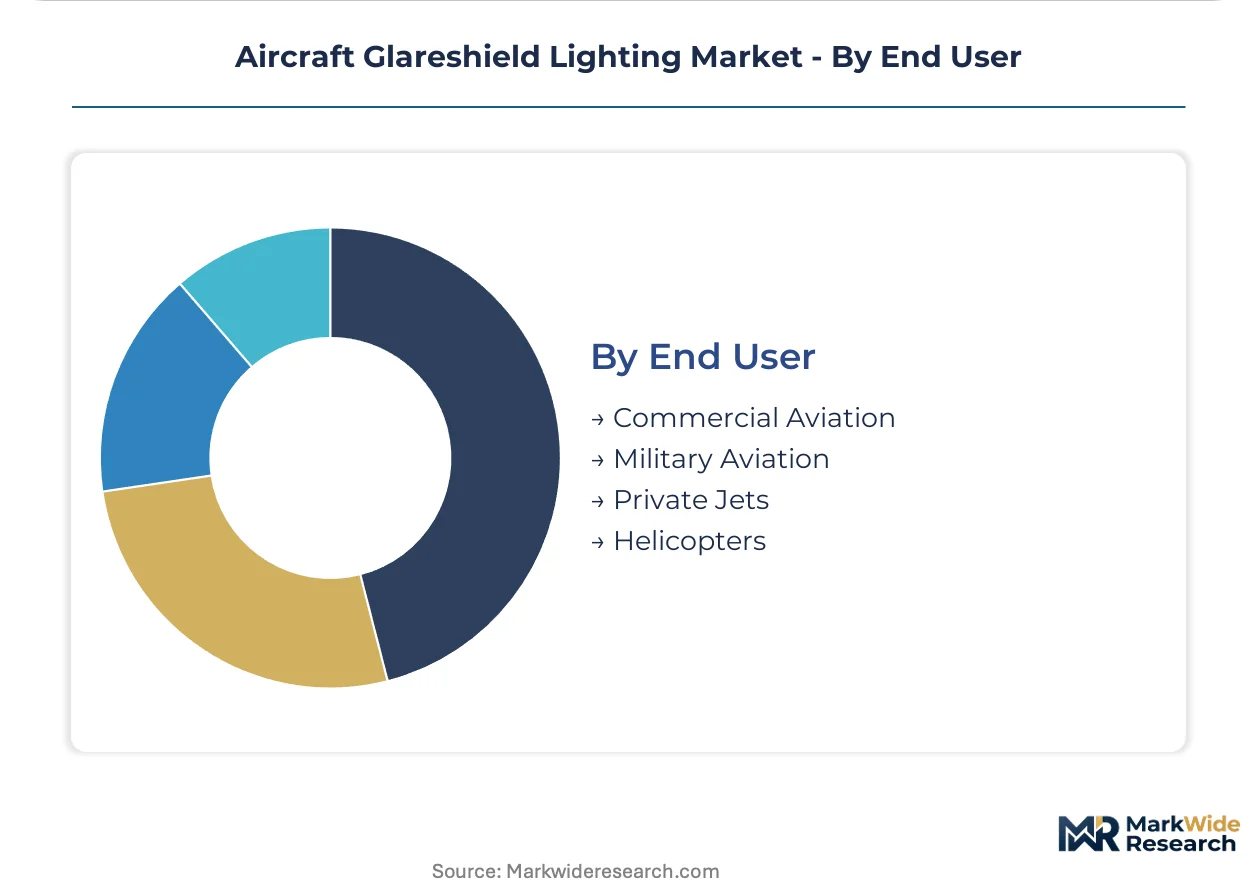
End User:
Application severity drives specification divergence: commercial and military programs demand full certification suites, while private aviation accepts reduced documentation for Part 25 supplemental type certificates.
- Commercial Aviation:Delta, United, and American Airlines consolidate subsystem purchasing through integrated flight-deck modernization contracts. FAA certification timelines and electromagnetic compatibility testing requirements govern vendor selection.
- Military Aviation:Night-vision goggle compatibility and electromagnetic pulse hardening specifications exceed commercial thresholds. United States defense programs source through dedicated military supply chains with specialized testing protocols.
- Private Jets:Completion centers specify custom spectral recipes and dimming curves for owner-preference cabin environments.
- Helicopters:Compact, low-power illumination architectures serve urban air mobility development programs with severe weight and power budgets.
Procurement volume concentrates in commercial aviation; helicopter applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium gallium nitride epitaxy supply concentrates in Japanese and American chemical processing facilities, anchoring raw material flows for LED die fabrication. FAA and EASA certification requirements govern finished product distribution across major aviation manufacturing clusters.
United States
Boeing 737 MAX and Gulfstream G700 production lines in Washington and Georgia drive OEM-integrated glareshield procurement. FAA TSO-C113 mandates night-vision goggle compatibility for Part 121 operators, compressing retrofit timelines. Wichita, Kansas hosts specialized MRO facilities bundling illumination upgrades with flight-deck modernization contracts.
Germany
Airbus A320 family final assembly in Hamburg and Toulouse-linked component sourcing sustain European demand. EASA CS-25 electromagnetic compatibility testing requirements extend qualification timelines for spectral flicker compliance. Bavaria-based avionics integrators specialize in amber-dominant spectral recipes reducing circadian disruption metrics.
France
Dassault Falcon business jet completion centers in Bordeaux and Toulouse specify custom dimming curves for owner-preference cabin environments. EASA photobiological safety limits for blue-rich outputs above 450 nanometers shape supplier qualification. Île-de-France hosts Thales avionics engineering facilities coordinating adaptive lighting architecture development.
United Kingdom
BAE Systems military aviation programs in Lancashire and Bristol demand electromagnetic pulse hardening specifications exceeding commercial thresholds. The UK Ministry of Defence night-vision goggle compatibility standards govern procurement through dedicated military supply chains. Southwest England clusters specialized testing laboratories for spectral qualification.
Japan
Cerium-doped yttrium aluminum garnet phosphor supply concentrates with Japanese chemical processors, creating critical input dependency for LED conversion materials. METI efficiency directives shape design requirements for intelligent illumination systems. Nagoya-area manufacturing clusters supply optical components for regional jet programs.
Aircraft Glareshield Lighting Market Competitive Environment
Strategic partnerships dominate the current landscape as tier-one avionics integrators bundle glareshield solutions with broader flight-deck upgrades. The vendor base organizes around three tiers: diversified aerospace conglomerates with captive semiconductor sourcing, specialized cockpit lighting manufacturers with spectral engineering expertise, and regional MRO service providers expanding into subsystem procurement. Consolidation pressures favor players with in-house optical testing capabilities and direct airline relationships. Technology licensing and backward integration into LED packaging represent the primary competitive vectors.
Among diversified aerospace conglomerates, Honeywell International Inc. and Collins Aerospace exemplify the integrated platform archetype, leveraging avionics suites to capture illumination subsystem value. Diehl Stiftung occupies a position within the specialized European manufacturing tier, serving both commercial and military cockpit programs from German production facilities. These three entities represent distinct strategic postures: semiconductor-captive supply chain control, avionics bundling power, and dual-use manufacturing specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| BAE Systems |
| Astronics Corporation |
| Cobham |
| STG Aerospace |
| Diehl Stiftung |
| Thales |
| Whelen Aerospace Technologies |
| Others |
Value Chain & Pricing Dynamics
Cerium-doped yttrium aluminum garnet phosphor pricing volatility cascades through LED die fabrication into tiered supplier margins, with Japanese chemical processors commanding premium pass-through to aerospace-qualified lighting manufacturers while non-certified competitors face exclusion from Part 121 retrofit contracts.
Pricing Analysis
Warranty and airworthiness certification bundling separates premium-tier suppliers from commodity competitors, with FAA TSO-C113 and EASA CS-25 documentation included in integrated flight-deck contracts but unbundled for aftermarket line-replaceable units. Three-tier pricing structure across certified-avionics-integrated, certified-standalone, and non-certified-economy levels tracks certification investment amortization and captive semiconductor sourcing. Cost compression in standalone LED driver modules is intensifying because silicon carbide substrate demand from adjacent power electronics sectors strains epitaxy reactor availability. Regional carriers with captive MRO capabilities exhibit highest price sensitivity; Gulfstream and Bombardier completion centers show lowest sensitivity given cabin customization budgets.
Supply Chain Analysis
Indium gallium nitride epitaxy feedstock rests on Japanese and American metal-organic chemical vapor deposition reactor operators, with amber-phosphor conversion materials anchored in Japanese specialty chemical processing. Blue LED die fabrication draws from Taiwanese packaging houses and German optical testing laboratories. Single-source vulnerability concentrates in cerium-doped yttrium aluminum garnet phosphor supply from Nagoya-area processors. Distribution runs through tier-one avionics integrators for new-build programs and airline-captive MRO facilities for retrofit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA TSO-C113 and EASA CS-25 certification requirements erect a cost-of-compliance barrier that protects incumbent positions while forcing capital-constrained entrants toward non-certified segments or partnership structures.
For Market Incumbents: Cement spectral testing capabilities in-house to eliminate third-party laboratory dependency and accelerate qualification timelines. Backward integration into LED packaging insulates margins from indium gallium nitride epitaxy cost volatility. Channel control through direct airline engineering relationships displaces traditional OEM intermediaries in United States narrow-body retrofit procurement. For New Entrants and Emerging Players: Launch via urban air mobility cockpit specialization where compact low-power architectures and reduced certification burden create white-space opportunity. Target helicopter and electric vertical take-off aircraft programs in Georgia and Washington state manufacturing clusters. Pursue adaptive lighting algorithm development for EU AI Act conformity assessment preferential access. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cockpit lighting manufacturers with existing EASA and FAA certifications in German and United Kingdom production clusters. Five-to-ten year viability hinges on night-vision goggle compatibility standard evolution and solid-state reliability margin expansion. Watch for electromagnetic pulse hardening specification relaxation in military transport categories as inflection signal for dual-use technology crossover.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Packaging | Captive semiconductor sourcing insulates Honeywell and Collins Aerospace from Japanese phosphor supply volatility. |
| Spectral Testing Laboratory Acquisition | In-house goniophotometer and spectroradiometer capabilities compress EASA electromagnetic compatibility qualification timelines. |
| Urban Air Mobility Cockpit Partnership | Electric vertical take-off aircraft manufacturers in Washington and Georgia require compact illumination architectures absent from transport categories. |
| EU AI Act Algorithmic Transparency Certification | Adaptive lighting systems with embedded pilot gaze tracking gain preferential market access under emerging conformity assessment frameworks. |
| Direct Airline Procurement Channel Development | Delta, United, and American Airlines consolidated subsystem purchasing bypasses traditional OEM intermediaries for flight-deck retrofit contracts. |
Study Parameters
Document review covered FAA Technical Standard Orders, EASA Certification Specifications, and semiconductor industry trade data, complemented by interviews with avionics engineering directors, airline fleet modernization managers, MRO procurement leads, and optical testing laboratory technicians. Secondary validation drew from customs records, SEC aerospace supplier filings, and METI efficiency directive documentation. Bottom-up build from individual platform retrofit schedules and top-down cross-reference against fleet projection databases enabled triangulation.
Historical installation rates across narrow-body, wide-body, and business jet categories were cross-referenced against panel input from tier-one integrators and airline engineering organizations. Segmentation dimensions modeled include product type, technology architecture, installation channel, and end-user application severity. CAGRs were derived from unit placement trajectories and average selling price evolution across the projection horizon. Forecast inputs incorporated night-vision goggle compatibility mandate timing and silicon carbide substrate supply expansion.
The model assumes a particular LED technology adoption path; alternative pathways for OLED emissive layer deposition would alter the outlook if curved glareshield geometries achieve cost parity. Forecasts reflect assumptions regarding FAA and EASA regulatory stability, indium gallium nitride epitaxy capacity expansion, and airline fleet modernization cycle continuity. A small set of named triggers—EASA photobiological safety limit revision, EU AI Act enforcement intensity, and urban air mobility certification pathway finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market