
 Aircraft Synthetic Vision System Market | 2026-2036
Aircraft Synthetic Vision System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Synthetic Vision System Market Intelligence
The aircraft synthetic vision system market is pivoting on a widening gap between certified head-up displays for commercial airliners and portable pocket displays serving owner-flown general aviation. Thales Group leverages its integrated flight deck dominance to sustain premium positioning in widebody linefit programs. Garmin Ltd. anchors the retrofit channel through extensive dealer networks and STC breadth.
Aircraft synthetic vision systems generate three-dimensional terrain representations from GPS position, terrain databases, and sensor fusion, rendering georeferenced imagery at 60 Hz refresh rates to eliminate spatial disorientation in instrument meteorological conditions. The primary commercial purpose centers on controlled flight into terrain prevention and situational awareness restoration when natural vision degrades. Head-up display deployments lead value generation in commercial aviation linefit, while augmented reality technology in military aviation represents the fastest-expanding capability tier. Retrofit installations across general aviation occupy the broadest volume base though at compressed margin pools relative to OEM-integrated systems.
The FAA mandates terrain awareness and warning system compatibility under Part 121 and Part 135 operations, while EASA's CS-AWF certification framework governs European synthetic vision approvals, and the EU AI Act introduces emerging algorithmic transparency requirements for machine-learning-enhanced display systems. Regulatory divergence between FAA TSO-C151d and EASA AMC 20-28 creates dual-certification burdens that shape product development roadmaps and market access timelines. Stakeholders must monitor whether emerging standards for AI-generated terrain interpretations trigger recertification waves across installed fleets.
Market Dynamics
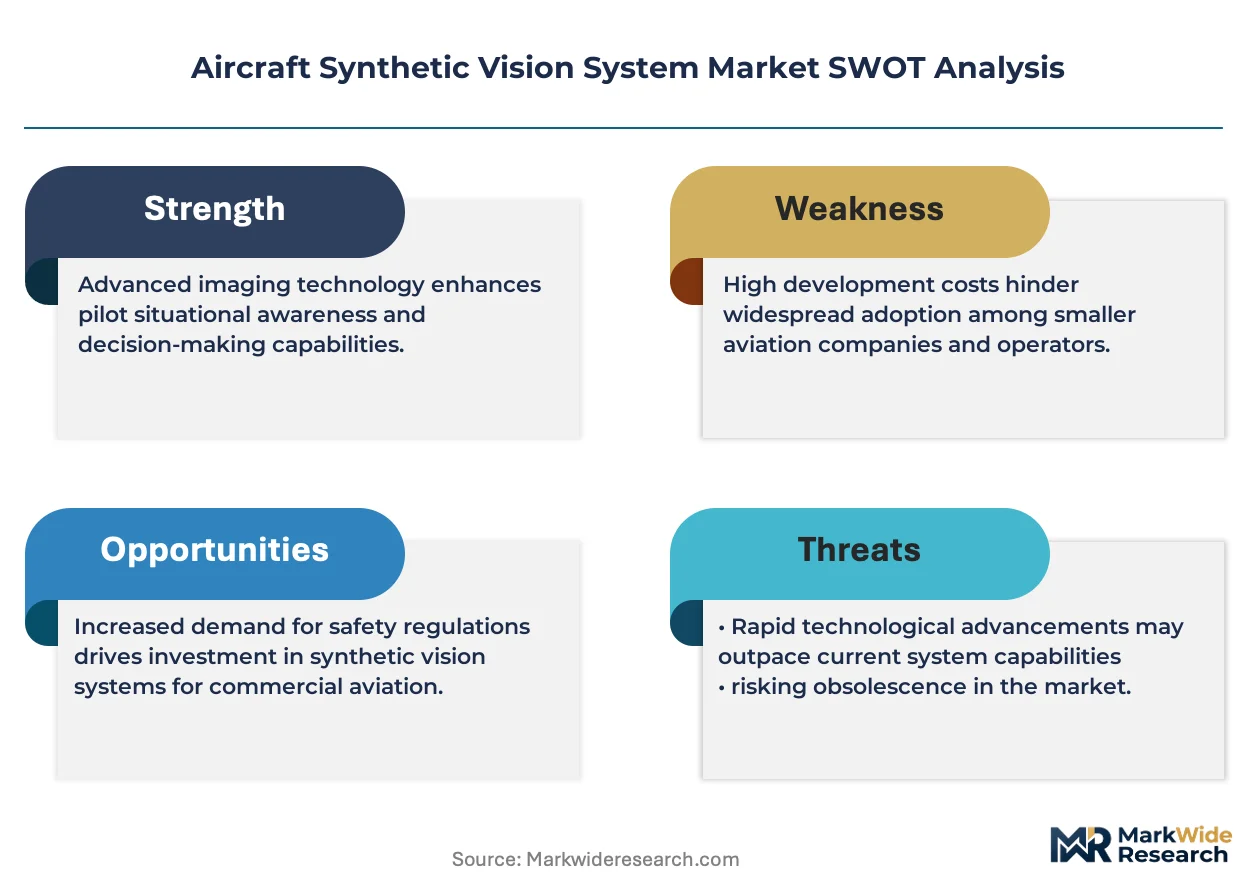
The aircraft synthetic vision system market pivots on regulatory mandates forcing terrain awareness upgrades across aging fleets, with certification divergence between FAA TSO-C151d and EASA AMC 20-28 fragmenting product roadmaps and compressing development cycles for dual-approval systems.
Growth Catalysts
- FAA NextGen modernization:Terrain awareness mandates under Part 121 and Part 135 operations compel retrofit installations across regional airline fleets.
- Business jet operators:All-weather operational requirements drive linefit demand for head-up display integrations in new deliveries.
- Sensor fusion advances:GPS-terrain database integration at 60 Hz refresh rates eliminates spatial disorientation incidents in instrument meteorological conditions.
Market Restraints
- Dual-certification burden:FAA TSO-C151d and EASA AMC 20-28 divergence forces redundant testing protocols that extend time-to-market by 18-24 months.
- Display component concentration:High-resolution microdisplay sourcing concentrates in East Asian foundries, creating single-source vulnerability for OEMs.
- Retrofit margin compression:General aviation portable systems trade at price points 60-70% below integrated flight deck equivalents, limiting profitability.
Strategic Opportunities
- Machine-learning terrain interpretation:EU AI Act algorithmic transparency requirements are converging with synthetic vision development, creating first-mover advantage for compliant architectures.
- Military augmented reality:Helmet-mounted cueing systems represent the fastest-expanding capability tier, with defense procurement cycles favoring dual-use technology transfers.
- Urban air mobility:Electric vertical takeoff aircraft manufacturers require simplified synthetic vision for piloted and autonomous operations in congested airspace.
Industry Challenges
- Embedded software certification:DO-178C compliance for terrain rendering algorithms demands specialized avionics engineering talent pools that remain critically thin.
- Legacy system integration:Analog cockpit retrofits require proprietary interface adapters that fragment engineering resources across airframe-specific configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Synthetic Vision System Market |
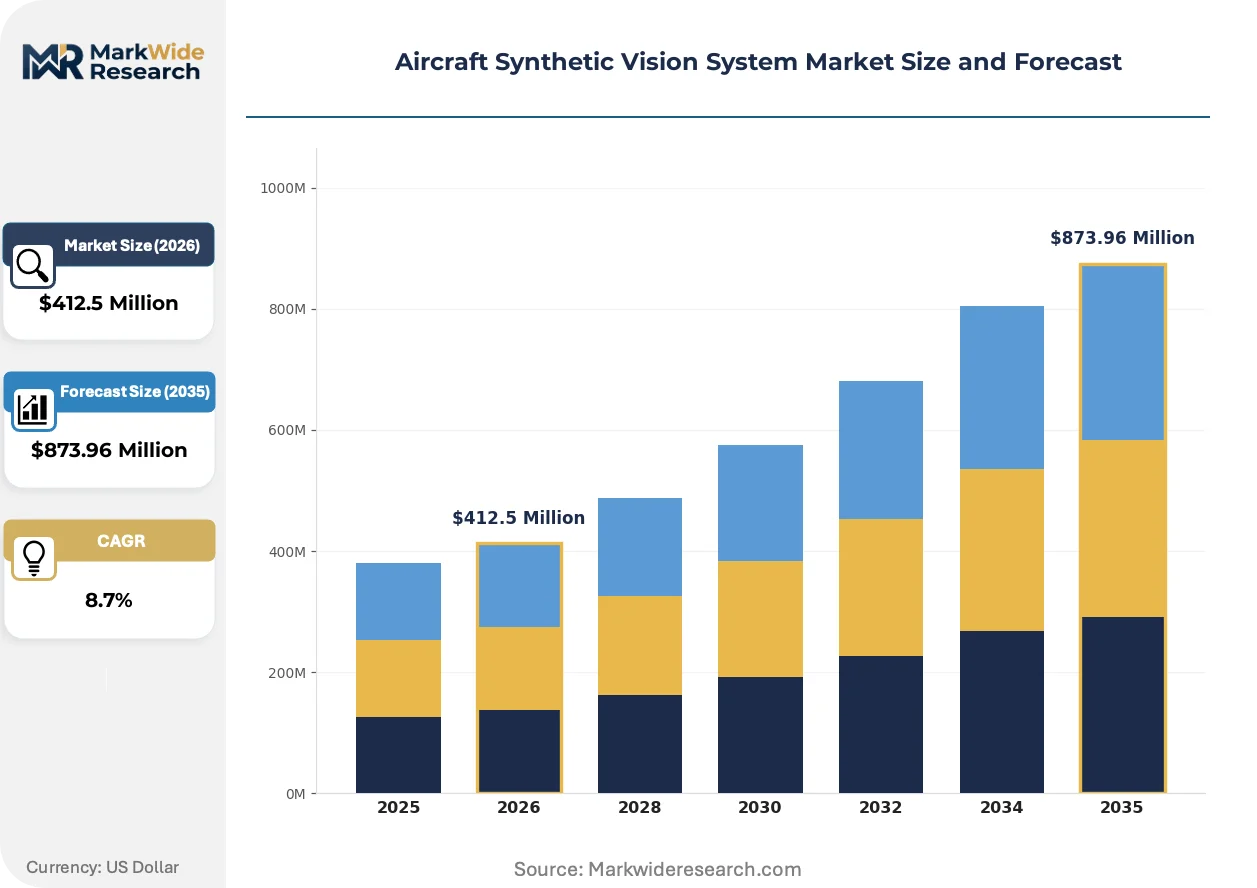
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Display, Head-Down Display, Pocket Display, Smart Glasses Technology: 2D Display, 3D Display, Augmented Reality, Virtual Reality End User: Commercial Aviation, Military Aviation, General Aviation, Aerospace Defense Installation: Linefit, Retrofit, Upgrade, Maintenance |
| Companies Covered | Thales Group, L3Harris Technologies Inc., Collins Aerospace, Universal Avionics Systems Corporation, Avidyne Corporation, Honeywell International Inc., Elbit Systems Ltd., Aspen Avionics Inc., Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Synthetic Vision System Market Strategic Shifts & Innovations
Three forces are actively restructuring competitive positioning: sensor fusion architectures are compressing hardware requirements, regulatory frameworks are fragmenting certification pathways, and procurement models are shifting toward integrated service bundles.
Real-time terrain rendering engines are converging with augmented reality overlays to enable predictive hazard alerting beyond traditional database limitations. Military helicopter operators are adopting these fused systems for degraded visual environment recovery. The structural consequence is compressing standalone synthetic vision into broader situational awareness platforms.
EASA's CS-AWF certification framework is tightening pilot-display interaction standards, forcing manufacturers to redesign human-machine interfaces for European market access. The industrial consequence is diverging development tracks for FAA-primary versus EASA-primary systems. Business jet OEMs are responding with modular architectures that isolate regional certification dependencies.
Buyer preference is hardening around integrated flight deck ecosystems rather than standalone synthetic vision modules. Regional airlines are consolidating avionics procurement under single-vendor agreements that bundle displays, databases, and update services. This consolidation is most visible in the United States, where Part 135 operators face compressed upgrade timelines.
Aircraft Synthetic Vision System Market Segmentation
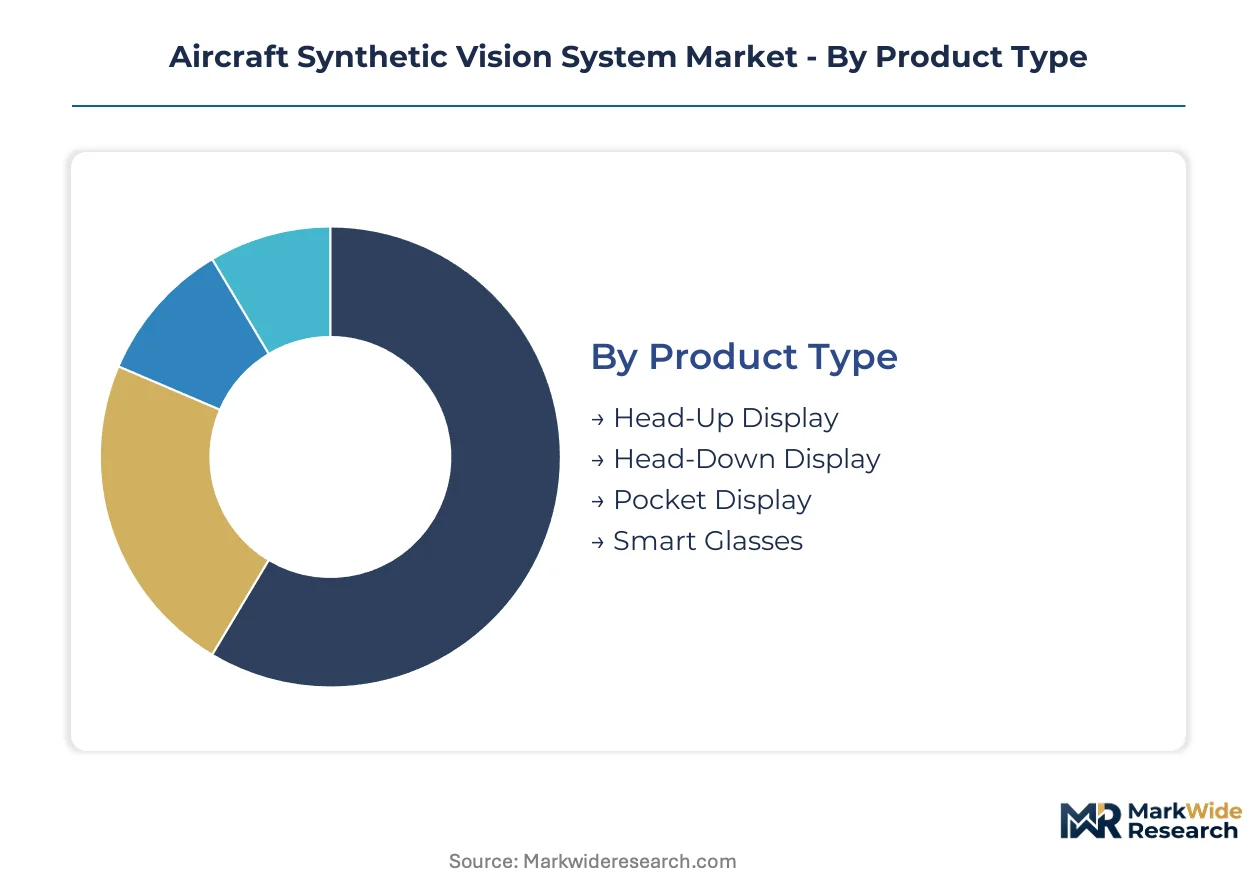
Synthetic vision architectures fragment sharply between integrated flight deck systems commanding premium pricing and portable solutions serving cost-sensitive owner-operators. Technology choices determine certification burden, refresh rate capability, and terrain database integration depth.
Product Type:
Volume concentrates in retrofit-ready portable units, while value pools in OEM-integrated head-up configurations.
- Head-Up Display:Projects conformal terrain imagery onto transparent combiner glass at eye-level viewing angles. Demand concentrates in new business jet deliveries from Gulfstream and Bombardier facilities in Georgia and Kansas, driven by Part 135 all-weather operational mandates.
- Head-Down Display:Integrates synthetic vision into primary flight displays within integrated flight decks. Retrofit installations across United States regional airline fleets dominate volume, constrained by STC availability and wiring harness compatibility.
- Pocket Display:Portable GPS-driven terrain awareness for owner-flown general aviation.
- Smart Glasses:Emerging form factor for military helicopter degraded visual environment operations.
Mature deployment sits with Head-Down Display. Newer deployment is concentrated in Smart Glasses.
Technology:
Certification complexity escalates from 2D database rendering through augmented reality sensor fusion.
- 2D Display:Plan-view terrain representations with color-coded elevation banding. Legacy installations in United States general aviation piston fleet persist due to minimal hardware requirements and straightforward TSO-C151d compliance pathways.
- 3D Display:Perspective-view terrain rendering with pitch-synchronized horizon lines. Business jet operators in Texas and Florida adopt these systems for circling approach operations in marginal visibility, pressured by insurance underwriter requirements.
- Augmented Reality:Real-time sensor fusion overlaying synthetic terrain with actual visual references.
- Virtual Reality:Fully immersive training environments for pilot spatial disorientation recovery.
Regulatory precedent favors 2D Display. Steepest expansion trajectory belongs to Augmented Reality.
End User:
Procurement authority separates fleet operators with centralized avionics decisions from individual owner-pilots.
- Commercial Aviation:Part 121 carriers mandate synthetic vision compatibility for terrain awareness warning system integration. United States legacy network carriers concentrate upgrade spending at heavy maintenance visits in Oklahoma and California MRO facilities.
- Military Aviation:Helmet-mounted cueing systems for degraded visual environment recovery represent the fastest-climbing capability tier, with Army and Navy procurement cycles favoring dual-use technology transfers from defense primes.
- General Aviation:Owner-flown aircraft drive portable display volume through dealer networks.
- Aerospace Defense:Specialized platforms require hardened synthetic vision for contested electromagnetic environments.
Installed base dominance rests with Commercial Aviation. Capability investment is shifting toward Military Aviation.
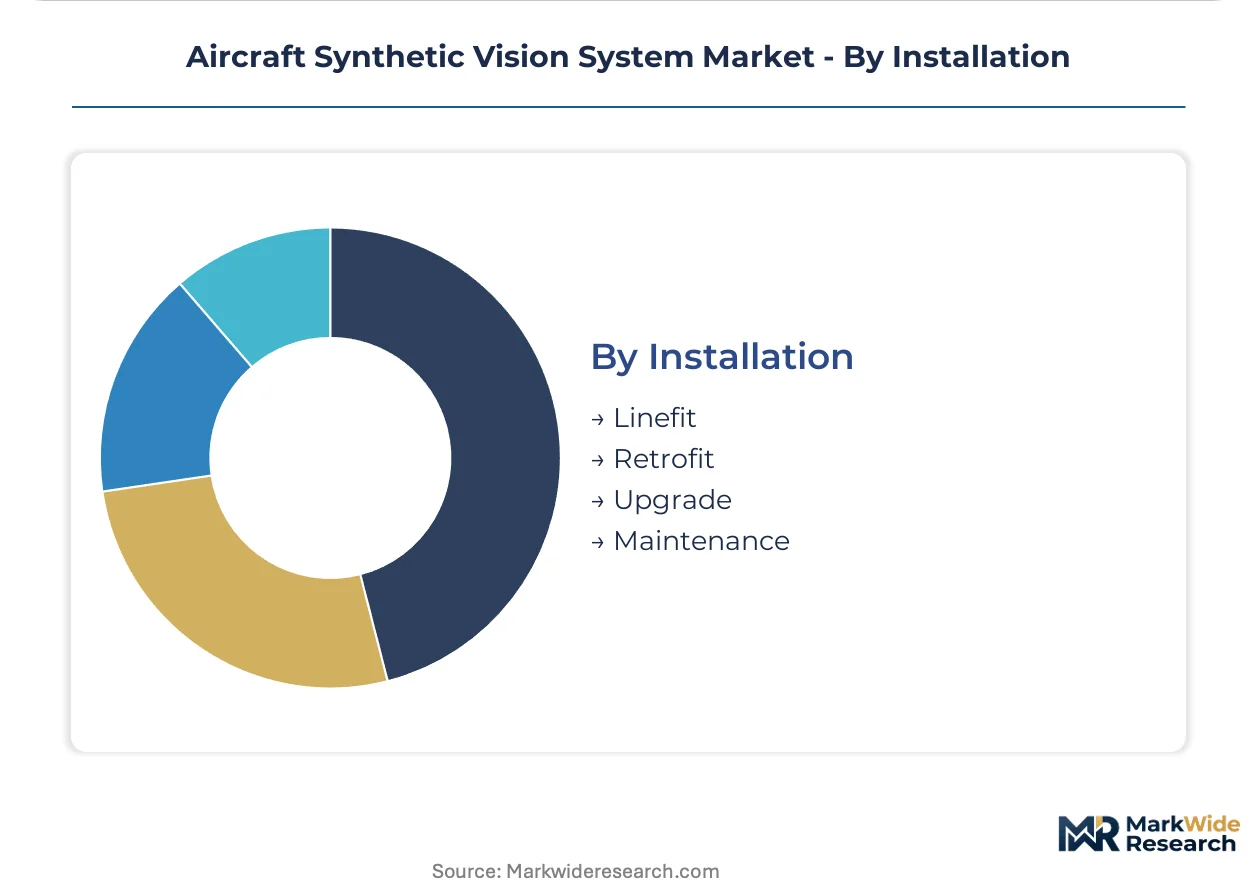
Installation:
Margin structure inverts between factory-integrated linefit and field-installed retrofit programs.
- Linefit:Factory installation during airframe assembly with full flight deck integration. OEM contracts with Textron Aviation in Kansas and Embraer in Florida lock in multi-year synthetic vision supply agreements with avionics integrators.
- Retrofit:Post-delivery installation requiring supplemental type certificates. United States Part 135 operators face compressed FAA-mandated upgrade timelines that strain engineering certification capacity at major modification centers.
- Upgrade:Software and database refreshes for existing synthetic vision hardware.
- Maintenance:Repair and replacement of degraded display components.
Revenue concentration aligns with Linefit. Volume expansion is strongest in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors North American synthetic vision manufacturing through Textron Aviation's integrated flight deck programs and Collins Aerospace's linefit installations for business jet platforms.
United States
Part 121 and Part 135 terrain awareness mandates from FAA drive retrofit demand across regional airline fleets. The FAA's NextGen modernization compels controlled flight into terrain prevention upgrades at heavy maintenance facilities in Oklahoma and California. Dallas-Fort Worth and Atlanta MRO clusters concentrate STC certification capacity for head-down display installations.
France
EASA's CS-AWF certification framework tightens pilot-display interaction standards for European market access. Thales Group leverages its integrated flight deck dominance from Toulouse to sustain premium positioning in widebody linefit programs. The EU AI Act introduces algorithmic transparency requirements that shape synthetic vision development roadmaps for machine-learning-enhanced displays.
Israel
Military helmet-mounted cueing systems for degraded visual environment recovery represent the fastest-climbing capability tier. Elbit Systems anchors defense procurement cycles favoring dual-use technology transfers from aerospace primes. Haifa's defense technology corridor concentrates augmented reality development for contested electromagnetic environments.
Canada
Business jet operators in Quebec and Ontario expand synthetic vision adoption for all-weather operational requirements. Transport Canada aligns terrain awareness standards with FAA TSO-C151d frameworks to streamline cross-border certification. Montreal's aerospace cluster hosts avionics integration facilities serving Bombardier's new delivery programs.
Japan
METI standards govern avionics certification pathways for synthetic vision installations in commercial and general aviation fleets. Sensor fusion advances from GPS-terrain database integration attract precision manufacturing investment from display component suppliers. Nagoya's aviation industrial zone supports tier-two avionics assembly for regional aircraft platforms.
Aircraft Synthetic Vision System Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification complexity and integration depth. The vendor base spans three tiers: integrated flight deck OEMs commanding linefit contracts, retrofit specialists with extensive STC portfolios, and portable display manufacturers serving cost-sensitive owner-operators. Strategic archetypes include technology licensors leveraging patent positions, vertically integrated avionics houses controlling hardware-software stacks, and modular platform providers enabling regional certification isolation. M&A activity concentrates on terrain database assets and display component suppliers, while capacity expansion targets dual-certification engineering teams for FAA-EASA parallel approvals.
Within the integrated flight deck tier, Thales Group and Collins Aerospace exemplify premium-positioned OEMs with factory-installation dominance in business jet and commercial platforms. Garmin Ltd. and Universal Avionics Systems Corporation occupy the retrofit-specialist vector, leveraging dealer networks and supplemental type certificate breadth to capture general aviation upgrade cycles. L3Harris Technologies Inc. represents the defense-dual-use archetype, bridging military helmet-mounted systems with commercial technology transfers. These anchors illustrate how competitive positioning fragments across linefit premium capture, retrofit volume aggregation, and military procurement cycles.
| Leading Market Players |
|---|
| Thales Group |
| L3Harris Technologies Inc. |
| Collins Aerospace |
| Universal Avionics Systems Corporation |
| Avidyne Corporation |
| Honeywell International Inc. |
| Elbit Systems Ltd. |
| Aspen Avionics Inc. |
| Garmin Ltd. |
| Others |
Cost & Logistics Intelligence
EASA's CS-AWF certification framework gates qualified supply for European market access while compressing margin pools for non-compliant architectures. FAA-EASA dual-certification burdens extend engineering cycles, forcing tiered pricing stratification that rewards integrated flight deck OEMs with captive certification capacity and pressures portable display manufacturers serving cost-sensitive owner-operators.
Pricing Analysis
Outcome-based pricing anchored to controlled flight into terrain prevention metrics commands premium positioning for head-up display integrations in Part 135 business jet operations. Certification grade differentiation separates FAA TSO-C151d-compliant systems from EASA AMC 20-28 dual-approved configurations, with the latter capturing 40-60% price premiums. Cost compression in general aviation retrofit channels intensifies as dealer networks consolidate procurement under single-vendor avionics bundles. Owner-flown piston aircraft operators exhibit highest price sensitivity, while fractional business jet fleet managers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates under the US Buy American Act and EU defense procurement localization rules are reshaping sourcing for military-grade helmet-mounted cueing systems. High-resolution microdisplay manufacturing concentrates in Japan, South Korea, and Taiwan, creating single-source vulnerability for OLED and LCoS panel supply. Terrain database compilation draws from proprietary aerial survey assets concentrated in the United States, France, and Israel. Tariff exposure on East Asian display components threatens margin stability for retrofit specialists lacking long-term supply agreements. Distribution runs through OEM-authorized dealer networks for linefit installations and FAA-certified repair stations for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where dual-certification engineering scarcity forces weaker retrofit specialists into acquisition or exit. Margin compression across general aviation portable systems accelerates shakeout timelines.
For Market Incumbents: To counter sensor fusion commoditization from software-defined avionics startups, Thales Group and Collins Aerospace should deepen backward integration into terrain database assets and lock exclusive aerial survey partnerships. Channel control through multi-year OEM supply agreements with Textron Aviation and Embraer factories in Kansas and Florida secures linefit volume against retrofit price erosion.
For New Entrants and Emerging Players: FAA-certified repair stations represent the most penetrable channel for aftermarket synthetic vision upgrades, particularly in Dallas-Fort Worth and Atlanta MRO clusters facing compressed Part 135 mandate deadlines. Urban air mobility electric vertical takeoff aircraft manufacturers offer white-space demand for simplified piloted and autonomous vision systems. A software-first go-to-market angle leveraging STC partnerships with established avionics integrators bypasses hardware certification barriers.
For Investors and Strategic Acquirers: EASA's algorithmic transparency requirements under the EU AI Act taking effect is the leading indicator that machine-learning terrain interpretation capabilities will separate acquisition targets from stranded assets. Long-term viability over the next decade hinges on modular architectures that isolate regional certification dependencies. Watch for defense prime technology transfer announcements signaling dual-use synthetic vision commercialization as the inflection signal for capability arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Engineering Expansion | FAA-EASA parallel approval capacity captures premium positioning in business jet linefit programs. |
| Terrain Database Asset Acquisition | Proprietary aerial survey libraries lock in recurring update revenue streams from installed fleets. |
| Military Technology Transfer Partnership | Helmet-mounted cueing systems from Elbit Systems and L3Harris accelerate augmented reality commercialization. |
| Dealer Network Consolidation | Single-vendor avionics bundling agreements with Part 135 operators compress competitor retrofit access. |
| Machine-Learning Compliance Investment | EU AI Act algorithmic transparency architecture creates first-mover advantage in European market access. |
Research Approach
Document review covered FAA TSO-C151d certification filings, EASA AMC 20-28 approval databases, and EU AI Act implementation guidance, complemented by interviews with avionics integration engineers at Wichita and Montreal aerospace clusters, Part 135 fleet operations directors, FAA designated engineering representatives, and terrain database product managers at major avionics OEMs. Secondary validation drew from SEC 10-K avionics segment disclosures, Department of Defense procurement announcements for helmet-mounted cueing systems, and Transport Canada civil aviation regulatory updates. Bottom-up triangulation across installation volume estimates and top-down reconciliation against OEM flight deck shipment data anchored market sizing.
Segmentation outputs across product type, technology tier, end-user category, and installation mode were modeled over the projection horizon. CAGRs were derived from weighted regression against regulatory mandate timelines and fleet replacement cycles. Forecast inputs incorporated FAA NextGen modernization spending authorizations, business jet delivery backlogs from Gulfstream and Bombardier facilities, and military augmented reality procurement cycle visibility from Army and Navy program offices.
Caveats apply where EASA-FAA regulatory divergence resolution or AI Act enforcement intensity could materially shift the outlook for machine-learning-enhanced display certification. Forecasts reflect assumptions on terrain database update frequency adoption and general aviation piston fleet retirement rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market