
 Global Aircraft Cockpit Display System Market | 2026-2036
Global Aircraft Cockpit Display System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Cockpit Display System Market Foresight
Avionics software engineering talent is rotating toward civilian platforms as defense budgets face congressional pressure, reshaping how suppliers allocate technical resources. Honeywell International Inc. leverages its integrated flight deck architecture to sustain long-term airline contracts. Collins Aerospace anchors military display programs through its position on multiple fighter and trainer platforms. Thales Group competes in the head-up display segment with specialized optical expertise.
Aircraft cockpit display systems comprise electronic visual interfaces that present flight, navigation, engine, and sensor data to flight crews through multi-layered glass panels operating at luminance levels exceeding 1000 cd/m² for direct sunlight readability. These systems integrate with flight management computers and terrain databases to reduce pilot workload and enhance situational awareness during all phases of flight. Primary flight displays and multi-function displays dominate installed base volumes, while synthetic vision systems command premium pricing due to their terrain-rendering computational demands. OLED technology is displacing legacy LCD in new business jet programs where weight reduction and contrast ratio improvements justify redesign costs.
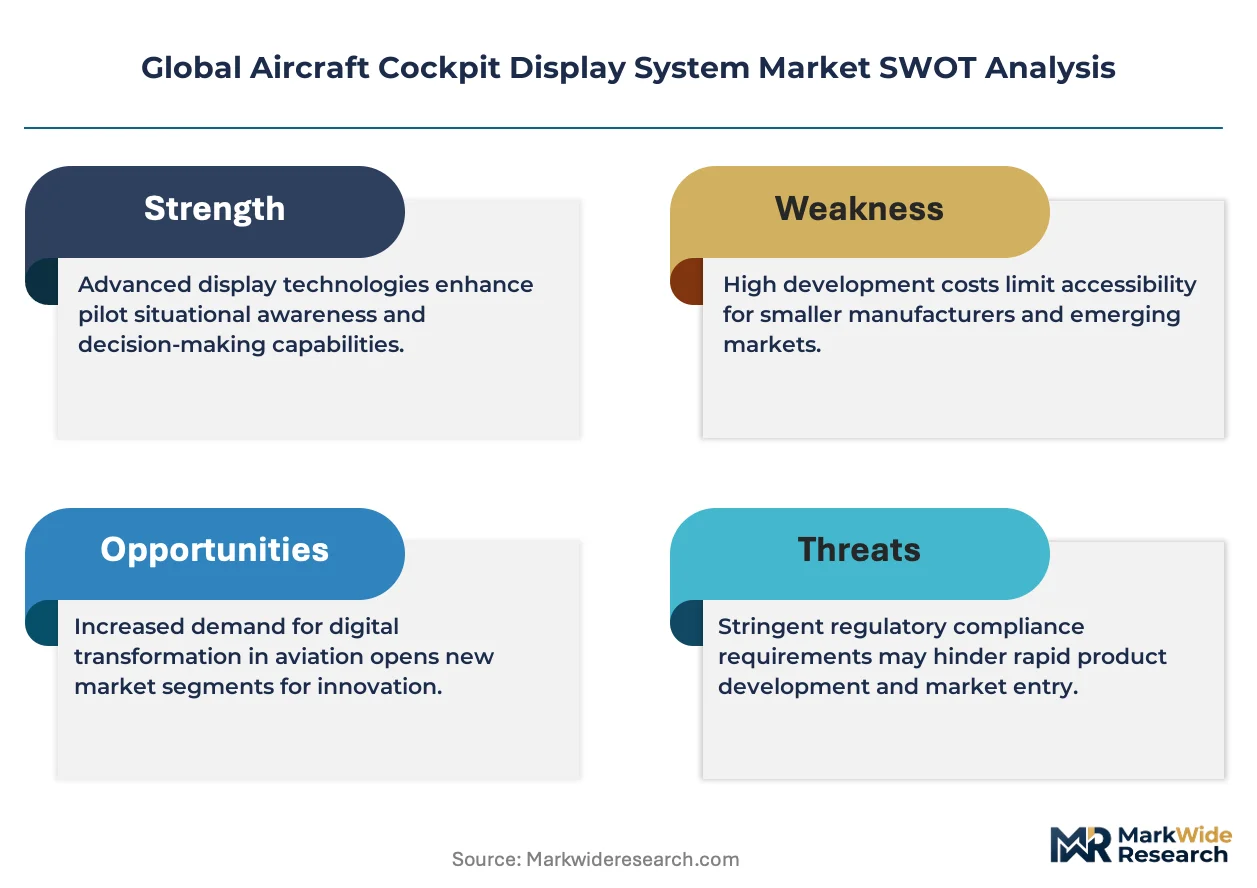
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate minimum field-of-view angles and failure-mode behavior for primary flight instruments, directly influencing display architecture decisions. EU AI Act provisions for safety-critical embedded systems are beginning to shape software validation protocols for next-generation adaptive displays. Stakeholders must monitor how emerging human factors research on attention fragmentation influences regulatory guidance for information density limits.
Market Dynamics
Retrofit mandates for aging commercial fleets and defense modernization cycles are compressing supplier lead times while fragmenting procurement authority across airline technical divisions and military program offices.
Growth Catalysts
- FAA Enhanced Vision System Mandates:United States commercial operators must upgrade primary flight displays to meet synthetic vision requirements, forcing replacement cycles ahead of airframe retirement.
- Business Jet OLED Adoption:New platform introductions prioritize organic light-emitting diode panels for weight reduction and sunlight readability, creating technology refresh demand.
- Defense Trainer Fleet Modernization:Military procurement offices in multiple geographies are standardizing integrated glass cockpits across basic and advanced trainer aircraft categories.
Market Restraints
- Indium Supply Concentration:Thin-film transistor manufacturing depends on indium tin oxide feedstock concentrated in Chinese processing facilities, exposing display panel costs to geopolitical supply disruption.
- Dual Certification Burden:EASA CS-25 and FAA Part 25 divergence on human factors validation protocols forces redundant testing for transatlantic platform approvals.
- LCD Legacy Lock-In:Existing airline fleets carry substantial sunk investment in liquid crystal display architectures, slowing organic technology substitution despite performance gaps.
Strategic Opportunities
- India Defense Indigenization:The country's offset procurement rules for fighter and transport aircraft create openings for local cockpit display subsystem integration partnerships.
- EU AI Act Safety-Critical Pathway:Adaptive display algorithms qualifying under emerging embedded system frameworks gain first-mover positioning in next-generation flight deck architectures.
- Urban Air Mobility Glass Cockpit Standardization:Electric vertical takeoff and landing manufacturers lack established avionics suppliers, inviting new entrant display system definitions.
Industry Challenges
- DO-178C Software Verification Talent Scarcity:Civil aviation certification expertise concentrates among a narrow cohort of engineers, constraining supplier scaling.
- Multi-Platform Integration Complexity:Display systems must synchronize with legacy flight management computers, terrain databases, and sensor fusion architectures across heterogeneous fleet ages.
- Human Factors Litigation Exposure:Pilot attention fragmentation research is reshaping liability frameworks for information density design decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Cockpit Display System Market |
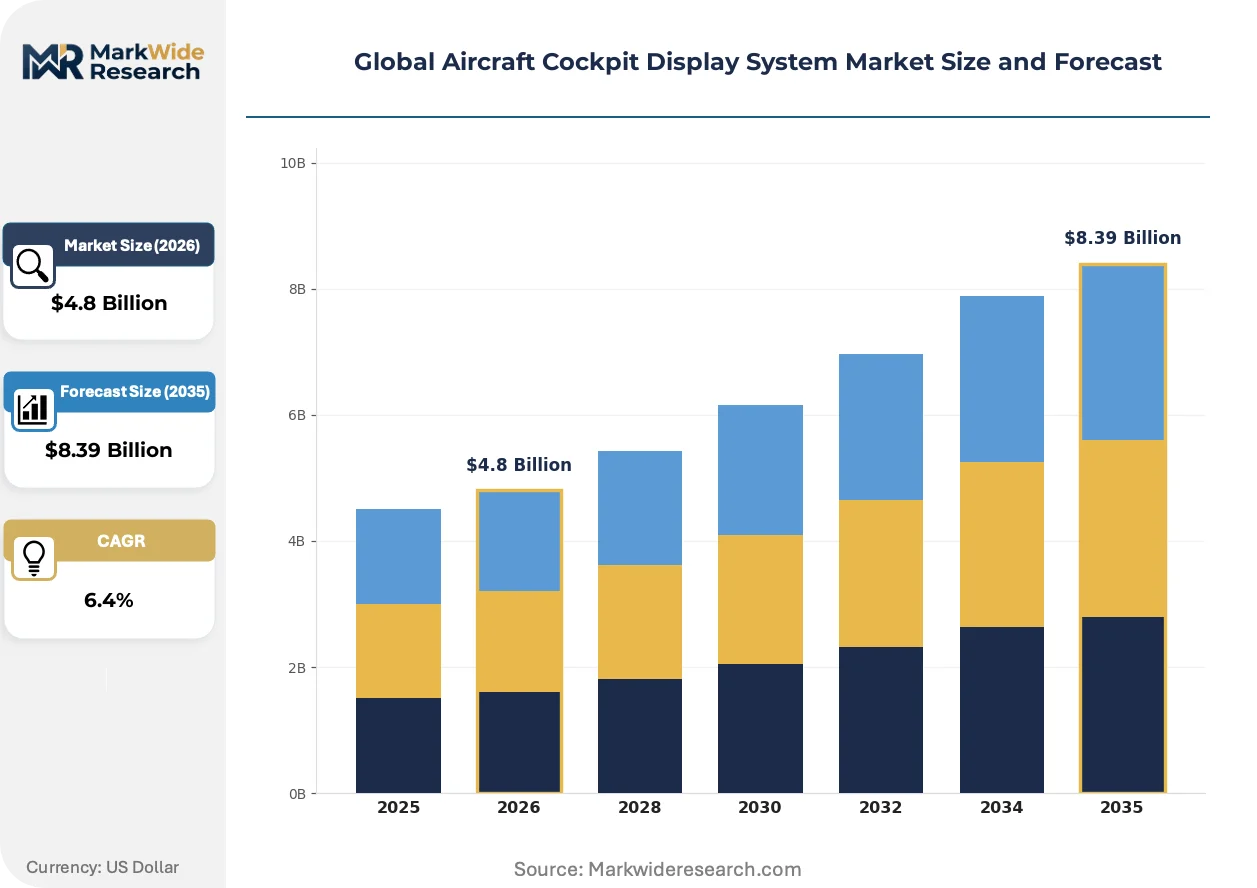
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Display Type: Primary Flight Display, Multi-Function Display, Head-Up Display, Enhanced Vision System, Synthetic Vision System Technology: LCD, OLED, LED, TFT, AMOLED Application: Commercial Aviation, Military Aviation, Business Jets, Unmanned Aerial Vehicles, Test Aircraft End User: Airlines, Defense Contractors, Aircraft Manufacturers, Avionics Integrators, Flight Schools |
| Companies Covered | Honeywell International Inc., Collins Aerospace, Thales Group, Garmin Ltd, Elbit Systems Ltd., L3Harris Technologies, Inc., Northrop Grumman Corporation, Aspen Avionics, Avidyne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Cockpit Display System Market Shifts & Advancements
Display architecture is pivoting from hardware-centric specifications toward software-defined interfaces that enable post-certification feature updates through over-the-air delivery mechanisms.
MicroLED backlighting is supplanting edge-lit LED arrays in wide-body commercial programs, delivering localized dimming zones that reduce power draw and thermal load. Emirates and Singapore Airlines have specified microLED primary flight displays for next-generation cabin refreshes. This transition compresses the supplier base toward semiconductor foundries with compound semiconductor fabrication capability.
EASA CS-25 Amendment 25-157 introduced revised field-of-view angle requirements for head-up display installations, compelling optical path redesigns in existing product families. European business jet OEMs are absorbing certification timeline extensions of eight to fourteen months. The amendment most affects integrated flight deck suppliers serving the super-midsize cabin category.
Airline technical procurement divisions are consolidating avionics purchasing under fleet-wide lifecycle agreements, displacing individual line-item negotiations for display replacements. Lufthansa Technik and ST Engineering have pioneered power-by-the-hour contracts covering cockpit display availability. This concentration is most advanced in Southeast Asia where third-party maintenance providers have captured MRO authority from flag carriers.
Global Aircraft Cockpit Display System Market Segmentation
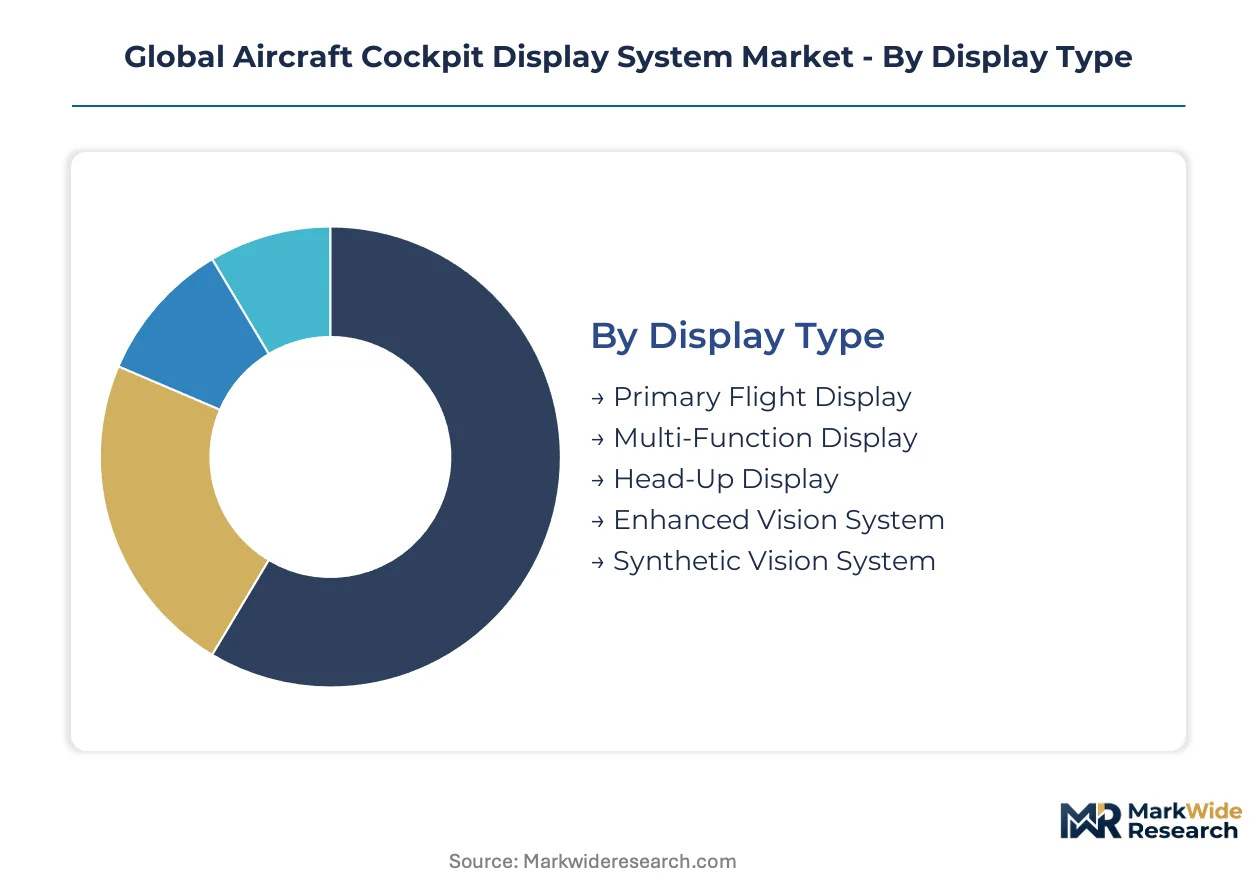
Cockpit display procurement splits across technical specifications, certification pathways, and operational use cases. Each dimension carries distinct margin profiles and supplier qualification barriers that reshape competitive positioning.
Display Type:
Substitution pressure runs strongest against legacy electromechanical instruments as glass cockpit mandates accelerate replacement cycles across all aircraft categories.
- Primary Flight Display:These units render attitude, altitude, airspeed, and heading data through redundant glass channels certified to FAA Part 25 fail-operational standards. Commercial airlines in the United States dominate procurement volumes as retrofit mandates compress replacement timelines for aging narrow-body fleets.
- Multi-Function Display:Configurable screen real estate hosts navigation charts, engine parameters, and system synoptics through pilot-selectable page layouts. Military trainer programs in multiple geographies are standardizing these units to reduce type-rating complexity across aircraft families.
- Head-Up Display:Collimated optical paths project flight data onto transparent combiner panels for eyes-forward operations. Business jet OEMs absorb EASA CS-25 Amendment 25-157 certification extensions.
- Enhanced Vision System:Infrared and millimeter-wave sensor feeds overlay real-time terrain imagery on primary displays. FAA mandates for Part 135 operators drive retrofit demand.
- Synthetic Vision System:Terrain-rendering algorithms generate three-dimensional forward views from database sources. Computational load requirements sustain premium pricing tiers.
Primary Flight Display retains volume leadership; Synthetic Vision System holds the steepest expansion curve.
Technology:
Cost tier separation widens between mature LCD volumes and emerging OLED premiums as business jet programs absorb redesign expenses for weight and contrast gains.
- LCD:Thin-film transistor liquid crystal architectures dominate installed base volumes across commercial air transport fleets. Sunk investment in certification and spares infrastructure slows substitution despite sunlight readability limitations.
- OLED:Organic light-emitting diode panels eliminate backlight assemblies to reduce weight and enable true black levels for night operations. New platform introductions at Gulfstream and Bombardier specify these units for flight deck modernization.
- LED:Edge-lit and direct-lit arrays serve backlighting functions in hybrid display architectures. Thermal management requirements constrain adoption in compact cockpit envelopes.
- TFT:Thin-film transistor active matrix backplanes enable high refresh rates for fast-moving symbology. Defense applications prioritize these specifications for fighter aircraft.
- AMOLED:Active matrix organic variants integrate drive electronics per pixel for improved response times. Emerging urban air mobility prototypes evaluate these units for weight-critical applications.
LCD commands installed base dominance; OLED is climbing the fastest among new platform specifications.
Application:
Customer type fragmentation splits procurement authority between airline technical divisions, military program offices, and OEM avionics teams with divergent certification timelines.
- Commercial Aviation:Scheduled carriers operate under FAA and EASA airworthiness directives mandating enhanced vision capabilities. Fleet-wide lifecycle agreements concentrate purchasing power at Lufthansa Technik and ST Engineering.
- Military Aviation:Defense procurement offices specify ruggedized displays with night vision goggle compatibility and electromagnetic hardening. Trainer fleet modernization programs across NATO members standardize integrated glass cockpits.
- Business Jets:Super-midsize and large-cabin OEMs prioritize customization flexibility and premium aesthetics. EASA field-of-view amendments extend certification timelines for European-registered platforms.
- Unmanned Aerial Vehicles:Ground control station displays mirror manned cockpit architectures for operator training transfer. Regulatory frameworks for beyond-visual-line-of-sight operations remain under development.
- Test Aircraft:Experimental and certification flight test programs require configurable display architectures for rapid instrumentation changes. Demand concentrates at NASA, DLR, and military flight test centers.
Commercial Aviation anchors procurement volumes; Unmanned Aerial Vehicles are gaining share fastest as regulatory pathways mature.
End User:
Supply concentration among avionics integrators and aircraft manufacturers is compressing tier-two supplier margins through captive sourcing requirements.
- Airlines:Technical procurement divisions at Delta, United, and Air France-KLM consolidate avionics purchasing under power-by-the-hour contracts. Third-party MRO providers in Southeast Asia capture display replacement authority from flag carriers.
- Defense Contractors:Lockheed Martin and Boeing Military Aircraft integrate display subsystems into platform-level contracts. Offset requirements in India and South Korea mandate local subsystem partnerships.
- Aircraft Manufacturers:Airbus and Boeing specify flight deck architectures that lock in long-term display supplier relationships. Airframe OEMs absorb certification liability for integrated systems.
- Avionics Integrators:Honeywell, Collins Aerospace, and Thales Group package displays with flight management computers and sensor fusion processors. DO-178C software verification expertise concentrates among this tier.
- Flight Schools:Training organizations prioritize cost-optimized displays for high-utilization trainer aircraft. Cessna and Piper piston fleets drive demand for retrofit glass panel kits.
Airlines retain volume leadership; Avionics Integrators hold the steepest expansion curve as system complexity concentrates design authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA mandates for enhanced flight deck capabilities anchor procurement volumes in the United States, while EASA certification amendments reshape European retrofit timelines. Defense modernization programs and commercial fleet renewals distribute demand across multiple geographies with distinct regulatory drivers.
United States
Commercial airlines operate under FAA Part 25 synthetic vision mandates that compress replacement cycles for aging narrow-body fleets. The Enhanced Flight Vision System rulemaking forces operators to upgrade primary flight displays ahead of scheduled airframe retirement. Major procurement concentrates at integrators in Phoenix, Arizona and Cedar Rapids, Iowa where defense and commercial programs share engineering resources.
Germany
EASA CS-25 Amendment 25-157 field-of-view requirements extend certification timelines for head-up display installations by eight to fourteen months. Lufthansa Technik consolidates avionics purchasing under power-by-the-hour contracts covering cockpit display availability. Industrial activity clusters in Hamburg and Munich where business jet OEMs absorb regulatory compliance costs.
France
Thales Group anchors head-up display manufacturing in the Paris metropolitan region with specialized optical expertise serving both commercial and military platforms. The EU AI Act safety-critical embedded system provisions are beginning to shape software validation protocols for adaptive display algorithms. Toulouse hosts airframe integration teams specifying flight deck architectures for next-generation programs.
India
Defense offset procurement rules for fighter and transport aircraft create openings for local cockpit display subsystem integration partnerships. The country's national aviation regulator aligns certification pathways with FAA and EASA standards while mandating indigenous component thresholds. Bengaluru and Hyderabad host emerging avionics assembly operations serving domestic platform requirements.
Japan
METI industrial policy supports domestic display panel manufacturing for defense applications with night vision goggle compatibility requirements. Mitsubishi Heavy Industries integrates flight deck systems into indigenous fighter programs with electromagnetic hardening specifications. Nagoya and Komaki concentrate airframe final assembly where cockpit display procurement ties to platform-level contracts.
Global Aircraft Cockpit Display System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with procurement authority consolidating at avionics integrators that package displays with flight management and sensor fusion systems. The structure rewards DO-178C software verification expertise and long-term airline lifecycle agreements. Three archetypes dominate: full-flight-deck integrators, display-technology specialists, and defense-focused ruggedization providers. Competitive moves center on M&A for software talent acquisition and strategic partnerships for compound semiconductor fabrication access.
Among integrated flight deck providers, Honeywell International Inc. and Collins Aerospace exemplify the tier that captures multi-system procurement authority through certification liability absorption. Thales Group occupies a distinct position in head-up display optical engineering. These three entities represent how competitive positioning increasingly depends on software-defined update capabilities rather than hardware specifications alone.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| Thales Group |
| Garmin Ltd |
| Elbit Systems Ltd. |
| L3Harris Technologies, Inc. |
| Northrop Grumman Corporation |
| Aspen Avionics |
| Avidyne Corporation |
| Others |
Supply & Pricing Matrix
OLED panel substitution for legacy LCD architectures is redrawing manufacturing geography toward South Korean and Chinese fabrication facilities while compressing price premiums for organic light-emitting diode flight deck systems. This technology transition simultaneously elevates compound semiconductor foundry pricing power and erodes cost advantages for thin-film transistor liquid crystal incumbent suppliers.
Pricing Analysis
Long-term lifecycle contracts dominate procurement as airlines consolidate avionics purchasing under power-by-the-hour agreements with Lufthansa Technik and ST Engineering. Pricing stratifies across fail-operational, fail-passive, and non-certified tiers with DO-178C software verification grade as the primary differentiation driver. Cost compression in LCD retrofit segments is intensifying because airlines delay replacement cycles amid airframe retirement uncertainty. Military program offices exhibit lowest price sensitivity due to electromagnetic hardening and night vision compatibility requirements.
Supply Chain Analysis
Inventory buffers for indium tin oxide feedstock have compressed to twelve-week levels as thin-film transistor panel manufacturers absorb geopolitical supply anxiety. Manufacturing concentrates in China, South Korea, and Japan for display backplane fabrication and compound semiconductor epitaxy. Supply chain risk centers on single-source vulnerability for aerospace-grade indium refining concentrated in Chinese processing facilities. Distribution runs through avionics integrators in Phoenix, Cedar Rapids, and Toulouse who absorb certification liability for integrated flight deck systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from defense procurement cyclicality as congressional budget pressure rotates engineering talent toward commercial platforms. Fleet retrofit mandates and trainer modernization programs provide demand visibility through the mid-decade.
For Market Incumbents: Secure DO-178C software verification talent pools through targeted acquisition of specialist engineering firms in Bengaluru and Hyderabad. Deepen backward integration into compound semiconductor fabrication partnerships to offset indium supply concentration risk. Lock in long-term airline lifecycle agreements before third-party MRO providers consolidate display replacement authority.
For New Entrants and Emerging Players: Lead with urban air mobility glass cockpit standardization where electric vertical takeoff and landing manufacturers lack established avionics supplier relationships. Target flight school retrofit segments with cost-optimized display kits for Cessna and Piper piston fleets. Pursue offset-driven partnerships with Indian defense contractors facing indigenous component mandates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed avionics software specialists holding concentrated DO-178C certification expertise. Five-to-ten year viability hinges on adaptive display algorithm positioning under EU AI Act safety-critical embedded system frameworks. Watch EASA-FAA regulatory convergence on human factors validation protocols as inflection indicator for transatlantic platform approval economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Display Architecture | Enables post-certification feature updates through over-the-air delivery mechanisms for airline customers. |
| Compound Semiconductor Fabrication Partnership | Secures microLED backlighting supply for Emirates and Singapore Airlines cabin refresh programs. |
| EU AI Act Compliance Pathway | Positions adaptive display algorithms for first-mover advantage in next-generation flight deck architectures. |
| Indian Offset Integration Joint Venture | Meets indigenous component thresholds for fighter and transport aircraft procurement mandates. |
| Power-by-the-Hour Contract Expansion | Captures cockpit display availability revenue through Lufthansa Technik fleet-wide lifecycle agreements. |
Research Methodology
Initial hypotheses were tested against primary input from avionics integration engineers, airline technical procurement directors, military program office acquisition leads, and flight deck human factors specialists and refined through secondary validation against FAA Part 25 airworthiness directives, EASA CS-25 certification amendments, SEC 10-K filings from tier-one suppliers, and customs trade data for indium tin oxide feedstock flows. Bottom-up segment sizing triangulated against top-down market aggregation across display type, technology, application, and end user dimensions.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics through independent modeling of retrofit cycle timing, new platform introduction rates, and technology substitution elasticities. Segmentation dimensions include display type, technology generation, certification pathway, aircraft category, and geographic regulatory cluster. CAGRs derive from logistic diffusion curves fitted to technology adoption patterns and fleet replacement schedules. Forecast inputs incorporate EASA CS-25 Amendment 25-157 compliance timeline extensions and FAA Enhanced Flight Vision System mandate enforcement phasing.
The analysis sits within stated boundaries; outcomes outside sustained defense budget authorization or accelerated airline fleet renewal would require recalibration. Forecasts reflect assumptions regarding regulatory harmonization progress and indium supply chain stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market