
 Digital Glass Military Aircraft Cockpit Systems Market | 2026-2036
Digital Glass Military Aircraft Cockpit Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Glass Military Aircraft Cockpit Systems Market Outlook
Fighter aircraft modernization is pivoting toward multi-domain networked cockpits that fuse sensor data across air, space, and cyber domains. Collins Aerospace leverages its Rockwell Collins heritage in head-up display architectures to sustain long-term supplier relationships with prime contractors. BAE Systems anchors European fighter programs through its Striker II helmet-mounted cueing system and digital display integration. Elbit Systems competes aggressively in the aftermarket retrofit segment, particularly for legacy platform upgrades in Eastern European and Asia-Pacific fleets.
Digital glass military aircraft cockpit systems integrate flat-panel displays, head-up displays, and helmet-mounted sighting systems to replace electromechanical flight instruments with software-driven visual interfaces. These systems typically employ active-matrix liquid crystal or organic light-emitting diode backplanes bonded to laminated glass substrates, processing real-time tactical data at refresh rates exceeding 60 Hz to maintain pilot situational awareness during high-G maneuvers. Head-up display configurations lead product type demand due to their safety-critical role in takeoff, landing, and weapons delivery phases where eyes-out flying remains mandatory. AMOLED technology segments are gaining fastest within the technology dimension as manufacturers pursue wider viewing angles and reduced power budgets for extended mission endurance. Surveillance applications concentrate margin pools because multi-spectral sensor fusion demands the highest display resolution and color fidelity specifications across the application spectrum.
The FAA's Technical Standard Orders for aircraft display systems and EASA's CS-25 certification requirements shape baseline performance thresholds that military variants often exceed through supplemental type certificates. The EU AI Act and emerging NATO STANAG digital interoperability standards are forcing display architectures toward open-systems designs that accommodate rapid software updates without hardware replacement. Stakeholders must monitor how classified data handling requirements intersect with commercial semiconductor supply chains as display controller chip sourcing becomes a sovereignty concern.
Market Dynamics
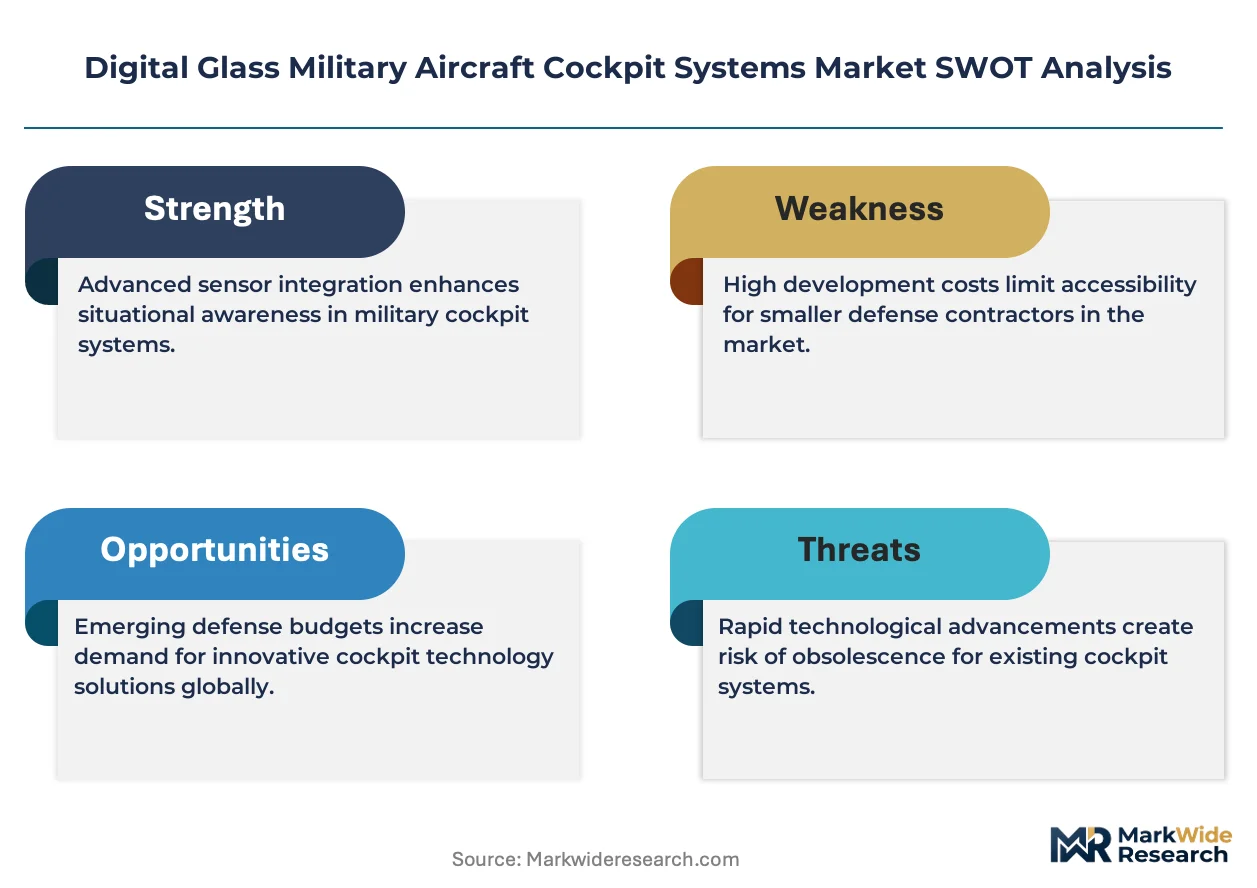
Multi-domain networked cockpit architectures are displacing standalone avionics suites as NATO air forces prioritize sensor fusion across air, space, and cyber operational domains. This structural shift compresses procurement cycles for legacy platform retrofits while elevating display system interoperability requirements.
Growth Catalysts
- Fifth-generation fighter modernization:The United States Department of Defense prioritizes cockpit upgrades for F-35 and F-22 fleets, creating sustained demand for high-refresh-rate display systems capable of processing multi-spectral sensor feeds.
- NATO STANAG digital interoperability standards:These frameworks mandate open-systems architectures that accelerate software update cycles without hardware replacement, expanding addressable market for modular display controllers.
- AMOLED backplane technology:Organic light-emitting diode displays deliver wider viewing angles and reduced power consumption, extending mission endurance for extended-range surveillance and combat air patrol sorties.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor materials for touch-sensitive display layers concentrate in East Asian refining operations, exposing manufacturers to input cost volatility and geopolitical supply disruptions.
- EASA CS-25 certification friction:European military variants must exceed commercial baseline performance thresholds through supplemental type certificates, extending development timelines and qualification expenses.
- Electromechanical instrument residual demand:Analog backup systems retain regulatory acceptance for flight-critical functions in certain national airworthiness frameworks, limiting complete digital replacement.
Strategic Opportunities
- Eastern European legacy fleet retrofit:Former Soviet-era fighter operators in Poland, Romania, and Bulgaria seek NATO-compatible digital glass cockpit suites to achieve interoperability with allied command structures.
- EU AI Act compliance services:The regulation's classified data handling requirements create demand for sovereign display controller chip sourcing and secure supply chain verification.
- Helmet-mounted sighting convergence:Integration of Striker II-type cueing systems with panoramic cockpit displays enables eyes-out weapons targeting without head-up display hardware, reducing aircraft weight and maintenance burden.
Industry Challenges
- Secure semiconductor talent scarcity:Design and verification engineers with security clearance and display controller architecture expertise concentrate in defense contractor clusters around Fort Worth, Texas and Warton, Lancashire.
- Supplemental type certificate timeline compression:FAA and EASA parallel certification pathways for synthetic vision systems demand simultaneous documentation across jurisdictions, straining regulatory affairs capacity.
- Legacy bus architecture integration:MIL-STD-1553 data buses in 1980s-era platforms require protocol bridging hardware to interface with modern Ethernet-based display networks, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Glass Military Aircraft Cockpit Systems Market |
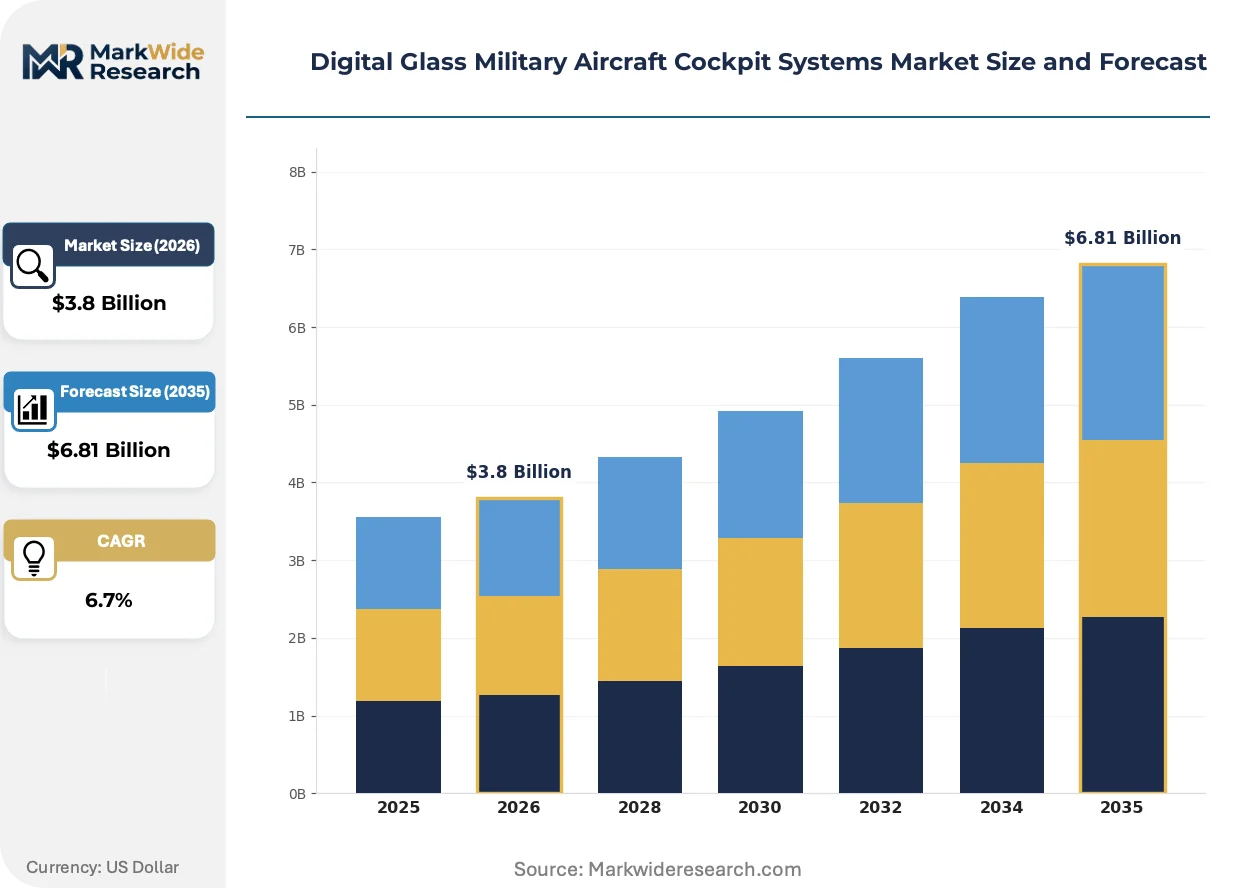
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HUD, MFD, TFOA, PFD Technology: LCD, LED, AMOLED, OLED End User: Military, Defense Contractors, OEMs, Aviation Authorities Application: Surveillance, Navigation, Targeting, Communication |
| Companies Covered | Collins Aerospace, BAE Systems, Honeywell International Inc., Astronautics Corporation of America, Garmin Ltd., Elbit Systems Ltd., Thales Group, Northrop Grumman, L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Glass Military Aircraft Cockpit Systems Market Strategic Shifts
Active-matrix organic light-emitting diode technology is compressing the performance gap between commercial avionics and military specifications. Three developments are restructuring competitive positioning in display subsystem procurement.
AMOLED backplanes bonded to laminated glass substrates are expanding into high-G fighter applications previously reserved for active-matrix liquid crystal alternatives. The United States Air Force and Royal Air Force are field-testing these displays in F-35 and Typhoon upgrade programs. This expansion is compressing the traditional technology refresh cycle from seven years to three years for frontline combat aircraft.
The EU AI Act's classified data handling provisions are forcing display architecture redesigns toward sovereign semiconductor supply chains. Manufacturers must now document chip provenance from wafer fabrication through final assembly, excluding certain East Asian foundry sources. Military variant suppliers in France and Germany are responding by qualifying alternative controller suppliers from domestic semiconductor clusters.
Buyer concentration among prime contractors is consolidating subsystem procurement authority at the platform integrator level. Tier-two display specialists now negotiate directly with Lockheed Martin and BAE Systems rather than through air force material commands. This concentration is most visible in United States fifth-generation programs where sole-source cockpit suite awards have replaced competitive subsystem bidding.
Digital Glass Military Aircraft Cockpit Systems Market Segmentation
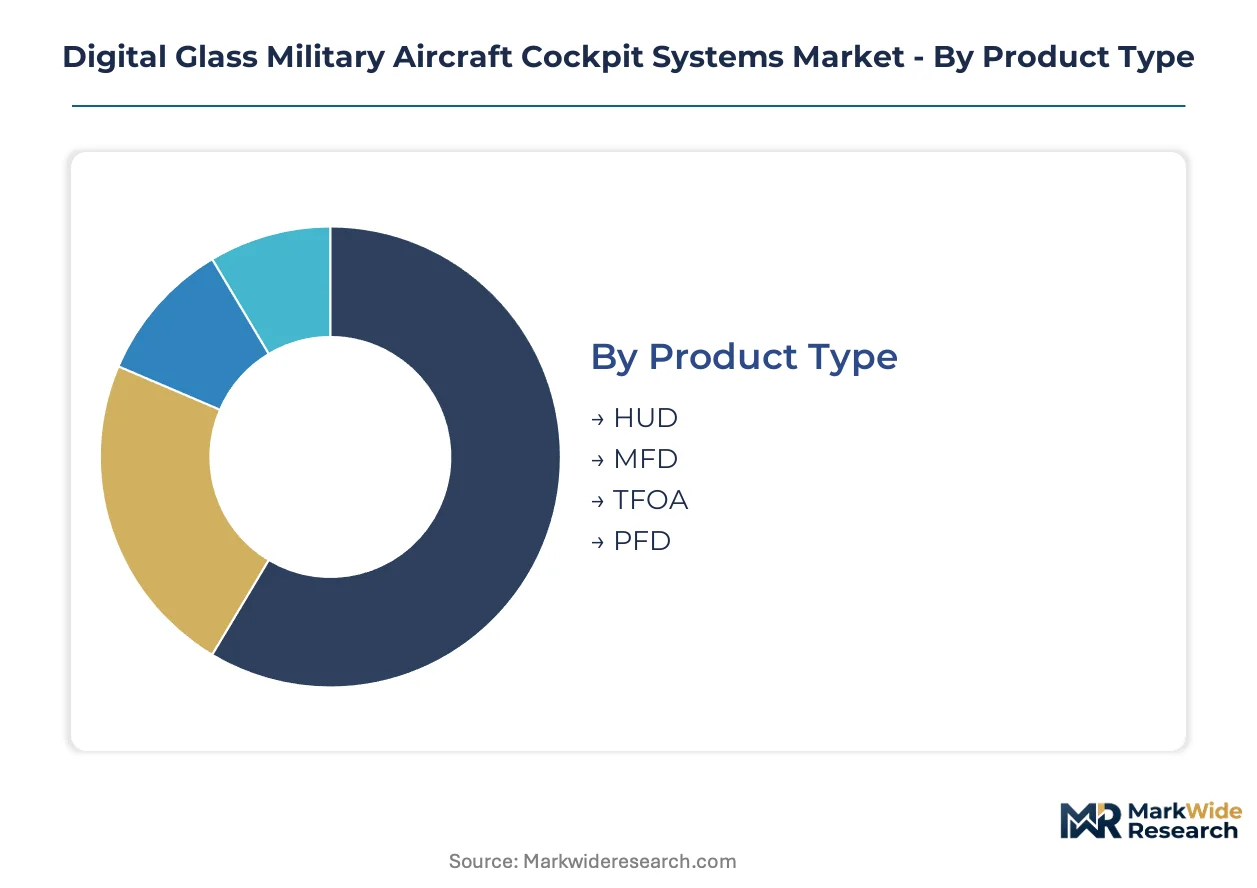
Segmentation in digital glass cockpit systems reveals how integration depth varies from standalone pilot-facing instruments to fully embedded sensor fusion networks. Procurement patterns diverge sharply between retrofit programs requiring backward-compatible form factors and new-build platforms specifying open-architecture standards.
Product Type:
Head-up displays function as standalone safety-critical instruments with dedicated optical paths, while multi-function displays embed deeply into integrated avionics suites requiring extensive software interface layers.
- HUD:Transparent combiner glass projects flight symbology at infinity focus, maintaining pilot eyes-out capability during takeoff and weapons delivery. Demand concentrates in United States fifth-generation fighter modernization where F-35 Block 4 upgrades mandate enhanced field-of-view specifications. FAA Technical Standard Orders for synthetic vision compatibility tighten optical performance thresholds.
- MFD:Multi-function displays consolidate engine instruments, tactical maps, and sensor feeds onto reconfigurable screen real estate. Royal Air Force Typhoon fleet upgrades in the United Kingdom drive procurement for large-format landscape-oriented variants that reduce pilot scan patterns during multi-domain operations.
- TFOA:Touchscreen flight operation avionics replace mechanical switches with gesture-controlled glass interfaces, demanding hardened coatings for gloved-hand operation in turbulence.
- PFD:Primary flight displays present attitude, altitude, and airspeed data with synthetic vision overlays, requiring certification to CS-25 baseline performance thresholds for European military variants.
HUD leads volumes today; MFD is gaining share fastest.
Technology:
Backplane chemistry determines power budgets, viewing angles, and refresh rates—critical parameters for extended combat air patrol endurance and high-G maneuver readability.
- AMOLED:Organic light-emitting diode matrices eliminate backlight assemblies, reducing weight and enabling conformal curved surfaces for helmet-mounted sighting integration. United States Air Force flight testing in F-35 upgrade programs validates performance under sustained high-G loading previously reserved for liquid crystal alternatives.
- LCD:Active-matrix liquid crystal displays with LED edge-lighting dominate legacy platform retrofits where proven supply chains and established qualification data reduce certification risk for Eastern European operators.
- LED:Direct-view LED arrays serve large-format mission crew stations in surveillance platforms where pixel pitch requirements exceed liquid crystal manufacturing limits.
- OLED:Passive-matrix organic alternatives occupy cost-sensitive training aircraft segments where refresh rate requirements remain below combat aircraft thresholds.
LCD retains installed base dominance; AMOLED climbs the fastest.
End User:
Procurement authority concentrates differently across direct military operators, system integrators, and regulatory bodies—each imposing distinct specification hierarchies and approval workflows.
- Military:Air force material commands in the United States, United Kingdom, and Germany issue platform-specific technical requirements that cascade through prime contractor specifications. Direct procurement of cockpit suites for F-35 and Eurofighter Typhoon programs sustains long-term supplier relationships with Collins Aerospace and BAE Systems.
- Defense Contractors:Lockheed Martin and BAE Systems consolidate subsystem procurement authority, negotiating sole-source awards that bypass competitive bidding for display specialists.
- OEMs:Original equipment manufacturers for rotorcraft and unmanned platforms specify commercial-derivative displays adapted through supplemental type certificates.
- Aviation Authorities:FAA and EASA certification pathways for synthetic vision systems establish baseline performance thresholds that military variants must exceed.
Military channels dominate absolute spend; defense contractors are consolidating procurement authority most rapidly.
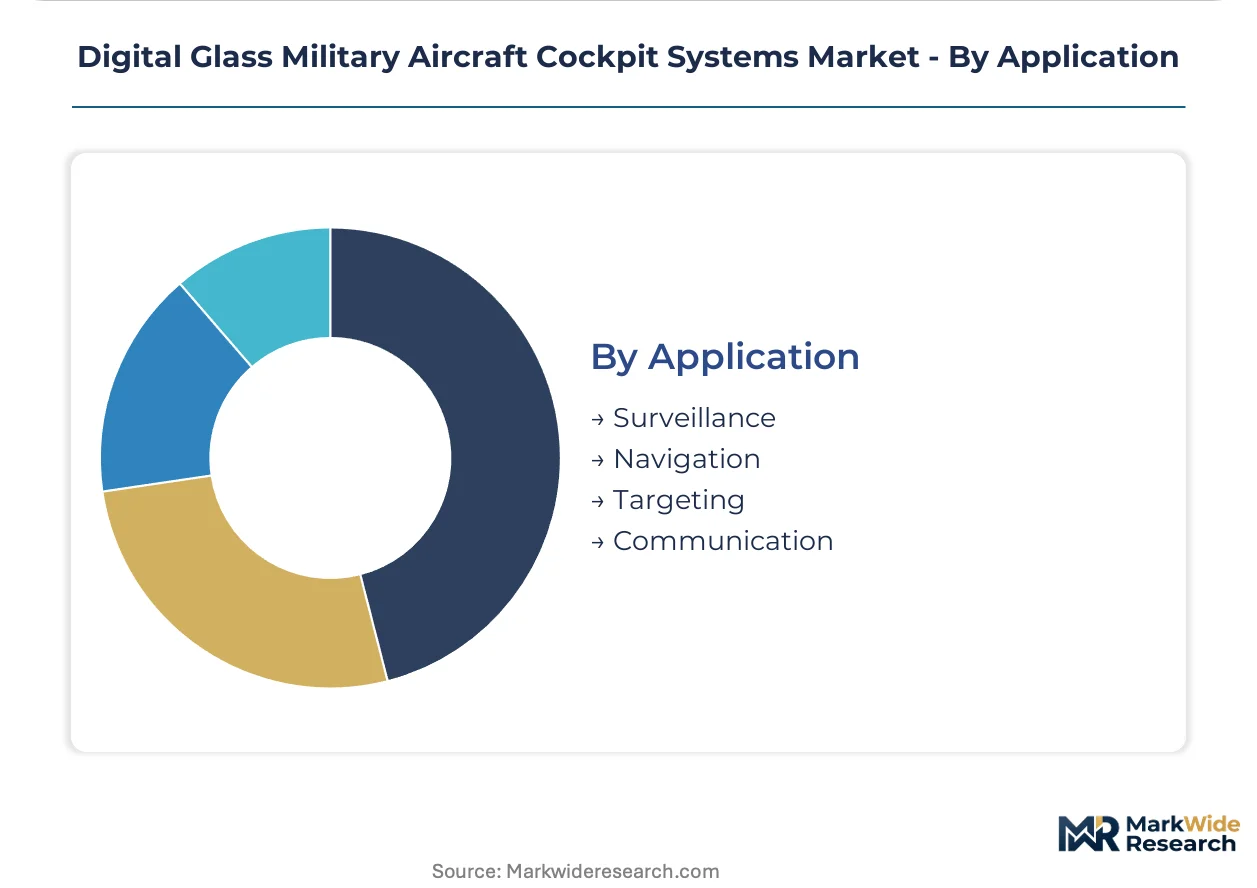
Application:
Functional use cases impose divergent resolution, latency, and color fidelity requirements—surveillance demands the most stringent specifications while communication functions tolerate relaxed parameters.
- Surveillance:Multi-spectral sensor fusion for electro-optical and infrared feeds demands display resolutions exceeding 4K-equivalent pixel density with calibrated color spaces for target identification. NATO airborne early warning programs in the United Kingdom and France specify these systems for mission endurance exceeding twelve hours.
- Targeting:Weapons delivery interfaces require sub-50-millisecond latency from sensor detection to pilot display, with symbology stabilization algorithms for high-G maneuver environments.
- Navigation:Moving map displays with terrain-following overlays integrate GPS and inertial reference data for low-level penetration missions.
- Communication:Data link message displays and frequency management panels occupy lower-tier specification bands, often utilizing commercial-derivative hardware with military environmental qualification.
Surveillance commands premium pricing tiers; targeting shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting display controller fabrication toward jurisdictions with sovereign semiconductor incentives, as the EU AI Act and NATO STANAG interoperability mandates impose divergent compliance costs across production locations.
United States
F-35 Block 4 and F-22 modernization programs drive sustained procurement of high-refresh-rate display systems for fifth-generation fighter fleets. The FAA's Technical Standard Orders for synthetic vision compatibility establish baseline performance thresholds that military variants must exceed through supplemental type certificates. Defense contractor clusters around Fort Worth, Texas concentrate cockpit suite integration expertise for Lockheed Martin prime contracts.
United Kingdom
Royal Air Force Typhoon fleet upgrades generate demand for large-format multi-function displays optimized for multi-domain networked operations. EASA CS-25 certification requirements for European military variants extend development timelines compared to commercial baselines. The Warton, Lancashire industrial complex anchors BAE Systems display integration capabilities for Eurofighter programs.
Germany
Eurofighter Typhoon Tranche 4 procurement and NATO-compatible interoperability upgrades sustain demand for open-architecture display controllers. The EU AI Act's classified data handling provisions are forcing domestic semiconductor qualification to replace East Asian foundry sources. Bavaria's defense electronics corridor around Munich hosts display controller design verification facilities with security-cleared engineering talent.
Israel
Helmet-mounted sighting system exports and legacy platform retrofit contracts across Eastern European and Asia-Pacific fleets drive aftermarket display subsystem demand. The country's national defense procurement authority prioritizes indigenous display controller architectures for sovereign supply chain security. Tel Aviv-area engineering clusters specialize in high-G environment display validation for combat aircraft applications.
Poland
Former Soviet-era fighter modernization programs seek NATO-compatible digital glass cockpit suites to achieve interoperability with allied command structures. National defense modernization funds allocate specifically for display system upgrades that meet STANAG digital standards. The Warsaw-Łódź industrial corridor hosts emerging integration facilities for Western display subsystem retrofit into legacy airframes.
Digital Glass Military Aircraft Cockpit Systems Market Competitive Environment
Platform integrator consolidation dominates the current landscape, as prime contractors compress procurement authority from air force material commands toward sole-source cockpit suite awards. The vendor structure concentrates around tier-one platform integrators and tier-two subsystem specialists with established security clearances. Three archetypes define competitive positioning: aerospace conglomerates with avionics heritage, defense-electronics specialists with display controller expertise, and aftermarket retrofit contractors with legacy platform engineering capabilities. M&A activity and strategic partnerships represent the dominant competitive vectors, as display specialists seek security-cleared engineering talent and platform integrators pursue vertical control over cockpit subsystem supply.
Among aerospace conglomerates with avionics heritage, Collins Aerospace and BAE Systems exemplify the integrated platform supplier archetype, leveraging long-term prime contractor relationships to sustain cockpit suite procurement authority. Elbit Systems occupies a position within the aftermarket retrofit specialist tier, capturing legacy platform upgrade demand across NATO expansion markets. These three anchors illustrate how competitive positioning stratifies between platform-integrated incumbents and segment-focused challengers.
| Leading Market Players |
|---|
| Collins Aerospace |
| BAE Systems |
| Honeywell International Inc. |
| Astronautics Corporation of America |
| Garmin Ltd. |
| Elbit Systems Ltd. |
| Thales Group |
| Northrop Grumman |
| L3Harris Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Indium tin oxide spot pricing volatility cascades through display controller fabrication into three-tier pricing structure across premium, standard, and economy levels for military cockpit systems. Input cost pressure from East Asian refining concentration compresses margins for AMOLED backplane suppliers while elevating qualification premiums for sovereign-sourced alternatives.
Pricing Analysis
Prime contractor direct-to-OEM discounts dominate procurement, with sole-source cockpit suite awards replacing competitive subsystem bidding. Price differentiation separates ITAR-compliant certified variants from commercial-derivative hardware, with volume scale driving standard-tier procurement for fleet upgrades. Pricing pressure stems from NATO STANAG interoperability mandates requiring open-architecture redesigns. Eastern European retrofit operators exhibit highest price sensitivity due to national defense budget constraints; United States fifth-generation programs show lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Dual-sourcing requirements for transparent conductor materials mandate multi-supplier qualification across Taiwanese, South Korean, and domestic German foundry operations. Controller chip fabrication draws from Taiwan's semiconductor clusters, South Korea's OLED material production, and emerging Bavarian sovereign facilities. Supply chain risk centers on single-source vulnerability for indium refining concentrated in Chinese state-owned enterprises. Distribution runs through prime contractor integration hubs at Fort Worth, Texas and Warton, Lancashire rather than direct air force material command procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act classified data handling provisions and NATO STANAG digital interoperability standards continuously generate upgrade demand across installed fighter fleets.
For Market Incumbents: Acquire security-cleared engineering talent pools to defend against emerging sovereign semiconductor specialists. Secure supplemental type certificate pre-qualification data packages to compress development timelines for F-35 Block 4 and Eurofighter Typhoon Tranche 4 programs. Backward integration into domestic wafer fabrication addresses EU AI Act provenance documentation requirements while excluding East Asian foundry exposure.
For New Entrants and Emerging Players: Enter via aftermarket retrofit specialization for Soviet-era fighter platforms in Poland, Romania, and Bulgaria where NATO interoperability mandates create addressable demand. Target helmet-mounted sighting convergence opportunities as Striker II-type systems displace head-up display hardware weight. Pursue sole-source awards for display controller subsystems through direct prime contractor negotiation rather than air force material command channels.
For Investors and Strategic Acquirers: Asymmetric upside sits with sovereign semiconductor specialists possessing security-cleared design verification capabilities. Long-term viability hinges on sustained fifth-generation modernization budgets and NATO expansion fleet interoperability requirements. Monitor F-35 Block 4 upgrade program award announcements as inflection indicators for cockpit suite procurement authority consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Semiconductor Qualification | EU AI Act compliance enables exclusion of East Asian foundry sources from military supply chains. |
| Helmet-Mounted Sighting Integration | Striker II-type cueing convergence reduces aircraft weight and maintenance burden for combat platforms. |
| Legacy Platform Retrofit Specialization | Eastern European NATO expansion markets generate sustained demand for backward-compatible form factors. |
| Open-Architecture Controller Development | NATO STANAG interoperability mandates accelerate software update cycles without hardware replacement. |
| Supplemental Type Certificate Pre-Qualification | FAA and EASA parallel certification pathways compress development timelines for synthetic vision systems. |
Study Parameters
Direct dialogue with platform integration engineers, display controller architects, regulatory affairs specialists at aviation authorities, and air force procurement officers grounded qualitative assessment. Secondary validation drew from FAA Technical Standard Orders documentation, EASA CS-25 certification records, NATO STANAG publications, and defense contractor SEC filings. Bottom-up segment sizing triangulated against top-down military aviation budget allocation analysis.
Segment-level outputs across product type, technology backplane chemistry, end user procurement channel, and application functional use case informed the analytical framework over the projection horizon. CAGRs derived from platform modernization program timelines, technology refresh cycle compression observed in F-35 and Typhoon upgrade programs, and AMOLED adoption trajectory in high-G fighter applications. Forecast inputs incorporated supplemental type certificate timeline data and sovereign semiconductor qualification pipeline status.
Inputs from aviation authority certification databases and prime contractor procurement disclosures were available through the study window; gaps in classified program budget allocations introduce uncertainty bands around fifth-generation platform upgrade timing. Forecasts reflect documented assumptions regarding NATO STANAG implementation schedules and EU AI Act enforcement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market