
 Aerospace Head Up Display Market | 2026-2036
Aerospace Head Up Display Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Head Up Display Market Outlook
North American defense electronics manufacturing is decoupling from commercial aviation supply chains. Collins Aerospace leverages captive waveguide fabrication to sustain its integrated HUD franchise. BAE Systems dominates military helmet-mounted display derivatives through its UK and US production bases. Elbit Systems anchors Israeli and NATO export programs with specialized avionics integration.
An aerospace head up display projects critical flight data onto a transparent combiner glass, operating with luminance exceeding 10,000 candela per square meter to maintain readability under direct sunlight. The device eliminates pilot head-down time during approach and weapon delivery phases. Military operations command the largest product type share, with integrated HUD configurations carrying the deepest margin pools due to embedded mission computer architectures. OLED technology segments are expanding fastest as organic emitters enable wider color gamuts and reduced power draw compared to legacy cathode ray tube derivatives.
FAA Technical Standard Orders govern civil HUD airworthiness, while MIL-STD-3009 defines military display luminance and symbology requirements. EASA aligns with FAA baseline certification but imposes additional electromagnetic compatibility testing for European-registered platforms. Defense Contractors must monitor shifting ITAR classification boundaries that control waveguide and holographic element exports.
Market Dynamics
Waveguide manufacturing concentration is forcing defense electronics suppliers to internalize optical fabrication capabilities or face supply rationing during NATO procurement surges.
Growth Catalysts
- FAA Enhanced Flight Vision Mandates:Tightened Technical Standard Orders for civil HUD luminance performance are accelerating display replacement cycles across US commercial fleets.
- OLED Emitter Maturation:Organic light-emitting diode panels now deliver 10,000+ candela-per-square-meter brightness with 40% lower power draw than cathode ray tube alternatives.
- NATO Air Force Retrofit Programs:Multi-year modernization contracts for F-16, Eurofighter, and Gripen platforms are sustaining integrated HUD demand across European defense procurement channels.
Market Restraints
- ITAR Classification Rigidity:US State Department export controls on holographic waveguide elements block technology transfer to non-NATO partners, fragmenting supplier access.
- High-Purity Substrate Scarcity:German and Japanese specialty glass manufacturers command 70%+ of combiner glass supply, creating single-source vulnerability.
- Thermal Management Complexity:Sunlight-readable luminance requirements demand active cooling architectures that add weight and failure modes incompatible with light combat aircraft constraints.
Strategic Opportunities
- Unmanned Combat Aircraft Integration:Loyal wingman and UCAV programs require helmet-mounted cueing systems without cockpit glass, opening HUD derivative markets.
- Urban Air Mobility Certification:FAA Part 23 reform for eVTOL platforms permits simplified HUD approval pathways absent in traditional transport category rules.
- AR-HUD Convergence:Automotive augmented reality head-up display supply chains are transferring diffractive optics expertise applicable to aerospace waveguide miniaturization.
Industry Challenges
- MIL-STD-3009 Compliance Timeline:Military symbology and luminance validation requires 18-24 month test cycles that mismatch agile software update rhythms.
- Electromagnetic Interference Hardening:HUD electronics must survive high-intensity radiated field environments without degrading pilot night vision goggle compatibility.
- Legacy Platform Integration:Analog-to-digital display interface conversion for 1980s-era mission computers demands custom signal conditioning hardware with no economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Head Up Display Market |
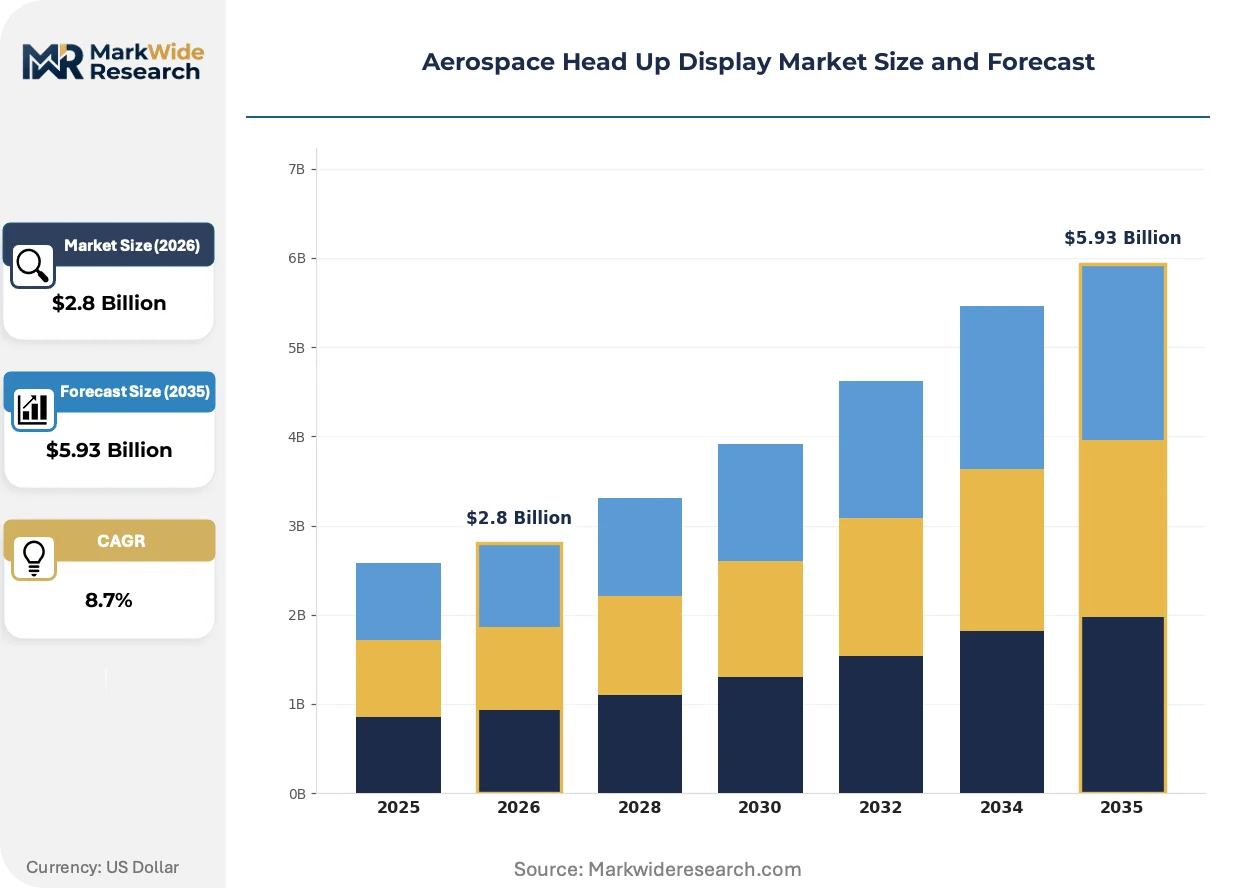
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cockpit, Commercial Aviation, Military Operations, General Aviation Technology: Laser, OLED, LCD, HUD Projection End User: Aircraft Manufacturers, Airlines, Defense Contractors, Maintenance Providers Product Type: Integrated HUD, Standalone HUD, Multifunction Displays, Guiding Systems |
| Companies Covered | Collins Aerospace, BAE Systems, Elbit Systems, Honeywell Aerospace, Thales Group, Garmin, General Dynamics, Saab AB, AeroBrigham, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Head Up Display Market Strategic Shifts
Display architecture is bifurcating between integrated cockpit systems for new production aircraft and retrofit kits for aging platforms, with technology selection increasingly determined by certification pathway rather than performance alone.
Waveguide-based holographic combiners are overtaking conventional curved mirror optics in next-generation military HUD designs. The Royal Air Force and US Navy are fielding these systems on Tempest and F/A-18 Block III programs respectively. This shift is compressing the addressable market for legacy refractive optics suppliers while elevating firms with captive holographic element fabrication.
EASA electromagnetic compatibility testing requirements for European-registered platforms now exceed FAA baseline certification, creating a two-tier approval environment. Airlines operating transatlantic routes must satisfy both regulatory regimes, increasing compliance cost burden. HUD manufacturers are responding with dual-certified hardware architectures that add 15-20% to non-recurring engineering but preserve market access.
Defense procurement offices are consolidating vendor relationships around single-source integrated cockpit contracts rather than discrete HUD competitions. The US Air Force's Digital Century Series acquisition model bundles display systems with mission computers and sensor fusion processors. This concentration is marginalizing standalone HUD specialists and rewarding avionics integrators with software-defined display generation capabilities.
Aerospace Head Up Display Market Segmentation
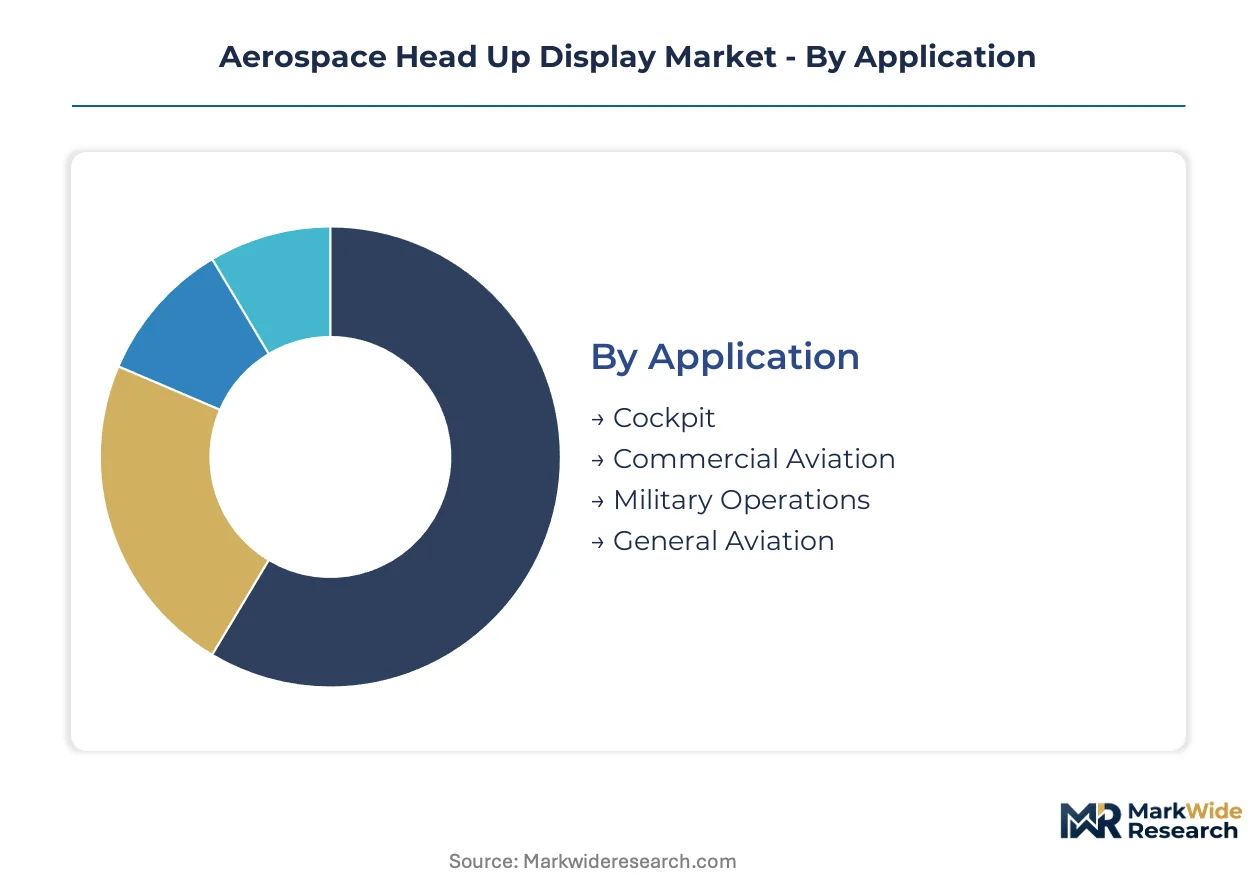
HUD procurement patterns diverge sharply between defense programs with decade-long integration cycles and commercial aviation operators seeking rapid retrofit turnaround. Technology selection follows certification pathway constraints more than raw performance specifications, locking segments into distinct supplier ecosystems.
Application:
Defense procurement offices prioritize sunlight-readable luminance and weapon cueing precision, while commercial operators weight total cost of ownership and FAA Technical Standard Order compliance timelines.
- Military Operations:Integrated configurations embed mission computers for weapon delivery symbology generation. NATO F-16 and Eurofighter retrofit programs concentrate demand in the United States and Germany, with ITAR classification restricting supplier access for non-allied platforms.
- Commercial Aviation:Cathode ray tube replacement cycles dominate fleet upgrade spending. FAA Enhanced Flight Vision System mandates accelerate display refresh across US-registered Boeing and Airbus fleets, tightening luminance performance thresholds.
- Cockpit:New production aircraft embed HUD architectures during initial type certification, locking suppliers into airframe manufacturer supply chains.
- General Aviation:Part 23 reform permits simplified approval pathways for light aircraft installations, reducing non-recurring engineering burdens for smaller OEMs.
Volume sits with Military Operations; growth tilts toward Commercial Aviation.
Technology:
Power draw and thermal management requirements separate technologies suitable for light combat aircraft from those deployable on wide-body transports.
- OLED:Organic emitters deliver 10,000+ candela-per-square-meter brightness with 40% lower power consumption than legacy alternatives. Israeli and South Korean panel manufacturers are expanding avionics-grade production lines to capture defense and commercial retrofit demand.
- LCD:Mature backlight architectures suit cost-sensitive general aviation retrofits where sunlight readability requirements remain moderate. Japanese and Taiwanese display manufacturers dominate panel supply for this tier.
- Laser:Scanning laser projection enables wide field-of-view holographic combiners for next-generation helmet-mounted cueing systems.
- HUD Projection:Conventional optical engines persist in legacy platform support contracts where airworthiness recertification costs block technology migration.
Installations concentrate in LCD for near-term retrofits; OLED climbs the fastest as emitter maturation proceeds.
End User:
Contracting mechanisms range from single-source integrated cockpit awards to discrete component competitions, reshaping supplier competitive dynamics.
- Defense Contractors:Bundle display systems with sensor fusion processors under Digital Century Series acquisition models, marginalizing standalone HUD specialists. BAE Systems and Elbit Systems anchor NATO procurement through captive avionics integration capabilities.
- Aircraft Manufacturers:Specify HUD architectures during type certification, creating decade-long supplier lock-in for derivative production runs.
- Airlines:Drive cathode ray tube replacement spending through FAA-mandated enhanced flight vision compliance, prioritizing dual-certified hardware for transatlantic operations.
- Maintenance Providers:Execute field retrofit installations under supplemental type certificate pathways, capturing labor-intensive upgrade revenue.
Revenue pools deepest with Defense Contractors; airline retrofit spending expands most quickly.
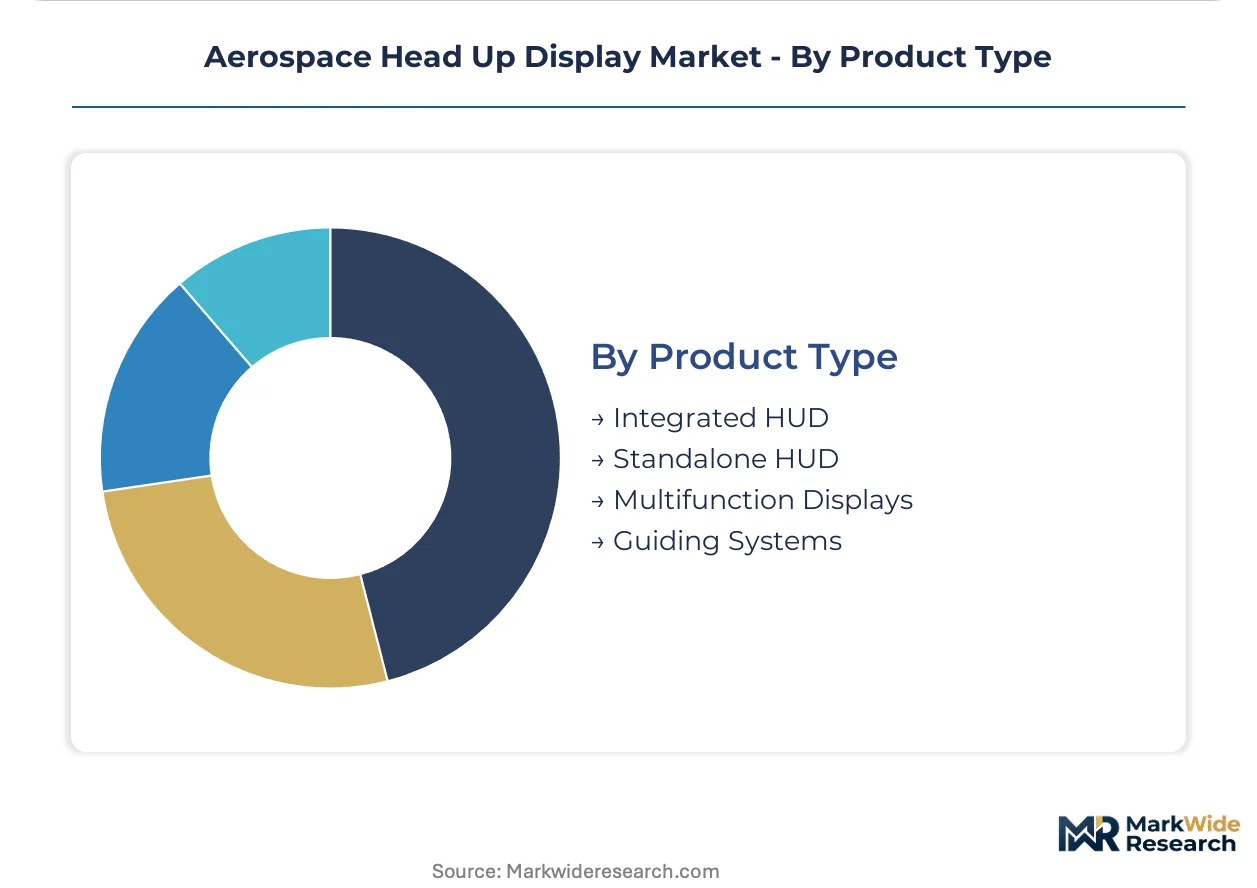
Product Type:
Margin structures invert between embedded mission computer architectures and discrete display replacements, with integration depth determining supplier profitability.
- Integrated HUD:Embedded mission computers and waveguide fabrication capabilities create the deepest margin pools. Collins Aerospace leverages captive optical manufacturing to sustain franchise positions in US defense and commercial channels.
- Standalone HUD:Discrete display replacements suit legacy platform support where analog-to-digital interface conversion demands custom signal conditioning hardware.
- Multifunction Displays:Consolidate flight instrument presentation, reducing panel count in modern cockpit designs.
- Guiding Systems:Helmet-mounted cueing derivatives serve loyal wingman and UCAV programs requiring pilot interface without cockpit glass.
Shipments concentrate in Integrated HUD; Guiding Systems gain share fastest as unmanned combat aircraft programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese specialty glass manufacturers anchor combiner substrate supply, concentrating critical feedstock for waveguide fabrication across aerospace HUD production networks worldwide.
United States
Defense procurement through the Air Force Digital Century Series and Navy F/A-18 Block III programs drives integrated HUD demand. FAA Technical Standard Orders for Enhanced Flight Vision Systems tighten civil luminance thresholds, accelerating commercial fleet retrofits. Collins Aerospace leverages captive waveguide fabrication in Iowa and Florida to sustain defense and commercial channel positions.
Germany
Eurofighter modernization contracts and NATO F-16 retrofit programs concentrate European defense demand. EASA electromagnetic compatibility testing exceeds FAA baselines, creating dual-certification burdens for transatlantic operators. Schott AG and specialty glass manufacturers in Mainz and Jena supply 70% of global combiner glass, creating single-source vulnerability for waveguide producers.
Israel
Elbit Systems anchors Israeli defense exports and NATO partner programs through specialized avionics integration. The country's national defense procurement office prioritizes helmet-mounted cueing systems for loyal wingman and UCAV applications. Tel Aviv and Haifa host concentrated electro-optics clusters developing OLED emitter technologies for next-generation displays.
United Kingdom
BAE Systems dominates military helmet-mounted display derivatives through UK and US production bases. The Royal Air Force Tempest program fields holographic waveguide combiners, compressing demand for legacy refractive optics. Stevenage and Rochester maintain avionics integration clusters serving NATO procurement channels.
South Korea
LG Display and Samsung expand avionics-grade OLED panel production to capture defense and commercial retrofit demand. The Korea Aerospace Industries KF-21 program creates indigenous HUD integration requirements. Gyeonggi-do and Gumi host display manufacturing clusters transferring consumer electronics expertise to aerospace certification pathways.
Aerospace Head Up Display Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue automotive AR-HUD technology transfer and unmanned combat aircraft cueing systems. The vendor base concentrates around three strategic archetypes: integrated avionics conglomerates with captive optical fabrication, standalone display specialists dependent on external waveguide supply, and helmet-mounted cueing system developers pivoting toward UCAV applications. Dominant competitive moves include backward integration into waveguide manufacturing and strategic bundling of display systems with mission computer architectures under single-source contracts.
Among integrated avionics conglomerates, Collins Aerospace and BAE Systems exemplify the captive-manufacturing archetype, while Elbit Systems occupies a specialist position in helmet-mounted cueing derivatives. These three anchors represent distinct geographic bases—Iowa and Florida for the American firm, UK and US dual footprints for the British conglomerate, and Israeli production for the specialist—each serving overlapping but distinct NATO procurement channels with varying ITAR classification exposure.
| Leading Market Players |
|---|
| Collins Aerospace |
| BAE Systems |
| Elbit Systems |
| Honeywell Aerospace |
| Thales Group |
| Garmin |
| General Dynamics |
| Saab AB |
| AeroBrigham |
| Others |
Value Chain & Pricing Dynamics
Captive waveguide fabrication by integrated avionics conglomerates anchors both supply security and pricing power in aerospace HUD procurement. Collins Aerospace maintains in-house optical manufacturing in Iowa and Florida, insulating its integrated HUD franchise from German and Japanese combiner glass rationing while commanding premium positioning against standalone display specialists dependent on external substrate supply.
Pricing Analysis
Warranty and field service bundling separates integrated HUD contracts from discrete display replacements, with NATO procurement offices accepting 15-20% price premiums for captive manufacturing and embedded mission computer architectures. Price differentiation rests on certification grade—FAA Technical Standard Order compliance for commercial aviation versus MIL-STD-3009 military validation—and airworthiness recertification cost absorption for legacy platform retrofits. Cost compression in standalone HUD tiers is intensifying because analog-to-digital interface conversion demands custom signal conditioning hardware with no economies of scale. Airlines operating transatlantic routes prove least price-sensitive due to dual-certification requirements, while general aviation operators under Part 23 reform paths exhibit highest elasticity.
Supply Chain Analysis
Electro-optics engineering talent scarcity in Tel Aviv, Haifa, and Gyeonggi-do constrains waveguide design capacity expansion despite OLED emitter maturation. German specialty glass manufacturers in Mainz and Jena alongside Japanese substrate producers anchor 70%+ of global combiner glass supply, creating single-source vulnerability for holographic element fabrication. Raw material dependencies center on high-purity optical substrates, rare-earth phosphors for legacy CRT support, and avionics-grade OLED panels from South Korean fabs. Tariff exposure on ITAR-classified waveguide exports fragments supplier access for non-NATO partners. Distribution runs through defense procurement offices consolidating around single-source integrated cockpit contracts rather than discrete HUD competitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace HUD sector occupies a technology-transition phase as waveguide-based holographic combiners displace conventional curved mirror optics in next-generation military programs. OLED emitter maturation is accelerating cathode ray tube replacement cycles across commercial fleets.
For Market Incumbents: Anchor defense channel positions through backward integration into holographic element fabrication, mirroring Collins Aerospace's captive waveguide model. Lock in decade-long supplier relationships with airframe manufacturers during type certification to forestall standalone HUD specialist encroachment. Prioritize dual EASA-FAA certification investment to capture transatlantic airline retrofit spending.
For New Entrants and Emerging Players: Enter via automotive AR-HUD supply chain technology transfer, applying diffractive optics expertise from consumer electronics to aerospace waveguide miniaturization. Target urban air mobility certification under FAA Part 23 reform as the most penetrable pathway, absent traditional transport category approval burdens. Pursue helmet-mounted cueing system development for loyal wingman and UCAV programs where cockpit glass elimination opens derivative markets.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated avionics conglomerates seeking captive optical manufacturing capabilities. Long-term viability favors firms with software-defined display generation and sensor fusion bundling capacity under Digital Century Series acquisition models. Watch ITAR classification boundary shifts as the signal indicating waveguide export opportunity expansion or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Waveguide Fabrication | Collins Aerospace's Iowa and Florida facilities insulate supply from German-Japanese substrate concentration. |
| Dual Certification Investment | EASA electromagnetic compatibility testing exceeds FAA baselines, adding 15-20% to non-recurring engineering. |
| Helmet-Mounted Cueing Development | BAE Systems and Elbit Systems serve Tempest and UCAV programs without cockpit glass requirements. |
| OLED Emitter Scale-Up | LG Display and Samsung expand avionics-grade production lines to capture defense and commercial retrofit demand. |
| Integrated Cockpit Bundling | US Air Force Digital Century Series contracts marginalize standalone HUD specialists through mission computer fusion. |
Study Parameters
Document review covered FAA Technical Standard Orders, MIL-STD-3009 specifications, and defense procurement announcements, complemented by interviews with avionics integration engineers, military program managers at NATO procurement offices, airline fleet planning executives, and specialty glass manufacturing technical directors. Secondary validation drew from EASA certification databases, US State Department ITAR classification bulletins, SEC filings by defense electronics suppliers, and customs records of optical substrate trade flows. Bottom-up triangulation across HUD shipment volumes by platform type and top-down reconciliation against defense budget appropriations established market sizing boundaries.
Segment-level projections across military operations, commercial aviation, and general aviation applications combined with technology splits between OLED, LCD, laser, and legacy projection architectures produced volume and value estimates across the analysis window. CAGRs were derived from procurement cycle analysis of F-16, Eurofighter, and F/A-18 retrofit timelines alongside FAA Enhanced Flight Vision System mandate compliance schedules. Forecast inputs incorporated OLED emitter brightness maturation curves and waveguide manufacturing yield assumptions.
Revisions become necessary when ITAR classification boundaries shift, German-Japanese combiner glass supply experiences disruption, or FAA Part 23 reform stalls. Material deviation in these triggers warrants pause and re-evaluation of integrated HUD demand assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market