
 Aviation Headsets Market | 2026-2036
Aviation Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Headsets Market Analysis
Asian electronics manufacturing clusters are repositioning component supply for aviation audio systems. Bose Corporation leverages proprietary active noise cancellation patents to sustain premium positioning in cockpit equipment. David Clark Company anchors its presence through MIL-SPEC certification depth and domestic production control.
Aviation headsets integrate acoustic drivers, noise-attenuating ear cups, and microphone assemblies to deliver intelligible communication in ambient noise environments exceeding 100 decibels; active noise cancelling variants employ phase-inversion circuitry to suppress low-frequency engine and propeller signatures. Passive noise reduction headsets occupy the value-tier segment where private pilots and flight schools prioritize cost over electronic sophistication. Bluetooth connectivity is displacing wired interfaces in training simulators and ground operations as tablet-based electronic flight bag adoption spreads.
FAA Technical Standard Orders govern airworthiness certification for aviation headsets installed in certified aircraft, while EU REACH and RoHS directives constrain hazardous substance use in European-sold electronics. Military procurement through MIL-STD-810G and MIL-STD-461 standards creates a parallel demand channel with distinct durability and electromagnetic compatibility requirements. Stakeholders must track evolving ICAO cabin safety guidance and emerging lithium battery transport rules that affect wireless headset power system design.
Market Dynamics
FAA certification tightening for active noise reduction is compressing supplier qualification timelines while flight training fleet modernization accelerates replacement cycles across commercial and general aviation segments.
Growth Catalysts
- TSO-C139a Certification Mandate:FAA airworthiness standards for active noise cancelling headsets are pulling passive-only models out of certified aircraft installations, forcing equipment upgrades at Part 121 and Part 135 operators.
- Flight School Fleet Expansion:Pilot training academies in the United States are scaling simulator-based instruction that requires Bluetooth-enabled communication headsets compatible with tablet-based electronic flight bag ecosystems.
- MIL-STD-810G Procurement:Military aviation contracts for tactical headsets are sustaining domestic manufacturing capacity that cross-subsidizes commercial product development and testing infrastructure.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production for wireless aviation headsets clusters in East Asian manufacturing hubs, exposing lead times to geopolitical friction and export control volatility.
- Acoustic Driver Component Sourcing:Precision neodymium magnet suppliers are consolidating in China, constraining alternative sourcing for noise-cancelling driver assemblies.
- REACH Substance Restrictions:EU RoHS and REACH directives are phasing out specific flame retardants and plasticizers used in legacy headset housings, forcing material reformulation without performance degradation.
Strategic Opportunities
- Unmanned Aerial Systems Ground Control:Drone operator headsets for beyond-visual-line-of-sight operations represent an uncaptured application segment with distinct audio isolation requirements and lighter weight specifications.
- Domestic Production Incentives:US Department of Defense Buy American provisions are creating procurement preference for headsets with verified domestic supply chains and assembly operations.
- Bluetooth 5.3 Audio Convergence:Integration of low-latency wireless protocols with existing aviation intercom systems is opening retrofit opportunities in privately owned aircraft fleets.
Industry Challenges
- Acoustic Engineer Talent Scarcity:Specialized expertise in active noise cancellation algorithm development for high-noise aviation environments is concentrated at a handful of defense contractors and audio technology firms.
- Certification Timeline Compression:FAA TSO validation cycles for new active noise cancelling designs are extending to 18-24 months, delaying revenue recognition for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Headsets Market |
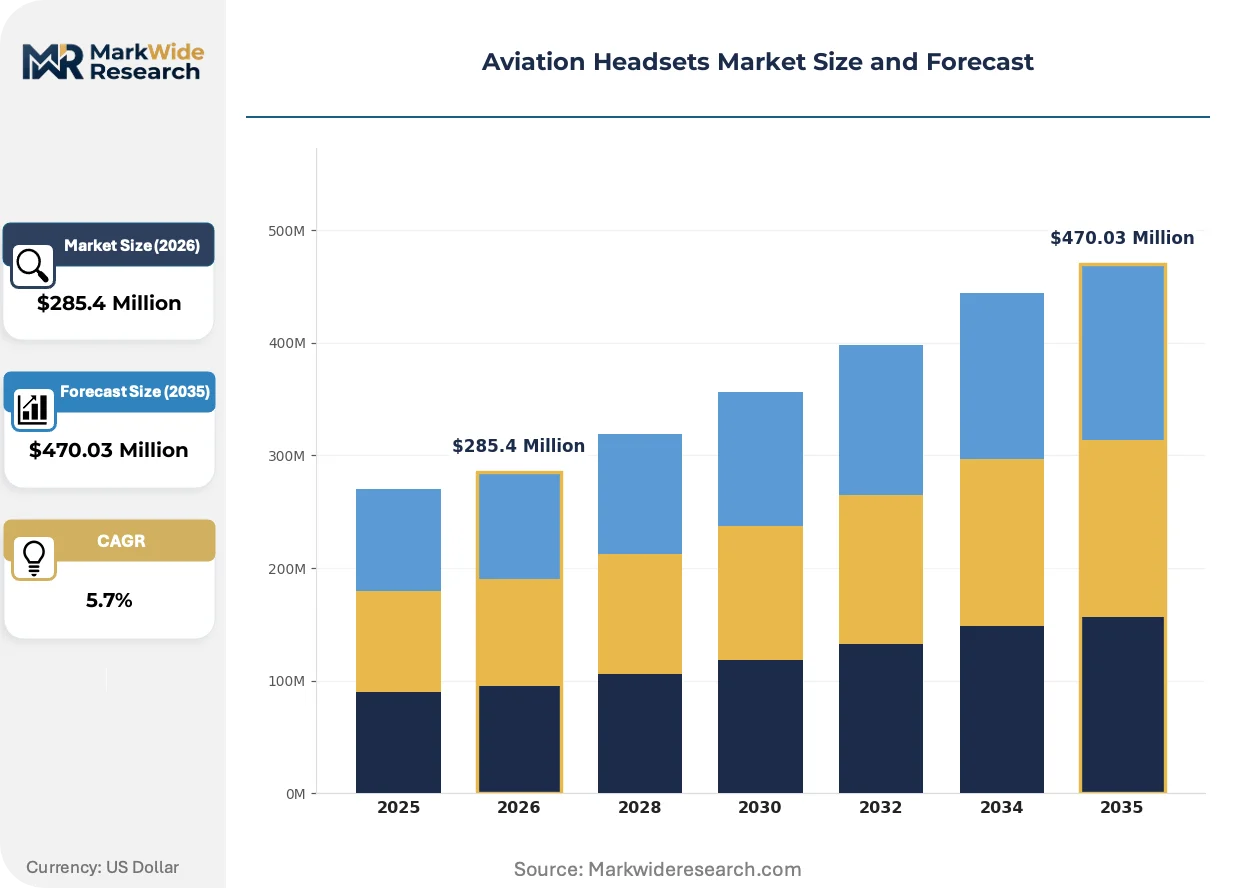
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Noise Cancelling, Passive Noise Reduction, Communication Headsets, Flight Crew Headsets End User: Commercial Pilots, Private Pilots, Flight Instructors, Military Personnel Connectivity: Wired, Bluetooth, Wi-Fi, USB Usage Environment: Cockpit, Training Simulator, Ground Operations, Air Traffic Control |
| Companies Covered | Bose Corporation, David Clark Company, Lightspeed Aviation, 3M Company, Sennheiser Electronic GmbH & Co. KG, Faro Aviation, Flightcom Corporation, Bosch Security Systems, Plantronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Headsets Market Emerging Trajectories
Aviation headset architecture is pivoting from analog wired systems toward digital signal processing platforms that integrate with cockpit avionics and portable electronic flight bag devices.
Hybrid active-passive noise reduction technology is expanding into the general aviation training segment. Flight schools operating high-utilization Cessna and Piper fleets are adopting mid-tier hybrid headsets to reduce student fatigue during extended cross-country instruction. This technology is expanding into price-sensitive buyer categories previously served by purely passive designs, compressing the addressable market for basic models.
EU REACH substance restrictions are accelerating material transitions in headset manufacturing. The European Chemicals Agency's expanded candidate list is forcing suppliers to eliminate specific phthalates and halogenated flame retardants from ear cup cushions and cable sheathing. Manufacturers serving European commercial operators are responding with accelerated polymer qualification programs and dual-stock inventory strategies.
Direct-to-operator sales channels are displacing traditional aviation retail distribution. Part 91 owner-operators and small flight schools are purchasing headsets through manufacturer websites and specialized e-commerce platforms rather than brick-andarero FBO pilot shops. This pattern is most pronounced in the United States, where fractional ownership programs and flying clubs are consolidating procurement decisions at the fleet level.
Aviation Headsets Market Segmentation
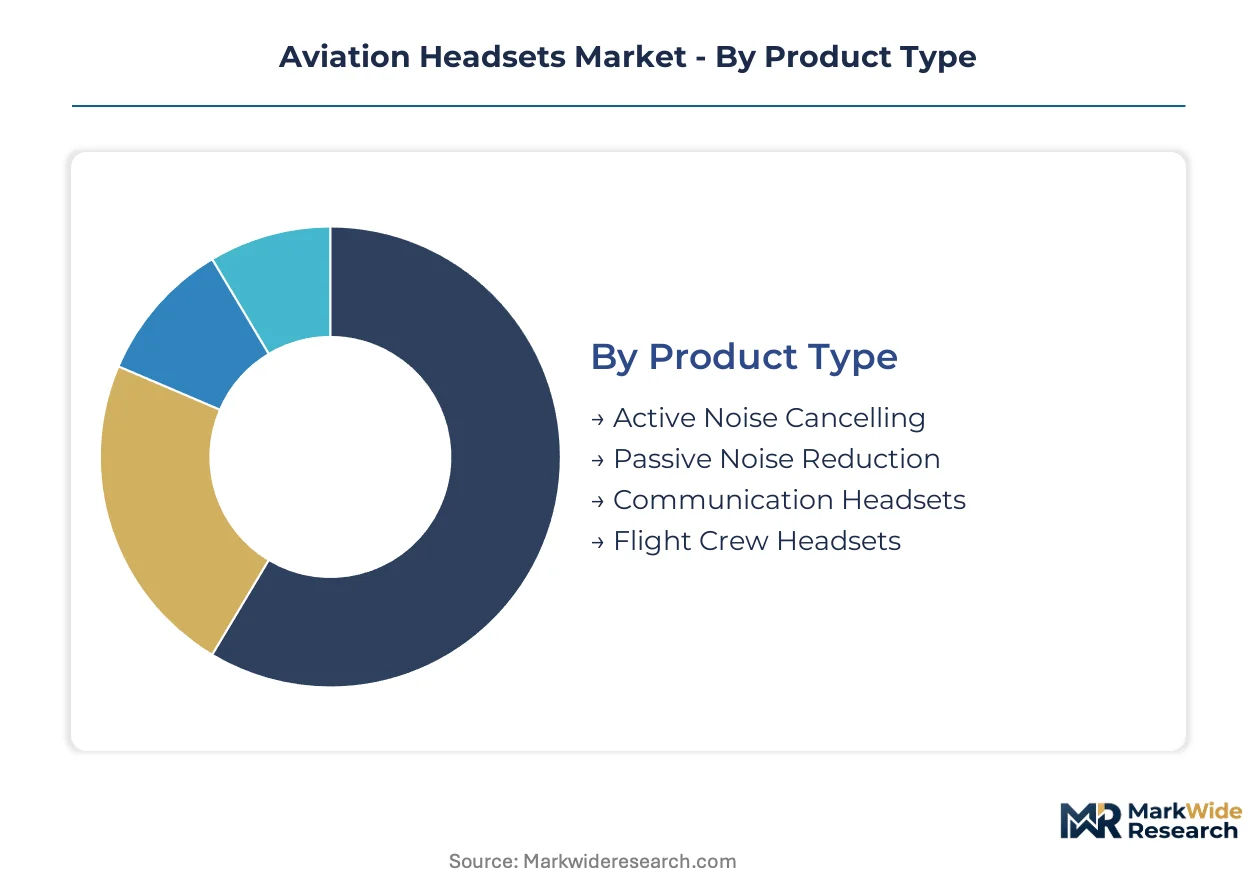
Aviation headset procurement patterns diverge sharply across operational contexts, with certification requirements and noise exposure levels dictating technology selection. Fleet operators segment purchases by pilot seniority and aircraft type, creating distinct demand channels within the same organization.
Product Type:
Active noise cancelling headsets demand the highest upfront engineering investment, requiring proprietary digital signal processing chips and acoustic laboratory validation for FAA TSO-C139a compliance.
- Active Noise Cancelling:Phase-inversion circuitry suppresses engine and propeller frequencies below 500 Hz. Commercial airline training departments in the United States are mandating these for all turbine transition courses, phasing out passive-only inventory.
- Passive Noise Reduction:Acoustic ear cups rely on mass and seal integrity without electronics. Flight schools operating piston fleets in high-temperature climates favor these for reliability and battery independence.
- Communication Headsets:Prioritize microphone clarity over noise suppression for ground crew and maintenance coordination.
- Flight Crew Headsets:Integrate with aircraft intercom systems through standardized connectors, emphasizing durability over 10,000+ flight hour lifecycles.
Most installed capacity flows through Active Noise Cancelling. Expansion is steepest in Communication Headsets for unmanned aerial systems ground control stations.
End User:
Procurement authority concentrates with fleet managers rather than individual pilots, reshaping volume discounts and warranty negotiation leverage.
- Commercial Pilots:Part 121 carriers issue standardized equipment through crew resource management programs, creating bulk purchase contracts with 3-5 year replacement cycles.
- Private Pilots:Owner-operators of Part 91 aircraft select headsets through direct-to-manufacturer e-commerce channels, prioritizing Bluetooth compatibility with tablet flight bags.
- Flight Instructors:High-utilization training environments demand rapid replacement parts availability and dual-earcup monitoring capability for student supervision.
- Military Personnel:MIL-STD-810G procurement specifications require electromagnetic hardening and chemical resistance beyond commercial aviation standards.
Volume concentrates with Commercial Pilots. Private Pilots are expanding most quickly as fractional ownership programs proliferate.
Connectivity:
Interface selection determines aftermarket retrofit complexity and compatibility with legacy aircraft electrical systems.
- Wired:Dual-plug and panel-powered configurations dominate certified aircraft installations, ensuring uninterrupted power without battery dependency.
- Bluetooth:Low-latency audio codecs enable wireless integration with electronic flight bag tablets and simulator networks, climbing fastest in training academy procurement.
- Wi-Fi:Emerging standard for multi-crew coordination in large-cabin business jets with cabin management systems.
- USB:Primarily confined to simulator and ground training applications where digital audio routing is standardized.
Wired interfaces retain the largest installed base. Bluetooth is gaining share fastest as Part 141 schools modernize simulator fleets.
Usage Environment:
Acoustic exposure profiles and regulatory oversight intensity vary dramatically across operational settings, driving specification divergence.
- Cockpit:Ambient noise exceeds 100 decibels in turbine aircraft, necessitating active noise cancellation for extended duty periods without hearing fatigue.
- Training Simulator:Controlled acoustic environments permit lighter headset designs with emphasis on communication clarity and instructor monitoring channels.
- Ground Operations:Ramp personnel require hearing protection with push-to-talk functionality, prioritizing durability over audio fidelity.
- Air Traffic Control:Controller headsets emphasize speech intelligibility and all-day comfort in low-noise tower environments.
Cockpit applications absorb the greatest unit volume. Training Simulator procurement is climbing the fastest as simulator-to-aircraft training hour ratios increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting aviation headset assembly toward jurisdictions with streamlined FAA TSO reciprocity and lower electromagnetic compliance testing costs. Manufacturers are relocating final assembly to exploit gaps between US airworthiness mandates and less burdensome export certification regimes.
United States
Part 121 carrier fleet modernization and Part 141 flight school expansion are absorbing the largest headset volumes. FAA TSO-C139a enforcement is phasing out passive-only equipment from certified turbine aircraft. Wichita's aviation manufacturing corridor hosts testing laboratories serving both commercial and military procurement channels.
Germany
EU REACH substance restrictions are forcing material reformulation in ear cup cushions and cable assemblies destined for European operators. ECHA's expanded candidate list is accelerating polymer substitution programs. Bavaria's precision electronics cluster supplies acoustic driver components to aviation audio system integrators.
China
Neodymium magnet and lithium-ion cell production concentrates in Guangdong and Jiangsu provinces, exposing supply chains to export control volatility. MIIT standards for wireless audio equipment are diverging from FAA electromagnetic compatibility requirements. Shenzhen's electronics manufacturing base is repositioning component output toward aviation applications.
Japan
METI funding for domestic aerospace supply chain resilience is sustaining precision manufacturing capacity for acoustic transducers. JIS standards for hearing protection equipment provide alternative certification pathways for regional operators. Nagoya's aviation industrial zone maintains specialized testing infrastructure for active noise cancellation systems.
United Kingdom
Post-Brexit regulatory divergence from EU REACH is creating dual compliance obligations for manufacturers serving both markets. CAA certification requirements for commercial pilot equipment remain aligned with ICAO guidance. Southeast England's aerospace engineering corridor retains expertise in cockpit audio system integration.
Aviation Headsets Market Vendor Landscape
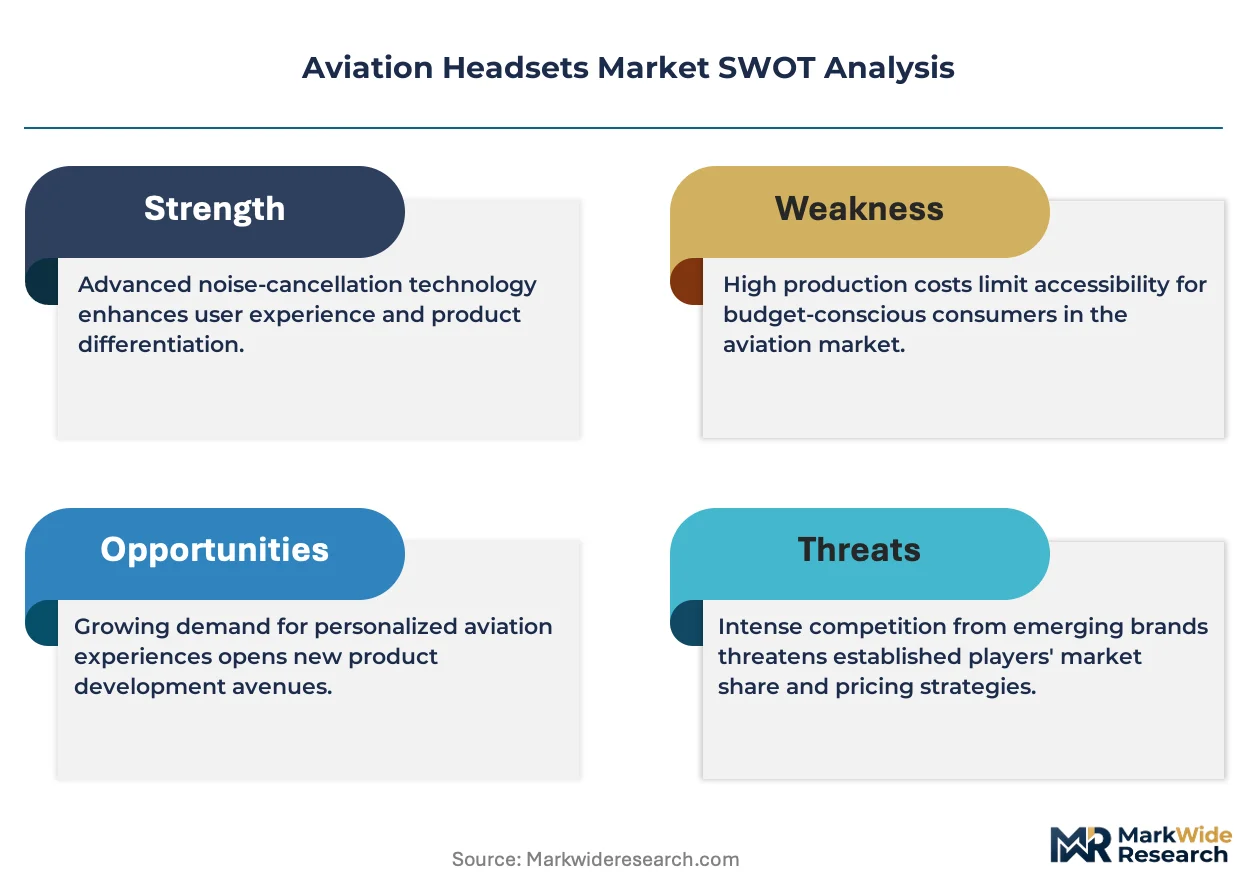
Established producers occupy the standard tier; emerging entrants pursue unmanned aerial systems ground control and simulator integration segments. The supplier base organizes around three archetypes: defense contractors with MIL-SPEC certification depth, consumer audio specialists leveraging noise cancellation IP, and domestic manufacturers exploiting Buy American procurement preferences. Consolidation pressure is intensifying through technology licensing agreements and cross-border distribution partnerships.
Among US-based specialists, Bose Corporation and David Clark Company exemplify divergent strategic positioning within the active noise cancellation segment. Sennheiser Electronic GmbH & Co. KG anchors European precision audio engineering capabilities. These three entities represent distinct competitive vectors: proprietary digital signal processing, military specification compliance, and transducer manufacturing heritage.
| Leading Market Players |
|---|
| Bose Corporation |
| David Clark Company |
| Lightspeed Aviation |
| 3M Company |
| Sennheiser Electronic GmbH & Co. KG |
| Faro Aviation |
| Flightcom Corporation |
| Bosch Security Systems |
| Plantronics |
| Others |
Supply Flow & Price Mechanics
Captive acoustic driver production in domestic facilities anchors both supply security and premium pricing power for MIL-SPEC certified manufacturers serving defense and commercial aviation channels. This integration pattern insulates against neodymium magnet supply volatility while supporting three-tier pricing stratification across certification grades.
Pricing Analysis
Distributor margins for aviation retail channels compress pricing by 18-25 points before reaching flight schools and owner-operators. Three-tier pricing structure across premium, standard, and economy levels separates FAA TSO-C139a certified active noise cancelling models from hybrid designs and passive-only alternatives. Cost compression in the economy tier intensifies as Chinese component suppliers expand direct-to-manufacturer sales channels. Flight schools operating high-utilization piston fleets exhibit the highest price sensitivity, while Part 121 carriers prioritize certification compliance over unit cost.
Supply Chain Analysis
Acoustic engineer availability constrains final assembly capacity in Wichita's aviation corridor and Bavaria's precision electronics cluster. Neodymium magnet sourcing draws from Chinese rare earth processing facilities, lithium-ion cell production concentrates in Guangdong and Jiangsu provinces, and acoustic driver assemblies hinge on Japanese transducer manufacturing. Single-source vulnerability in rare earth magnet supply exposes lead times to export control volatility. Distribution runs through specialized aviation distributors, direct-to-fleet procurement contracts, and manufacturer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA TSO-C139a certification mandates force equipment replacement cycles regardless of macroeconomic conditions. The mandate's phased enforcement creates predictable demand visibility for qualified suppliers.
For Market Incumbents: Hedge against lithium-ion supply concentration by qualifying secondary battery cell vendors in South Korea and Japan. Secure captive neodymium magnet sourcing through offtake agreements with Australian rare earth projects. Certification timeline compression from 18-24 month FAA validation cycles threatens revenue recognition timing for new product launches.
For New Entrants and Emerging Players: Unmanned aerial systems ground control operators represent an underserved buyer archetype with distinct audio isolation requirements and lighter weight specifications. Drone operator headsets for beyond-visual-line-of-sight operations lack established certification standards, creating first-mover advantage potential. Simulator-based training academies offer the most penetrable entry channel through Bluetooth 5.3 audio convergence for tablet-based electronic flight bag integration.
For Investors and Strategic Acquirers: Roll-up economics work for domestic assembly specialists with verified MIL-STD-810G testing infrastructure because Buy American procurement provisions create durable competitive moats. Long-term viability centers on defense contract cross-subsidization of commercial product development. Watch for ICAO cabin safety guidance revisions as the signal indicating inflection in wireless headset power system design requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA TSO-C139a Certification Investment | Active noise cancelling designs gain mandatory installation status in Part 121 turbine aircraft. |
| Domestic Production Footprint Expansion | Buy American provisions create procurement preference for verified US supply chains. |
| Bluetooth 5.3 Audio Protocol Integration | Low-latency wireless enables retrofit opportunities in privately owned aircraft fleets. |
| Unmanned Aerial Systems Product Line | Beyond-visual-line-of-sight drone operations lack established headset certification standards. |
| Dual-Stock Inventory Strategy | EU REACH substance restrictions force parallel material formulations for European operators. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's aviation manufacturing clusters. The analysis combines primary interviews with FAA certification engineers, flight school fleet managers, defense procurement officers, and acoustic R&D directors with secondary validation from FAA TSO filings, ECHA substance restriction updates, and customs trade data. Bottom-up triangulation across product type, end user, and connectivity segments converges with top-down macroeconomic modeling.
Granularity-level framing models active noise cancelling, passive noise reduction, and hybrid variants at the SKU level across commercial pilot, private pilot, flight instructor, and military personnel end-user categories. Deployment environment segmentation captures cockpit, training simulator, ground operations, and air traffic control usage contexts. CAGRs derive from replacement cycle analysis tied to FAA mandate enforcement timelines and fleet modernization schedules. Forecast inputs incorporate lithium-ion cell supply lead times and rare earth magnet export permit volatility.
Underlying measurement precision varies by segment; commercial airline procurement data carries tighter precision than fragmented private pilot direct-to-consumer sales. Forecasts reflect assumptions about FAA certification timeline stability and REACH substance restriction implementation schedules. Material deviation in defense procurement budgets or lithium battery transport rule revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market