
 Global Adaptive Learning Market | 2026-2036
Global Adaptive Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Learning Market Foresight
The capability gap between cloud-native specialists and legacy publishers is collapsing as infrastructure costs democratize. McGraw Hill LLC sustains its position through deep curriculum integration and institutional relationships built over decades. Area9 Lyceum ApS competes on medical and professional education specialization, leveraging adaptive pathways that map to competency frameworks. DreamBox Learning, Inc. dominates the K-12 mathematics niche with proprietary intelligent adaptive engines that adjust item difficulty in real time.
Adaptive learning systems employ algorithms that dynamically modify content sequencing, assessment difficulty, and instructional scaffolding based on individual learner performance data. These platforms typically integrate machine learning models with learning management system architectures to optimize knowledge retention and reduce time-to-proficiency. The technology dimension shows machine learning and natural language processing segments capturing disproportionate R&D investment as vendors race to build generative tutoring interfaces. On the application side, corporate training and higher education represent structurally different margin pools, with enterprises paying premium per-seat rates for measurable competency outcomes while universities prioritize scale and accessibility.
The EU AI Act imposes risk classification requirements on educational algorithms that profile learners, directly affecting how European vendors architect their recommendation engines. In the United States, FERPA and COPPA create compliance thresholds that favor established providers with dedicated legal infrastructure over emerging entrants. Stakeholders must monitor how emerging algorithmic accountability legislation across multiple jurisdictions reshapes product development roadmaps and cross-border data handling requirements.
Market Dynamics
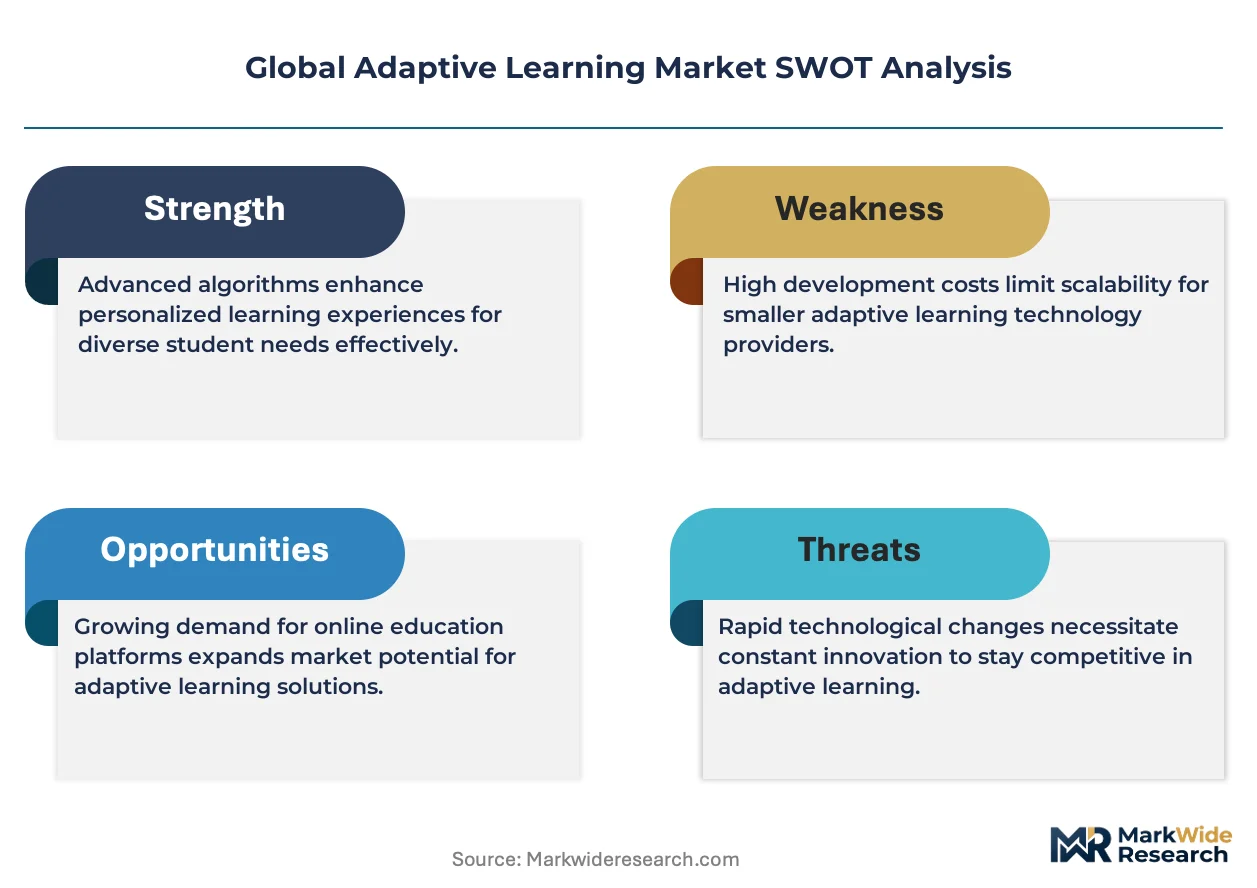
Algorithmic personalization is decomposing the traditional one-to-many instructional model as machine learning engines fragment content delivery into individualized competency pathways. The EU AI Act and FERPA compliance requirements are forcing vendors to rebuild recommendation architectures around explainable decision logic rather than opaque neural networks.
Growth Catalysts
- ESSA Funding Flexibility:United States federal education policy enables district-level procurement autonomy, accelerating adaptive platform adoption in K-12 systems seeking measurable learning outcomes.
- Corporate Competency Frameworks:Enterprise learning departments now mandate skill-verification protocols that only adaptive systems can deliver through granular performance tracking.
- Natural Language Processing:Conversational AI engines enable real-time Socratic tutoring interfaces that reduce instructor dependency in asynchronous training environments.
Market Restraints
- GDPR Algorithmic Transparency:European data protection requirements impose costly re-engineering of proprietary recommendation engines to expose decision logic.
- Cloud Infrastructure Concentration:Three hyperscale providers control essential GPU compute capacity for model training, creating vendor lock-in risk.
- Legacy LMS Integration Friction:Decades-old institutional technology stacks resist API-based interoperability with modern adaptive architectures.
Strategic Opportunities
- Brazilian Professional Certification:Latin America's largest economy lacks localized adaptive platforms for regulated healthcare and accounting credentials.
- Generative Assessment Convergence:Large language models combined with psychometric engines enable dynamic test-item generation that adapts to learner misconceptions in real time.
- India's Digital Public Infrastructure:The country's unified payments and identity systems create foundational rails for population-scale adaptive education deployment.
Industry Challenges
- Learning Engineer Talent Scarcity:The hybrid skill set combining instructional design, data science, and cognitive psychology commands premium compensation that squeezes vendor margins.
- FERPA-COPPA Compliance Complexity:United States educational privacy laws create divergent technical requirements for K-12 versus higher education deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Learning Market |
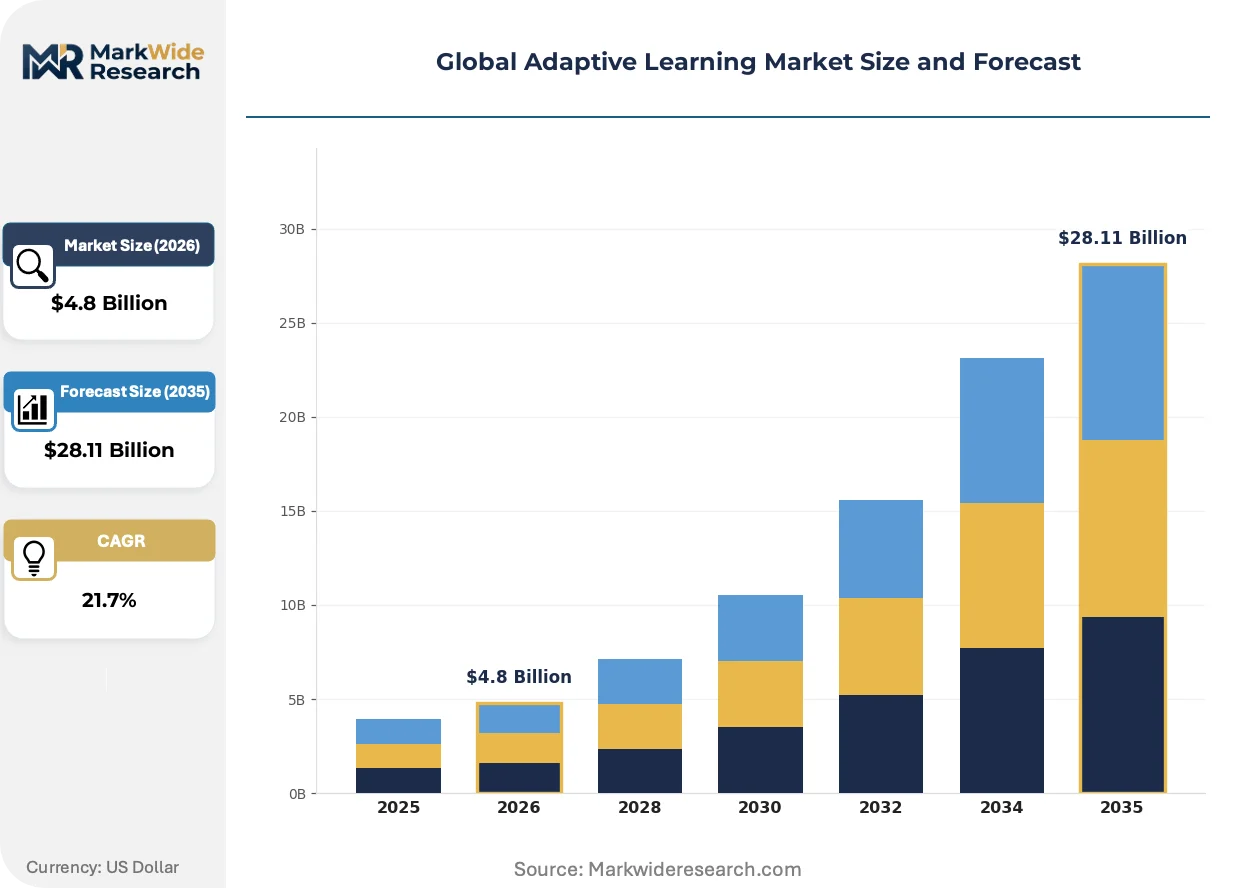
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $28.11 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Data Analytics, Predictive Modeling, Content Management Systems Application: K-12 Education, Corporate Training, Higher Education, Vocational Training, Language Learning End User: Educational Institutions, Enterprise Businesses, Government Agencies, Non-Profit Organizations, eLearning Providers Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Platforms, SaaS |
| Companies Covered | Pearson PLC, McGraw Hill LLC, Curriculum Associates, LLC, DreamBox Learning, Inc., John Wiley & Sons, Inc., Houghton Mifflin Harcourt Publishing Company, Knewton, Inc., Area9 Lyceum ApS, Imagine Learning LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Learning Market Shifts & Advancements
Generative AI is collapsing the cost structure of content production while simultaneously raising the bar for pedagogical quality verification. Vendors now compete on inference efficiency and hallucination mitigation rather than content library breadth alone.
Transformer-based large language models are decomposing the traditional content-authoring pipeline by generating personalized explanations, worked examples, and remedial materials on demand. Higher education publishers and corporate training departments are piloting these systems for technical skills instruction where knowledge obsolescence cycles compress below twelve months. The structural consequence is decomposing the economics of static textbook publishing into perpetually refreshed, algorithmically assembled learning experiences.
The EU AI Act's risk classification framework is reclassifying adaptive tutoring systems as high-risk when they profile learners for educational or vocational decisions. European vendors must now implement human-in-the-loop review mechanisms and algorithmic impact assessments before deployment. Medical and professional education segments face the steepest compliance burden as competency determinations directly affect licensure eligibility.
Enterprise procurement teams now mandate learning record interoperability through xAPI and SCORM standards before contract execution, rejecting proprietary data silos. This behavioral shift favors vendors with open ecosystem architectures over closed-platform incumbents. The United States corporate training market exhibits this pattern most acutely as Fortune 500 learning technology stacks consolidate around unified data lakes.
Global Adaptive Learning Market Segmentation
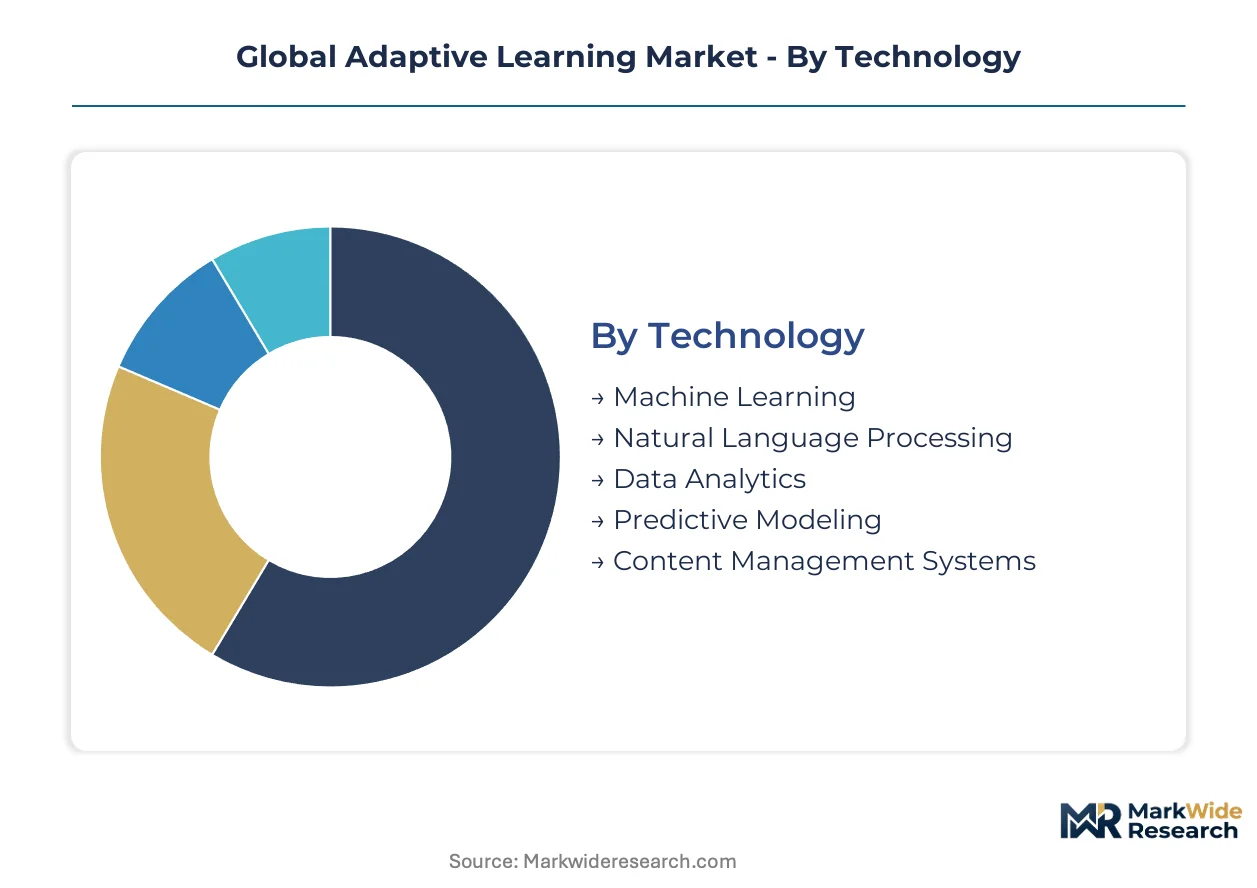
Adaptive learning platforms fragment along technology capability, institutional buyer type, and infrastructure architecture. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor competitive positioning.
Technology:
Machine learning and natural language processing segments concentrate R&D investment in the United States and China, while data analytics platforms find stronger adoption in European markets governed by algorithmic transparency requirements.
- Machine Learning:Algorithms dynamically modify content sequencing and assessment difficulty based on real-time learner performance data. Demand concentrates in corporate training departments across the United States, where Fortune 500 enterprises pay premium per-seat rates for measurable competency outcomes.
- Natural Language Processing:Conversational AI engines enable Socratic tutoring interfaces that reduce instructor dependency in asynchronous environments. German and French corporate learning departments pilot these systems most aggressively, driven by EU AI Act compliance timelines that favor explainable linguistic models over opaque neural architectures.
- Data Analytics:Learning record aggregation and visualization tools that feed institutional dashboards.
- Predictive Modeling:Early-warning systems identifying at-risk learners through behavioral pattern recognition.
- Content Management Systems:Authoring and repository infrastructure for adaptive content libraries.
Machine learning commands the established base. The steepest expansion runs through natural language processing.
Application:
Corporate training applications generate premium pricing power, while K-12 deployments scale through federal funding mechanisms that vary dramatically by country.
- Corporate Training:Enterprise learning departments mandate skill-verification protocols through granular performance tracking. United States technology and financial services sectors drive disproportionate spend, with procurement teams demanding xAPI interoperability before contract execution.
- Higher Education:Universities prioritize accessibility and enrollment scale over per-student revenue maximization. Indian public universities and Brazilian federal institutions represent emerging deployment frontiers where digital public infrastructure reduces implementation friction.
- K-12 Education:Primary and secondary systems leveraging ESSA funding flexibility in the United States.
- Vocational Training:Regulated credential pathways for healthcare, accounting, and technical trades.
- Language Learning:Specialized spoken and written proficiency acquisition platforms.
Corporate training captures margin concentration. Higher education delivers volume scaling most rapidly.
End User:
Enterprise businesses and educational institutions represent structurally different procurement cycles, with government agencies imposing the most stringent data sovereignty requirements.
- Educational Institutions:K-12 districts and universities with FERPA and COPPA compliance obligations. United States public school systems consolidate procurement through state-level cooperative agreements that favor established vendors with dedicated legal infrastructure.
- Enterprise Businesses:Corporate learning and development departments with unified technology stack requirements. Japanese manufacturing conglomerates and South Korean chaebols drive Asia-Pacific demand for competency framework integration.
- Government Agencies:Federal and state workforce development programs.
- Non-Profit Organizations:Foundation-funded educational access initiatives.
- eLearning Providers:Platform-agnostic content and delivery specialists.
Educational institutions anchor installed base. Enterprise businesses are climbing the fastest.
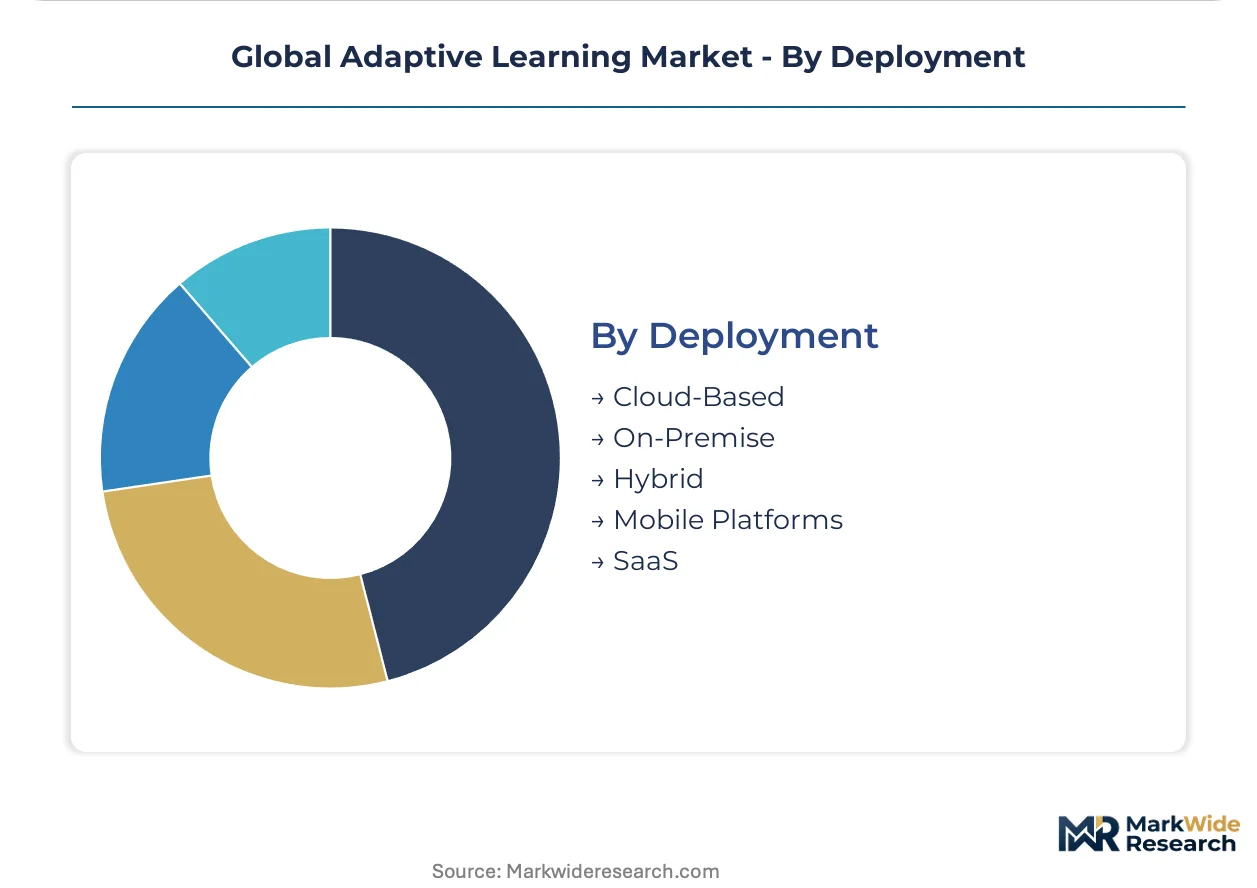
Deployment:
Cloud-based architectures dominate new procurement, though hybrid models persist in European and Middle Eastern markets with strict data residency mandates.
- Cloud-Based:Hyperscale-hosted platforms with elastic compute scaling. Saudi Arabian and UAE government contracts increasingly require in-country cloud regions, forcing vendors into multi-tenant infrastructure investments.
- SaaS:Subscription-managed delivery eliminating capital expenditure barriers. Small and mid-sized enterprises across Germany and the United Kingdom favor this model for rapid deployment without IT overhead.
- On-Premise:Institutionally controlled server infrastructure for sensitive learner data.
- Hybrid:Split architectures balancing cloud agility with local data retention.
- Mobile Platforms:Smartphone-native delivery optimized for bandwidth-constrained environments.
Cloud-based deployment commands the established base. SaaS models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States districts deploy adaptive platforms for measurable skill outcomes, while European institutions prioritize algorithmic transparency over personalization depth. Indian and Brazilian markets concentrate on scale-driven accessibility models.
United States
Corporate training departments and K-12 districts drive divergent procurement patterns. ESSA funding flexibility enables state-level cooperative purchasing agreements. Texas and California education technology clusters host the densest vendor implementation activity.
Germany
Corporate learning departments pilot conversational AI tutoring systems under EU AI Act compliance timelines. GDPR and algorithmic transparency requirements favor explainable linguistic models. Berlin and Munich host the largest enterprise learning technology deployments.
India
Public universities and federal institutions seek population-scale adaptive deployment through digital public infrastructure. The country's unified payments and identity systems reduce implementation friction. Karnataka and Maharashtra concentrate the highest ed-tech startup density.
Brazil
Regulated healthcare and accounting credentials lack localized adaptive platforms for professional certification. Federal workforce development programs create procurement entry points. São Paulo anchors the corporate learning technology adoption curve.
United Kingdom
Higher education institutions prioritize enrollment scale and accessibility over per-student revenue maximization. Data protection requirements align with GDPR frameworks. London and the Southeast concentrate ed-tech vendor headquarters and pilot programs.
Global Adaptive Learning Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with curriculum-embedded publishers competing against cloud-native adaptive engines. The structure rewards deep institutional relationships and compliance infrastructure over pure technology performance. Three archetypes dominate: legacy publishers with curriculum integration, specialized competency-framework vendors, and intelligent adaptive engine specialists. Consolidation moves through strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent workforce verification markets.
Within the curriculum-integrated tier, McGraw Hill LLC and Pearson PLC occupy positions built on decades of institutional procurement relationships. Area9 Lyceum ApS represents the specialized competency-framework archetype, anchoring medical and professional education segments where adaptive pathways map directly to licensure requirements. DreamBox Learning, Inc. exemplifies the intelligent adaptive engine specialist, concentrating proprietary real-time difficulty adjustment within K-12 mathematics.
| Leading Market Players |
|---|
| Pearson PLC |
| McGraw Hill LLC |
| Curriculum Associates, LLC |
| DreamBox Learning, Inc. |
| John Wiley & Sons, Inc. |
| Houghton Mifflin Harcourt Publishing Company |
| Knewton, Inc. |
| Area9 Lyceum ApS |
| Imagine Learning LLC |
| Others |
Supply & Pricing Matrix
Hyperscale cloud capacity utilization above eighty percent in United States and Chinese data centers compresses marginal compute costs for adaptive learning vendors, concentrating supply-side leverage among three GPU providers and establishing subscription pricing floors that lock out capital-constrained entrants. This scale dynamic forces mid-tier vendors toward SaaS-tiered models while enterprise buyers extract volume discounts through multi-year commitments.
Pricing Analysis
Professional services and implementation support drive lifetime value beyond base subscription fees. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 enterprises from mid-market adopters and individual learners. Price differentiation rests on integration complexity and dedicated learning engineer allocation. Cost compression in the economy tier is intensifying because open-source machine learning frameworks reduce proprietary engine development barriers. Higher education institutions exhibit greatest price sensitivity; corporate training departments least.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane elevates inbound logistics costs for on-premise server hardware destined to Middle Eastern and Southeast Asian government clients. Cloud infrastructure concentrates in the United States, China, and Ireland. Raw material dependencies span NVIDIA GPU accelerators, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability runs through TSMC's advanced node fabrication. Distribution runs through hyperscale reseller channels and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive learning platforms function as service-attach businesses where ongoing content refresh and learning engineer support expand faster than initial software licensing. Recurring revenue multiples exceed perpetual license valuations by substantial margins.
For Market Incumbents: Shield installed base relationships through deep LMS integration partnerships that increase switching costs. Invest in EU AI Act compliance infrastructure before the high-risk classification deadline to capture European enterprise renewals. Vertical integration into proprietary assessment item banks reduces dependency on third-party psychometric content.
For New Entrants and Emerging Players: Anchor in Brazilian professional certification markets where localized adaptive platforms for healthcare and accounting credentials remain underdeveloped. Target India's digital public infrastructure rails for population-scale deployment with minimal customer acquisition friction. Pursue channel partnerships with existing workforce development agencies rather than direct institutional sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native adaptive engine specialists with established competency-framework mappings. Long-term viability over the next decade favors vendors with explainable AI architectures that satisfy emerging algorithmic accountability legislation. Monitor EU AI Act enforcement patterns as the critical inflection signal for European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Competency Framework Integration | Maps adaptive pathways directly to medical licensure requirements in Germany and the United States. |
| Explainable AI Architecture Redesign | Satisfies GDPR algorithmic transparency mandates for European higher education procurement. |
| xAPI Interoperability Certification | Meets Fortune 500 learning technology stack consolidation requirements before contract execution. |
| Generative Assessment Engine Development | Combines large language models with psychometric engines for dynamic test-item generation. |
| Digital Public Infrastructure Partnership | Leverages India's unified identity systems for population-scale adaptive deployment. |
Research Methodology
A spread of perspectives from chief learning officers, LMS procurement directors, learning engineers, and regulatory compliance leads converged on the working assumptions. Primary interviews with corporate training executives and university technology officers combined with secondary validation against SEC filings, ESSA funding disclosures, hyperscaler capex reports, and EU regulatory impact assessments. Bottom-up platform deployment estimates triangulated against top-down education technology spending aggregates.
Segmentation dimensions modeled span technology capability, application type, end-user archetype, and deployment architecture across the analysis window. CAGRs derive from fitted growth curves anchored to documented procurement volumes and funding authorization trajectories. Forecast inputs incorporate EU AI Act implementation timelines and federal ESSA flexibility provisions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and funding continuity assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Global Smart Classroom Market