
 Global Accounting Finance Market | 2026-2036
Global Accounting Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accounting Finance Market Foresight
The healthcare and pharmaceutical vertical is broadening its share of accounting finance spending as compliance complexity multiplies. Deloitte Touche Tohmatsu Limited leverages its audit and assurance depth to dominate regulatory-intensive sectors. Ernst & Young International anchors its position through tax technology leadership across European and Asian markets. Intuit competes aggressively for small business segments with intuitive cloud-native platforms.
Global accounting finance encompasses the systems, software, and professional services used to record, analyze, report, and forecast monetary flows across organizations, typically operating through double-entry ledgers, automated reconciliation engines, and real-time dashboard architectures. Its primary commercial purpose is to reduce capital cost, ensure statutory compliance, and enable resource allocation decisions. Cloud-based deployment now leads solution delivery as enterprises prioritize remote accessibility and reduced IT overhead. Financial planning software captures the fastest expansion as CFOs demand scenario modeling and predictive analytics. Small businesses represent an underpenetrated but accelerating end user type where mobile-first platforms are displacing spreadsheet-based workflows.
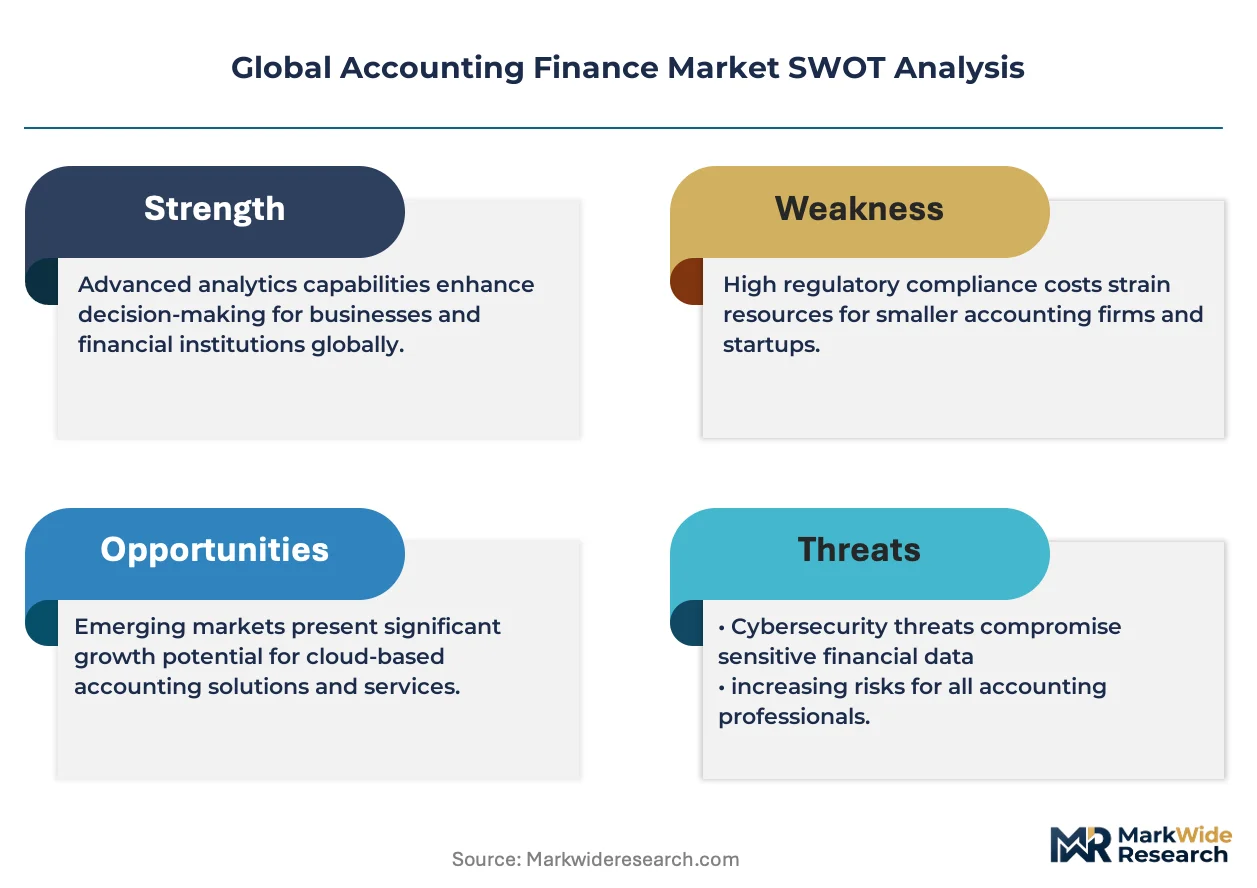
The SEC in the United States mandates granular financial disclosures that elevate demand for auditing platforms and compliance monitoring tools. EMA and EU AI Act requirements in Europe impose algorithmic transparency standards on automated risk management tools, reshaping vendor product roadmaps. ISO 27001 and SOC 2 frameworks govern data security expectations across cross-border service delivery. Stakeholders must monitor how fragmented national AI regulations fragment platform standardization and inflate compliance architecture costs.
Market Dynamics
The EU AI Act is forcing algorithmic transparency mandates onto automated accounting platforms, compelling vendors to reengineer reconciliation engines and risk-scoring modules for audit trail visibility.
Growth Catalysts
- Cloud Migration:Mid-sized enterprises across Germany and India are replacing on-premise ERP installations with SaaS financial planning suites, reducing IT overhead while enabling remote workforce access.
- SEC Disclosure Mandates:Granular financial reporting requirements in the United States elevate demand for real-time auditing platforms and automated compliance monitoring tools.
- Healthcare Compliance Multiplication:Pharmaceutical verticals face escalating statutory complexity around revenue recognition and transfer pricing, driving specialized accounting software procurement.
Market Restraints
- Algorithmic Governance Fragmentation:Divergent AI transparency standards between the EU AI Act, emerging US state-level frameworks, and India's draft AI principles inflate compliance architecture costs for multinational platform vendors.
- Data Sovereignty Requirements:Cross-border financial data flows face mounting friction from GDPR localization mandates and India's data protection bill provisions, constraining centralized cloud delivery models.
- Legacy System Entrenchment:Large enterprises maintain decades-old general ledger installations with deep customization, creating switching friction that slows cloud-native platform displacement.
Strategic Opportunities
- Small Business Mobility:Mobile-first accounting applications remain underpenetrated among sole proprietors and micro-enterprises in India, where smartphone-based invoicing and tax filing are displacing spreadsheet workflows.
- CSRD-Driven ESG Reporting:The EU Corporate Sustainability Reporting Directive mandates granular sustainability disclosures, creating demand for integrated financial and non-financial data platforms.
- Predictive Analytics Convergence:Machine learning scenario modeling is merging with traditional financial planning software, enabling CFOs to stress-test capital allocation decisions against macroeconomic volatility.
Industry Challenges
- Specialized Talent Scarcity:The intersection of accounting domain expertise and machine learning engineering remains shallow, constraining vendor ability to build transparent algorithmic audit tools.
- ISO 27001 Certification Burden:Achieving information security management certification for cloud-native platforms demands 12-18 month implementation cycles, delaying market entry for emerging vendors.
- Interoperability Complexity:Real-time data exchange between modern planning software and legacy ERP installations requires expensive middleware development, eroding SaaS margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accounting Finance Market |
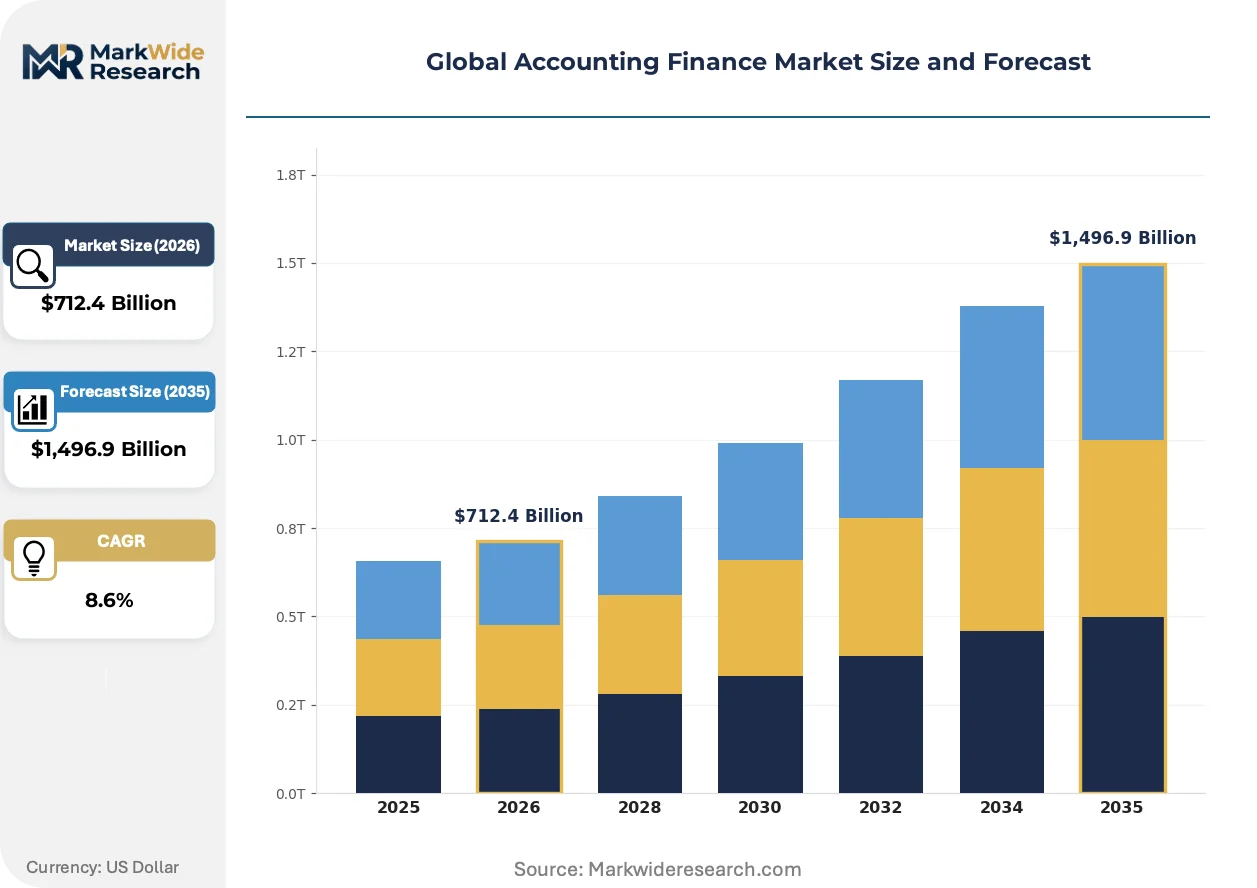
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,496.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Financial Planning Software, Risk Management Tools, Taxation Software, Payroll Systems, Expense Management, Auditing Platforms Deployment Mode: Cloud-Based, On-Premises, Hybrid, Mobile Access End User Type: Small Businesses, Mid-Sized Enterprises, Large Corporations, Non-Profit Organizations, Government Agencies Application Segment: Accounts Payable, Accounts Receivable, General Ledger, Budgeting & Forecasting, Compliance Monitoring, Financial Reporting |
| Companies Covered | Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers, Ernst & Young International, KPMG, Intuit, SAP, Oracle, Workday, BDO International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accounting Finance Market Shifts & Advancements
Real-time financial data architectures are compressing decision cycles from quarterly to continuous, reshaping how enterprises allocate capital and manage liquidity.
Embedded machine learning for anomaly detection is overtaking rules-based reconciliation engines in transaction monitoring. Large enterprises in the United States and Germany are deploying these tools to flag irregular journal entries within minutes rather than days. The technology is overtaking traditional sampling-based audit approaches by enabling 100% transaction coverage without proportional cost scaling.
EMA algorithmic transparency guidelines and the EU AI Act are mandating explainability standards for automated risk scoring tools used in credit and insurance accounting. Vendors must now document decision pathways and maintain human-in-the-loop override capabilities. European banks and insurers are responding by procuring platforms with built-in audit trail architectures rather than retrofitting legacy systems.
Subscription pricing for financial planning software is displacing perpetual license models among mid-market buyers. CFOs in India and Germany prefer operational expenditure treatment and automatic feature updates over capital-intensive on-premise deployments. This shift is most visible in healthcare and pharmaceutical verticals where IT capital budgets face heightened scrutiny from private equity owners.
Global Accounting Finance Market Segmentation
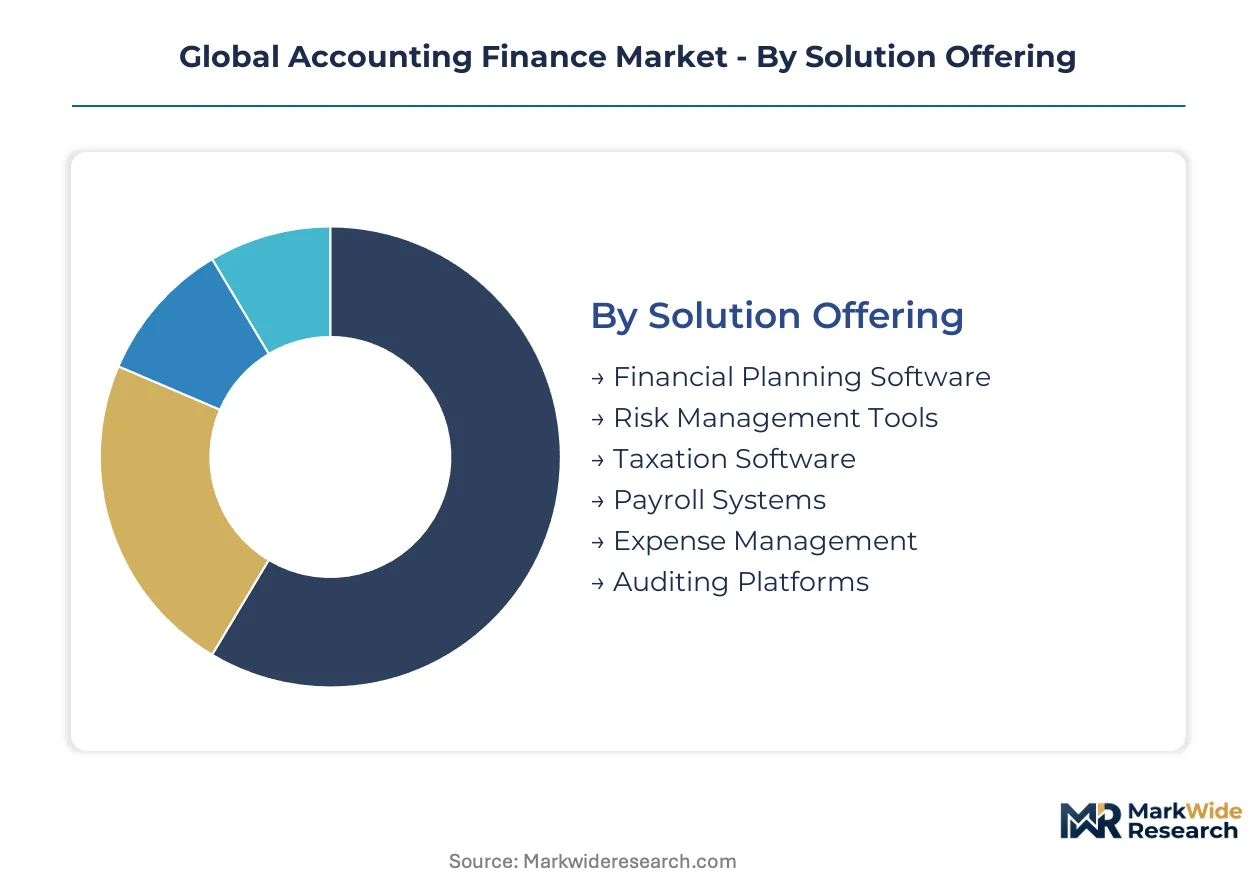
Segmentation in accounting finance reveals how buyer priorities diverge across technical sophistication, regulatory exposure, and operational scale. Procurement patterns in Germany and India demonstrate that deployment flexibility now outweighs feature depth for mid-market buyers. Understanding these fault lines enables vendors to align R&D investment with segments commanding premium pricing power.
Solution Offering:
Buyers in this category differentiate by compliance intensity and analytical maturity rather than company size alone.
- Financial Planning Software:Platforms integrating scenario modeling and predictive analytics dominate CFO procurement pipelines. Mid-sized enterprises in Germany are replacing spreadsheet workflows with cloud-native suites that enable real-time capital allocation decisions. The CSRD mandates in Europe are accelerating demand for sustainability-integrated forecasting modules.
- Risk Management Tools:Algorithmic engines for credit scoring and liquidity monitoring require explainable AI architectures under EU AI Act transparency rules. European banks and insurers are procuring platforms with built-in audit trails rather than retrofitting legacy installations. Human-in-the-loop override capabilities have become non-negotiable for automated risk-scoring deployments.
- Taxation Software:Multi-jurisdictional engines handle transfer pricing and VAT compliance across fragmented regulatory environments.
- Payroll Systems:Real-time calculation engines integrate with HRIS platforms for workforce cost optimization.
- Expense Management:Mobile-first receipt capture and policy enforcement tools target distributed workforces.
- Auditing Platforms:Continuous monitoring systems replace sampling-based approaches with 100% transaction coverage.
Financial Planning Software leads volumes today; Risk Management Tools are gaining share fastest.
Deployment Mode:
IT budget treatment and data sovereignty requirements create sharp buyer segmentation between capital and operational expenditure preferences.
- Cloud-Based:SaaS delivery enables remote workforce access and automatic security patching without on-premise infrastructure. Mid-sized enterprises across India are displacing legacy ERP installations with browser-accessible financial suites that reduce IT headcount requirements. Subscription pricing models align with private equity scrutiny of capital expenditure in healthcare verticals.
- On-Premises:Deep customization and air-gapped security satisfy defense contractors and critical infrastructure operators. Large German manufacturers maintain decades-old general ledger installations with proprietary extensions that resist cloud migration. Switching friction and retraining costs entrench these deployments despite higher total cost of ownership.
- Hybrid:Sensitive data remains on-premise while analytics workloads shift to cloud infrastructure.
- Mobile Access:Smartphone-native interfaces target sole proprietors and field-based service operations in India.
Cloud-Based deployment captures the majority of new procurement; Mobile Access is climbing the fastest among underpenetrated micro-enterprise segments.
End User Type:
Organizational complexity and regulatory scrutiny determine solution sophistication requirements across buyer tiers.
- Mid-Sized Enterprises:These buyers prioritize rapid implementation and pre-configured workflows over customization depth. Companies in India and Germany are consolidating point solutions into integrated suites that reduce vendor management overhead. Cloud migration accelerates as IT teams lack bandwidth for on-premise maintenance.
- Large Corporations:Multi-entity consolidation and intercompany elimination drive demand for enterprise-grade general ledger platforms. SEC disclosure mandates in the United States elevate requirements for granular financial reporting and real-time compliance monitoring. Procurement cycles extend to 18-24 months as security certification and interoperability testing consume evaluation timelines.
- Small Businesses:Sole proprietors seek mobile-first invoicing and automated tax filing with minimal configuration.
- Non-Profit Organizations:Fund accounting and donor restriction tracking differentiate requirements from commercial buyers.
- Government Agencies:Fiscal transparency mandates and appropriation accounting create specialized procurement criteria.
Large Corporations maintain the highest absolute spending; Mid-Sized Enterprises show the steepest expansion trajectory as cloud accessibility democratizes enterprise-grade capabilities.
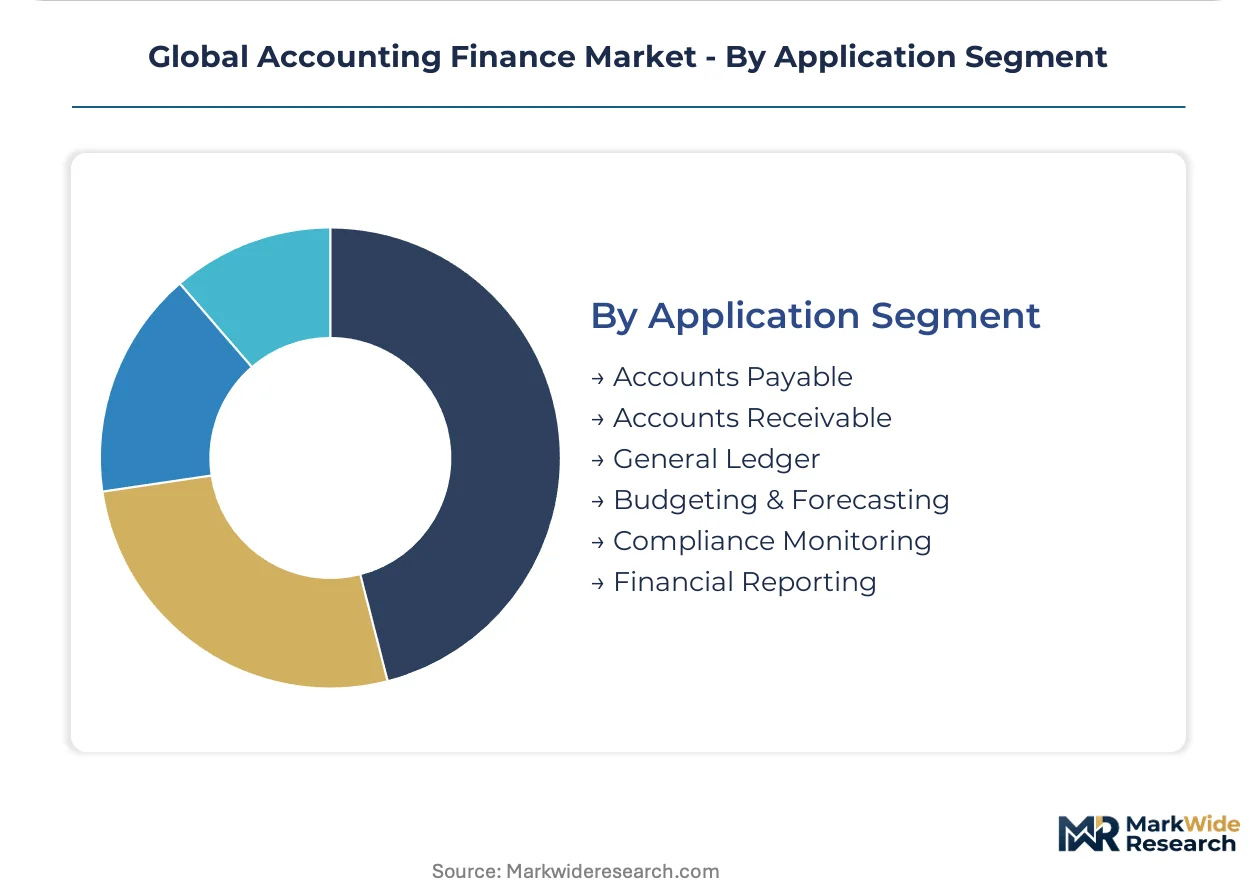
Application Segment:
Process automation potential and regulatory visibility determine investment priority across financial workflows.
- Budgeting & Forecasting:Rolling forecast capabilities with machine learning scenario modeling compress planning cycles from annual to continuous. CFOs in the United States deploy these tools to stress-test capital allocation against macroeconomic volatility. Integration with operational data sources enables driver-based planning that links financial targets to operational metrics.
- Compliance Monitoring:Real-time regulatory tracking and automated control testing reduce audit preparation burden. EU AI Act and SEC disclosure mandates are elevating procurement of platforms with built-in governance frameworks. Pharmaceutical verticals face particular pressure as revenue recognition rules multiply across jurisdictions.
- Accounts Payable:Invoice capture and three-way matching automation reduce manual processing costs.
- Accounts Receivable:Collections optimization and cash application tools accelerate working capital conversion.
- General Ledger:Multi-currency consolidation and elimination engines serve complex entity structures.
- Financial Reporting:Self-service dashboards and narrative generation tools reduce dependence on IT for management packs.
General Ledger remains the foundational investment; Compliance Monitoring is expanding most quickly as regulatory fragmentation intensifies architecture requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing accounting finance platform deployment as compliance cost differentials widen between jurisdictions. Vendors are optimizing delivery architectures around data sovereignty requirements and algorithmic governance intensity.
United States
SEC disclosure mandates and SOX compliance requirements drive procurement of real-time auditing platforms. The IRA's corporate minimum tax provisions elevate demand for sophisticated tax technology. New York and San Francisco financial clusters host the densest concentration of enterprise buyers replacing legacy ERP installations.
Germany
EMA algorithmic transparency guidelines and EU AI Act implementation reshape automated risk-scoring procurement. Mittelstand manufacturers in Baden-Württemberg and Bavaria accelerate cloud migration for financial planning suites. Frankfurt's banking density sustains premium demand for compliance-integrated platforms.
India
RBI digital payment proliferation and SEBI disclosure mandates expand addressable market for automated reconciliation tools. Bengaluru and Mumbai software corridors attract vendor R&D investment for mobile-first SME platforms. PLI scheme incentives for IT hardware indirectly reduce cloud infrastructure costs for domestic deployers.
United Kingdom
FCA conduct rules and HMRC Making Tax Digital requirements sustain demand for tax automation. London's fintech density creates adjacent demand for embedded accounting APIs. Manchester and Edinburgh regional finance centers show accelerating cloud adoption among mid-market professional services firms.
Japan
METI digital transformation subsidies and JIS data security standards guide platform selection. Tokyo-Osaka corporate corridors maintain on-premise preference for general ledger core systems while adopting cloud analytics overlays. Regional banks face FSA pressure to modernize risk-scoring infrastructure.
Global Accounting Finance Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend from audit roots into adjacent software segments. The vendor base stratifies across three tiers: Big Four networks anchoring regulatory-intensive verticals, ERP conglomerates integrating financial modules into enterprise suites, and cloud-native specialists capturing SME mobility demand. Strategic archetypes include audit-origin platforms leveraging compliance depth, software conglomerates exploiting data integration advantages, and vertical SaaS players optimizing for specific end-user workflows. M&A activity and technology licensing partnerships represent the primary competitive vectors reshaping market boundaries.
Within the audit-origin tier, Deloitte Touche Tohmatsu Limited and Ernst & Young International exemplify the regulatory-anchored archetype, occupying positions where assurance credibility transfers into software procurement decisions. Intuit sits within the cloud-native specialist category, representing mobile-first platform architecture optimized for micro-enterprise segments. These three entities collectively illustrate how competitive positioning fragments across compliance intensity, deployment accessibility, and buyer scale dimensions rather than converging on uniform solution design.
| Leading Market Players |
|---|
| Deloitte Touche Tohmatsu Limited |
| PricewaterhouseCoopers |
| Ernst & Young International |
| KPMG |
| Intuit |
| SAP |
| Oracle |
| Workday |
| BDO International |
| Others |
Supply & Pricing Matrix
Machine learning engineering talent concentration in Bengaluru and Hyderabad generates labor-cost differentials that widen pricing-tier spreads between premium algorithmic audit tools and standard reconciliation platforms. Indian development centers enable cloud-native vendors to undercut legacy ERP pricing by thirty to fifty percent while maintaining ISO 27001 certification equivalence.
Pricing Analysis
Channel-margin compression sits with distributor markups on legacy ERP installations, while direct-to-enterprise SaaS subscriptions capture margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates SOC 2-certified predictive analytics suites from browser-based bookkeeping tools. Pricing pressure stems from subscription fatigue among mid-sized enterprises consolidating vendor relationships. Small businesses in India exhibit highest price sensitivity; pharmaceutical CFOs in Germany show lowest sensitivity due to compliance failure costs.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in United States, Ireland, and Singapore data center clusters. Platform development draws from open-source machine learning frameworks, offshore engineering talent pools, and proprietary training datasets. Supply chain risk centers on regulatory fragmentation forcing multi-region deployment architectures. Distribution runs through direct sales teams for enterprise accounts and self-service app stores for micro-enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in accounting finance rests on automation-driven cost compression in customer acquisition and support delivery. Cloud-native vendors capture premium-tier shifts as compliance complexity justifies higher subscription pricing.
For Market Incumbents: Hedge against algorithmic transparency mandates by pre-building EU AI Act-compliant audit trails into risk-scoring modules. Acquire mobile-first development studios in India to neutralize cloud-native challenger speed-to-market advantages. Certification investment in ISO 27001 and SOC 2 Type II remains essential for defending enterprise procurement pipelines. For New Entrants and Emerging Players: Sole proprietors in India's tier-two cities represent an underserved buyer archetype with minimal incumbent penetration. White-space targets include smartphone-native tax filing for gig economy workers and embedded accounting APIs for vertical SaaS platforms. Go-to-market through telecom distributor partnerships leverages existing mobile wallet relationships. For Investors and Strategic Acquirers: Private equity firms with healthcare vertical expertise are the most active acquirer in this space, targeting regulatory-anchored audit platforms. Long-term viability favors vendors with dual capability in compliance depth and cloud delivery economics. Watch for CSRD implementation acceleration in Europe as inflection indicator for ESG-integrated financial planning demand.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Compliance | EU AI Act mandates reshape product roadmaps for automated risk-scoring tools. |
| Mobile-First Platform Development | Smartphone-native interfaces displace spreadsheet workflows among Indian micro-enterprises. |
| CSRD-Integrated Reporting Suite | Sustainability disclosure mandates create demand for combined financial and ESG data platforms. |
| Continuous Audit Architecture | Real-time transaction monitoring replaces sampling-based approaches under SEC guidance. |
| Vertical SaaS Partnership | Embedded accounting APIs capture workflow-integrated procurement in healthcare and pharma. |
Research Methodology
Direct dialogue with CFOs, compliance officers, cloud procurement leads, and platform engineering directors grounded qualitative findings in operational reality. Secondary validation drew from SEC disclosure filings, EU regulatory registers, RBI payment system reports, and vendor security certification databases. Bottom-up segmentation modeling triangulated against top-down market sizing from IT expenditure surveys.
Revenue and growth trajectories emerged from scenario-weighted projections across deployment mode, organization size, vertical compliance intensity, and regional regulatory framework. Modeled dimensions included solution offering, end user type, application segment, and geographic adoption pattern. CAGRs derived from historical expenditure elasticity and technology substitution curves, with cloud migration velocity and AI governance implementation pace as key forecast inputs.
Underlying measurement precision varies by segment; financial planning software and risk management tools carry tighter precision than legacy payroll system replacement markets. Forecasts incorporate assumptions around regulatory implementation timelines and enterprise IT budget treatment shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
Japan Forensic Accounting Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
AI in Accounting Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Construction Accounting Software Market