
 Accounting and Budgeting Software Market | 2026-2036
Accounting and Budgeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Accounting and Budgeting Software Market Analysis
GDPR is recalibrating the cost-of-entry calculus for vendors serving European enterprise clients, forcing substantial investments in data residency architecture and audit trail transparency. Sage Intacct leverages deep vertical specialization in healthcare and nonprofit accounting to sustain premium positioning against horizontal competitors. QuickBooks Online anchors the small enterprise segment through intuitive onboarding flows and extensive third-party app marketplace integrations. Xero competes aggressively in English-speaking Commonwealth markets with bank-feed automation and multi-currency reconciliation capabilities.
Accounting and budgeting software comprises modular applications that automate general ledger maintenance, accounts payable and receivable tracking, payroll processing, financial forecasting, and variance analysis through rule-based workflows and API-connected data pipelines. These systems serve the primary commercial purpose of replacing spreadsheet-dependent financial management with auditable, collaborative platforms that reduce close-cycle latency and improve capital allocation decisions. Cloud-based solutions now dominate new deployments as finance teams prioritize remote accessibility and automatic security patching over capital-intensive on-premises infrastructure. Small enterprises represent the fastest-growing end-user category as micro-SaaS vendors strip complexity from traditional enterprise feature sets. Hybrid deployment models are gaining traction among manufacturing verticals with legacy ERP investments requiring phased cloud migration paths.
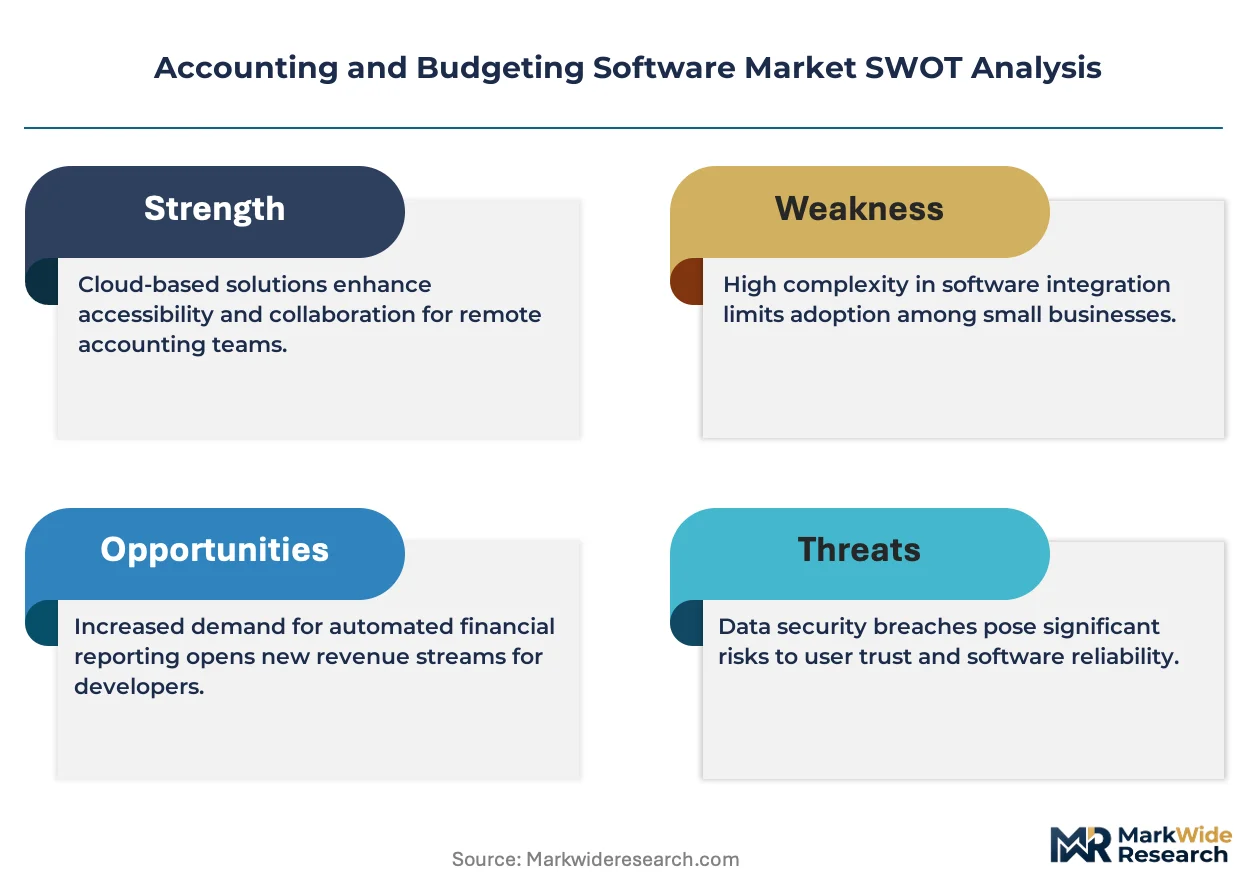
The SEC mandates granular financial disclosure timelines that pressure public companies toward integrated planning and reporting platforms with immutable audit logs. HIPAA constrains healthcare adopters to business associate agreement-compliant vendors with encrypted data transmission and access controls. ISO 27001 certification has become a non-negotiable procurement filter for large corporations evaluating SaaS finance providers. Stakeholders must monitor how generative AI capabilities reshape regulatory scrutiny of automated forecasting algorithms and determine whether to build, partner, or acquire compliance-ready intelligence layers.
Market Dynamics
Cloud-native financial platforms are compressing deployment cycles and forcing legacy vendors to rearchitect around API-first data exchange, fundamentally altering competitive moats in enterprise accounting.
Growth Catalysts
- EU AI Act compliance mandates:Automated forecasting systems across European healthcare and retail verticals require auditable algorithmic transparency, accelerating procurement of certified platforms with built-in explainability layers.
- Mid-sized enterprise cloud migration:Finance teams in United States healthcare and retail sectors prioritize real-time budget visibility over capital-intensive on-premises infrastructure, driving subscription revenue concentration.
- Real-time bank-feed automation:Multi-currency reconciliation capabilities reduce close-cycle latency for cross-border operations, pulling English-speaking Commonwealth markets toward modern general ledger platforms.
Market Restraints
- GDPR data residency architecture:Vendors serving European enterprise clients face substantial upfront investments in regional cloud infrastructure and audit trail transparency, elevating cost-of-entry barriers.
- Legacy ERP integration complexity:Manufacturing verticals with decades-old on-premises investments require phased migration paths, slowing cloud adoption velocity and extending sales cycles.
- Generative AI regulatory uncertainty:Automated forecasting algorithms face evolving scrutiny from multiple national financial regulators, creating compliance timeline risk for product roadmaps.
Strategic Opportunities
- Micro-SaaS feature stripping:Small enterprise segments remain underpenetrated by complex enterprise suites, creating white space for stripped-down general ledger and payroll modules.
- Hybrid deployment models:Manufacturing verticals with legacy ERP investments seek phased cloud migration paths, enabling vendors to capture transitional revenue streams.
- ISO 27001 certification differentiation:Large corporations now filter procurement through non-negotiable security standards, rewarding early certifiers with preferred vendor status.
Industry Challenges
- Embedded finance talent scarcity:Development of API-connected data pipelines and rule-based workflow engines requires specialized engineering expertise that outpaces supply.
- SEC disclosure timeline pressure:Public companies must maintain immutable audit logs and granular financial reporting capabilities, forcing continuous platform investment.
- HIPAA business associate agreement navigation:Healthcare adopters demand encrypted transmission and access controls that extend compliance burden across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accounting and Budgeting Software Market |
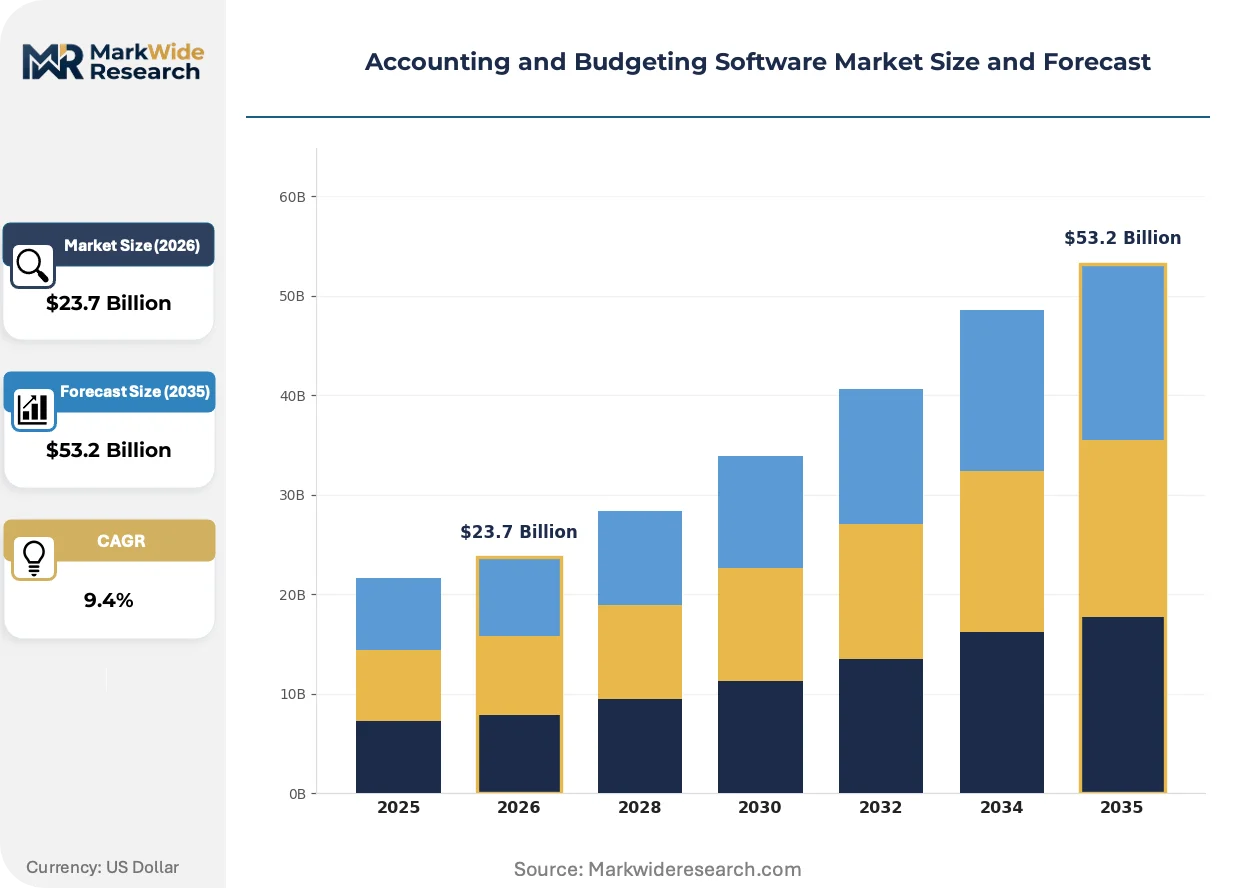
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Mobile Applications End User: Small Enterprises, Medium Enterprises, Large Corporations, Non-Profits Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Server Industry Vertical: Healthcare, Retail, Manufacturing, Educational Institutions |
| Companies Covered | Centage, Planful, QuickBooks Online, Cube, Vena, Xero, Workday Adaptive Planning, Sage Intacct, NetSuite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accounting and Budgeting Software Market Emerging Trajectories
Generative AI capabilities are penetrating financial forecasting workflows, while regulatory pressure on algorithmic transparency intensifies and buyer expectations shift toward composable, best-of-breed architectures.
Machine learning-powered variance analysis is electrifying how finance teams detect anomalies in general ledger transactions. Mid-sized enterprises in United States healthcare verticals are adopting these tools at accelerating pace. The technology is compressing the traditional monthly close cycle into continuous reconciliation workflows.
The EU AI Act is mandating explainability standards for automated accounting systems deployed across European member states. Vendors must now document decision pathways within forecasting algorithms to satisfy national financial regulators. Healthcare and nonprofit accounting platforms face the steepest compliance curve as they retrofit existing products.
Subscription-based procurement models are displacing perpetual license structures in enterprise financial software. Chief financial officers now prioritize operational expenditure flexibility over capital ownership, particularly in retail and healthcare verticals. United States mid-market buyers are leading this behavioral shift, demanding usage-based pricing aligned with transaction volume.
Accounting and Budgeting Software Market Segmentation
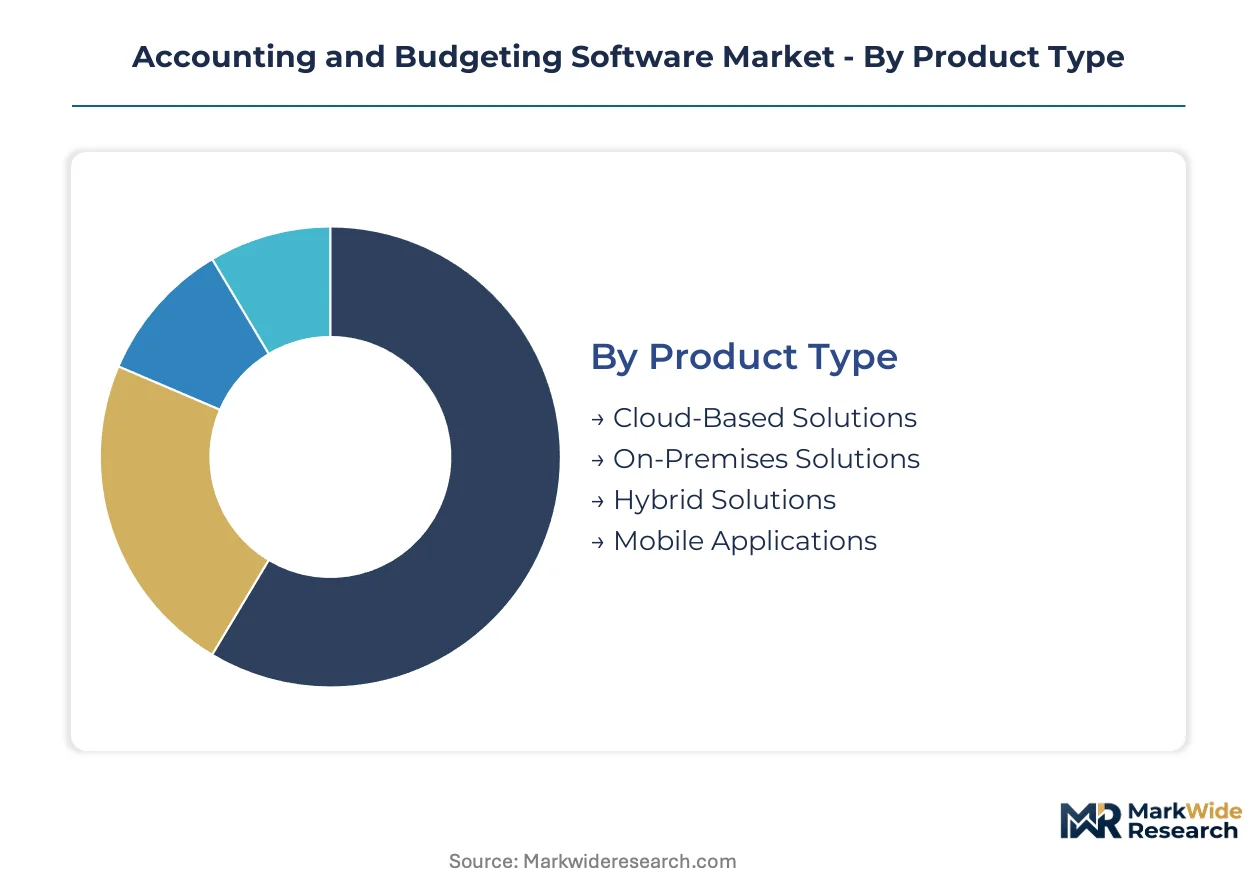
Segmentation in accounting and budgeting software reveals divergent compliance burdens across product architectures and customer scales. ISO 27001 certification filters procurement for large corporations while HIPAA constraints reshape healthcare vertical requirements. Understanding these certification boundaries enables vendors to calibrate feature depth against audit readiness.
Product Type:
Cloud-based deployments trigger distinct certification matrices compared to on-premises alternatives, with ISO 27001 and SOC 2 Type II dominating vendor evaluation criteria.
- Cloud-Based Solutions:Multi-tenant architectures with automatic security patching and API-connected data pipelines. United States healthcare and retail verticals prioritize these platforms for real-time budget visibility and remote accessibility, though HIPAA business associate agreements extend compliance burden across vendor ecosystems.
- On-Premises Solutions:Single-tenant installations on client-owned infrastructure with manual upgrade cycles. Manufacturing verticals with legacy ERP investments retain these systems for phased migration paths, accepting higher capital expenditure to preserve data sovereignty controls.
- Hybrid Solutions:Split architectures connecting cloud forecasting modules with on-premises general ledger systems.
- Mobile Applications:iOS and Android-native interfaces with biometric authentication and offline transaction logging.
Leading the category by volume: Cloud-Based Solutions. Growing fastest: Hybrid Solutions.
End User:
Customer scale determines pricing architecture complexity and implementation service intensity, with micro-SaaS vendors stripping features for the smallest segments.
- Small Enterprises:Sub-fifty-employee organizations requiring stripped-down general ledger and payroll modules without variance analysis complexity. Micro-SaaS competitors capture this segment through intuitive onboarding flows and usage-based pricing aligned with transaction volume.
- Medium Enterprises:Fifty-to-five-hundred-employee organizations with dedicated finance teams demanding collaborative close-cycle workflows. These buyers concentrate in United States healthcare and retail verticals, prioritizing subscription flexibility over capital ownership.
- Large Corporations:Multi-entity organizations with SEC disclosure mandates requiring immutable audit logs and granular financial reporting capabilities.
- Non-Profits:Fund-accounting specialists with grant compliance tracking and donor restriction management needs.
Revenue concentrates with: Medium Enterprises. Expanding most quickly: Small Enterprises.
Deployment:
Infrastructure location choices map directly to data residency requirements under GDPR and sector-specific regulations like HIPAA.
- Public Cloud:Shared infrastructure with automatic scaling and regional redundancy. European enterprise clients demand EU-based data centers with documented subprocessor chains to satisfy GDPR audit trail transparency requirements.
- Private Cloud:Dedicated single-tenant environments with customized security configurations. Healthcare adopters specify these deployments for encrypted transmission and access control granularity under HIPAA business associate agreements.
- Hybrid Cloud:Workload-split architectures with sensitive data on private infrastructure and analytics on public platforms.
- Local Server:On-site hardware with air-gapped backup capabilities and physical access controls.
Deployment share leader: Public Cloud. Steepest expansion trajectory: Hybrid Cloud.
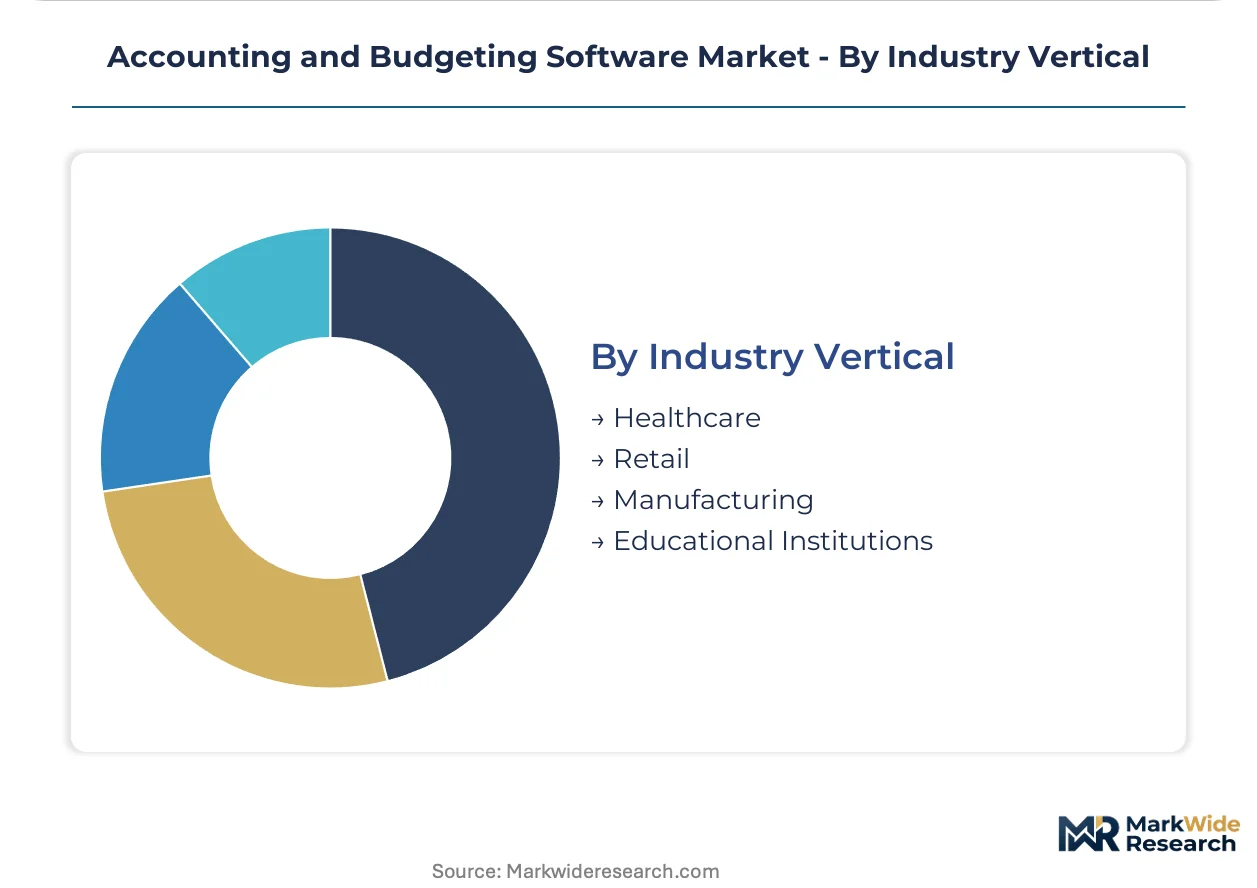
Industry Vertical:
Sector-specific regulatory frameworks reshape feature prioritization, with healthcare and manufacturing presenting the steepest compliance curves.
- Healthcare:HIPAA-constrained organizations requiring encrypted data transmission, business associate agreement-compliant vendors, and audit-ready access logs. United States providers accelerate procurement of certified platforms with built-in explainability layers for automated forecasting.
- Retail:Multi-channel operators with high transaction velocity and multi-currency reconciliation needs. These buyers prioritize real-time bank-feed automation and usage-based pricing aligned with seasonal volume fluctuations.
- Manufacturing:Legacy ERP-heavy operations with decades-old on-premises investments requiring phased cloud migration paths.
- Educational Institutions:Grant-funded organizations with restricted fund accounting and compliance reporting requirements.
Vertical revenue leader: Healthcare. Gaining share fastest: Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's enterprise software corridor concentrates venture capital flows for cloud-native financial platforms. Special economic zones in Bangalore and Shenzhen accelerate R&D cost arbitrage for mid-market SaaS vendors. Regulatory divergence across national financial authorities fragments compliance architecture requirements.
United States
Mid-sized healthcare providers in Chicago and Dallas-Fort Worth accelerate procurement of real-time budget visibility tools. SEC disclosure mandates pressure public companies toward integrated planning platforms with immutable audit logs. The Boston fintech corridor incubates specialized forecasting algorithm startups serving HIPAA-constrained medical groups.
Germany
Mittelstand manufacturers in Baden-Württemberg seek phased cloud migration paths for legacy ERP investments. The EU AI Act mandates auditable algorithmic transparency for automated forecasting systems deployed across Bavarian industrial clusters. Frankfurt's financial services hub drives demand for multi-entity consolidation platforms with GDPR-compliant data residency.
United Kingdom
London-based retail operators prioritize multi-currency reconciliation capabilities for cross-border e-commerce operations. The Financial Conduct Authority's evolving stance on AI-generated financial advice creates compliance timeline uncertainty for forecasting vendors. Manchester's growing SaaS sector incubates micro-SaaS payroll modules targeting sub-fifty-employee organizations.
India
Bangalore's technology parks host development centers for global accounting software vendors seeking engineering cost optimization. RBI guidelines on cloud data localization reshape procurement criteria for domestic banks evaluating SaaS finance providers. Hyderabad's emerging fintech cluster attracts venture investment for small enterprise general ledger automation.
Australia
Sydney-based professional services firms adopt bank-feed automation tools for continuous reconciliation workflows. The Australian Prudential Regulation Authority's cybersecurity standards elevate ISO 27001 certification to non-negotiable procurement filter status. Melbourne's nonprofit sector concentrates demand for grant compliance tracking and donor restriction management capabilities.
Accounting and Budgeting Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor landscape organizes around three strategic archetypes: horizontal ERP incumbents with broad financial modules, vertical specialists targeting healthcare and nonprofit accounting, and micro-SaaS disruptors stripping complexity for small enterprises. Consolidation pressure intensifies as private equity sponsors roll up regional players. Technology licensing partnerships proliferate as legacy vendors seek cloud-native capabilities without full platform rebuilds.
Within the vertical specialization tier, Sage Intacct and Xero exemplify contrasting geographic positioning strategies. Sage Intacct occupies a position among North American healthcare-focused platforms, while Xero anchors English-speaking Commonwealth market penetration through bank-feed automation capabilities. QuickBooks Online sits within the small enterprise mass-market segment, representing the archetype of intuitive onboarding flows and extensive third-party marketplace integrations.
| Leading Market Players |
|---|
| Centage |
| Planful |
| QuickBooks Online |
| Cube |
| Vena |
| Xero |
| Workday Adaptive Planning |
| Sage Intacct |
| NetSuite |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between ISO 27001-certified platforms and uncertified alternatives bifurcates both pricing power and supply chain architecture across the accounting software landscape. Premium vendors command subscription multiples from large corporations while commodity players compete on implementation speed, with GDPR data residency requirements forcing regional infrastructure investments that reshape cost structures.
Pricing Analysis
Short lead-time deployments command premium subscription rates from mid-sized healthcare providers requiring immediate HIPAA compliance, while extended implementation cycles attract discounted pricing for manufacturing clients with phased migration timelines. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and integration complexity. Pricing pressure stems from micro-SaaS entrants stripping features for small enterprises. Large corporations show least price sensitivity given SEC audit mandates, while sub-fifty-employee organizations drive hardest bargain negotiations.
Supply Chain Analysis
Freight costs for physical infrastructure components remain negligible given software's digital delivery model, though data center equipment sourcing draws from Taiwan, South Korea, and United States for server hardware and networking gear. Cloud-native development rests on open-source frameworks and API middleware from distributed global contributor bases. Single-source vulnerability concentrates in hyperscaler infrastructure dependencies. Distribution runs through direct sales teams for enterprise accounts and self-service portals for small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as compliance burdens from the EU AI Act and GDPR force subscale vendors toward acquisition or exit, rewarding platforms with pre-built certification architecture.
For Market Incumbents: To counter micro-SaaS feature stripping in the small enterprise segment, anchor premium positioning through vertical specialization in healthcare and nonprofit accounting while accelerating ISO 27001 certification coverage across all product tiers. Deepen API-first architecture investments to capture manufacturing hybrid deployment transitions. For New Entrants and Emerging Players: Enter via underpenetrated Commonwealth markets outside Xero's core English-speaking strongholds, targeting mid-sized retail operators with multi-currency reconciliation gaps. White space concentrates in grant-compliance modules for educational institutions. Go-to-market leverage should emphasize usage-based pricing aligned with seasonal transaction volatility. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing pre-certified HIPAA and EU AI Act compliance layers given regulatory timeline acceleration. Long-term viability favors platforms with embedded explainability for automated forecasting algorithms. Watch for SEC disclosure mandate expansion to private companies as inflection signal for integrated planning platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture captures manufacturing hybrid migration revenue streams. |
| Acquisition of Specialist Firm | Vertical healthcare accounting expertise accelerates HIPAA compliance differentiation. |
| Geographic Expansion | EU data center investments satisfy GDPR residency mandates for Frankfurt financial clients. |
| Strategic Partnership | Hyperscaler alliances reduce infrastructure capital burden for mid-market SaaS vendors. |
| Product Launch | Explainability-layer modules address EU AI Act algorithmic transparency requirements. |
Methodological Framework
Multi-period observation of cloud migration velocity, certification procurement patterns, and subscription pricing trajectories anchored the trend analysis, supplemented by interviews with CFOs at mid-sized healthcare providers, IT procurement officers at retail chains, compliance leads at manufacturing firms, and platform engineers at SaaS vendors. Secondary validation drew from SEC 10-K filings, EU regulatory impact assessments, hyperscaler capex disclosures, and healthcare GPO contract databases. Bottom-up segment sizing triangulated against top-down market construction.
Segment-weighting across deployment models, organization size tiers, vertical specializations, and regional adoption patterns structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to subscription revenue trajectories and user expansion rates. Forecast inputs incorporated EU AI Act implementation timelines and HIPAA business associate agreement renewal cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regulatory enforcement or generative AI liability expansion scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Global Auditing Services Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Europe Forensic Accounting Market