
 Integrated Accounting Software Market | 2026-2036
Integrated Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Accounting Software Market Analysis
Embedded artificial intelligence and machine learning within core financial architectures is reshaping how accounting platforms automate reconciliation, anomaly detection, and predictive forecasting. Intuit Inc. leverages its consumer-to-business ecosystem to anchor small-business adoption across North America. SAP SE competes through deep ERP integration that sustains enterprise-grade deployment complexity. Oracle Corporation dominates in hybrid cloud configurations that extend legacy system interoperability for large multinationals.
Integrated accounting software denotes unified platforms that consolidate general ledger, accounts payable, accounts receivable, payroll, tax computation, and financial reporting into a single database architecture with real-time synchronization across modules. These systems typically employ double-entry bookkeeping algorithms, role-based access controls, and API-first connectivity to eliminate manual data re-entry and reduce reconciliation latency for finance departments. Cloud-based deployment leads in new installations as subscription economics shift capital expenditure to operational budgets, while on-premises solutions retain strength in regulated industries requiring localized data sovereignty. Financial reporting features command premium pricing due to multi-entity consolidation demands, whereas payroll modules face margin compression from specialized human-capital competitors.
The EU AI Act, GDPR, and ISO 27001 standards collectively mandate algorithmic transparency, data residency, and information-security certification that shape vendor product roadmaps and customer procurement criteria. The US SEC and IRS impose electronic filing and audit-trail requirements that accelerate replacement of legacy desktop accounting packages. Stakeholders must weigh compliance automation depth against total cost of ownership when selecting between all-in-one suites and best-of-breed integrations.
Market Dynamics
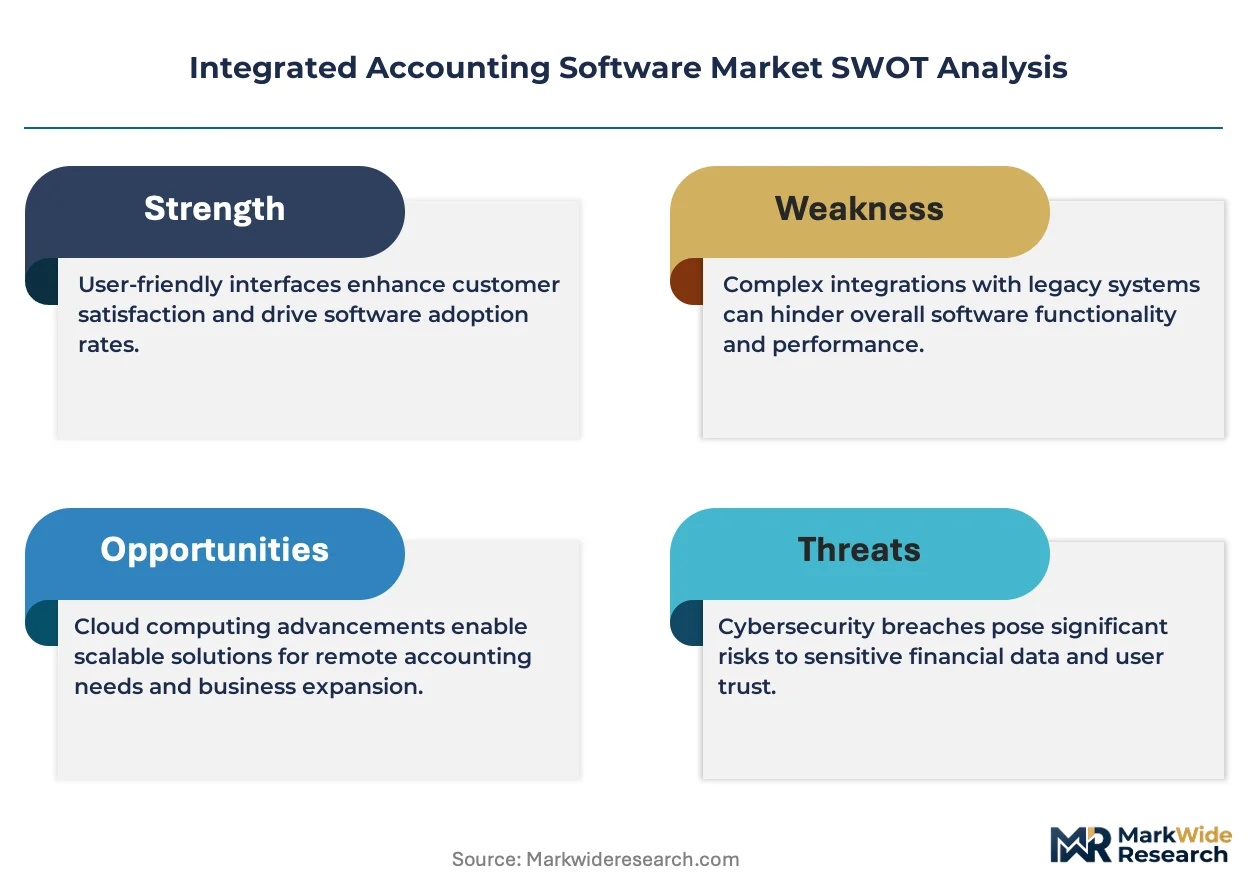
Cloud migration is compressing deployment cycles for integrated accounting platforms as mid-sized enterprises abandon perpetual licenses for subscription models, forcing vendors to restructure revenue recognition and customer success operations around recurring metrics rather than upfront implementation fees.
Growth Catalysts
- EU AI Act Compliance Mandates:Automated audit trail requirements embedded in algorithmic financial processing are compelling European enterprises to replace legacy desktop systems with governance-ready cloud architectures that document decision pathways for regulatory inspection.
- Real-Time Tax Reporting:India's GST Network and similar digitized revenue authorities in Germany and the United States are mandating continuous transaction disclosure, driving demand for accounting platforms that synchronize ledger entries directly with government portals.
- API-First Architecture:Open banking protocols and standardized financial data exchange formats are enabling mid-market firms to consolidate previously siloed payroll, expense management, and treasury functions without custom integration development.
Market Restraints
- Data Residency Requirements:GDPR localization clauses and India's data protection rules are fragmenting cloud infrastructure economics, forcing vendors to maintain redundant regional data centers that inflate operational overhead compared to centralized architectures.
- Specialized Payroll Competition:Dedicated human capital management vendors with deeper compliance engines for multi-jurisdiction employment law are compressing margins on integrated payroll modules, limiting cross-sell profitability for generalist accounting suites.
- Legacy System Entrenchment:Large multinationals with decades of customized on-premises ERP configurations face prohibitive migration costs and business continuity risks that delay replacement timelines despite functional obsolescence.
Strategic Opportunities
- Embedded Carbon Accounting:CSRD sustainability reporting requirements are creating demand for modules that capture Scope 1-3 emissions data alongside financial transactions, enabling vendors to command premium pricing for environmental disclosure automation.
- Vertical-Specific Templates:Pre-configured chart-of-accounts and compliance workflows for construction, healthcare, and nonprofit sectors represent underserved niches where specialized functionality outperforms generic horizontal platforms.
- Mobile-First Design:Field-service businesses and distributed workforces in India and Southeast Asian markets are driving requirements for full ledger functionality on smartphone interfaces, opening segments where desktop-centric incumbents hold weak positions.
Industry Challenges
- Multi-Entity Consolidation Complexity:Currency translation, intercompany elimination, and divergent local GAAP requirements across subsidiary networks strain engineering resources and extend implementation timelines for global deployments.
- ISO 27001 Certification Burden:Information security management system audits and continuous compliance monitoring consume substantial operational bandwidth for vendors serving regulated financial services and healthcare clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Accounting Software Market |
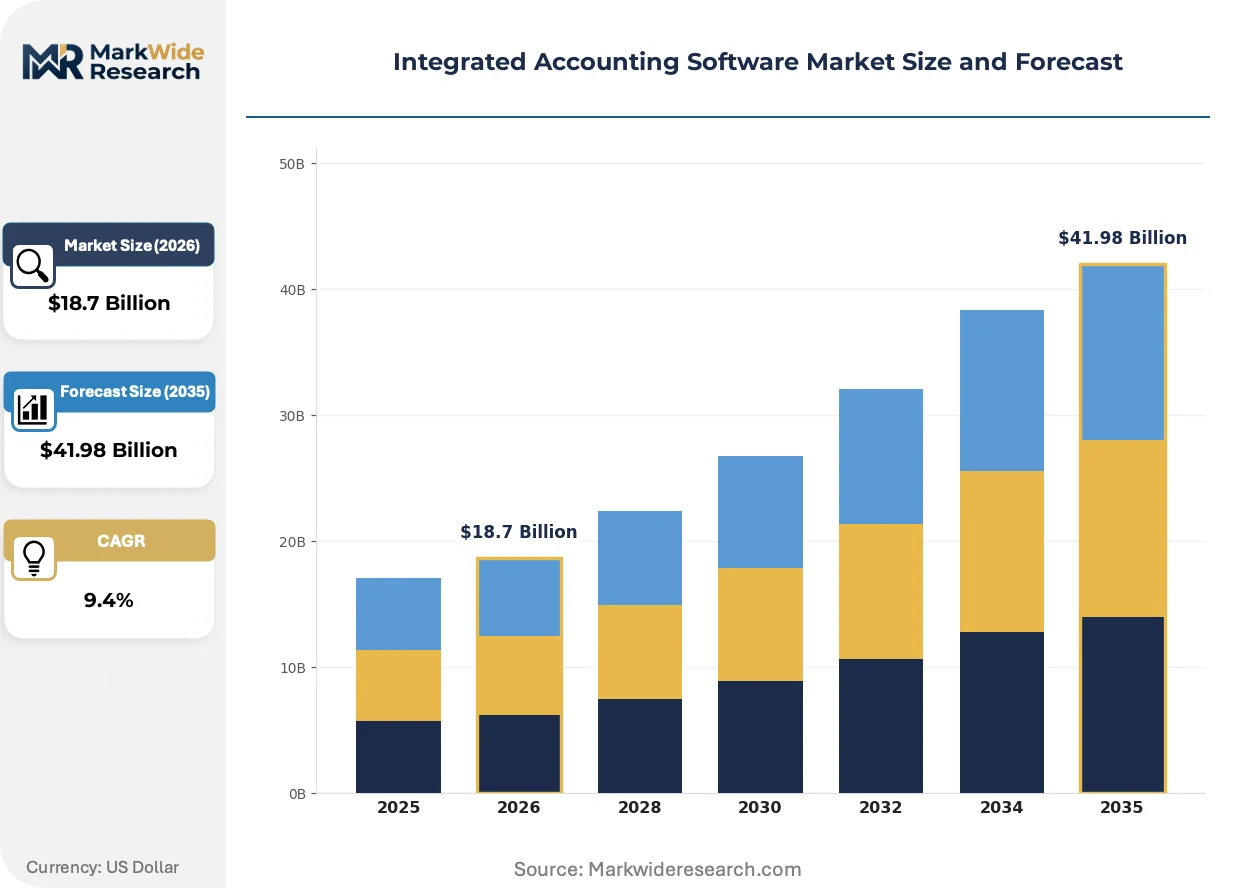
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Businesses, Enterprises, Freelancers, E-Commerce Feature: Invoicing, Payroll, Tax Management, Financial Reporting Industry Vertical: Retail, Healthcare, Education, Construction |
| Companies Covered | Intuit Inc., The Sage Group plc, SAP SE, Oracle Corporation, Microsoft Corporation, Infor, Workday Inc, Xero, Yonyou Software Co Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Accounting Software Market Emerging Trajectories
Artificial intelligence integration is redefining core accounting workflows by automating judgment-dependent tasks previously requiring professional staff intervention, while regulatory digitization and buyer expectations around immediate accessibility are reshaping platform architecture priorities.
Machine learning algorithms trained on historical transaction patterns now execute bank reconciliation and anomaly flagging without manual rule configuration. Mid-sized enterprises in professional services and retail verticals are deploying these tools within eighteen-month refresh cycles. Automated exception handling is rendering obsolete the staff-intensive matching processes that previously consumed thirty to forty percent of monthly close time.
The EU AI Act's risk classification framework for financial decision-support systems imposes documentation and human oversight requirements on automated credit scoring and fraud detection modules. Vendors must now maintain algorithmic impact assessments and audit logs that satisfy national supervisory authorities. Enterprise procurement committees in Germany and France are prioritizing vendors with established conformity assessment procedures over faster-moving competitors lacking regulatory pre-certification.
Subscription fatigue among finance departments is compressing evaluation cycles and elevating switching considerations. Buyers increasingly unbundle core ledger functions from adjacent modules, selecting best-of-breed expense management or treasury tools despite integration friction. This fragmentation is most pronounced in United States technology and media sectors where finance leaders prioritize user experience over suite completeness.
Integrated Accounting Software Market Segmentation
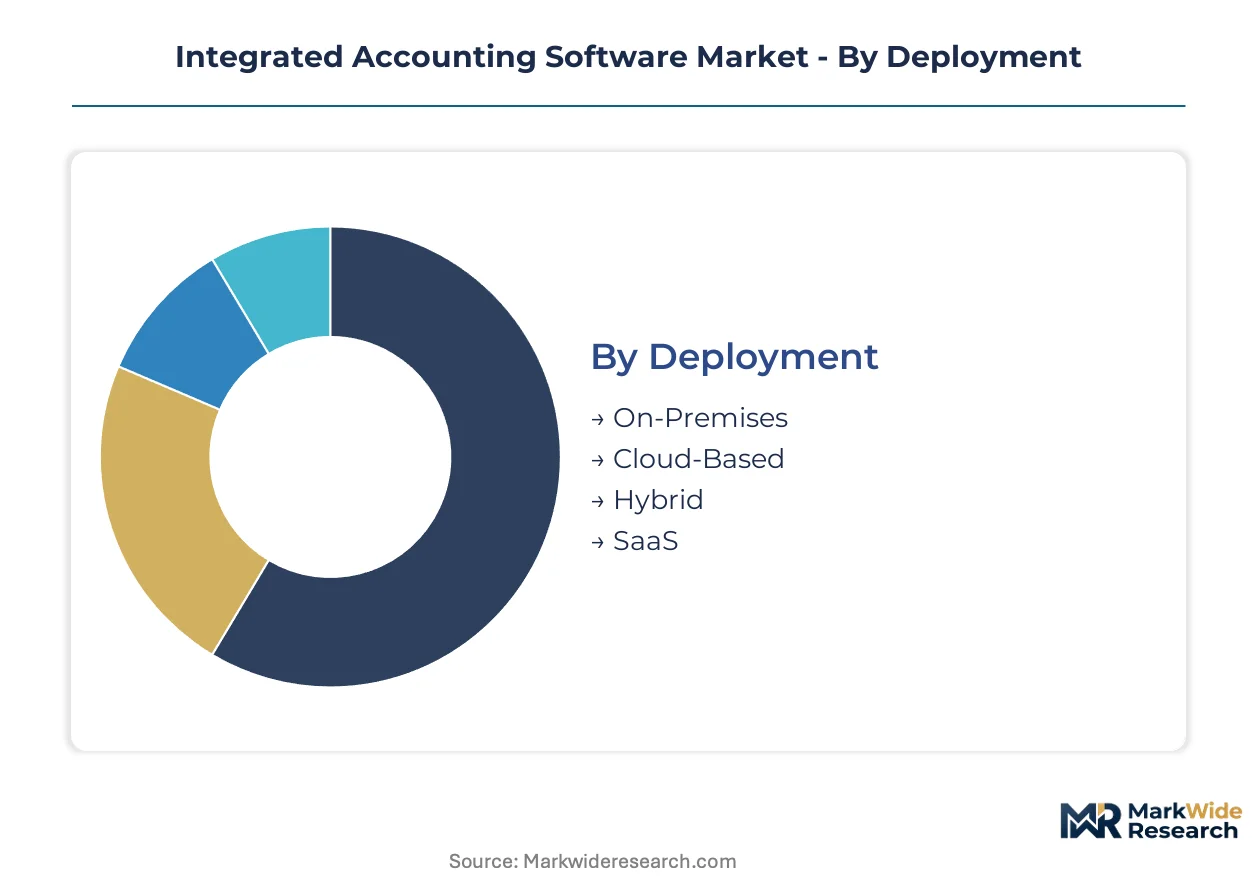
Deployment architecture, user scale, functional depth, and sector-specific compliance requirements fragment procurement patterns across the integrated accounting software landscape. Vendors must align pricing, implementation complexity, and regulatory coverage to distinct buyer profiles or risk margin erosion from mismatched capability bundling.
Deployment:
Cloud architectures span from fully managed SaaS to client-controlled infrastructure, with hybrid configurations bridging legacy system dependencies.
- Cloud-Based:Multi-tenant architectures with automatic updates and API-native connectivity dominate new mid-market installations. German and Indian enterprises prioritize these platforms to satisfy real-time tax portal synchronization mandates from the BZSt and GST Network respectively.
- Hybrid:Split configurations keep sensitive payroll or intercompany data on-premises while routing transactional workflows through cloud interfaces. United States healthcare systems and financial services firms deploy these setups to maintain HIPAA and SEC audit trail sovereignty without sacrificing accessibility.
- On-Premises:Perpetual license models with localized database servers persist in defense contractors and critical infrastructure operators facing national security data classification requirements.
- SaaS:Pure subscription delivery with zero infrastructure management overhead attracts freelance professionals and micro-businesses seeking mobile-first ledger access without IT staffing.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
End User:
Buyer sophistication ranges from individual practitioners to distributed multinational finance departments with divergent integration requirements.
- Enterprises:Multi-entity deployments with intercompany elimination, currency translation, and role-based access hierarchies across hundreds of users. These installations demand ISO 27001 certification and dedicated customer success management from vendors.
- Small Businesses:Owner-operator led implementations prioritizing bank feed automation and simplified tax filing over advanced forecasting. Indian GST compliance and US Schedule C automation represent concentrated demand pockets.
- Freelancers:Sole practitioners requiring mileage tracking, 1099 preparation, and quarterly estimated tax calculations with minimal learning curve.
- E-Commerce:Sellers managing multi-channel inventory valuation, sales tax nexus tracking across jurisdictions, and payment processor reconciliation at transaction volumes exceeding traditional retail velocities.
Enterprise contracts generate the highest absolute revenue per account; E-Commerce represents the steepest expansion trajectory as platform selling proliferates.
Feature:
Functional modules command divergent price premiums based on regulatory complexity and labor substitution potential.
- Financial Reporting:Consolidated statement generation with multi-GAAP mapping and CSRD sustainability disclosure integration. These modules sustain pricing power through auditor acceptance requirements and board presentation formatting standards.
- Tax Management:Automated jurisdiction-specific calculation engines with direct filing portal submission. India's GST e-invoice integration and Germany's ELSTER interface exemplify the compliance-driven feature depth commanding subscription upgrades.
- Payroll:Bi-directional general ledger posting with employment law compliance across federal, state, and municipal layers. Margin pressure intensifies from specialized human capital management competitors with deeper regulatory engines.
- Invoicing:Receivables workflow automation with payment link embedding and dunning sequence management. Standardized functionality compresses differentiation and pricing leverage for standalone offerings.
Financial Reporting anchors vendor profitability; Tax Management is climbing the fastest as digitized revenue authorities expand real-time filing mandates.
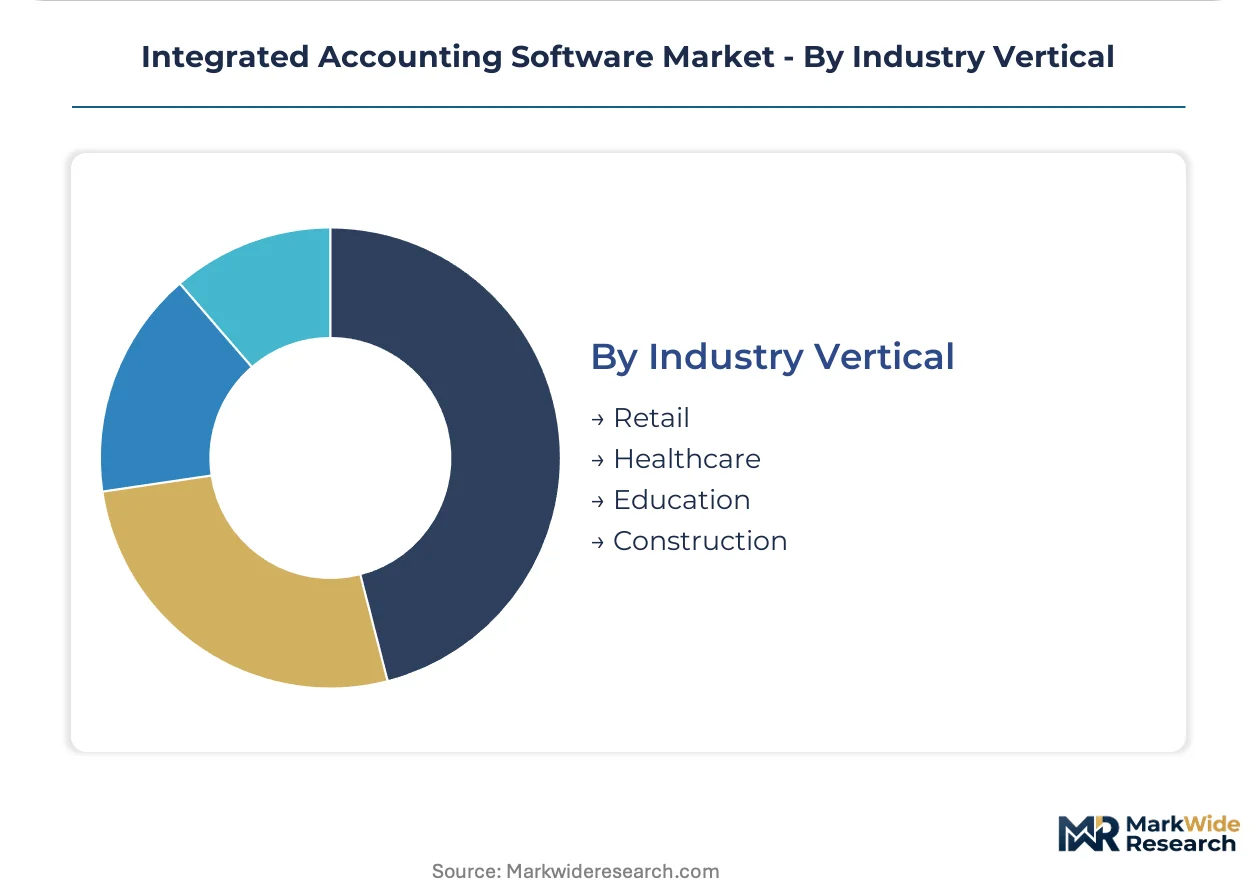
Industry Vertical:
Sector-specific accounting conventions and compliance obligations drive template customization and implementation methodology divergence.
- Healthcare:Revenue cycle integration with insurance claim tracking, patient responsibility estimation, and HIPAA-aligned access logging. United States provider networks and German Krankenhaus operators represent concentrated procurement pools.
- Construction:Percentage-of-completion revenue recognition, retention tracking, and union payroll compliance with certified payroll reporting. Project-based cost allocation distinguishes these deployments from standard retail configurations.
- Retail:High-velocity inventory valuation with LIFO/FIFO automation, point-of-sale integration, and omnichannel return reconciliation.
- Education:Fund accounting with restricted grant tracking, tuition revenue recognition schedules, and endowment investment reporting for nonprofit institutions.
Healthcare commands implementation premiums; Construction offers underserved expansion potential where generic horizontal platforms underperform project accounting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balance dynamics favor net-importing jurisdictions with stringent compliance mandates, while software-as-a-service delivery models reduce traditional trade friction in cross-border licensing arrangements. The United States, Germany, and India collectively concentrate procurement velocity as digitized tax infrastructure accelerates replacement cycles.
United States
Small-business formation rates and freelance workforce expansion sustain demand for cloud-native ledger platforms with automated Schedule C preparation. The SEC mandates electronic filing and audit-trail retention for public registrants, pushing enterprises toward governance-ready architectures. Silicon Valley and New York City finance clusters anchor vendor development centers and enterprise procurement committees.
Germany
Mittelstand manufacturing networks require multi-entity consolidation with ELSTER tax portal synchronization and CSRD sustainability disclosure integration. The EU AI Act risk classification framework imposes documentation burdens on automated financial processing modules. Bavaria and Baden-Württemberg industrial corridors concentrate procurement decision-making for ERP-integrated deployments.
India
GST Network real-time invoice reporting and e-way bill compliance drive mid-market enterprises toward API-first platforms with direct government portal connectivity. The country's data protection localization rules fragment cloud infrastructure economics for foreign vendors. Bengaluru and Mumbai financial technology clusters incubate indigenous platform development and enterprise adoption.
United Kingdom
Making Tax Digital mandates for VAT-registered businesses compress evaluation cycles for cloud-based solutions with HMRC submission automation. Post-Brexit regulatory divergence from EU frameworks complicates multi-jurisdiction compliance for multinational headquarters. London's financial services concentration sustains demand for sophisticated consolidation and treasury management capabilities.
Japan
Invoice system reforms requiring qualified electronic invoice issuance accelerate replacement of legacy desktop accounting packages among small enterprises. METI digital transformation subsidies reduce adoption friction for cloud migration among traditional manufacturing suppliers. Tokyo and Osaka metropolitan areas concentrate enterprise procurement and systems integrator expertise.
Integrated Accounting Software Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: consumer-to-business ecosystem platforms, deep ERP integration specialists, and pure-play cloud-native challengers. Strategic archetypes include horizontal suite vendors, vertical-specific template providers, and API-first connectivity layers. Dominant competitive moves encompass M&A activity targeting vertical workflow automation and strategic partnerships with open banking infrastructure providers.
Within the ecosystem-platform tier, Intuit Inc. and Xero exemplify archetypes that anchor small-business and freelance adoption through consumer-grade user experiences and direct bank feed aggregation. SAP SE and Oracle Corporation occupy positions among enterprise-grade integration specialists, sustaining deployment complexity for multinational finance departments. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Intuit Inc. |
| The Sage Group plc |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Infor |
| Workday Inc |
| Xero |
| Yonyou Software Co Ltd. |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States, Germany, and India anchors margin distribution across deployment tiers, with hyperscaler data center economics in these jurisdictions directly determining where subscription pricing power accumulates versus where cost compression dominates.
Pricing Analysis
Enterprise buyers anchor pricing power through multi-year commitments that secure rate locks against SaaS inflation, while freelance and small-business segments face standard list pricing with limited negotiation leverage. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified enterprise suites from mid-market automation bundles and basic ledger entry tools. Cost compression in payroll modules intensifies because specialized human capital management vendors undercut generalist suite pricing. Freelancers exhibit highest price sensitivity due to per-seat subscription economics, whereas enterprises with hundreds of users extract volume discounts that compress per-seat realized pricing.
Supply Chain Analysis
Extended payment terms from large enterprise customers strain vendor working capital, forcing accounting software providers to draw from supply-chain finance facilities or accelerate cash collection through annual prepay incentives. Engineering talent concentrates in the United States, India, and Germany, with AI/ML specialists and compliance engineers commanding premium compensation. Cloud compute and API gateway dependencies rest on hyperscaler infrastructure. Single-source vulnerability runs through concentrated hyperscaler regions where GDPR localization mandates fragment data center economics. Distribution runs through direct sales teams for enterprise accounts, self-service digital channels for micro-businesses, and value-added reseller networks for mid-market vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of engineers with simultaneous expertise in EU AI Act algorithmic documentation and real-time tax API integration constrains vendor expansion velocity, creating acquisition premiums for teams possessing this dual competency.
For Market Incumbents: Entrench multi-entity consolidation capabilities through deeper ERP integration that raises switching costs for enterprise finance departments. Invest in ISO 27001 certification maintenance and CSRD sustainability module pre-configuration to defend against pure-play cloud challengers lacking compliance depth. Vertical integration into specialized payroll compliance engines offsets margin erosion from dedicated human capital management competitors. For New Entrants and Emerging Players: Establish a beachhead in construction and field-service verticals where generic horizontal platforms underperform project accounting requirements. Mobile-first design for distributed workforces in India and Southeast Asia represents the most penetrable segment, as desktop-centric incumbents hold weak positions. Partner with open banking infrastructure providers to accelerate API-native connectivity without proprietary development overhead. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists possessing pre-configured industry templates and established auditor acceptance relationships. Long-term viability hinges on recurring revenue concentration above eighty percent and net revenue retention exceeding one hundred ten percent. Watch for inflection signals in government procurement shifts toward real-time tax portal synchronization mandates, which accelerate replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity with SAP and Oracle systems sustains enterprise-grade deployment complexity and switching costs. |
| Acquisition of Specialist Firm | Vertical workflow automation targets in construction and healthcare fill template gaps that generic platforms cannot address. |
| Strategic Partnership | Open banking infrastructure alliances with payment processors accelerate API-native connectivity for mid-market consolidation. |
| Product Launch | Embedded carbon accounting modules capture CSRD sustainability reporting demand and command premium subscription pricing. |
| Geographic Expansion | Regional data center buildout in India satisfies data localization rules and enables GST Network direct connectivity. |
Methodological Framework
The analysis maps cloud-based, hybrid, on-premises, and SaaS deployment architectures, each validated through CFOs, IT procurement officers, platform engineers, and integration specialists across primary interviews. Secondary validation draws from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and GST Network technical specifications. Bottom-up triangulation across vendor-reported subscription metrics and top-down reconciliation against aggregate enterprise software spending estimates ensure cross-verified outputs.
Assumptions held fixed include prevailing regulatory frameworks across the analysis window, with EU AI Act documentation requirements and real-time tax portal mandates treated as binding constraints. Segmentation dimensions modeled span deployment model, organization size, functional module depth, and vertical industry. CAGRs derive from logistic diffusion curves fitted to adoption velocity patterns, with inputs including cloud migration rates, mid-market formation trends, and compliance automation penetration.
Stress conditions across interest rate environments, data localization enforcement intensity, and hyperscaler pricing volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
Finance and Accounting Outsourcing (FAO) Market