
 Construction Accounting Software Market | 2026-2036
Construction Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Accounting Software Market Analysis
Certified construction accountants with ERP integration skills is reorganizing how software vendors allocate R&D budgets and partner with trade schools. Procore Technologies leverages its project management heritage to bundle financial modules with field operations workflows. Sage Group anchors its position through deep compliance libraries tailored to North American tax jurisdictions. Oracle Corporation competes by extending its NetSuite architecture into subcontractor payment automation and lien management.
Construction accounting software integrates job costing, payroll, accounts payable, and project financial reporting into unified ledgers that track work-in-progress, retainage, and committed costs against original estimates. Cloud-based solutions dominate new deployments by eliminating on-site server maintenance and enabling real-time field-to-office data synchronization. General contractors represent the most mature end-user segment with established procurement cycles, while subcontractor adoption is accelerating fastest as lien compliance complexity rises. Implementation services command the largest service-type revenue pool due to multi-month chart-of-accounts customization and legacy data migration requirements.
The US Internal Revenue Service shapes product roadmaps through escalating electronic filing mandates for 1099-NEC and certified payroll reporting. The Financial Accounting Standards Board's ASC 606 revenue recognition standard forces contractors to retool percentage-of-completion calculations within their accounting engines. Stakeholders must monitor how state-level prevailing wage apps and certified payroll automation requirements proliferate across jurisdictions with active infrastructure programs.
Market Dynamics
Cloud-native job-costing architectures are compressing implementation timelines from quarters to weeks, forcing incumbent vendors to restructure professional services revenue models or lose mid-market accounts to agile challengers.
Growth Catalysts
- IRS 1099-NEC electronic filing mandates:The US Internal Revenue Service's escalating electronic submission requirements for non-employee compensation are compelling general contractors to automate subcontractor payment tracking and tax documentation workflows.
- Texas infrastructure budgets:Sustained commercial construction permit growth and state-level infrastructure allocations in Texas are generating concentrated demand for real-time project financial visibility tools.
- ASC 606 revenue recognition:The Financial Accounting Standards Board's percentage-of-completion accounting standard is forcing contractors to upgrade legacy systems for compliant work-in-progress reporting.
Market Restraints
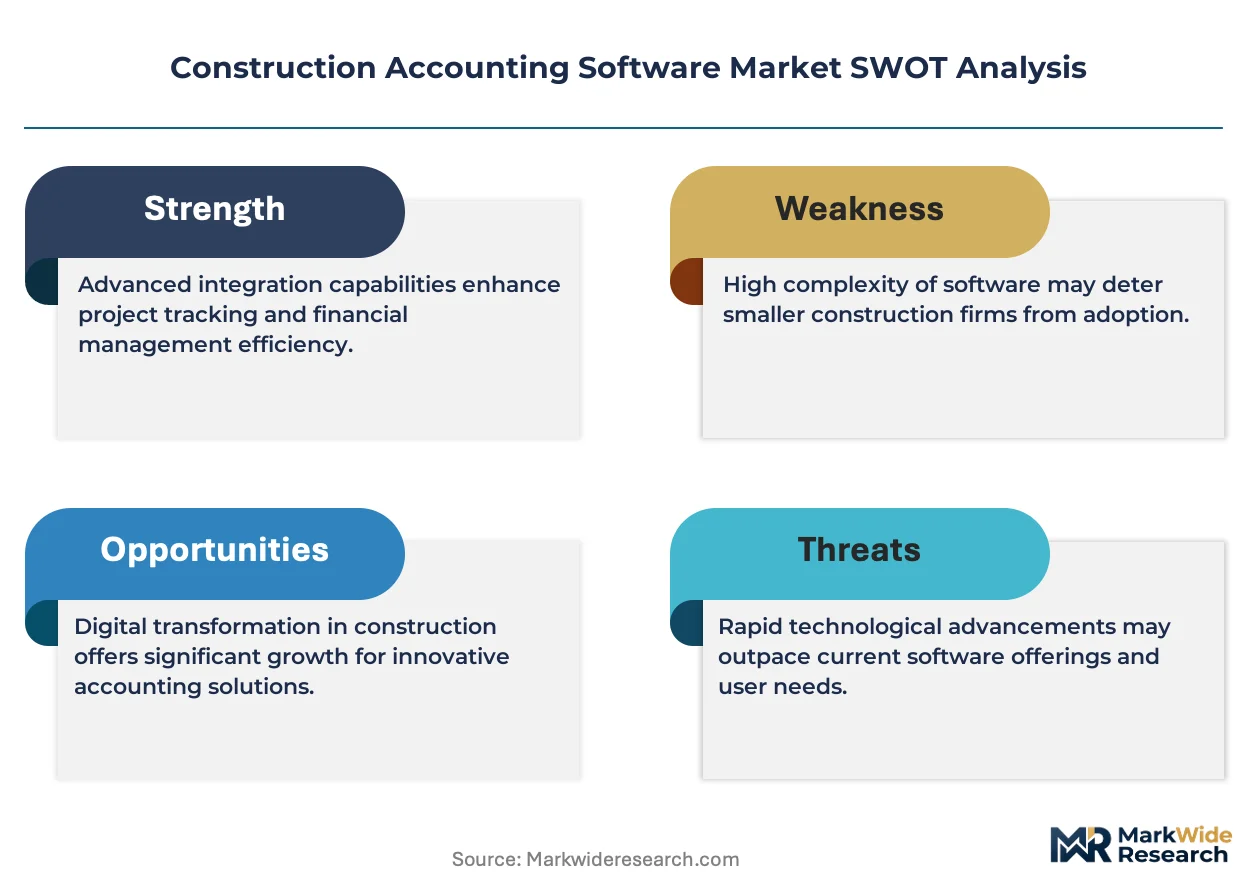
- Implementation cost structure:Multi-month chart-of-accounts customization and legacy data migration requirements consume 40-60% of first-year total cost of ownership, freezing budget-constrained subcontractors.
- Certified payroll talent scarcity:Shortages of construction accountants with ERP integration and prevailing wage compliance expertise extend deployment timelines and inflate professional services fees.
- State-level regulatory fragmentation:Proliferating certified payroll automation requirements across jurisdictions with active infrastructure programs force vendors to maintain parallel compliance codebases.
Strategic Opportunities
- Subcontractor lien compliance automation:Rising mechanic's lien complexity and joint-check requirements among specialty trades represent an underserved segment with faster replacement cycles than general contractors.
- Real-time field-to-office synchronization:Mobile-first architectures enabling superintendents to capture labor and equipment costs at the point of work create switching incentives for firms with distributed project portfolios.
- Trade school partnership channels:Software vendors embedding financial modules into construction management curricula can capture emerging contractors before procurement habits solidify.
Industry Challenges
- Retainage calculation complexity:Variable withholding percentages across contract tiers and jurisdictions require granular sub-ledger tracking that strains legacy database architectures.
- Committed cost forecasting accuracy:Purchase order encumbrance and change order integration with live job budgets demands real-time EDI connectivity that many supplier networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Accounting Software Market |
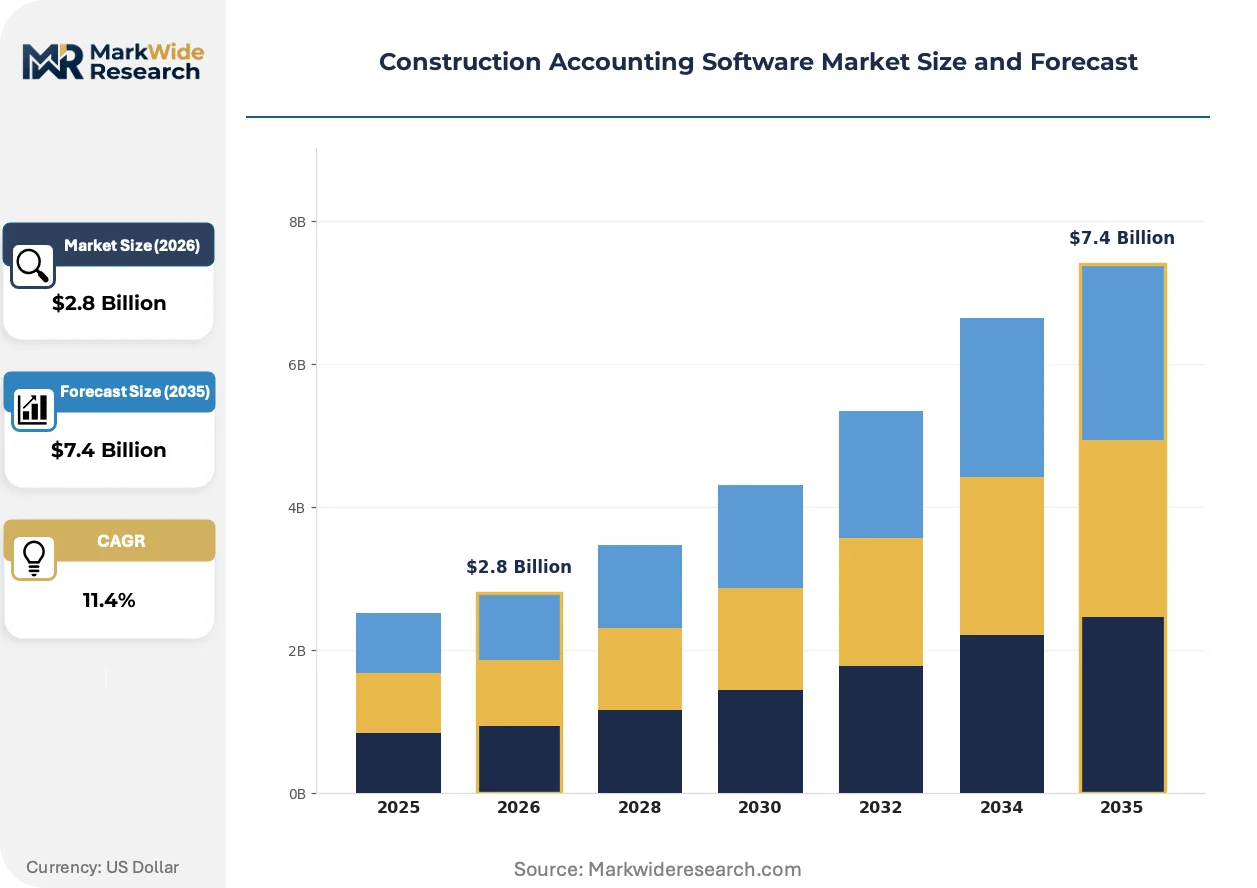
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Mobile Applications, Hybrid Systems End User: General Contractors, Subcontractors, Project Managers, Architects Deployment: Public Cloud, Private Cloud, On-Premise, Hybrid Deployment Service Type: Implementation Services, Support Services, Training Services, Consulting Services |
| Companies Covered | Procore Technologies, Oracle Corporation, Autodesk, Sage Group, Trimble, Nemetschek Group, Constellation Software, CMiC, Foundation Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Accounting Software Market Emerging Trajectories
Artificial intelligence is penetrating construction financial workflows through predictive cash flow modeling and automated anomaly detection in job-cost variances, compressing the feedback loop between field operations and accounting close processes.
Embedded AI-driven forecasting engines are bifurcating the market between premium platforms offering predictive project profitability scoring and basic cloud ledger systems. Mid-sized general contractors with 50-200 active projects are adopting these tools fastest, using machine learning models trained on historical bid-to-actual variance patterns to flag at-risk jobs before cost overruns crystallize. The technology is bifurcating vendor R&D allocation, forcing established players to acquire or build predictive capabilities while niche providers retreat to compliance-focused feature sets.
The US Internal Revenue Service's phased electronic filing requirements for certified payroll reports are mandating direct system-to-government data transmission. Construction firms must now maintain audit trails linking individual timecard entries to wage determinations and fringe benefit allocations. Subcontractors performing prevailing wage work in multiple states face the steepest compliance burden, driving consolidation toward platforms with pre-built Davis-Bacon Act and state prevailing wage rule libraries.
Subscription pricing for implementation services is displacing traditional time-and-materials professional engagements. General contractors accustomed to capitalizing software deployments are resisting recurring fees for chart-of-accounts configuration and legacy migration, forcing vendors to unbundle setup costs from ongoing platform access. This tension is most visible in the Texas market, where rapid firm expansion creates repeated implementation demand that buyers prefer to expense rather than capitalize.
Construction Accounting Software Market Segmentation
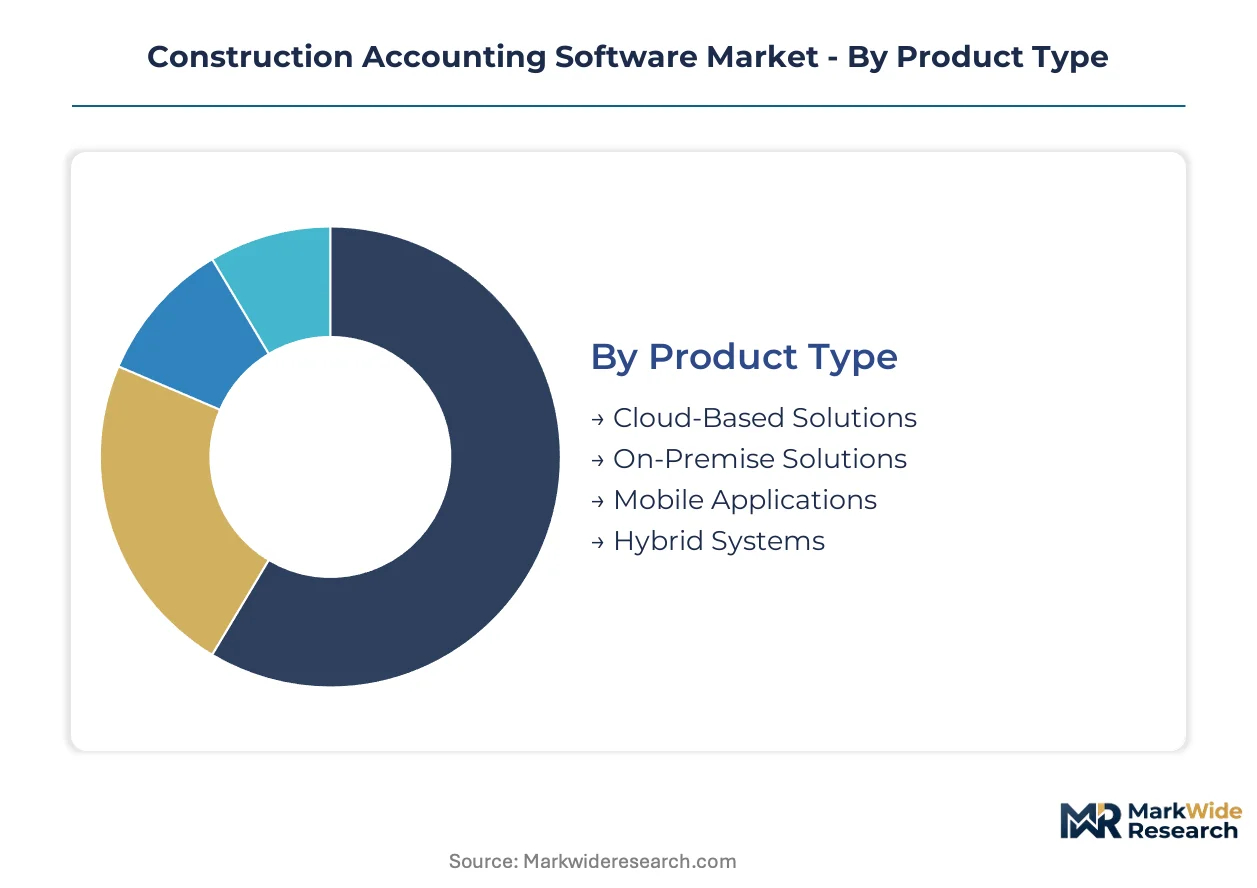
Construction accounting software vendors structure product portfolios around deployment flexibility and buyer sophistication. Segment boundaries are blurring as cloud-native architectures absorb functionality once locked in on-premise systems.
Product Type:
Substitution pressure runs strongest against on-premise installations as cloud economics reframe total cost of ownership calculations for mid-market buyers.
- Cloud-Based Solutions:Multi-tenant SaaS architectures eliminate server maintenance overhead while enabling real-time field-to-office synchronization. Demand concentrates among Texas general contractors managing distributed project portfolios where instant work-in-progress visibility prevents cost overruns.
- On-Premise Solutions:Single-tenant deployments persist in defense contracting and critical infrastructure segments with stringent data sovereignty requirements. Legacy system entrenchment and multi-year amortization schedules slow replacement cycles despite higher maintenance burdens.
- Mobile Applications:Native iOS and Android tools capture labor and equipment costs at the point of work, serving superintendents requiring offline functionality.
- Hybrid Systems:Split architectures maintain sensitive payroll data on-premise while pushing project reporting to cloud instances.
Cloud-Based Solutions retain volume leadership; Mobile Applications hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade procurement cycles from the rapid adoption patterns of specialty trades.
- General Contractors:Prime contractors with established ERP investments demand deep integration between job costing and enterprise procurement systems. Procurement cycles stretch 12-18 months as finance committees evaluate compliance library depth.
- Subcontractors:Specialty trades face accelerating lien compliance complexity and joint-check requirements that outstrip spreadsheet-based tracking. Smaller firms in Texas electrical and mechanical trades are adopting cloud modules fastest to automate prevailing wage documentation.
- Project Managers:Field operations leaders prioritize mobile-first tools bridging daily reporting with accounting close processes.
- Architects:Design-phase professionals require lightweight project budgeting modules rather than full ledger functionality.
General Contractors command the highest average contract values; Subcontractors are expanding most quickly.
Deployment:
Application criticality determines infrastructure choices, with payment processing and tax filing workflows driving security posture decisions.
- Public Cloud:Shared infrastructure delivers elastic compute for seasonal construction cycles and multi-project reporting bursts. AWS and Azure regions in Dallas and Houston serve Texas infrastructure contractors with low-latency compliance reporting.
- Private Cloud:Dedicated single-tenant environments address certified payroll data residency requirements for federal contractors. Higher per-seat costs restrict adoption to firms with active Davis-Bacon Act obligations.
- On-Premise:Air-gapped installations persist in correctional and military construction where network segmentation is mandatory.
- Hybrid Deployment:Selective cloud bursting for analytics workloads while retaining transactional ledgers locally.
Public Cloud retains volume leadership; Hybrid Deployment holds the steepest expansion curve.
Service Type:
Customer type segmentation reveals divergent willingness to pay for expertise versus self-service enablement.
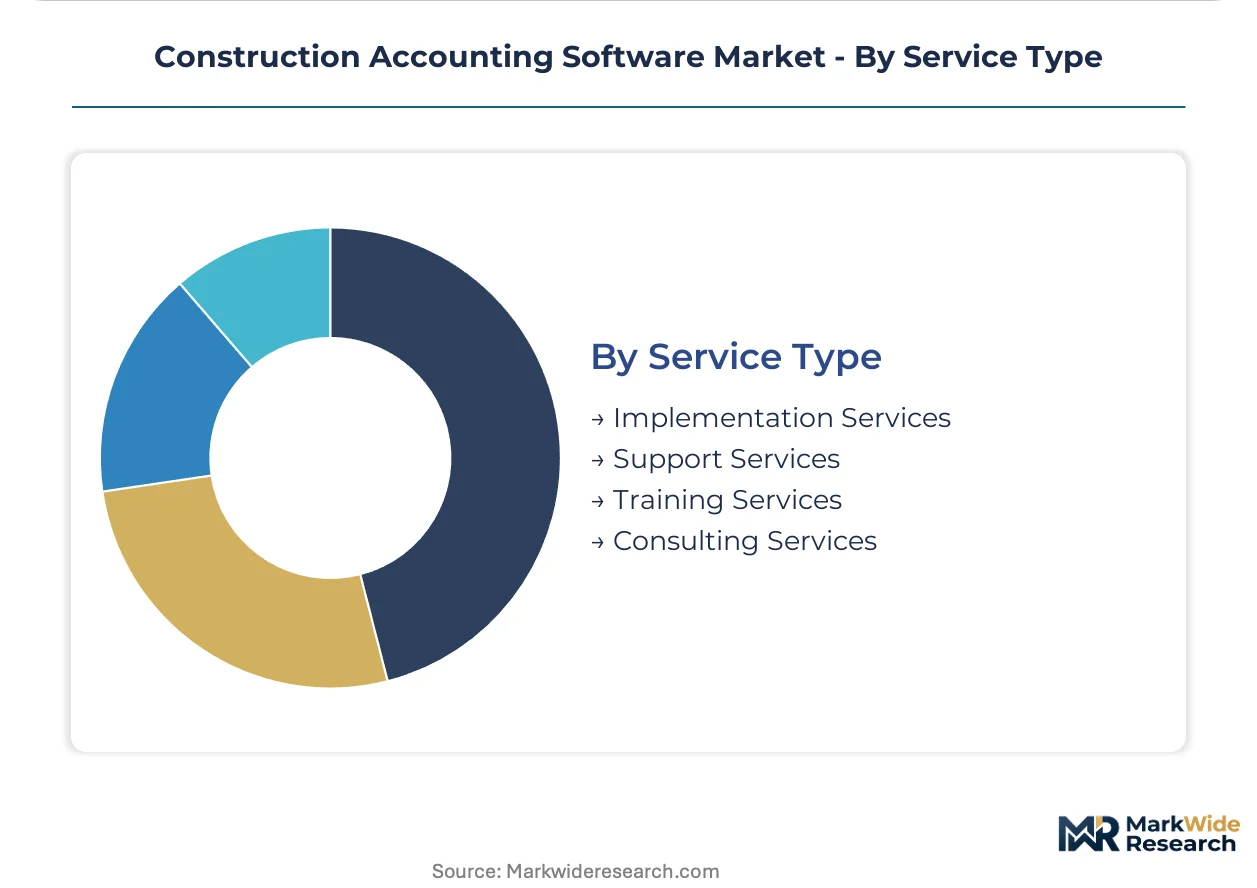
- Implementation Services:Chart-of-accounts customization and legacy data migration consume 40-60% of first-year ownership costs. Multi-month engagements dominate revenue pools as subcontractors require prevailing wage rule configuration.
- Support Services:Tiered response commitments with guaranteed resolution times for tax filing deadline pressures. Subscription pricing models are displacing traditional time-and-materials contracts.
- Training Services:Role-based certification programs for project accountants and field supervisors.
- Consulting Services:ASC 606 revenue recognition remediation and audit preparation assistance.
Implementation Services retains volume leadership; Support Services holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Internal Revenue Service anchors the dominant geography through escalating electronic filing mandates for 1099-NEC and certified payroll documentation. These regulatory pressures concentrate software demand among mid-sized general contractors seeking automated compliance infrastructure. Texas infrastructure budgets and commercial construction permits generate additional regional pull.
United States
Mid-sized general contractors in Texas and Florida are accelerating cloud-based job-costing module adoption to manage distributed project portfolios. The IRS phased electronic filing requirements for certified payroll reports mandate direct system-to-government data transmission with audit trails linking timecard entries to wage determinations. Dallas and Houston construction clusters drive concentrated demand for real-time work-in-progress visibility tools.
Canada
Federal contractors in Ontario and British Columbia require dedicated single-tenant environments addressing certified payroll data residency obligations. The Canada Revenue Agency's T4A and T5018 electronic filing specifications push firms toward automated subcontractor payment tracking systems. Toronto's commercial construction expansion and Vancouver's infrastructure pipeline generate sustained procurement activity for compliance-integrated platforms.
Germany
Mittelstand construction firms in Bavaria and North Rhine-Westphalia are migrating from on-premise ERP systems to cloud-native architectures for multi-project financial consolidation. The German Commercial Code (HGB) and GoBD digital record-keeping standards mandate granular audit trails for construction revenue recognition. Munich and Düsseldorf industrial construction clusters prioritize platforms with embedded ASC 606-equivalent percentage-of-completion calculation engines.
United Kingdom
Construction firms in Greater London and the Southeast are adopting mobile-first field-to-office synchronization tools to capture labor costs at the point of work. HMRC's Construction Industry Scheme (CIS) monthly return electronic filing requirements automate subcontractor deduction verification workflows. The Thames Tideway and HS2 infrastructure programs sustain demand for real-time committed cost forecasting against original estimates.
Australia
State-level infrastructure programs in New South Wales and Victoria are driving adoption of lien compliance automation among specialty trades. The Australian Taxation Office's Single Touch Payroll Phase 2 requirements extend real-time reporting obligations to construction industry employers. Sydney and Melbourne commercial construction permits generate concentrated demand for cloud-based retainage calculation modules handling variable withholding percentages across contract tiers.
Construction Accounting Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the construction accounting software market. Cloud-native challengers compress implementation timelines from quarters to weeks, forcing incumbent vendors to restructure professional services revenue models or surrender mid-market accounts. The competitive structure stratifies into three archetypes: enterprise ERP extenders, vertical construction specialists, and agile SaaS challengers. Dominant competitive moves include strategic partnerships with trade schools and portfolio diversification into subcontractor payment automation.
Within the enterprise extender tier, Oracle Corporation and Sage Group exemplify archetypes leveraging deep compliance libraries and existing ERP footprints to anchor market position. Procore Technologies occupies a distinct position bundling financial modules with field operations workflows, representing the vertical specialist approach. These three companies sit within different strategic postures—ERP integration depth, compliance library breadth, and field-to-office synchronization capability—without any single player commanding unified technology and cost leadership.
| Leading Market Players |
|---|
| Procore Technologies |
| Oracle Corporation |
| Autodesk |
| Sage Group |
| Trimble |
| Nemetschek Group |
| Constellation Software |
| CMiC |
| Foundation Software |
| Others |
Supply Flow & Price Mechanics
Multi-year SaaS subscription contracts with embedded implementation services lock in both platform access and predictable cost structures for general contractors navigating IRS electronic filing mandates. These arrangements tie pricing visibility to compliance module bundling, with Texas infrastructure contractors commanding tiered rates based on project portfolio scale and prevailing wage rule complexity.
Pricing Analysis
Texas-based general contractors pay premium rates compared to Florida peers due to concentrated infrastructure demand and certified payroll automation requirements. Three-tier pricing structure across enterprise, mid-market, and subcontractor levels reflects integration depth and compliance library breadth. Cost compression in the mid-market tier is intensifying because cloud-native challengers compress implementation timelines from quarters to weeks. Subcontractors exhibit highest price sensitivity due to lien compliance complexity and joint-check automation needs.
Supply Chain Analysis
AWS and Azure data center concentration in Dallas and Houston creates geographic chokepoints for Texas infrastructure contractors requiring low-latency certified payroll reporting. Software development talent concentrates in the United States, India, and Ireland, with implementation services drawing from certified construction accountant pools in Texas and California. Single-source vulnerability runs through hyperscaler infrastructure dependencies. Distribution runs through direct vendor sales teams and construction trade school partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction accounting software demand tracks commercial construction permit cycles, with Texas infrastructure budgets signaling cyclical recovery momentum through sustained public allocation growth.
For Market Incumbents: Shield mid-market accounts from agile SaaS challengers by restructuring professional services revenue models toward subscription pricing. Acquire predictive AI capabilities to match forecasting engines from cloud-native entrants. Prioritize compliance library depth in North American tax jurisdictions as the defensive moat. For New Entrants and Emerging Players: Lead with mobile-first field-to-office synchronization targeting specialty trades in Texas electrical and mechanical segments. Subcontractor lien compliance automation represents the most penetrable white space, with faster replacement cycles than entrenched general contractor procurement. Embed financial modules into construction management curricula through trade school partnerships to capture emerging contractors. For Investors and Strategic Acquirers: Capital is best deployed toward vertical construction specialists with field-to-office workflow integration and established subcontractor payment automation capabilities. Platforms combining job-costing heritage with AI-driven forecasting engines offer superior long-term viability across a 5-10 year holding window. Monitor Texas commercial permit issuance as the inflection indicator for implementation services demand.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Library Expansion | Deepened IRS 1099-NEC and certified payroll rule coverage anchors retention in regulated jurisdictions. |
| AI Forecasting Engine Development | Predictive project profitability scoring differentiates premium platforms from basic cloud ledger systems. |
| Trade School Curriculum Partnership | Early capture of emerging contractors before procurement habits solidify locks in lifetime value. |
| Subcontractor Payment Automation | Mechanic's lien and joint-check workflow integration addresses underserved specialty trade demand. |
| Mobile-First Architecture Rollout | Point-of-work cost capture creates switching incentives for distributed project portfolios. |
Methodological Framework
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings in observable procurement patterns. Construction technology officers, certified construction accountants, project controllers, and ERP integration specialists provided deployment timeline and compliance burden assessments. Secondary validation drew from SEC filings of publicly traded software vendors, IRS electronic filing specification documents, Texas Department of Transportation infrastructure budget disclosures, and commercial construction permit databases. Bottom-up project-level demand estimates triangulated against top-down vendor revenue segmentation.
Sensitivity analysis across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern shaped the forecast framework. CAGRs derived from historical replacement cycle analysis and projected compliance mandate acceleration. Percentage-of-completion accounting standard adoption curves and prevailing wage rule proliferation across state jurisdictions served as construction-specific demand drivers across the modeling period.
Forecasts assume regulatory continuity in IRS electronic filing mandates and Texas infrastructure allocation regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ASC 606 enforcement intensity and state-level certified payroll automation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
UAE Forensic Accounting Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Canada Accounting Software Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market